
 Variable Frequency Drive (VFD) Market | 2026-2036
Variable Frequency Drive (VFD) Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Frequency Drive (VFD) Market Outlook
Electrical engineering talent specialized in power electronics is collapsing across mature industrial economies, forcing VFD vendors to restructure service networks and automate commissioning workflows. ABB leverages its integrated automation platform to embed drive diagnostics within broader plant control architectures. Siemens sustains engineering density through captive apprenticeship pipelines in Germany and regional technical centers. Yaskawa Electric Corporation dominates precision servo-drive applications where motion-control expertise remains scarce and premium-priced.
A variable frequency drive modulates AC motor speed by varying input frequency and voltage, typically operating between 0.5 Hz and 400 Hz with voltage-source inverter topologies using IGBT or SiC power modules. The device enables energy recovery, soft starting, and process-level speed control across centrifugal loads and mechanical powertrains. AC drives anchor the largest installed base due to their compatibility with standard induction motors across pumps, fans, and compressor trains. Direct torque control technology is gaining share in high-performance material handling and elevator applications where dynamic response requirements exceed conventional V/f capability. Servo drives occupy the highest margin tier by pairing precision position feedback with multi-axis coordination in packaging and semiconductor fabrication.
EPA efficiency regulations for electric motor systems and EU Ecodesign requirements under the F-Gas framework are tightening minimum performance thresholds for new drive installations and retrofit specifications. IEC 61800 adjustable speed electrical power drive systems standards govern electromagnetic compatibility and functional safety classifications that determine market access across European and Asia-Pacific jurisdictions. NHTSA fuel economy mandates indirectly stimulate VFD demand through electrified auxiliary systems in commercial vehicle manufacturing. Stakeholders must monitor silicon carbide semiconductor cost curves and embedded cybersecurity certification requirements as these dual vectors reshape procurement criteria and supplier qualification protocols.
Market Dynamics
Silicon carbide power modules are compressing incumbent IGBT architectures across medium-voltage drive portfolios, forcing incumbent vendors to accelerate semiconductor sourcing diversification and redesign thermal management systems before cost parity arrives.
Growth Catalysts
- Water Infrastructure Retrofit Mandates:China's state-backed facility modernization programs are accelerating motor-drive replacements across municipal pumping stations and wastewater treatment plants.
- F-Gas Phase-Down Schedules:The EU F-Gas Regulation is tightening minimum performance thresholds for new drive installations and retrofit specifications across industrial refrigeration and HVAC systems.
- Direct Torque Control Adoption:High-performance material handling and elevator applications are migrating from conventional V/f control to dynamic torque response architectures.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export quota adjustments are compressing permanent magnet motor-drive margins.
- Semiconductor Supply Concentration:SiC wafer fabrication remains concentrated among three dominant substrate suppliers, creating allocation risk for drive OEMs scaling beyond 400V architectures.
- Cybersecurity Certification Friction:IEC 62443 compliance timelines for industrial automation cybersecurity are extending product qualification cycles by 8-14 months.
Strategic Opportunities
- India Manufacturing Corridor Expansion:PLI scheme incentives for textile and pharmaceutical processing equipment are creating localized drive assembly demand across Gujarat and Tamil Nadu industrial zones.
- Electrified Commercial Vehicle Auxiliaries:NHTSA fuel economy mandates are stimulating VFD procurement for compressor and pump electrification in heavy-duty truck manufacturing.
- Edge Analytics Convergence:Embedded vibration monitoring fused with drive control loops is enabling predictive maintenance service contracts in pulp and paper processing.
Industry Challenges
- Power Electronics Talent Collapse:Electrical engineering specialization in gate driver design and thermal simulation is contracting across German and Japanese technical universities.
- Legacy Control Architecture Integration:Proprietary fieldbus protocols in installed plant automation systems are obstructing seamless drive commissioning without costly gateway infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Frequency Drive (VFD) Market |
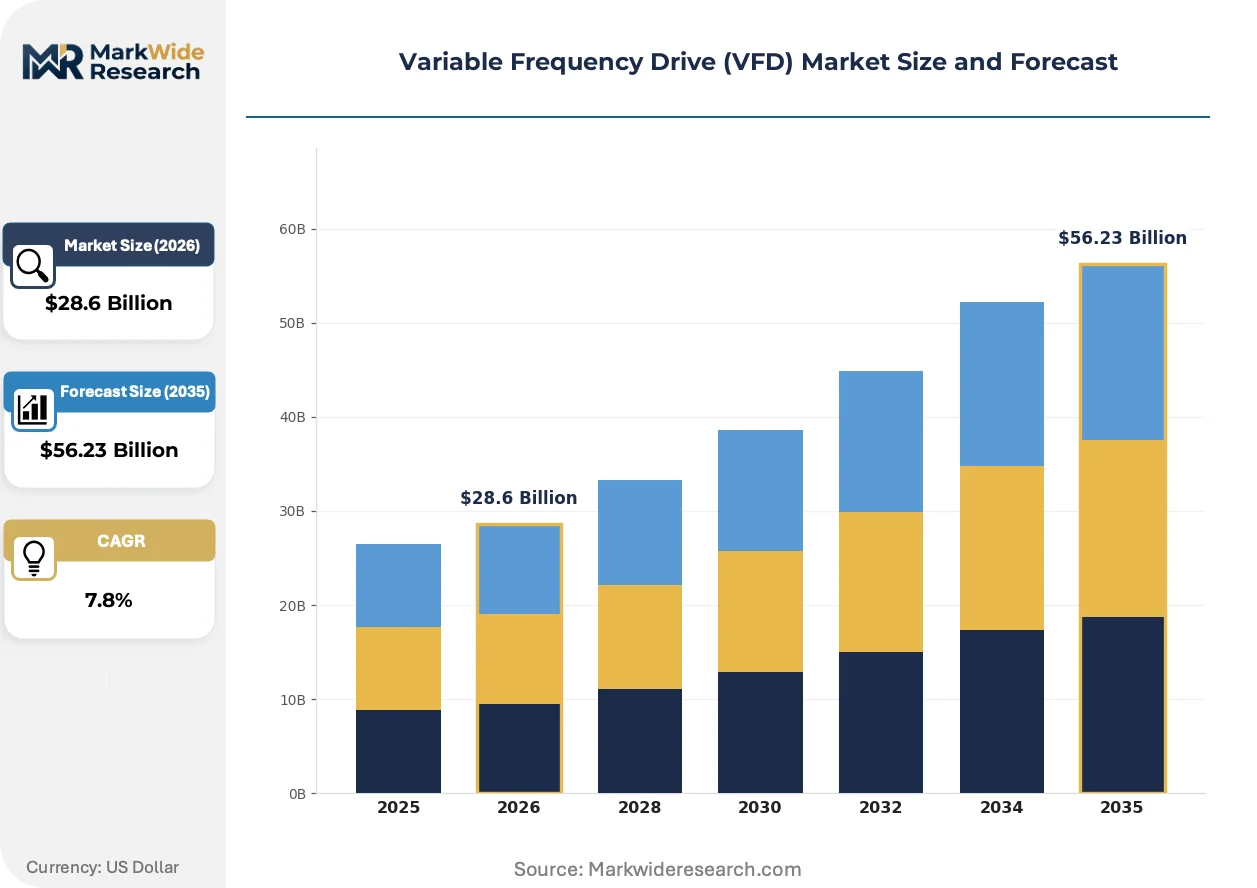
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Soft Starters End User: Manufacturing, Oil & Gas, Water & Wastewater, HVAC Technology: V/f Control, Flux Vector Control, Direct Torque Control, Sensorless Control Application: Pumps, Fans, Compressors, Conveyors |
| Companies Covered | ABB, Rockwell Automation, Siemens, Danfoss, Schneider Electric, General Electric, Yaskawa Electric Corporation, Eaton, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Frequency Drive (VFD) Market Strategic Shifts
Wide-bandgap semiconductors and embedded intelligence layers are restructuring competitive differentiation away from hardware specifications toward software-defined performance optimization and lifecycle service attach rates.
Silicon carbide MOSFETs enable higher switching frequencies with reduced thermal losses compared to silicon IGBTs. Mining and metals processing operators in Western Australia are deploying 3.3kV SiC drives for conveyor systems. This transition is displacing conventional multilevel inverter topologies in applications above 500kW.
The EU Ecodesign Directive's expanding scope under the F-Gas framework now governs drive-motor system efficiency across refrigeration compressors. Industrial cold chain operators face mandatory minimum efficiency index thresholds. Packaged drive-motor combinations are capturing specification preference over component-level procurement.
After-sales service unbundling is accelerating as end-users separate hardware procurement from commissioning and maintenance contracts. Water utility districts in California and Texas are negotiating multi-year performance agreements independent of initial capital expenditure. This restructuring concentrates vendor risk in operational uptime guarantees rather than equipment reliability alone.
Variable Frequency Drive (VFD) Market Segmentation
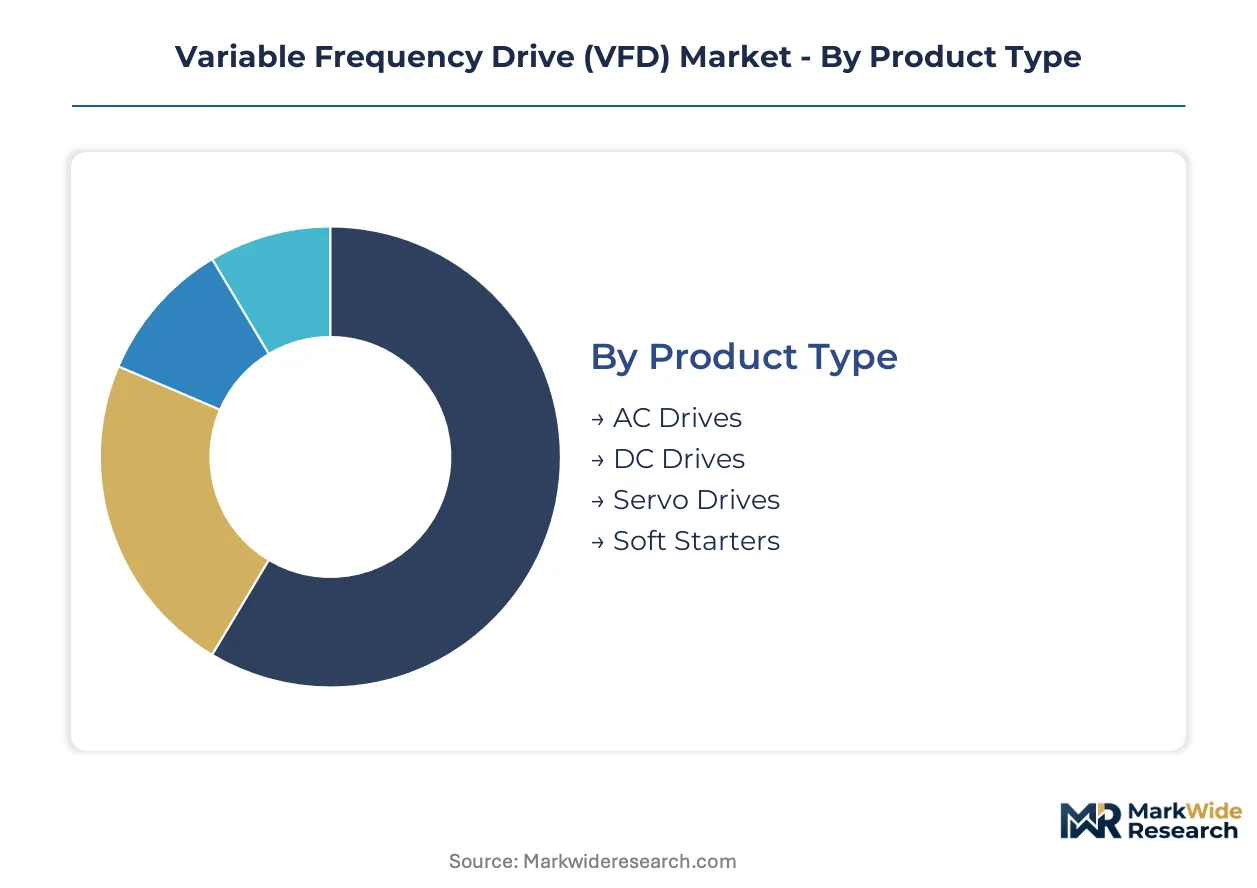
VFD segmentation reveals stark substitution pressures across product architectures. End-user concentration in water infrastructure and manufacturing clusters determines procurement specifications. Technology tiers separate commodity motion control from premium precision applications.
Product Type:
AC drives face the most acute substitution threat from servo architectures in precision applications, while DC drives confront terminal decline as AC technology captures regenerative braking and four-quadrant operation.
- AC Drives:Voltage-source inverter topologies using IGBT or SiC power modules dominate installed base compatibility with standard induction motors. Demand concentrates in China's industrial corridor zones where state-backed facility retrofits accelerate motor-drive replacements across pumping stations and processing plants.
- Servo Drives:Precision position feedback systems paired with multi-axis coordination enable nanometer-scale accuracy in packaging and semiconductor fabrication. Yaskawa Electric Corporation dominates this tier where motion-control expertise remains scarce and commands premium pricing.
- DC Drives:Ward Leonard legacy systems persist in metals rolling mills requiring high starting torque.
- Soft Starters:Reduced-voltage motor starting for fixed-speed applications where VFD sophistication is uneconomical.
AC drives retain volume leadership; servo drives hold the steepest expansion curve.
End User:
Cost tier stratification separates specification-intensive process industries from price-sensitive commercial building applications.
- Water & Wastewater:Municipal pumping stations and treatment plants require NEMA 4X enclosures and harmonic mitigation. China's state-backed modernization programs accelerate procurement volumes across municipal infrastructure.
- Manufacturing:Discrete automation and process control applications span material handling to precision machining. India's PLI scheme incentives for textile and pharmaceutical processing equipment create localized demand across Gujarat and Tamil Nadu industrial zones.
- Oil & Gas:Explosion-proof ratings and subsea pressure vessel compliance dominate upstream specifications.
- HVAC:Commercial building automation prioritizes energy recovery and variable air volume control.
Water & wastewater commands the highest specification intensity; manufacturing delivers the broadest volume base.
Technology:
Application complexity determines control algorithm selection, with material handling and elevator installations driving migration toward dynamic response architectures.
- Direct Torque Control:Flux and torque decoupling enables sub-millisecond response for high-performance material handling and elevator applications. Mining operators in Western Australia deploy 3.3kV SiC-enabled systems for conveyor regenerative braking.
- Flux Vector Control:Rotor flux orientation provides servo-like performance without position encoders in mid-range automation.
- V/f Control:Constant volt-per-hertz ratio serves centrifugal pumps and fans where dynamic response requirements are minimal.
- Sensorless Control:Observer-based speed estimation reduces hardware cost in washdown and hazardous environments.
V/f control maintains installed base dominance; direct torque control gains share fastest in high-performance segments.
Application:
Volume concentration in rotating equipment creates divergent margin profiles between commodity fluid handling and mechanical power transmission.
- Pumps:Centrifugal load profiles maximize energy recovery potential across water distribution and process industries. California and Texas water utility districts negotiate multi-year performance agreements independent of initial capital expenditure.
- Fans:Variable air volume systems in commercial HVAC and industrial ventilation represent the largest addressable unit volume.
- Compressors:Rotary screw and centrifugal configurations in refrigeration and compressed air systems face EU F-Gas Regulation efficiency mandates.
- Conveyors:Bulk materials handling in mining and logistics requires coordinated multi-drive synchronization.
Fans deliver the deepest unit volume; pumps capture the highest service attach rates through predictive maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors while Chinese manufacturing zones compress margins through scale-driven procurement. This asymmetry shapes regional vendor strategies and technology positioning across the forecast window.
China
State-backed facility modernization programs accelerate motor-drive replacements across municipal pumping stations and wastewater treatment plants. MIIT efficiency mandates under dual carbon goals enforce IEC-compliant equipment specifications. Industrial corridor zones in Jiangsu and Zhejiang provinces concentrate procurement volumes for textile and pharmaceutical processing equipment.
Germany
Captive apprenticeship pipelines sustain engineering density for power electronics specialization across industrial automation vendors. EU Ecodesign Directive requirements under the F-Gas framework tighten minimum efficiency thresholds for drive-motor systems. Technical centers in Bavaria and Baden-Württemberg anchor servo-drive development for precision motion control applications.
United States
Water utility districts in California and Texas negotiate multi-year performance agreements independent of initial capital expenditure. EPA efficiency regulations for electric motor systems govern new drive installations and retrofit specifications. Electrified auxiliary systems procurement accelerates across heavy-duty truck manufacturing under NHTSA fuel economy mandates.
India
PLI scheme incentives for textile and pharmaceutical processing equipment create localized drive assembly demand. CEA technical standards harmonize with IEC 61800 classifications for electromagnetic compatibility and functional safety. Industrial zones in Gujarat and Tamil Nadu concentrate manufacturing corridor expansion for domestic and export market supply.
Japan
Motion-control expertise scarcity sustains premium pricing for precision servo-drive applications in packaging and semiconductor fabrication. METI industrial efficiency programs promote wide-bandgap semiconductor adoption in medium-voltage drive portfolios. Technical universities in the Kanto and Kansai regions contract power electronics specialization enrollment despite industry demand.
Variable Frequency Drive (VFD) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the VFD market structure. The vendor base separates into three tiers: integrated automation platforms commanding premium service attach rates, scale-driven manufacturers optimizing unit economics, and precision specialists capturing scarce engineering premiums. Consolidation pressure concentrates among mid-tier players lacking captive semiconductor sourcing or embedded software capabilities. Dominant competitive moves include strategic partnerships for SiC wafer allocation and portfolio diversification into predictive maintenance service contracts.
Within the integrated automation tier, ABB and Siemens represent archetypes of platform-embedded drive diagnostics and captive technical training pipelines. Yaskawa Electric Corporation occupies a position exemplifying precision servo-drive specialization where motion-control expertise commands scarcity pricing. These three anchors illustrate the strategic divergence between scale-driven hardware manufacturing and premium-tier software-defined performance optimization.
| Leading Market Players |
|---|
| ABB |
| Rockwell Automation |
| Siemens |
| Danfoss |
| Schneider Electric |
| General Electric |
| Yaskawa Electric Corporation |
| Eaton |
| Hitachi |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide module substitution for legacy IGBT architectures is redrawing procurement geography toward Japanese and German substrate specialists while compressing price premiums across medium-voltage drive portfolios. This semiconductor transition concentrates sourcing leverage among three dominant wafer suppliers and forces drive OEMs to absorb qualification costs before cost parity arrives.
Pricing Analysis
German engineering corridors command 15-25% price premiums over Chinese manufacturing zones for equivalent IEC-compliant drive specifications. Three-tier pricing structure across premium, standard, and economy levels separates servo-drive precision tiers from commodity AC drive volumes. Cost compression in standard AC drives is intensifying because Chinese state-backed retrofit programs consolidate procurement volumes around domestic suppliers. Water utility districts in California and Texas exhibit lowest price sensitivity through multi-year performance contracting, while Indian textile OEMs in Gujarat industrial zones drive hardest bargain on unit economics.
Supply Chain Analysis
Inventory buffers for SiC power modules have thinned to 8-12 weeks against 20-week norms as mining and metals operators in Western Australia accelerate 3.3kV drive deployments. Substrate fabrication concentrates in Japan, Germany, and the United States with epitaxial wafer growth anchored in Japanese technical centers. Rare earth magnet supply draws from Chinese processing facilities, creating tariff exposure from export quota adjustments. Distribution runs through authorized system integrators in process industries and direct OEM channels for volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VFD market sits in early-cycle expansion as EU F-Gas phase-down schedules and China's dual carbon retrofit mandates force replacement demand across installed motor bases. Wide-bandgap semiconductor cost curves and embedded cybersecurity certification requirements are reshaping procurement criteria before mass adoption inflection.
For Market Incumbents: Shield installed base relationships through predictive maintenance service contracts that bundle drive diagnostics with operational uptime guarantees. SiC semiconductor allocation agreements with Japanese substrate specialists provide supply security against Chinese rare earth volatility. IEC 62443 cybersecurity certification investment extends product qualification cycles but locks out mid-tier competitors lacking compliance infrastructure.
For New Entrants and Emerging Players: Anchor in India's PLI scheme manufacturing corridors where localized drive assembly demand outruns established service network coverage. Gujarat and Tamil Nadu textile processing zones offer lowest competitive density for precision servo-drive applications. Partner with German technical universities on captive apprenticeship pipelines to overcome power electronics talent collapse.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive SiC sourcing and embedded software capabilities. Long-term viability over the projection horizon rests on service attach rate expansion rather than hardware margin extraction. Watch for inflection when IEC efficiency design standards compress addressable market for non-compliant legacy units below critical mass.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Sourcing | Captive wafer allocation insulates against Japanese supplier concentration risk. |
| Predictive Maintenance Service Contract Expansion | California water utility districts unbundle hardware from multi-year performance agreements. |
| IEC 62443 Cybersecurity Certification Investment | Compliance timelines extend product cycles but create vendor qualification moats. |
| Regional Assembly Expansion in India | PLI scheme incentives localize production for Gujarat pharmaceutical processing demand. |
| Direct Torque Control Technology Licensing | Mining operators in Western Australia deploy 3.3kV systems for conveyor regenerative braking. |
Study Parameters
A spread of perspectives from plant engineers at water treatment facilities, OEM procurement teams in industrial automation, power electronics specialists at German technical universities, and aftermarket service directors converged on the working assumptions. Secondary validation drew from IEC 61800 standards documentation, EPA motor efficiency rulemakings, EU Ecodesign Directive filings, and customs trade data on semiconductor substrate flows. Bottom-up unit demand modeling triangulated against top-down energy efficiency mandate penetration curves.
Segmentation dimensions modeled span product architecture, control technology tier, end-use industry concentration, and regional regulatory cluster across the analysis window. CAGRs derived from replacement cycle timing against efficiency mandate enforcement schedules and SiC cost parity projections. Forecast inputs incorporated F-Gas phase-down compliance timelines and China's dual carbon facility retrofit program acceleration.
Material uncertainties — silicon carbide wafer fabrication capacity expansion, rare earth export quota adjustments, and IEC cybersecurity certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions on semiconductor substitution pace and regulatory enforcement consistency. Revision becomes warranted when SiC module pricing crosses below IGBT parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
Europe Power Rental Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Egypt Power EPC Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Induction Heating System Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Romania Power EPC Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Process Air Heater Market