
 Asia-Pacific Steam Turbine Market | 2026-2036
Asia-Pacific Steam Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Steam Turbine Market Outlook
India's manufacturing corridor is fragmenting as domestic and foreign turbine suppliers establish parallel supply bases. Bharat Heavy Electricals Limited anchors the indigenous heavy fabrication segment with captive casting capacity. Shanghai Electric Group Company Ltd. extends its coastal manufacturing footprint to serve Southeast Asian export demand. Mitsubishi Power Asia Pacific Pte. Ltd. competes on ultra-supercritical technology leadership for high-efficiency installations.
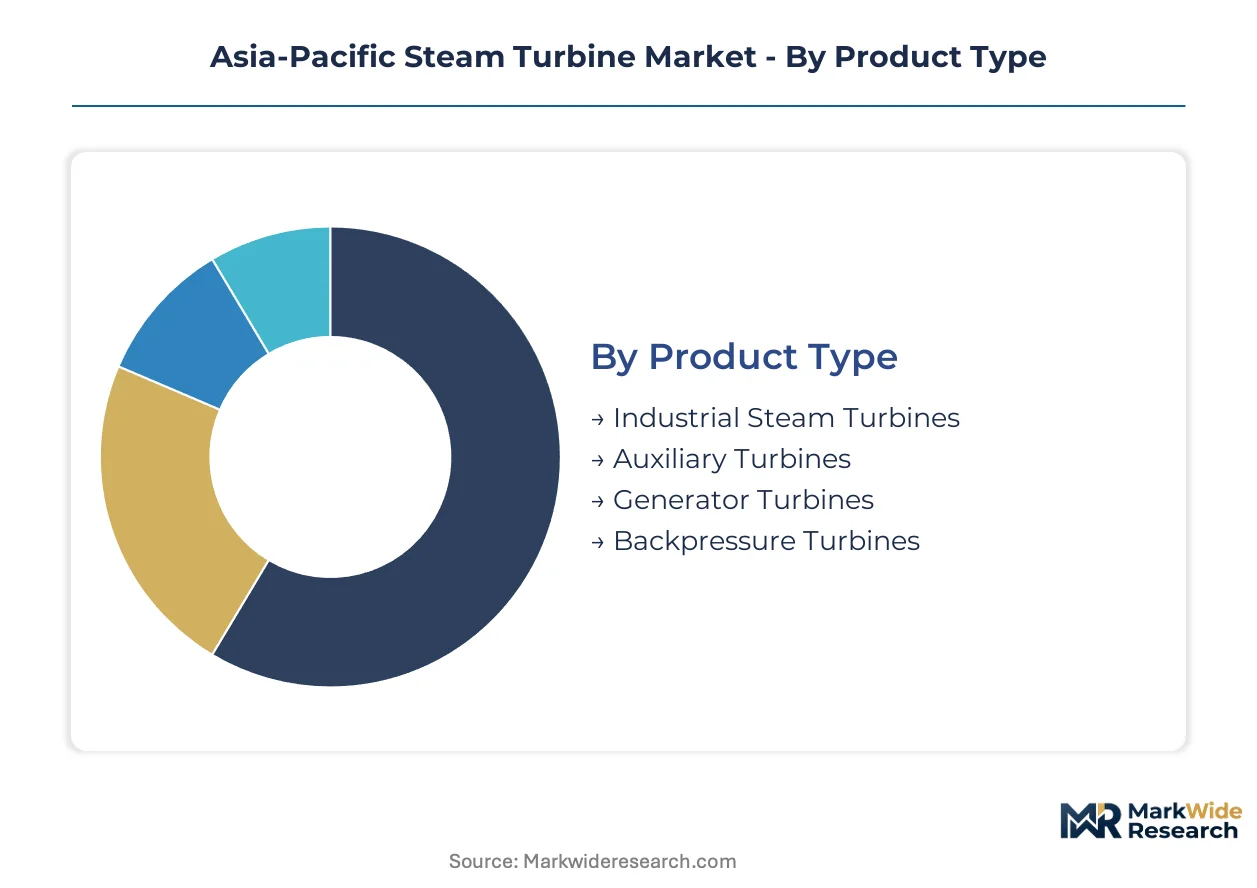
A steam turbine converts thermal energy from pressurized steam into rotational mechanical work, typically operating at inlet temperatures exceeding 540 degrees Celsius and pressures above 24 megapascals in modern power generation configurations. The equipment serves as the prime mover in thermal power cycles, driving electrical generators or mechanical loads across industrial process applications. Generator turbines occupy the largest installed base due to persistent baseload power requirements across emerging Asian economies, while backpressure turbines capture expanding margin pools in cogeneration deployments for chemical and petrochemical complexes. Retrofit services represent the fastest-growing service type as aging fleets in Japan and South Korea require efficiency upgrades to meet tightened emissions benchmarks.
India's Central Electricity Authority mandates efficiency standards for new thermal installations, while China's Ministry of Ecology and Environment enforces dual carbon compliance timelines that accelerate supercritical technology adoption. Japan's METI oversees grid stability regulations that preserve steam turbine relevance in mixed-renewable portfolios. Stakeholders must monitor regulatory divergence between carbon-intensity pathways and baseload reliability mandates as they calibrate regional investment priorities.
Market Dynamics
Dual carbon compliance timelines from China's Ministry of Ecology and Environment are compressing procurement cycles for high-efficiency steam turbine systems across Southeast Asian power markets. Equipment buyers now prioritize supercritical and ultra-supercritical configurations that satisfy both baseload reliability mandates and tightening emissions benchmarks.
Growth Catalysts
- Geothermal corridor expansion:Indonesia's state utility accelerates capacity additions in volcanic belt regions, creating sustained demand for corrosion-resistant turbine designs rated for high-enthalpy steam conditions.
- PLI scheme localization:India's production-linked incentive framework for domestic manufacturing reduces landed cost differentials for indigenous heavy fabrication, redirecting procurement toward domestic supply bases.
- Coal-to-gas transition zones:Vietnam's power development plan mandates combined-cycle retrofits at legacy coal sites, preserving steam turbine relevance through heat recovery steam generator integration.
Market Restraints
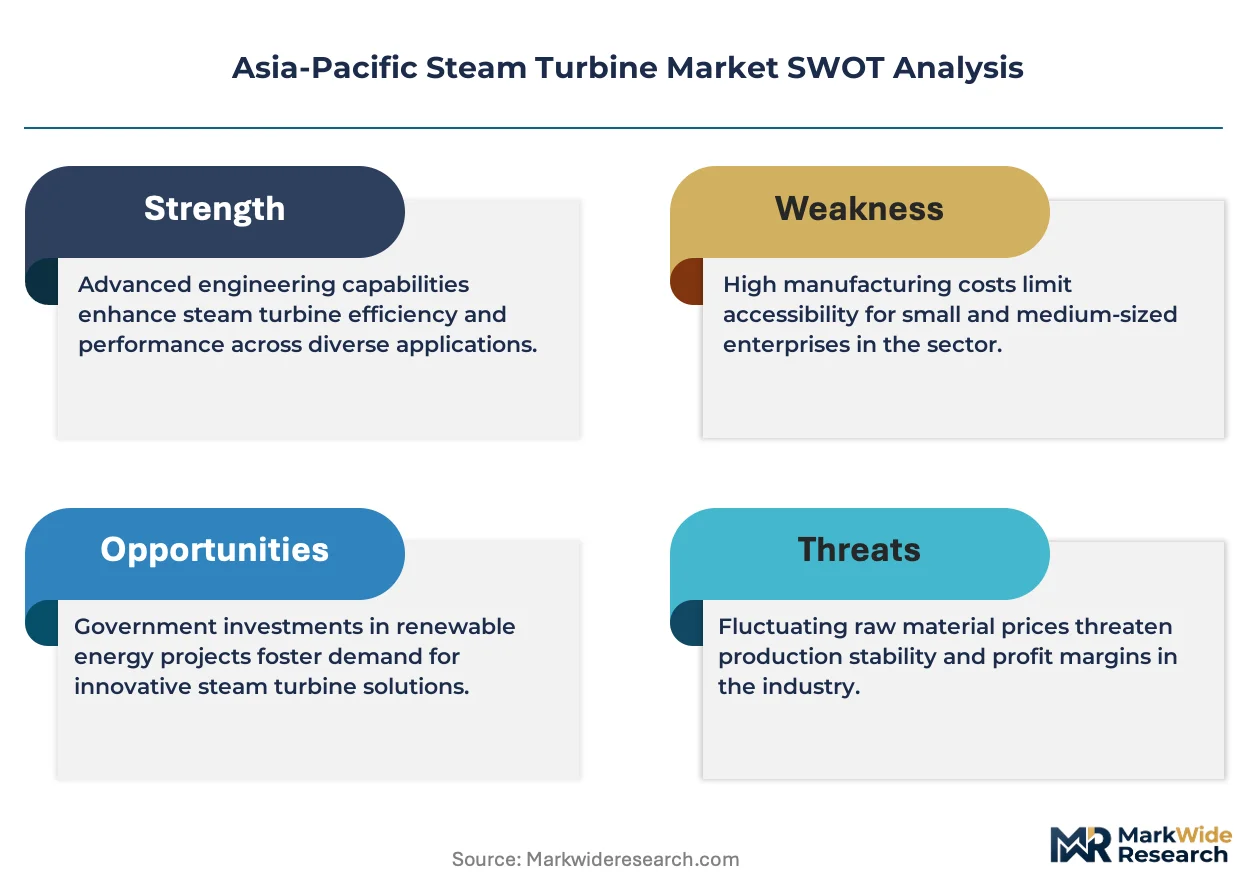
- Specialized alloy supply concentration:High-temperature rotor forgings depend on a limited supplier base concentrated in Japan and Germany, creating procurement bottlenecks for 600-degree Celsius rated units.
- Renewable substitution pressure:Utility-scale solar and offshore wind projects in South Korea and Taiwan displace greenfield thermal capacity, narrowing the addressable market for new steam turbine installations.
- Extended certification timelines:Japan's METI grid stability regulations impose multi-year type-approval processes for novel turbine configurations, delaying commercial deployment of advanced designs.
Strategic Opportunities
- Retrofit service white space:Aging subcritical fleets in Japan and South Korea require efficiency upgrades to meet tightened emissions benchmarks, creating aftermarket revenue pools for blade replacement and sealing system modernization.
- Industrial cogeneration penetration:Chemical complexes in Thailand and Malaysia adopt backpressure turbines for process steam integration, capturing margin pools outside traditional power generation.
- Cross-border equipment mobility:Decommissioned units from Australian coal closures relocate to Indonesian and Vietnamese secondary markets, enabling lower-capex deployment pathways.
Industry Challenges
- Welding specialist scarcity:Precision joining of nickel-based superalloys for high-temperature rotor assemblies requires certified technicians in short supply across Southeast Asian fabrication yards.
- Legacy control system integration:Digital turbine governors must interface with analog protection systems at 1980s-era Japanese and South Korean installations, complicating automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Steam Turbine Market |
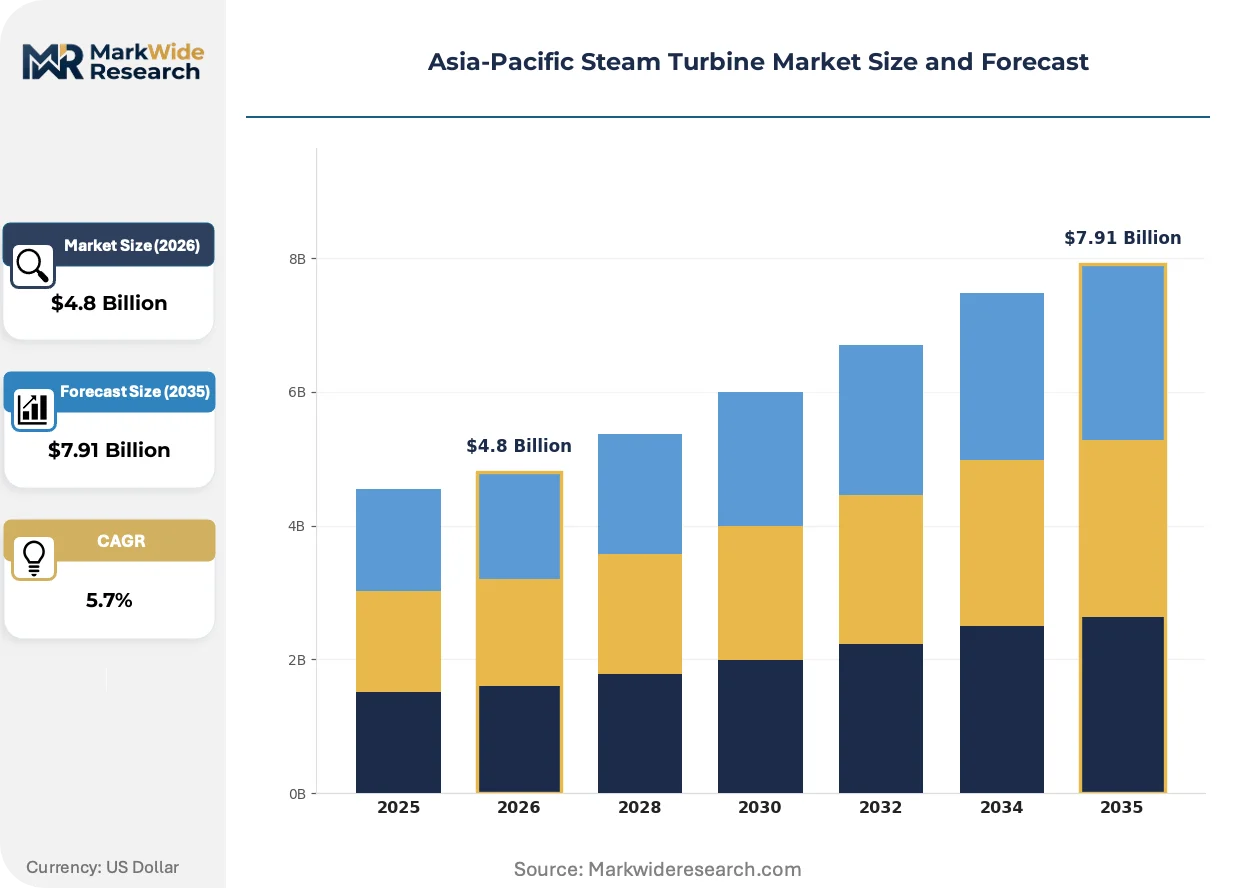
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Steam Turbines, Auxiliary Turbines, Generator Turbines, Backpressure Turbines End User: Power Plants, Manufacturing Facilities, Chemical Industries, Marine Applications Installation Type: Onshore, Offshore, Combined Cycle, Modular Service Type: Maintenance Services, Retrofit Services, Consulting Services, Operational Support |
| Companies Covered | Bharat Heavy Electricals Limited, Shanghai Electric Group Company Ltd., Siemens Energy, Fuji Electric, Doosan Skoda Power, General Electric, Mitsubishi Power Asia Pacific Pte. Ltd., Kawasaki Heavy Industries, Dongfang Turbine Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Steam Turbine Market Strategic Shifts
Steam turbine technology trajectories across Asia-Pacific converge on efficiency maximization and operational flexibility, driven by grid balancing requirements in high-renewable penetration markets. Equipment specifications now prioritize rapid ramp rates and part-load optimization alongside traditional baseload metrics.
Advanced blade aerodynamics utilizing three-dimensional flow modeling is migrating from aerospace-derived computational methods into power generation turbine design. Chinese and Japanese OEMs deploy these profiles in last-stage low-pressure sections to reduce exhaust losses. The technology is migrating from experimental prototypes at demonstration plants into serial production for 1,000-megawatt class units, compressing efficiency gaps between established suppliers and emerging competitors.
China's dual carbon goals enforcement through the Ministry of Ecology and Environment mandates supercritical minimum efficiency standards for new thermal installations. This regulatory pressure accelerates technology retirement timelines for subcritical assets and redirects capital toward advanced ultra-supercritical configurations. Procurement specifications in Vietnam and Indonesia increasingly incorporate these Chinese efficiency benchmarks as reference standards, extending Beijing's regulatory influence across regional equipment markets.
Power purchase agreement structures now unbundle long-term service contracts from initial equipment supply, enabling independent service provider entry. Indonesian geothermal operators and Vietnamese independent power producers negotiate separate maintenance agreements with specialized retrofit contractors rather than OEM-locked service terms. This pattern is most visible in Southeast Asian markets where project finance requirements favor cost-transparent procurement models over bundled lifecycle offerings.
Asia-Pacific Steam Turbine Market Segmentation
Steam turbine procurement across Asia-Pacific follows distinct technical and commercial logics that reshape vendor priorities. Equipment buyers segment demand by thermal cycle configuration, operational duty requirements, and lifecycle service needs rather than treating turbines as interchangeable prime movers.
Product Type:
Mature baseload configurations anchor procurement volumes while emerging designs capture efficiency premiums in transition markets.
- Generator Turbines:These units convert steam thermal energy into rotational mechanical work driving electrical generators at inlet temperatures exceeding 540 degrees Celsius. Demand concentrates in Indonesia's geothermal expansion corridors where state utility procurement prioritizes baseload reliability for volcanic belt installations.
- Backpressure Turbines:Configured to exhaust steam at pressures suitable for industrial process heating rather than condensing to vacuum. Chemical complexes in Thailand and Malaysia adopt these units for cogeneration deployments, capturing margin pools outside traditional power generation through process steam integration.
- Industrial Steam Turbines:Smaller-capacity units rated for mechanical drive applications in process industries.
- Auxiliary Turbines:Compact systems powering plant auxiliary loads such as feedwater pumps and fans.
Generator Turbines handle the majority of throughput; Backpressure Turbines are the fastest mover on share.
End User:
Cost tier stratification separates capital-intensive utility procurement from industrial buyers optimizing total operating cost.
- Power Plants:Centralized generation facilities procure ultra-supercritical configurations satisfying China's dual carbon compliance timelines enforced by the Ministry of Ecology and Environment. Vietnam's coal-to-gas transition zones mandate combined-cycle retrofits preserving steam turbine relevance through heat recovery steam generator integration.
- Chemical Industries:Petrochemical complexes deploy backpressure turbines for process steam cogeneration, prioritizing thermal efficiency over electrical output maximization. Facilities in Malaysia's Pengerang Integrated Complex represent concentrated demand for corrosion-resistant blade materials handling aggressive process environments.
- Manufacturing Facilities:Textile and paper mills in India's Tamil Nadu and Gujarat states install medium-pressure units for captive power.
- Marine Applications:LNG carriers and naval vessels require compact, high-reliability turbines for propulsion and auxiliary power.
Power Plants dominate capital deployment; Chemical Industries are expanding most quickly as process integration economics improve.
Installation Type:
Application context drives specification divergence between greenfield utility projects and retrofit industrial sites.
- Combined Cycle:Heat recovery steam generator configurations integrating gas turbine exhaust with steam turbine bottoming cycles. Vietnam's power development plan mandates these retrofits at legacy coal sites, redirecting procurement toward high-efficiency heat recovery configurations.
- Modular:Pre-fabricated turbine-generator skids reducing field construction duration for remote geothermal installations. Indonesia's state utility deploys these units in volcanic belt regions where site access constraints favor minimized civil works.
- Onshore:Conventional ground-mounted installations at centralized power stations and industrial complexes.
- Offshore:Platform-mounted turbines for offshore oil and gas processing facilities.
Combined Cycle absorbs the largest share of new investment; Modular configurations are climbing the fastest as remote site development accelerates.
Service Type:
Customer type stratification separates asset owners seeking lifecycle cost control from operators prioritizing availability guarantees.
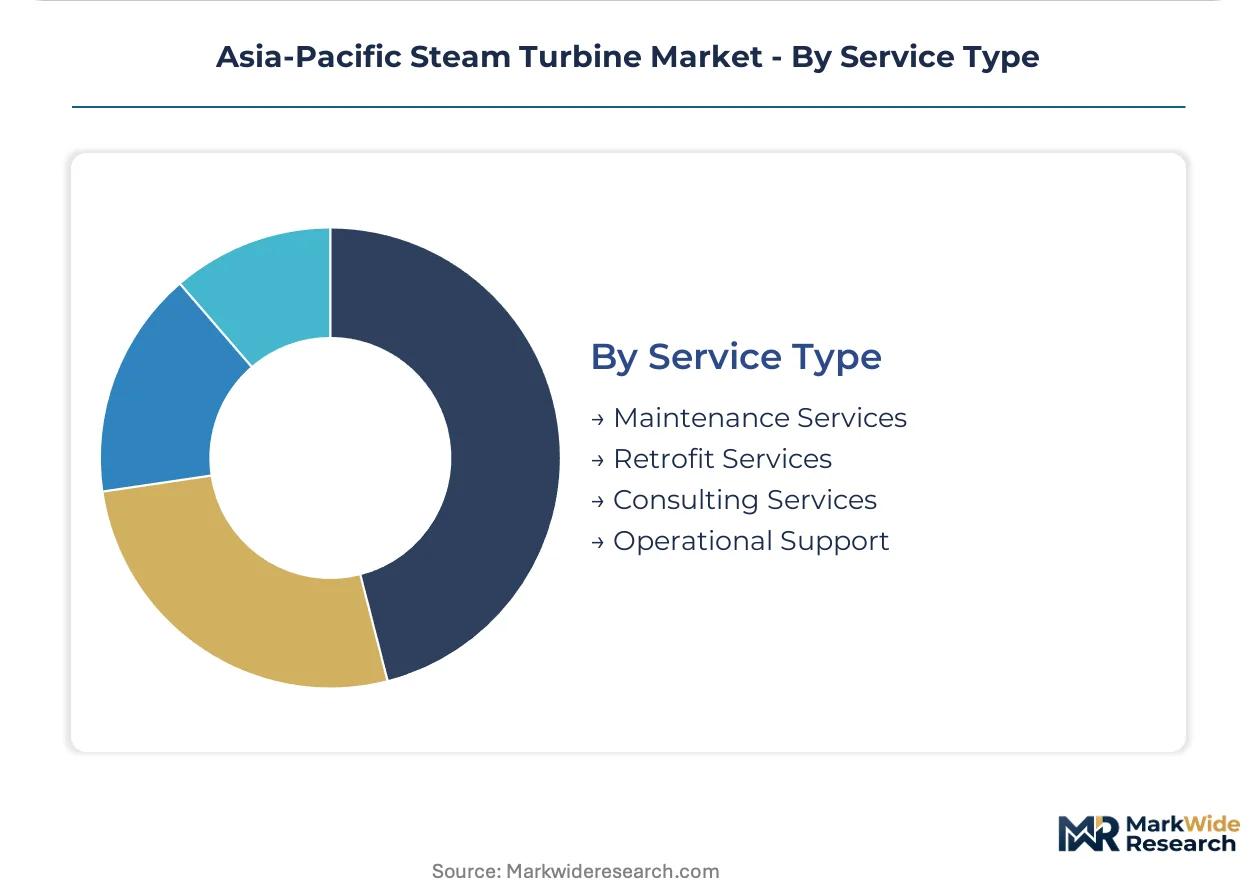
- Retrofit Services:Efficiency upgrades for aging subcritical fleets including blade replacement and sealing system modernization. Japan and South Korean installations from the 1980s require these interventions to meet tightened emissions benchmarks, creating aftermarket revenue pools independent of new equipment sales.
- Maintenance Services:Scheduled overhauls and condition-based monitoring preserving availability metrics. Indonesian geothermal operators negotiate separate maintenance agreements with specialized contractors rather than accepting OEM-locked service terms.
- Consulting Services:Engineering studies for fleet optimization and technology transition planning.
- Operational Support:Staff training and performance monitoring for owner-operated facilities.
Maintenance Services represents the largest service revenue category; Retrofit Services are gaining share fastest as aging fleet upgrade cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment anchors the regulatory framework reshaping procurement across the Asia-Pacific steam turbine market through dual carbon compliance timelines that mandate supercritical efficiency standards for new thermal installations.
China
Yangtze River Delta manufacturers scale ultra-supercritical turbine production for domestic power plant operators and Southeast Asian export demand. The Ministry of Ecology and Environment enforces dual carbon compliance timelines that accelerate technology retirement for subcritical assets. Shanghai Electric Group Company Ltd. extends its coastal manufacturing footprint to serve Indonesian and Vietnamese procurement.
India
Tamil Nadu and Gujarat industrial clusters drive captive power installations for textile and paper mills requiring medium-pressure steam turbine units. India's Central Electricity Authority mandates efficiency standards for new thermal installations through the PLI scheme for domestic manufacturing. Bharat Heavy Electricals Limited anchors indigenous heavy fabrication with captive casting capacity in the manufacturing corridor.
Japan
Kansai and Chubu regions host aging subcritical fleets from the 1980s requiring retrofit services for emissions compliance. Japan's METI oversees grid stability regulations that preserve steam turbine relevance in mixed-renewable portfolios and impose multi-year type-approval processes for novel configurations. Osaka-based fabricators concentrate on blade replacement and sealing system modernization for efficiency upgrades.
Indonesia
Volcanic belt geothermal corridors in Sumatra and Java sustain demand for corrosion-resistant turbine designs rated for high-enthalpy steam conditions. State utility procurement prioritizes modular pre-fabricated turbine-generator skids reducing field construction duration at remote sites. Independent power producers negotiate separate maintenance agreements with specialized contractors rather than accepting OEM-locked service terms.
Vietnam
Coal-to-gas transition zones in the Red River Delta and Mekong Delta mandate combined-cycle retrofits preserving steam turbine relevance through heat recovery steam generator integration. The power development plan redirects procurement toward high-efficiency heat recovery configurations at legacy coal sites. Project finance requirements favor cost-transparent procurement models over bundled lifecycle offerings.
Asia-Pacific Steam Turbine Market Competitive Environment
State-affiliated heavy fabricators and diversified industrial conglomerates split the market between domestic supply base anchoring and technology-licensed export positioning. The vendor structure concentrates around three strategic archetypes: captive casting specialists with indigenous supply chains, coastal export-oriented manufacturers with regional logistics advantages, and technology-licensed assemblers leveraging foreign engineering partnerships. Consolidation pressure intensifies through backward integration into rotor forging capacity and strategic alliances for supercritical design licensing.
Among Asia-Pacific-based fabricators, Bharat Heavy Electricals Limited, Shanghai Electric Group Company Ltd., and Mitsubishi Power Asia Pacific Pte. Ltd. occupy distinct competitive positions. Bharat Heavy Electricals Limited exemplifies the captive-capability archetype through indigenous heavy fabrication infrastructure. Shanghai Electric Group Company Ltd. represents coastal export-oriented manufacturing with regional logistics positioning. Mitsubishi Power Asia Pacific Pte. Ltd. sits within the technology-licensed tier, anchoring ultra-supercritical expertise for high-efficiency installations.
| Leading Market Players |
|---|
| Bharat Heavy Electricals Limited |
| Shanghai Electric Group Company Ltd. |
| Siemens Energy |
| Fuji Electric |
| Doosan Skoda Power |
| General Electric |
| Mitsubishi Power Asia Pacific Pte. Ltd. |
| Kawasaki Heavy Industries |
| Dongfang Turbine Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Jakarta maritime corridors carry supercritical turbine components at freight rates that compress landed cost differentials between Chinese coastal manufacturers and Southeast Asian project sites. This logistics dynamic amplifies pricing power for Yangtze River Delta fabricators while forcing Indian and Japanese suppliers to differentiate through after-sales bundling rather than equipment cost parity.
Pricing Analysis
Geographic price spreads between Chinese coastal manufacturing and Indonesian geothermal deployment sites exceed those within domestic Indian procurement by margins that reflect freight and duty stacking. Three-tier pricing structure across ultra-supercritical premium, supercritical standard, and subcritical economy levels segments buyer tiers, with state utilities in Vietnam and Indonesia exhibiting highest price sensitivity due to project finance constraints. Cost compression in the standard tier is intensifying because Shanghai Electric and Dongfang Turbine expand modular skid offerings. Independent power producers in Southeast Asian markets demonstrate least price sensitivity when efficiency guarantees unbundle from initial capital outlay.
Supply Chain Analysis
Rotor forging capacity concentrates at Japan Steel Works, Bharat Forge, and select Chinese heavy fabrication complexes that serve as contract manufacturers for OEM final assembly. High-temperature alloy supply draws from German and Japanese specialty steel producers, with nickel-based superalloy dependencies creating single-source vulnerability for 600-degree Celsius rated units. Distribution runs through EPC contractors and state utility procurement offices rather than direct OEM-to-operator channels, complicating price transparency for Indonesian geothermal developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Indonesian state utility consolidation of geothermal procurement and Vietnamese independent power producer aggregation under centralized power development plan mandates. This consolidation shifts negotiation leverage toward equipment specification standardization and away from OEM-locked service terms.
For Market Incumbents: Pre-empt rotor forging bottlenecks by securing captive capacity at Japanese or Indian specialty steel producers before alloy allocation tightens further. Anchor aftermarket revenue through blade replacement and sealing system modernization contracts for 1980s-era Japanese and South Korean installations facing emissions compliance deadlines. METI grid stability regulations preserve incumbent relevance but compress technology refresh timelines.
For New Entrants and Emerging Players: Thailand's chemical corridor underpenetration by specialized backpressure turbine suppliers offers white-space entry for corrosion-resistant designs rated for aggressive process environments. Target modular pre-fabricated configurations for Indonesian volcanic belt sites where civil works constraints favor minimized field construction. Partner with specialized retrofit contractors rather than competing for OEM-locked maintenance agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core turbine divisions lacking supercritical technology licensing. Long-term viability hinges on exposure to geothermal baseload expansion and coal-to-gas transition zones rather than renewable substitution markets. Watch for Indonesian state utility procurement standardization as inflection signal for equipment commoditization risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rotor Forging | Secures nickel-based superalloy supply for 600°C ultra-supercritical units against Japanese-German concentration. |
| Modular Skid Pre-fabrication | Reduces Indonesian volcanic belt site construction duration where access constraints dominate project economics. |
| Retrofit Service Unbundling | Captures blade replacement revenue from 1980s Japanese and South Korean subcritical fleets facing emissions deadlines. |
| Geothermal Corrosion-Resistant Design | Addresses high-enthalpy steam conditions in Sumatra and Java expansion corridors with specialized blade metallurgy. |
| Combined-Cycle Heat Recovery Integration | Preserves steam turbine relevance in Vietnam's coal-to-gas transition zones through bottoming cycle configuration. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads across Indonesia, Vietnam, India, and Japan; and secondary validation through IEA power generation databases, FERC-equivalent regulatory filings, customs trade records for turbine component flows, and equipment procurement disclosure documents. Bottom-up project pipeline aggregation triangulated against top-down market sizing from installed capacity and replacement cycle analysis.
Forecast inputs spanned thermal cycle configuration adoption curves, regulatory compliance timeline enforcement patterns, and alloy supply capacity constraints across the projection horizon. Segmentation modeling incorporated product type, end-use industry, installation context, and service contract structure dimensions. CAGRs derived from equipment shipment trajectories and aftermarket revenue intensity assumptions, with cross-reference to power plant commissioning schedules and industrial cogeneration penetration rates.
Practitioners should monitor dual carbon policy enforcement intensity, geothermal corridor development pace, and rotor forging capacity utilization for early signals of forecast revision. Quarterly review of Indonesian state utility procurement standardization, Vietnamese IPP financing closure rates, and Japanese METI type-approval backlog is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Natural Gas Turbine Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
AC Power Sources Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
US Power EPC Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Thailand Power Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Global Power System Simulator Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Gas Fixed Power Capacitors Sales Market