
 Power Recovery Winches Market | 2026-2036
Power Recovery Winches Market Size, Share, and Industry Trends Forecast 2026-2036
Power Recovery Winches Market Analytics
The capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in power recovery winches. Warn Industries leverages captive foundry capacity and in-house motor winding to control cost structures across the electric winch segment. Ramsey Winch anchors its position through specialized drum engineering for military and utility applications. Comeup Industries competes on compact planetary drive systems designed for Asia-Pacific construction and marine markets.
Power recovery winches are electromechanical or hydraulically actuated drum machines engineered to retrieve immobilized loads, typically rated between 2,000 and 120,000 pounds line pull, with automatic braking systems and variable speed control. These systems serve critical functions in offshore vessel operations, mining slope recovery, and construction site material handling where standard traction equipment cannot access or secure disabled machinery. Hydraulic winches dominate the high-load offshore and mining segments due to thermal durability under continuous duty cycles. Electric winches lead in portable and fixed installation categories where grid or battery power eliminates hydraulic infrastructure. The marine recovery application segment shows the fastest structural expansion, driven by subsea intervention vessel retrofit programs and port authority emergency response fleet modernization.
The United States Coast Guard and OSHA enforce load-testing and operator-certification mandates that shape product design and aftermarket service requirements for domestic suppliers. The EU Machinery Directive and CE marking framework govern winch deployment across European offshore and construction markets, creating compliance barriers for non-certified imports. Buyers must monitor evolving EPA Tier 4 and EU Stage V emissions rules affecting diesel-hydraulic power pack configurations in mobile recovery systems.
Market Dynamics
Decommissioning obligations on aging offshore platforms are forcing operators to accelerate fleet renewal, concentrating procurement demand around heavy-duty hydraulic systems capable of continuous subsea retrieval operations.
Growth Catalysts
- OSHA Winch Safety Standards:Updated certification mandates in the United States are compelling fleet operators to replace legacy braking systems, creating replacement demand across Gulf Coast ports.
- Subsea Intervention Vessels:Retrofit programs for offshore support fleets are expanding the installed base of high-capacity electric winches rated above 50,000 pounds line pull.
- EU Machinery Directive:CE marking requirements for load-bearing recovery systems are filtering non-compliant imports, protecting domestic European manufacturers.
Market Restraints
- Specialized Steel Alloys:Drum forging and heat-treatment capacity concentrates in German and Japanese foundries, exposing assemblers to input cost volatility and extended lead times.
- Hydraulic Infrastructure Dependency:High-load offshore segments require integrated power pack systems, limiting electric winch penetration where deck space for diesel-hydraulic units is already committed.
- REACH Chemical Compliance:European coating and lubricant specifications are raising formulation costs for corrosion-resistant finishes on marine-grade winch housings.
Strategic Opportunities
- Battery-Electric Power Packs:Convergence of lithium-ion energy density improvements with regenerative braking is opening port authority emergency response fleets to cordless electric retrieval systems.
- India Port Modernization:Sagarmala infrastructure investments are creating first-time demand for heavy-duty recovery equipment at minor ports previously served by manual rigging.
- EPA Tier 4 Flexibility:Emissions credit trading for diesel-hydraulic units is incentivizing manufacturers to develop cleaner-burning power pack configurations for mobile construction applications.
Industry Challenges
- Subsea Electronics Certification:IECEx and ATEX compliance timelines for variable frequency drives in explosion-risk zones extend product development cycles by 8-14 months.
- Planetary Gear Integration:Compact drive systems from Asian suppliers require reverse-engineering to match North American drum mounting standards, complicating aftermarket parts availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Recovery Winches Market |
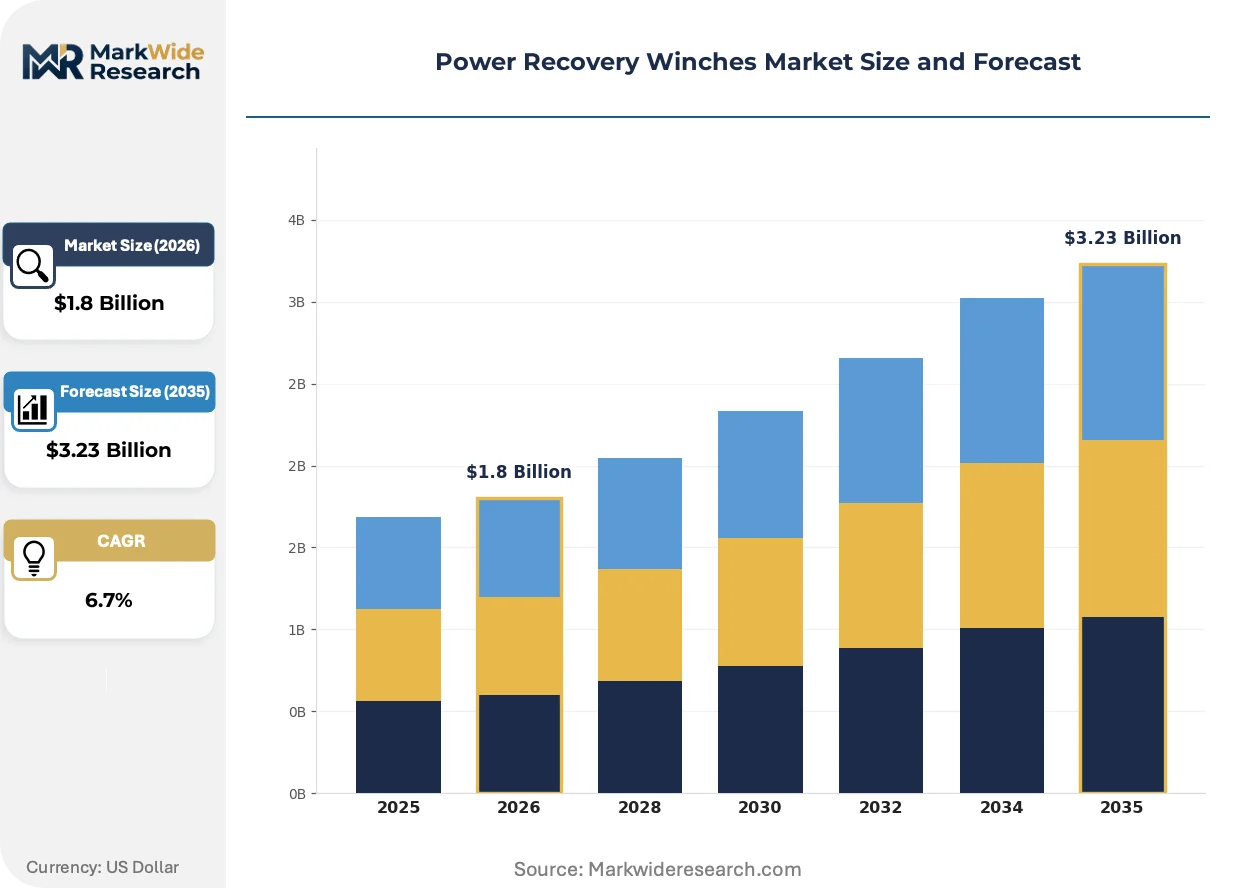
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Mechanical Winches, Pneumatic Winches Application: Offshore Operations, Industrial Lifting, Marine Recovery, Construction Projects Installation Type: Fixed Systems, Portable Systems, Integral Systems, Standalone Units End User: Construction Companies, Energy Sector, Marine Operators, Mining Industry |
| Companies Covered | Warn Industries, Ramsey Winch, Superwinch, Comeup Industries, Ingersoll Rand, Thern Inc., Mile Marker Industries, Caterpillar Inc., Paccar Winch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Recovery Winches Market Evolving Landscape
Synthetic rope materials and intelligent load monitoring are redrawing performance benchmarks across marine and mining recovery applications, compressing the traditional advantage of steel cable systems.
High-modulus polyethylene (HMPE) rope is fragmenting the steel cable monopoly in offshore vessel operations. Platform supply vessel operators in the North Sea and Gulf of Mexico are retrofitting existing drums with fiber rope compatibility kits to reduce deck weight and eliminate corrosion fatigue. The shift is fragmenting aftermarket revenue streams as rope replacement intervals compress from years to months.
EU Stage V emissions frameworks are tightening particulate limits on diesel-hydraulic power packs used in European port operations. Manufacturers are responding with dual-fuel configurations and exhaust after-treatment systems that add 15-20% to power pack unit costs. The construction rental channel is absorbing these premiums through extended lease terms rather than capital purchase.
Condition-based maintenance contracts are displacing traditional time-based service agreements in North American mining operations. Fleet managers at slope recovery sites are subscribing to telemetry-enabled monitoring that predicts brake wear and motor thermal stress. The model is compressing distributor margins while locking in multi-year parts supply commitments with original equipment manufacturers.
Power Recovery Winches Market Segmentation
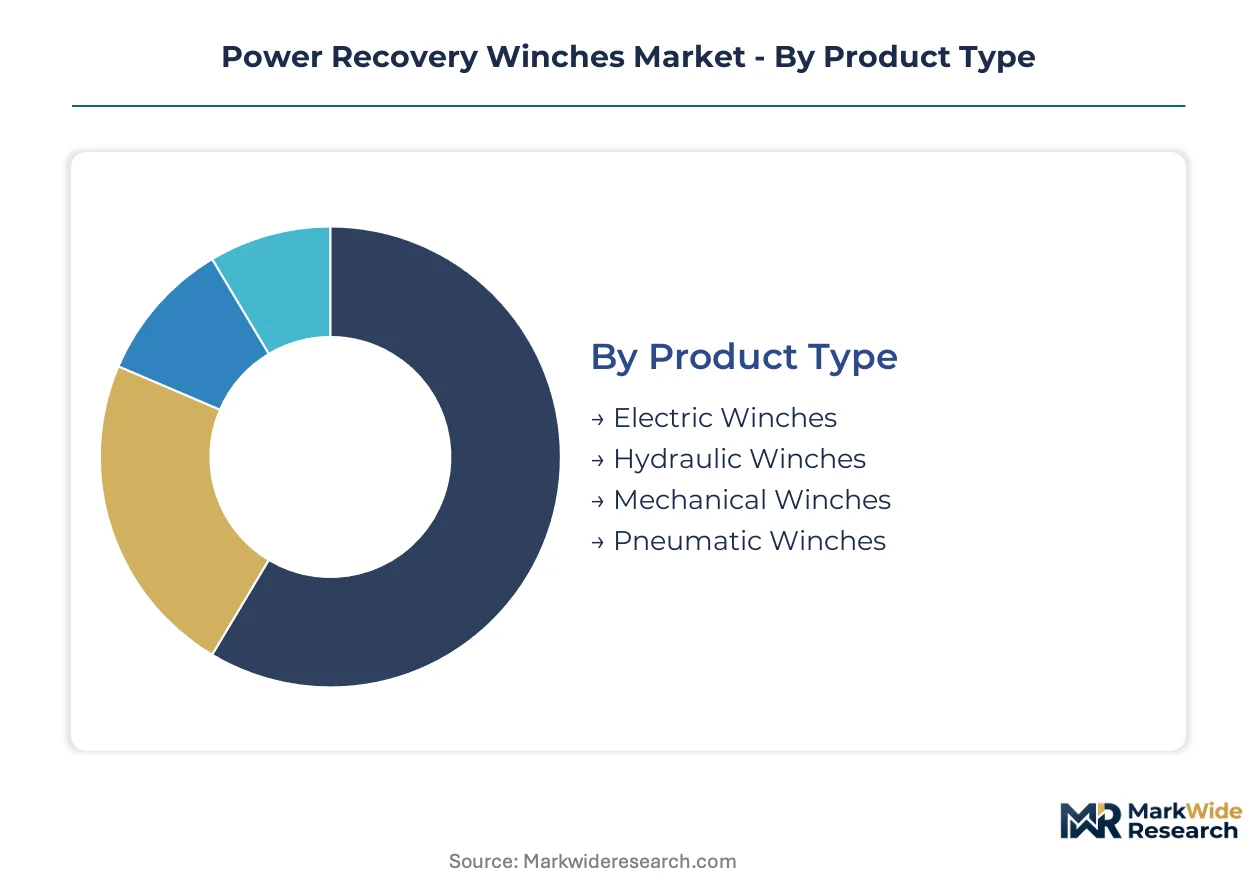
Power recovery winches serve divergent operational environments where load ratings, duty cycles, and infrastructure constraints dictate technology selection. Segmentation reveals how offshore operators, construction fleets, and mining contractors prioritize different performance trade-offs across electric, hydraulic, and mechanical drive systems.
Product Type:
Electric winches dominate domestic procurement in grid-connected markets, while hydraulic systems anchor export demand from specialized manufacturing clusters.
- Electric Winches:These systems deploy permanent magnet motors and variable frequency drives rated from 2,000 to 50,000 pounds line pull. Demand concentrates in United States Gulf Coast port modernization programs where OSHA-mandated brake upgrades are forcing fleet replacements.
- Hydraulic Winches:High-pressure piston motor configurations deliver continuous duty cycles above 75,000 pounds line pull. Mining slope recovery operations in Western Australia and Chilean copper belts specify these for thermal durability under sustained load.
- Mechanical Winches:Hand-crank and power-take-off variants persist in remote construction sites lacking electrical infrastructure.
- Pneumatic Winches:Compressed-air drive systems serve explosion-risk zones where IECEx certification mandates exclude electric alternatives.
Hydraulic winches hold the largest share; momentum sits with electric systems as battery power density improves.
Application:
Cost tier stratification separates capital-intensive offshore specifications from price-sensitive construction rentals.
- Offshore Operations:Subsea intervention vessels require explosion-proof enclosures and active heave compensation rated to 120,000 pounds line pull. North Sea operators are retrofitting fleets with synthetic rope compatibility to reduce topside weight.
- Marine Recovery:Port authority emergency response fleets specify rapid-deployment electric systems with regenerative braking. Indian Sagarmala investments are creating first-time demand at minor ports previously dependent on manual rigging.
- Industrial Lifting:Manufacturing and logistics facilities deploy fixed-mount electric winches for material handling below 30,000 pounds.
- Construction Projects:Mobile hydraulic units with diesel power packs dominate rental channels despite EPA Tier 4 compliance premiums.
Offshore operations command the highest unit margins; marine recovery is climbing the fastest as port infrastructure ages.
Installation Type:
Volume concentration favors standardized portable configurations, while margin capture resides in engineered fixed systems.
- Fixed Systems:Permanently mounted deck machinery on platform supply vessels integrates with vessel management systems. Norwegian and Brazilian shipyards specify these for newbuild contracts with 25-year service intervals.
- Portable Systems:Skid-mounted hydraulic units with quick-connect fittings serve construction rental fleets requiring field redeployment. United States equipment rental chains are expanding inventory ahead of infrastructure stimulus disbursements.
- Integral Systems:Winch-drum assemblies built into OEM equipment such as tow trucks and recovery vehicles.
- Standalone Units:Self-contained electric or pneumatic systems for temporary marine and mining applications.
Fixed systems retain the deepest aftermarket attachment; portable configurations are expanding most quickly through rental channel penetration.
End User:
Customer type determines procurement modality, with energy sector direct purchase contrasting construction rental dependence.
- Energy Sector:Integrated oil companies and offshore contractors specify custom hydraulic systems through multi-year frame agreements. Decommissioning obligations on United Kingdom and Norwegian continental shelf assets are accelerating replacement cycles.
- Marine Operators:Tug and salvage fleets prioritize rapid-spooling electric winches with synthetic rope packages. Japanese and South Korean shipowners are retrofitting existing drums to reduce crew handling injuries.
- Construction Companies:Rental-dependent procurement favors standardized portable hydraulic units with predictable maintenance costs.
- Mining Industry:Slope recovery operations in South African platinum and Indonesian nickel belts subscribe to condition-based maintenance contracts with telemetry monitoring.
Energy sector procurement holds the largest contract value; mining industry adoption is gaining share fastest through predictive service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German drum-forging clusters where specialized heat-treatment capacity commands premiums, while Chinese assemblers compete on planetary drive unit costs. This asymmetry shapes procurement patterns across offshore, mining, and port modernization segments.
United States
Gulf Coast decommissioning obligations and port infrastructure renewal are accelerating heavy-duty hydraulic winch procurement. OSHA updated winch safety standards mandate brake system replacements, forcing fleet operators at Houston and New Orleans terminals into compliance-driven upgrade cycles. United States Coast Guard load-testing requirements shape aftermarket service contracts for domestic suppliers.
Germany
Drum forging and heat-treatment capacity for high-load applications concentrates in German foundries, exposing assemblers to input cost volatility. EU Machinery Directive CE marking requirements filter non-compliant imports, protecting domestic manufacturers serving North Sea offshore operators. Hamburg and Bremen shipyards specify fixed-mount deck machinery with 25-year service intervals for platform supply vessel newbuilds.
China
Planetary drive system manufacturing clusters supply compact winch configurations for Asia-Pacific construction and marine markets. Domestic producers face REACH chemical compliance barriers on corrosion-resistant coatings for European export. Shanghai and Guangzhou port authorities are modernizing emergency response fleets with rapid-deployment electric systems.
Norway
Continental shelf decommissioning timelines are accelerating replacement cycles for subsea intervention vessel equipment. Norwegian shipyards integrate winch-drum assemblies with vessel management systems for newbuild contracts. Stavanger and Bergen offshore service hubs specify synthetic rope compatibility retrofits to reduce topside weight on platform supply vessels.
India
Sagarmala infrastructure investments are creating first-time demand for heavy-duty recovery equipment at minor ports previously dependent on manual rigging. Central Electricity Authority regulations shape electrical safety standards for grid-connected port installations. Mumbai and Chennai port trusts are procuring battery-electric power packs for emergency response fleet modernization.
Power Recovery Winches Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the power recovery winches sector. Integrated manufacturers with captive foundry capacity control cost structures in high-load hydraulic segments, while specialized drum engineers capture premium margins in military and utility applications. Component assemblers compete on compact drive systems for price-sensitive construction markets. M&A activity concentrates on securing heat-treatment capacity, and strategic partnerships target synthetic rope compatibility retrofits for existing drum installations.
Among North American manufacturers, Warn Industries exemplifies the integrated archetype through in-house motor winding capabilities, while Ramsey Winch occupies a position emphasizing specialized drum engineering. Comeup Industries represents the Asia-Pacific compact drive specialist tier. These three anchors illustrate how geographic manufacturing footprints and technical specializations stratify competitive positioning across electric, hydraulic, and planetary drive segments.
| Leading Market Players |
|---|
| Warn Industries |
| Ramsey Winch |
| Superwinch |
| Comeup Industries |
| Ingersoll Rand |
| Thern Inc. |
| Mile Marker Industries |
| Caterpillar Inc. |
| Paccar Winch |
| Others |
Value Network & Pricing Analysis
Drum-forging scale economies in German and Japanese foundries concentrate thermal-treatment capacity for high-load applications, compressing margin structures for assemblers lacking captive heat-treatment facilities while elevating price floors for certified marine-grade configurations. This concentration forces buyers into long-term frame agreements with integrated manufacturers or extended lead-time acceptance with component suppliers.
Pricing Analysis
Configured-to-order pricing for fixed-mount deck machinery on platform supply vessels commands substantial premiums over standard portable hydraulic units sold through construction rental channels. Price differentiation rests on IECEx certification tier and synthetic rope compatibility integration, with explosion-proof enclosures carrying material premiums. Cost compression in electric winch segments is intensifying because lithium-ion battery pack costs are declining faster than hydraulic power pack compliance costs. Construction rental fleets exhibit highest price sensitivity, while integrated oil companies purchasing subsea intervention equipment prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of specialized steel alloys and planetary gear components dominates procurement strategy among North American assemblers, mitigating lead-time volatility from German and Japanese forging clusters. Supply concentration centers on Germany for drum forging, Japan for heat-treatment capacity, and China for compact planetary drive systems. Raw material dependencies include high-strength steel alloys, permanent magnet motor components, and corrosion-resistant marine coatings. Single-source vulnerability in IECEx-certified variable frequency drive sourcing creates bottleneck risk for explosion-proof electric winch production. Distribution runs through OEM direct sales for offshore energy contracts and equipment rental chains for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power recovery winches market is entering a cyclical recovery phase driven by offshore platform decommissioning obligations accelerating fleet renewal timelines across North Sea and Gulf of Mexico operators.
For Market Incumbents: Shield margin structures by securing captive heat-treatment capacity through backward integration into drum forging or long-term offtake agreements with German foundry clusters. Accelerate IECEx and ATEX certification investment to extend compliance lead times that deter Asian component assemblers from entering explosion-risk segments. Counter synthetic rope retrofit demand by bundling fiber compatibility kits with multi-year service contracts that lock in aftermarket parts revenue. For New Entrants and Emerging Players: Aftermarket telemetry monitoring for brake wear prediction represents an under-served service layer where incumbent OEMs cede margin to distributors. Target Indian port modernization programs under Sagarmala infrastructure investments, where first-time demand for heavy-duty recovery equipment at minor ports lacks established supplier relationships. Pursue battery-electric power pack development for port authority emergency response fleets as a go-to-market angle that bypasses hydraulic infrastructure incumbency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive foundry capacity and in-house motor winding capabilities over pure-play component assemblers. Long-term viability hinges on exposure to decommissioning-driven replacement cycles rather than newbuild offshore vessel demand. Acquisition targets should display synthetic rope compatibility engineering and condition-based maintenance contract portfolios. Watch IECEx certification timeline extensions as an inflection indicator for competitive moat durability in explosion-risk applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drum Forging | Secures heat-treatment capacity for high-load marine applications against German foundry bottlenecks. |
| Synthetic Rope Compatibility Retrofit | Captures platform supply vessel retrofit demand from North Sea operators reducing topside weight. |
| Battery-Electric Power Pack Development | Opens port authority emergency response fleets to cordless systems as lithium-ion density improves. |
| IECEx Certification Acceleration | Extends product development timelines that filter non-compliant Asian imports from explosion-risk zones. |
| Condition-Based Maintenance Contracts | Locks in multi-year parts supply commitments with mining slope recovery operators through telemetry monitoring. |
Research Methodology
Desk research of customs trade databases, SEC filings from listed industrial equipment manufacturers, and offshore vessel specification registries preceded structured interviews with maintenance directors at mining operations, OEM procurement teams for platform supply vessels, aftermarket service heads at winch distributors, and port authority engineering officers. Primary fieldwork captured procurement modality preferences, replacement cycle timing, and certification compliance cost structures. Secondary validation drew from OSHA enforcement records, EU Machinery Directive implementation guidance, and EPA Tier 4 emissions compliance disclosures. Bottom-up unit economics triangulated against top-down market sizing from energy sector capital expenditure tracking.
Variance decomposition across product type, application, installation configuration, and end-user procurement modality anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include electric versus hydraulic drive technology, offshore versus marine recovery versus construction end-use, fixed versus portable installation, and energy sector direct purchase versus construction rental channel. CAGRs derived from regression analysis of historical replacement cycles against regulatory mandate implementation schedules. Industry-specific forecast inputs encompassed decommissioning obligation timelines for United Kingdom and Norwegian continental shelf assets and Sagarmala infrastructure disbursement pacing for Indian port modernization.
Forecasts assume regulatory continuity in OSHA winch safety standards, EU Machinery Directive CE marking requirements, and EPA Tier 4 emissions frameworks; material policy shifts would require re-modeling of replacement demand timing and compliance cost structures. Forecasts reflect assumptions regarding synthetic rope adoption velocity and battery-electric power pack energy density improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
China Power EPC Market
Power Equipment
Portable Power Station Market
Power Equipment
Romania Power EPC Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Air Preheater Market
Power Equipment
Turbine Governor Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Qatar Power EPC Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market