
 Auto Transformer Rectifier Unit (ATRU) Market | 2026-2036
Auto Transformer Rectifier Unit (ATRU) Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Transformer Rectifier Unit (ATRU) Market Insights
Silicon carbide is consolidating its position as a replacement for conventional silicon IGBTs in next-generation ATRU designs, cutting switching losses and thermal footprint. Crane Aerospace & Electronics leverages its aerospace power-electronics heritage to anchor premium defense and aviation contracts. Hitachi Energy sustains technology leadership through integrated grid-tie rectifier platforms. Siemens Energy competes on manufacturing scale across European rail electrification programs.
An Auto Transformer Rectifier Unit converts high-voltage AC input into controlled DC output through phase-shifted transformer windings paired with rectifier bridges, typically handling 25 kV/50 Hz or 15 kV/16.7 Hz railway supplies. The device enables efficient traction power distribution while isolating harmonic distortion from grid infrastructure. Three-phase ATRU configurations dominate heavy-traction installations where power density requirements exceed 5 MW per substation. Modular designs represent the fastest-expanding technology segment, allowing incremental capacity additions that reduce upfront capital commitment for rail operators. Silicon Controlled Rectifier technology retains share in legacy retrofit markets, though IGBT-based systems capture margin pools in new-build projects demanding higher switching frequencies.
The EU Green Deal and F-Gas Regulation drive efficiency benchmarks that shape ATRU procurement specifications across European rail networks. India's CEA mandates harmonize with BIS standards to enforce power-quality compliance on traction substations. China's GB standards and MIIT efficiency directives accelerate domestic silicon carbide supply chain maturation. Stakeholders must monitor semiconductor substrate availability and evolving efficiency certification thresholds to align product roadmaps with procurement cycles.
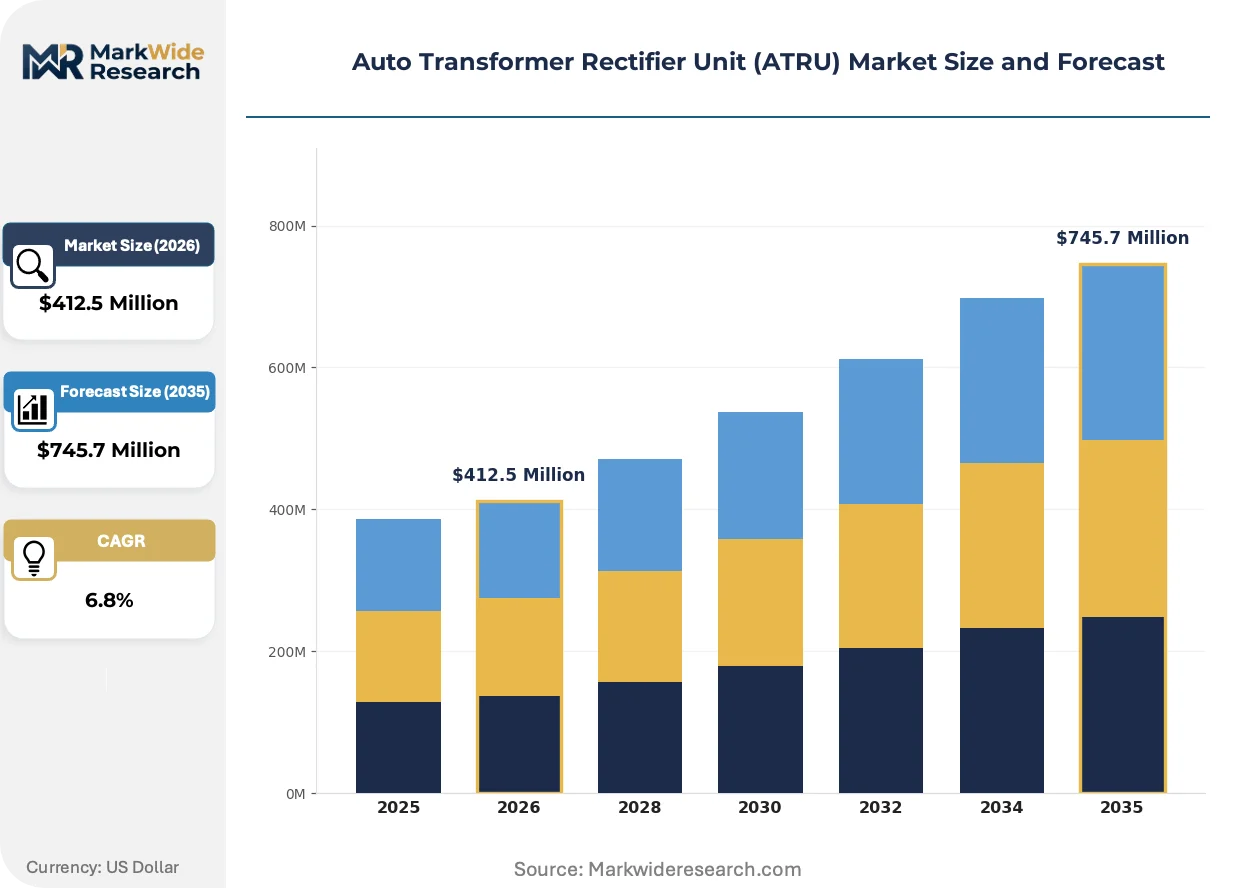
Market Dynamics
Silicon carbide substrate shortages and EU efficiency mandates are compressing ATRU design cycles while rail operators in India and China accelerate fleet electrification programs.
Growth Catalysts
- EU F-Gas Regulation:Efficiency thresholds for traction power equipment are forcing silicon carbide adoption into new-build substation designs across German and French rail networks.
- India's Dedicated Freight Corridor:Electrification mandates under CEA harmonized standards are generating concentrated procurement volumes for three-phase ATRU configurations.
- Silicon carbide semiconductors:Switching loss reductions of 40-70% versus silicon IGBTs are enabling higher power density in 25 kV/50 Hz railway supplies.
Market Restraints
- Substrate supply concentration:Silicon carbide wafer production clusters in Japan and the United States, creating input bottlenecks for European and Chinese ATRU manufacturers.
- Technical limitation:Gate oxide reliability in silicon carbide MOSFETs restricts operating temperatures below theoretical limits, complicating thermal management in tropical rail corridors.
- Regulatory friction:China's GB standards and MIIT efficiency directives impose divergent testing protocols that fragment product certification requirements for multinational suppliers.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian rail electrification programs in Vietnam and Indonesia remain below 15% network coverage, creating greenfield ATRU deployment potential.
- Technology convergence:Integration of solid-state circuit breakers with ATRU platforms enables fault-current limiting without mechanical interruption, reducing substation footprint.
- Regulatory tailwind:India's PLI scheme for power electronics manufacturing subsidizes domestic silicon carbide module assembly, lowering landed costs for railway tenders.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for silicon carbide gate driver design and thermal simulation concentrates in Germany, Japan, and the United States, constraining expansion timelines.
- Certification timeline compression:Parallel efficiency validation under EU F-Gas, India's CEA mandates, and China's GB standards extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Transformer Rectifier Unit (ATRU) Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Traction, Modular End User: Railways, Airports, Industrial Plants, Renewable Energy Installation: Indoor, Outdoor, Integrated, Standalone Technology: Silicon Controlled Rectifier, Thyristor, Diode, IGBT |
| Companies Covered | Raychem RPG, HIRECT, Crane Aerospace & Electronics, Wärtsilä, R Baker (Electrical), Hitachi Energy, Excelitas Technologies, Torotel, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Transformer Rectifier Unit (ATRU) Market Trends and Innovations
Solid-state power conversion architectures and procurement model evolution are restructuring how rail operators specify and deploy traction substation equipment.
Silicon carbide MOSFET modules are replacing conventional silicon IGBTs in 25 kV/50 Hz ATRU designs, enabling switching frequencies above 20 kHz. Chinese high-speed rail operators and Indian freight corridor developers are specifying these configurations for new-build substations exceeding 5 MW capacity. This semiconductor transition is modularizing ATRU platform architectures, allowing standardized power blocks that reduce engineering customization per project.
EU F-Gas Regulation efficiency benchmarks are mandating harmonic distortion limits below 3% for traction power supplies connected to grid infrastructure. Equipment manufacturers must redesign transformer-rectifier interfaces to meet these thresholds without oversized passive filters. Heavy-traction installations in Germany and France face the steepest compliance curves, driving integrated active filter adoption alongside main rectifier bridges.
Rail operators are unbundling after-sales service contracts from initial equipment procurement, separating maintenance obligations across specialized service providers. This fragmentation disrupts traditional turnkey supplier relationships in European and Indian markets. Chinese state rail operators resist this pattern, retaining integrated procurement through CRRC supply chains, creating divergent commercial models across major demand centers.
Auto Transformer Rectifier Unit (ATRU) Market Segmentation
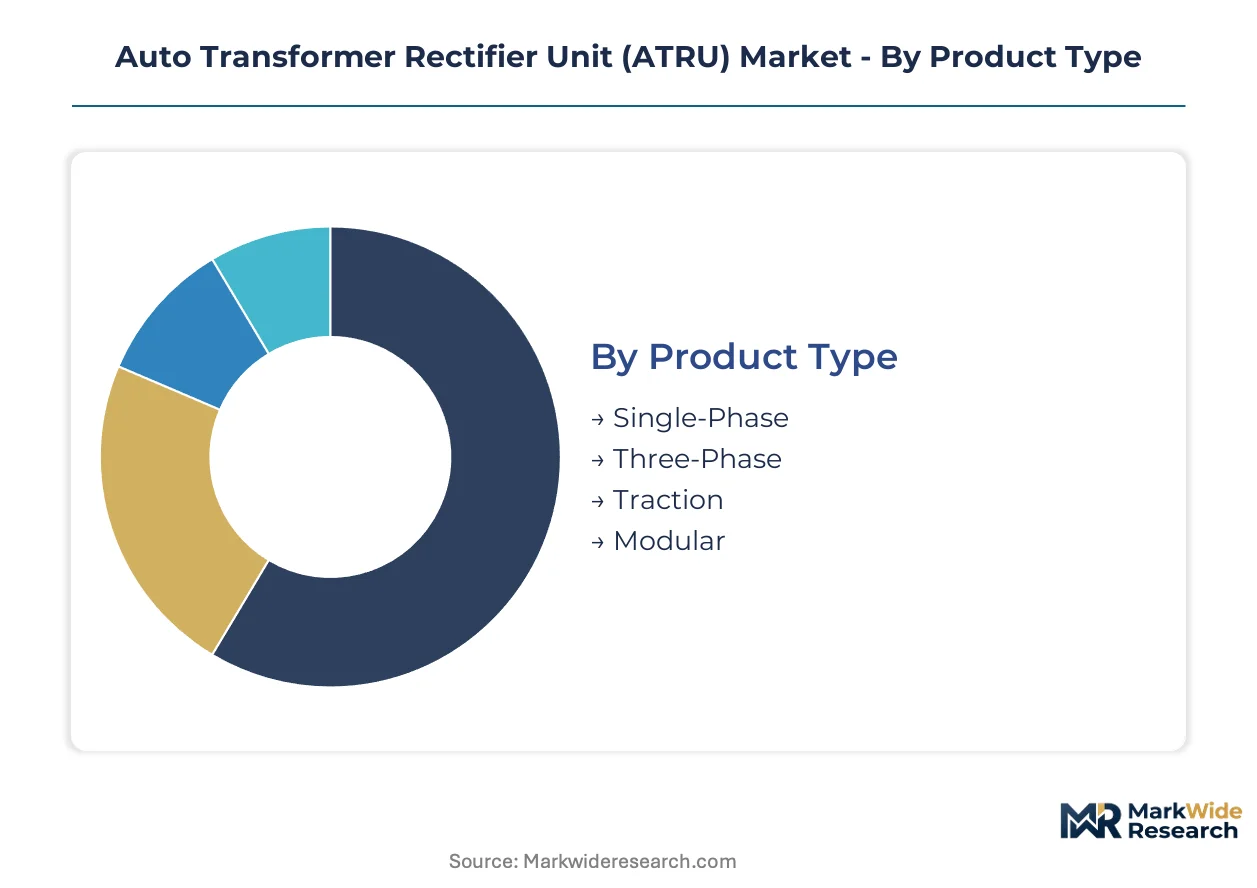
ATRU procurement patterns diverge sharply between heavy-traction railway networks requiring multi-megawatt capacity and distributed industrial installations where footprint constraints dominate specification priorities. Rail operators in India and China concentrate demand in standardized three-phase configurations, while European airports and renewable integration projects drive modular adoption for incremental scaling flexibility.
Product Type:
Standalone traction substations accommodate the highest power ratings through discrete transformer-rectifier pairs, whereas embedded modular architectures enable capacity expansion without full system replacement.
- Three-Phase:Configurations handle power densities exceeding 5 MW per substation through phase-shifted winding arrangements that suppress harmonic distortion in 25 kV/50 Hz railway supplies. India's Dedicated Freight Corridor developers specify these units under CEA-mandated harmonized standards for heavy-haul electrification. Thermal management requirements intensify in tropical corridors where ambient temperatures stress silicon carbide gate oxide reliability.
- Modular:Standardized power blocks reduce engineering customization per project while allowing rail operators to scale capacity incrementally. Chinese high-speed rail corridor expansions specify these configurations for phased commissioning schedules that align capital deployment with traffic ramp-up curves. EU F-Gas Regulation efficiency thresholds accelerate adoption where harmonic distortion limits below 3% necessitate integrated active filter redesigns.
- Single-Phase:Legacy 15 kV/16.7 Hz railway supplies in select European corridors retain demand for these compact configurations.
- Traction:Purpose-built units for locomotive pantograph interfaces dominate procurement volumes in India's CEA-regulated electrification programs.
Three-phase configurations lead volumes today; modular architectures are gaining share fastest.
End User:
Cost-tier stratification separates capital-intensive railway electrification programs from industrial installations where payback periods constrain specification ceilings.
- Railways:Traction power distribution accounts for the dominant procurement volume across Indian freight corridors and Chinese high-speed network expansions. CEA mandates in India and MIIT efficiency directives in China impose divergent testing protocols that fragment certification requirements for multinational suppliers. Silicon carbide substrate shortages compress delivery timelines for new-build substations exceeding 5 MW capacity.
- Renewable Energy:Grid-tie rectification for solar and wind integration demands rapid fault-response capabilities that silicon carbide switching frequencies above 20 kHz enable. European renewable developers specify these configurations under EU Green Deal efficiency benchmarks that mandate harmonic distortion suppression without oversized passive filters.
- Airports:Ground power units for aircraft servicing prioritize compact footprint and rapid deployment cycles.
- Industrial Plants:Process power supplies in steel and cement operations favor proven silicon IGBT reliability over unproven silicon carbide thermal margins.
Railway deployments anchor revenue concentration today; renewable energy integration is expanding most quickly.
Installation:
Volume distribution correlates with climate exposure and grid interconnection density across deployment geographies.
- Outdoor:Enclosure designs withstand monsoon humidity in Indian freight corridors and sand abrasion in Middle Eastern rail projects. IP-rated thermal management systems accommodate silicon carbide MOSFET temperature restrictions that fall below theoretical limits in tropical ambient conditions. German and French rail networks specify these units for decentralized substation architectures that reduce transmission losses.
- Integrated:Combined transformer-rectifier-active filter packages streamline procurement under EU F-Gas Regulation compliance timelines that compress design cycles. Indoor installations in Chinese high-speed rail control centers prioritize electromagnetic compatibility with signaling infrastructure.
- Indoor:Climate-controlled environments extend semiconductor lifespan in temperate European installations.
- Standalone:Discrete component procurement persists in legacy retrofit markets where operators preserve existing transformer assets.
Outdoor installations dominate unit shipments today; integrated configurations are climbing the fastest.
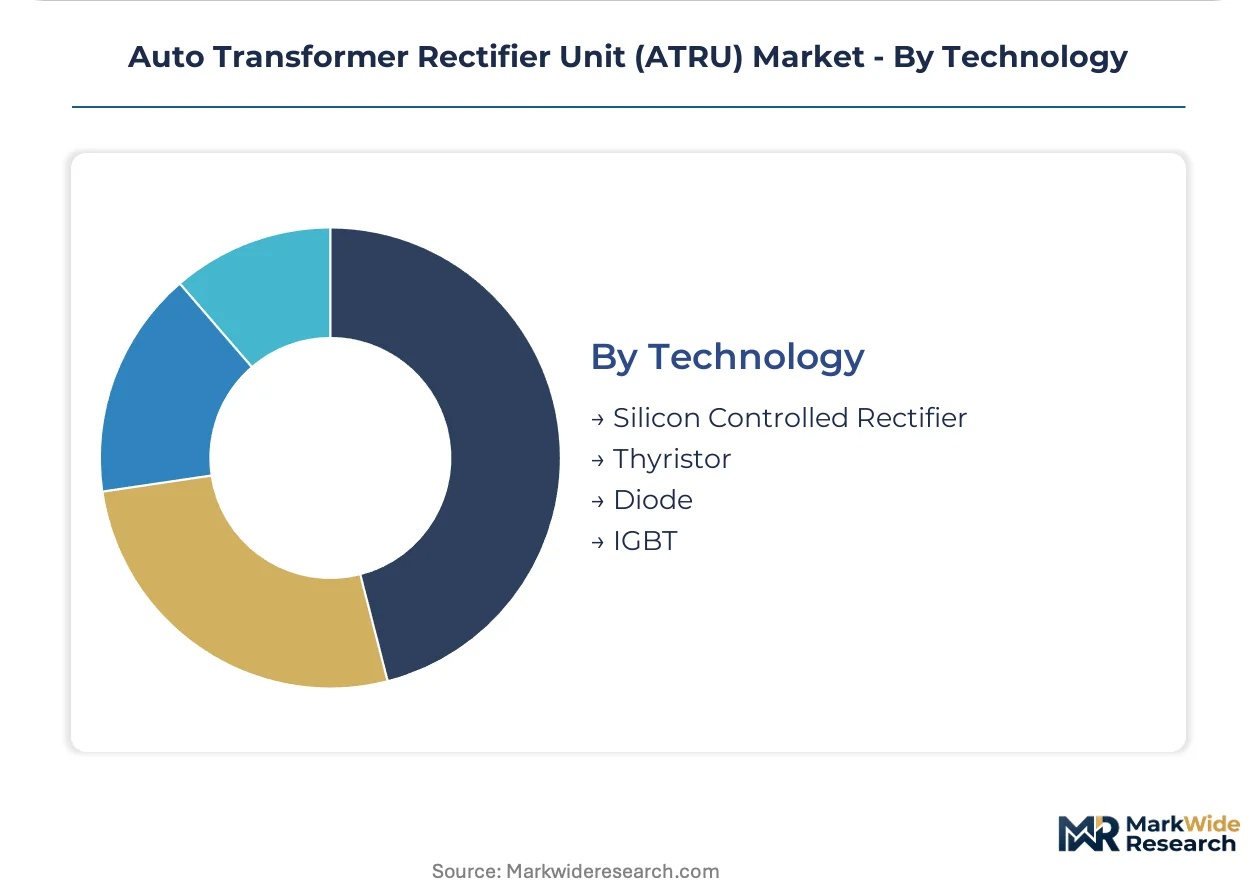
Technology:
Semiconductor substrate availability and switching loss trade-offs determine competitive positioning across efficiency tiers.
- IGBT:Insulated-gate bipolar transistors capture margin pools in new-build projects demanding switching frequencies above 20 kHz that silicon devices cannot achieve. Hitachi Energy and Siemens Energy compete on manufacturing scale for these configurations across European rail electrification programs. Gate driver design talent concentrates in Germany, Japan, and the United States, constraining expansion timelines for second-tier suppliers.
- Silicon Controlled Rectifier:Thyristor-based rectification retains installed base in legacy Indian and Chinese substations where replacement cycles lag technology roadmaps. Maintenance obligations unbundle from initial procurement under evolving European service contract fragmentation, disrupting traditional turnkey supplier relationships.
- Thyristor:Phase-controlled configurations persist in harmonic-tolerant industrial applications.
- Diode:Uncontrolled rectification satisfies lowest-cost specifications in remote auxiliary power supplies.
IGBT platforms lead new-build specifications today; silicon carbide-enhanced variants are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail corridor expansions anchor global ATRU procurement volumes through 2035. India's Dedicated Freight Corridor projects and European efficiency mandates under the EU Green Deal concentrate demand across three distinct regulatory environments.
China
High-speed rail corridor expansions in the Yangtze River Delta and Pearl River Delta drive concentrated ATRU procurement for 25 kV/50 Hz traction substations. MIIT efficiency directives and GB standards accelerate domestic silicon carbide supply chain maturation for power electronics manufacturing. CRRC supply chains in Beijing-Tianjin-Hebei retain integrated procurement models that resist service contract unbundling seen elsewhere.
India
Dedicated Freight Corridor electrification mandates generate three-phase ATRU procurement volumes exceeding 5 MW per substation across western and eastern corridors. CEA harmonized standards enforce power-quality compliance on traction substations under BIS-aligned testing protocols. Manufacturing clusters in Maharashtra and Gujarat benefit from PLI scheme subsidies for domestic silicon carbide module assembly, lowering landed costs for railway tenders.
Germany
Deutsche Bahn's grid modernization programs specify ATRU configurations meeting EU F-Gas Regulation efficiency thresholds below 3% harmonic distortion. German rail networks deploy outdoor substation architectures in Bavaria and North Rhine-Westphalia to reduce transmission losses across decentralized grids. Gate driver design talent concentrates in Baden-Württemberg, constraining expansion timelines for second-tier suppliers seeking silicon carbide expertise.
France
SNCF electrification programs under EU Green Deal timelines compress ATRU design cycles for legacy 15 kV/16.7 Hz and modern 25 kV/50 Hz supplies. French rail procurement specifies integrated transformer-rectifier-active filter packages to meet F-Gas Regulation compliance deadlines. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes host manufacturing scale competitions between European and Asian equipment suppliers.
United States
Amtrak's Northeast Corridor electrification studies evaluate silicon carbide-enabled ATRU architectures for future capacity expansion. FERC interconnection standards and FAA airport ground power requirements create dual specification pathways for traction and aviation applications. Manufacturing presence concentrates in aerospace-defence corridors where Crane Aerospace & Electronics leverages heritage power-electronics capabilities for premium contracts.
Auto Transformer Rectifier Unit (ATRU) Market Competitive Landscape
Global majors compete with regional champions across technology tiers and procurement channels. The vendor base stratifies between integrated grid-platform suppliers, aerospace heritage specialists, and scale-driven electrical equipment manufacturers. Three archetypes dominate: silicon carbide technology leaders, rail-integrated turnkey providers, and modular power-block specialists. Competitive moves concentrate on strategic partnerships for semiconductor supply security and geographic expansion into Southeast Asian greenfield rail programs.
Among diversified industrial conglomerates, Hitachi Energy and Siemens Energy exemplify scale-driven manufacturing archetypes competing across European rail electrification programs. Crane Aerospace & Electronics occupies a position within the aerospace-defence specialist tier, anchoring premium contract segments where heritage power-electronics capabilities differentiate procurement outcomes. These three companies represent distinct competitive vectors—integrated grid platforms, manufacturing scale, and vertical-domain specialization—that structure rivalry across efficiency-tiered specification segments.
| Leading Market Players |
|---|
| Raychem RPG |
| HIRECT |
| Crane Aerospace & Electronics |
| Wärtsilä |
| R Baker (Electrical) |
| Hitachi Energy |
| Excelitas Technologies |
| Torotel |
| Siemens Energy |
| Others |
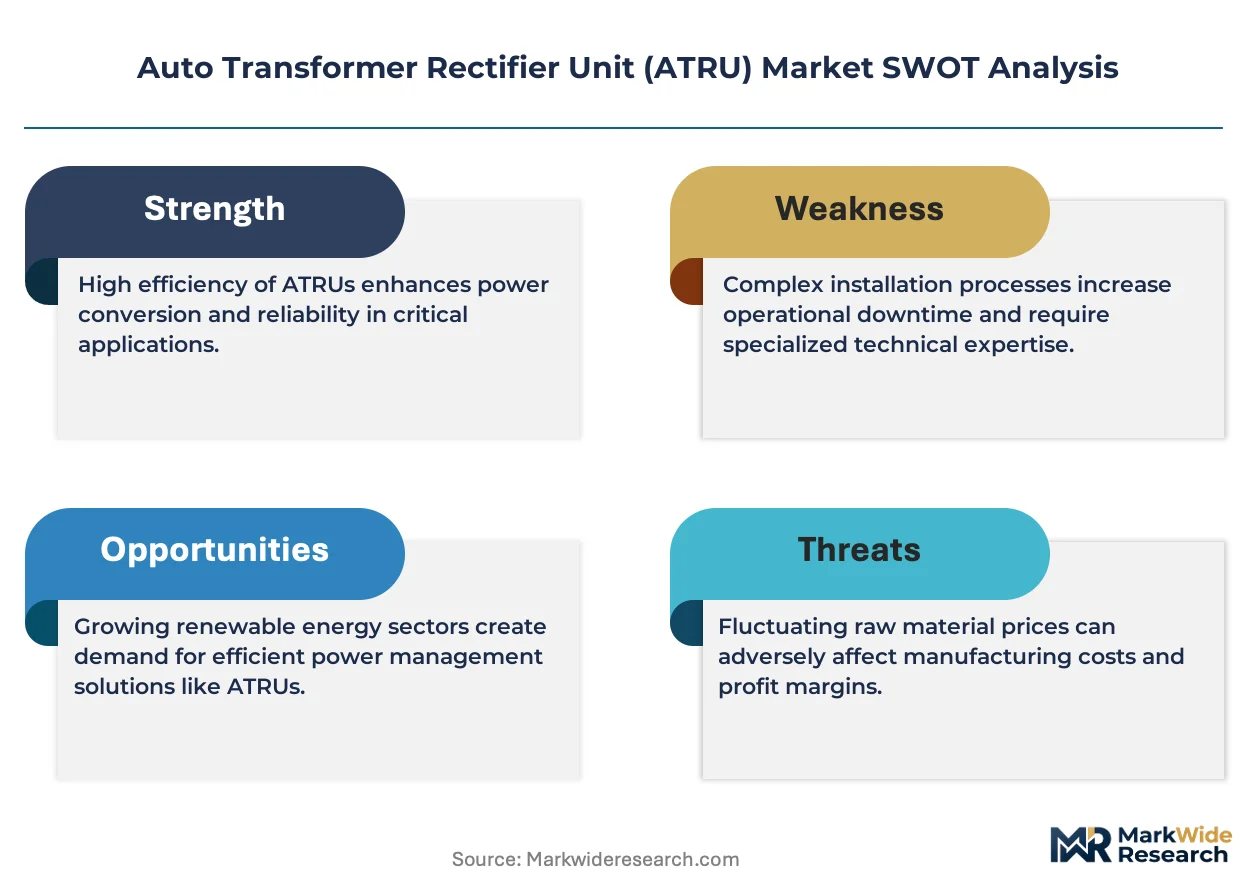
Pricing and Supply Chain Analysis
Specialized power electronics engineering talent clustering in Germany, Japan, and the United States widens labor-cost differentials that stratify ATRU pricing tiers across premium silicon carbide designs and standard silicon IGBT configurations.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer premiums shapes contract pricing for new-build railway substations exceeding 5 MW capacity. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-enabled systems with integrated active filters from conventional IGBT platforms and legacy thyristor retrofits. Cost compression in standard-tier equipment is intensifying because Chinese domestic supply chain maturation under MIIT directives erodes import premiums. Freight corridor developers in India exhibit highest price sensitivity, while European rail operators under EU F-Gas Regulation mandates absorb premium tier pricing for compliance certainty.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and SNCF mandate multi-supplier qualification for silicon carbide MOSFET modules, constraining single-source dependencies despite substrate production clustering in Japan and the United States. Raw material dependencies center on silicon carbide wafers, high-grade copper magnet wire, and nanocrystalline core materials. Single-source vulnerability concentrates in Japanese substrate foundries serving European ATRU manufacturers. Distribution runs through CRRC-anchored integrated procurement channels in China and unbundled service-contract frameworks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ATRU market functions as a regulatory compounder where EU F-Gas Regulation efficiency thresholds below 3% harmonic distortion mandate equipment replacement cycles regardless of underlying traffic growth.
For Market Incumbents: Hedge silicon carbide supply exposure through captive module assembly partnerships in India leveraging PLI scheme subsidies. Prioritize certification pre-positioning under China's divergent GB standards and MIIT testing protocols to compress parallel validation timelines. Defensive consolidation through acquisition of specialized gate driver design houses in Baden-Württemberg addresses engineering scarcity constraining expansion. For New Entrants and Emerging Players: Begin with Southeast Asian greenfield rail programs in Vietnam and Indonesia where network electrification remains below 15% coverage and incumbent relationships are unsettled. Target modular power-block architectures for phased commissioning schedules that align with capital-constrained operators. Go-to-market positioning as silicon carbide-native suppliers without legacy thyristor installed-base obligations unlocks specification advantages in new-build tenders. For Investors and Strategic Acquirers: Electrical equipment conglomerates with rail-integrated turnkey capabilities are the most active acquirer in this space, seeking silicon carbide competency to defend platform positions. Acquisition target archetype: regional champions with MIIT or CEA pre-certification and stranded engineering capacity. Watch silicon carbide substrate spot pricing as inflection indicator for margin compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Substrates | Captive wafer supply secures margin pools against Japanese and US production bottlenecks. |
| CEA Pre-Certification Investment | Early compliance with India's harmonized standards accelerates Dedicated Freight Corridor tender participation. |
| Modular Power-Block Platform Launch | Standardized architectures reduce engineering customization for Chinese high-speed rail phased expansions. |
| Integrated Active Filter Development | Combined transformer-rectifier packages streamline EU F-Gas Regulation compliance procurement. |
| Southeast Asian Joint Venture | Local manufacturing presence addresses Vietnam and Indonesia greenfield electrification requirements. |
Research Methodology
Multiple input streams — regulatory filing analysis, semiconductor trade data, and rail operator procurement documentation — were reconciled against primary interviews with traction power engineers, substation procurement officers at state rail authorities, silicon carbide module manufacturers, and power electronics engineering directors. Secondary validation drew from MIIT efficiency directive publications, CEA harmonized standard circulars, EU F-Gas Regulation implementing acts, and railway electrification project databases. Bottom-up unit deployment estimates and top-down infrastructure investment flows were cross-referenced to anchor volume assumptions.
Historical deployment trajectories in China, India, Germany, and France were cross-referenced against expert panel assessments of silicon carbide adoption curves and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product configuration (three-phase, modular, single-phase), semiconductor technology tier (silicon carbide-enhanced, IGBT, thyristor), installation environment (outdoor, integrated, indoor), and end-use application (railway traction, renewable integration, airport ground power). CAGRs were derived from slope consensus across input methodologies, with specific weighting to railway electrification mileages committed in national infrastructure plans and renewable interconnection queue depths.
Several conditions sit outside the modeled scope, including unannounced regulatory efficiency threshold revisions, breakthroughs in gallium nitride traction power applications, and geopolitical trade restrictions affecting semiconductor substrate flows. Forecasts reflect documented assumptions regarding silicon carbide yield improvements and rail operator capital commitment trajectories. Deviation in Chinese high-speed rail corridor commissioning schedules or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Smart Transformers Market
Transformers
Amorphous Core Transformers Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Power Transformer Market
Transformers
China Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
India Power Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Single Phase Power Transformer Market
Transformers
Transformer Core Market
Transformers
Step Up/Down Transformers Market
Transformers
Current Transformer Market
Transformers
United States Transformer Market