
 Adaptive Cooling Fan Market | 2026-2036
Adaptive Cooling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Cooling Fan Market Analytics
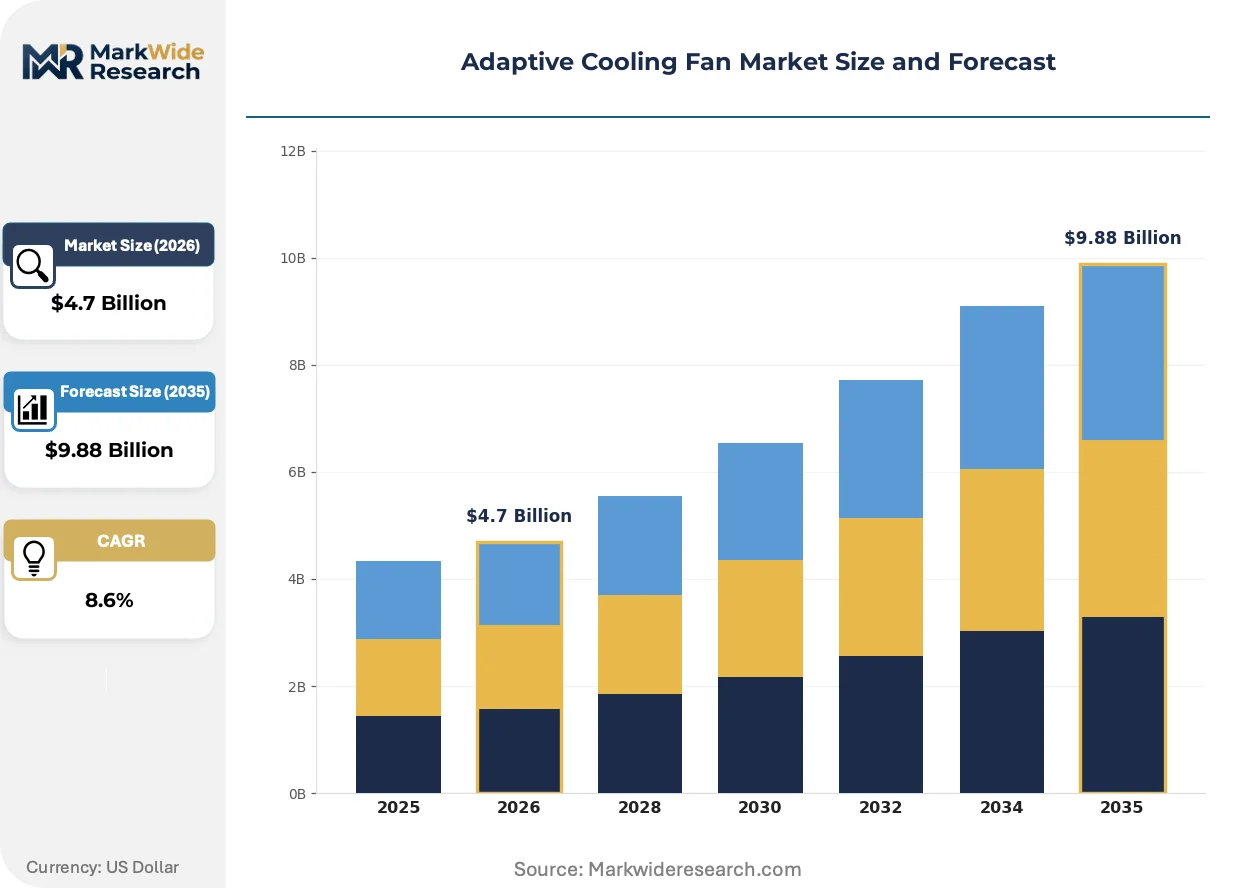
Software-defined speed calibration is hardening as a recurring revenue layer, shifting vendor economics from hardware-only transactions to subscription-enabled thermal management. ebm-papst Mulfingen GmbH & Co. KG leverages its German manufacturing base to dominate precision motor-fan integration. Delta Electronics, Inc. anchors its position through captive semiconductor production for PWM driver modules. Nidec Corporation specializes in compact high-RPM designs that serve server rack density requirements.
An adaptive cooling fan modulates airflow through sensor feedback, PWM signal response, or wireless command inputs to match real-time thermal loads rather than operating at fixed speeds. These devices typically employ brushless DC motors with operating ranges from 1,000 to 25,000 RPM and incorporate thermistors or digital temperature sensors for closed-loop control, serving critical functions in electronics thermal management and industrial process cooling. Centrifugal fans capture the premium margin pool in industrial HVAC and cleanroom applications where static pressure performance commands price premiums. Axial fans sustain volume leadership across data center and consumer electronics cooling, while smart sensor integration represents the fastest-expanding technology dimension as OEMs demand predictive maintenance capabilities.
The EPA Energy Star program and EU Ecodesign Directive jointly enforce minimum efficiency index thresholds that disqualify legacy fixed-speed products from commercial sale. IEC 60335-2-80 governs safety and performance testing for household and similar electrical fans, creating compliance cost barriers for new entrants. Stakeholders must monitor how emerging refrigerant-phase-down regulations under the F-Gas Regulation redirect investment toward air-side cooling alternatives in European commercial buildings.
Market Dynamics
Software-defined speed calibration is hardening as a recurring revenue layer, shifting vendor economics from hardware-only transactions to subscription-enabled thermal management. Data center operators in the United States are expanding procurement of variable-speed cooling systems, while the EU Ecodesign Directive and rising fan efficiency standards reshape product specifications across member states.
Growth Catalysts
- EU Ecodesign Directive:Rising fan efficiency standards across member states are disqualifying legacy fixed-speed products from commercial sale, forcing replacement cycles and premium product adoption.
- Industrial automation clusters in Germany:Premium axial fan orders concentrate in Baden-Württemberg and Bavaria, where automotive and machinery OEMs demand closed-loop thermal control.
- PWM driver modules:Semiconductor integration into motor controllers enables granular speed modulation, reducing energy consumption in data center cooling by matching airflow to real-time server loads.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies create input cost volatility for brushless DC motor production.
- Technical limitation in static pressure performance:Axial fan designs face inherent aerodynamic ceilings above 2,500 Pa, ceding premium industrial HVAC applications to centrifugal alternatives.
- Substitution threat from liquid cooling:Direct-to-chip and immersion cooling systems are capturing rack-density applications above 50 kW per server, compressing air-cooling addressable market at the high-performance edge.
Strategic Opportunities
- Underpenetrated India market:The PLI scheme for electronics manufacturing is attracting data center investments in Tamil Nadu and Telangana, creating first-mover advantage for adaptive cooling vendors establishing local assembly.
- Technology convergence of edge computing and 5G:Micro data centers and telecom enclosures require compact, sensor-integrated fans with wireless command capabilities for remote thermal management.
- Regulatory tailwind from F-Gas Regulation:Refrigerant-phase-down mandates under European climate policy redirect commercial building investment toward air-side cooling alternatives, expanding addressable market for high-efficiency fan systems.
Industry Challenges
- Embedded systems firmware expertise gap:Vendors struggle to hire engineers capable of integrating predictive maintenance algorithms with existing motor control architectures.
- Certification timeline compression:IEC 60335-2-80 safety testing and regional efficiency mark requirements create multi-month approval bottlenecks that delay product launches.
- Legacy BMS integration complexity:Building management systems in commercial HVAC installations use proprietary communication protocols that resist standardized fan controller interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Cooling Fan Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Bladeless Fans, DC Fans Technology: Smart Sensors, Wireless Control, PWM Control, Speed Regulation Application: Industrial, Residential, Automotive, Electronic Devices End User: Manufacturers, Home Users, Tech Companies, OEMs |
| Companies Covered | ebm-papst Mulfingen GmbH & Co. KG, Sanyo Denki Co., Ltd., Delta Electronics, Inc., Orion Fans, Mechatronics Fan Group, Nidec Corporation, AVC (Asia Vital Components Co., Ltd.), S. Tech Corp., Sunonwealth Electric Machine Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Cooling Fan Market Evolving Landscape
Digital temperature sensing and wireless mesh networking are converging to enable predictive thermal management, transforming cooling fans from passive components into active data nodes within broader facility optimization systems.
Edge-embedded thermistor arrays with Bluetooth Low Energy transmission are integrating real-time thermal mapping capabilities directly into fan housings. Data center operators in Singapore and the Netherlands are deploying these sensor-fan units at scale, enabling zone-level airflow optimization that reduces overprovisioning in raised-floor environments. This integration is compressing commissioning timelines and shifting competitive advantage toward vendors with captive IoT firmware development.
The EPA Energy Star program and EU Ecodesign Directive jointly enforce minimum efficiency index thresholds that now capture commercial and industrial fan categories previously exempt from mandatory standards. Manufacturers serving the United States and European Union must redesign motor laminations and blade geometries to meet these indexed performance floors, raising R&D intensity and consolidating supplier tiers around vertically integrated producers. The industrial HVAC segment faces the steepest compliance cost escalation, with multi-stage centrifugal units requiring complete aerodynamic retooling.
Buying organizations are unbundling hardware procurement from lifecycle service contracts, demanding outcome-based thermal performance guarantees rather than equipment specifications. Data center REITs in Northern Virginia and Frankfurt are leading this shift, contracting cooling capacity by the kilowatt-managed rather than by the fan unit installed. This compression of the traditional equipment-plus-service bundle is forcing OEMs to build recurring revenue infrastructure or cede margin to systems integrators capturing the performance-contracting layer.
Adaptive Cooling Fan Market Segmentation
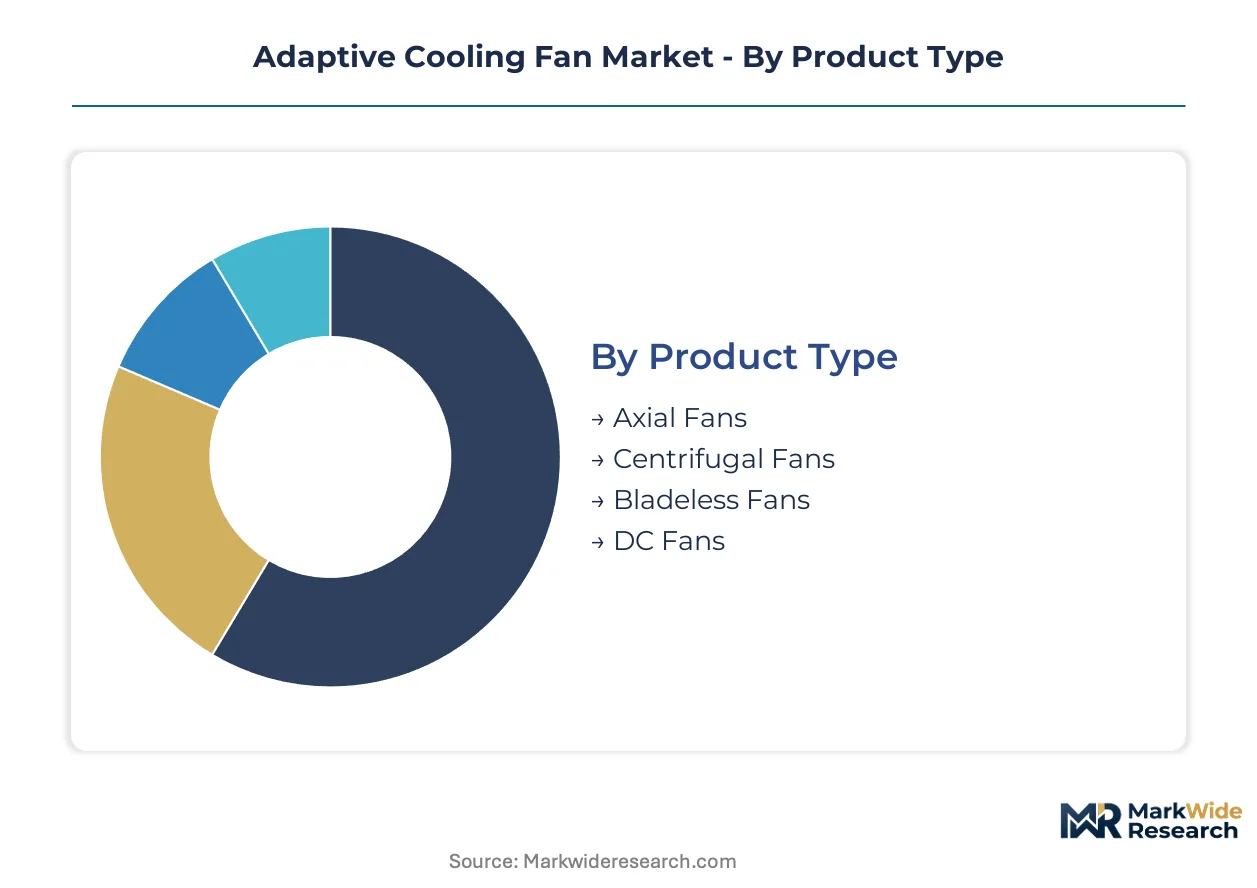
Segmentation in adaptive cooling fans reveals how thermal management requirements diverge across power density, noise tolerance, and control sophistication. Supply-side specialization clusters around motor integration capabilities and sensor firmware development, creating distinct competitive arenas.
Product Type:
Supply concentration in precision motor manufacturing favors producers with captive lamination and magnet assembly capabilities.
- Axial Fans:These units move air parallel to the shaft axis using propeller-style impellers, typically achieving flow rates of 50 to 500 CFM at low static pressure. Data center operators in Northern Virginia and Frankfurt deploy variable-speed axial arrays for server rack cooling, driven by rack density requirements above 30 kW per cabinet. Axial fans absorb the bulk of installed capacity; bladeless configurations are expanding most quickly.
- Centrifugal Fans:Radial impeller designs generate higher static pressure, reaching 2,500 Pa and above for ducted industrial applications. Cleanroom installations in Germany's pharmaceutical clusters specify multi-stage centrifugal units where HEPA filtration creates airflow resistance. Centrifugal fans command premium pricing in industrial HVAC; DC variants are gaining share fastest in mobile electronics.
- Bladeless Fans:Air multiplication technology eliminates exposed rotating components, targeting consumer aesthetics and safety-critical medical environments.
- DC Fans:Brushless motor architectures enable precise PWM speed control from 1,000 to 25,000 RPM, serving battery-powered and efficiency-regulated applications.
Axial fans absorb the bulk of installed capacity; bladeless configurations are expanding most quickly.
Technology:
Cost tier differentiation separates commodity motor controllers from premium predictive maintenance platforms.
- Smart Sensors:Embedded thermistor arrays and MEMS temperature sensors enable closed-loop thermal feedback with ±0.5°C accuracy. Singapore data centers deploy Bluetooth Low Energy sensor-fan units for zone-level airflow optimization, compressing commissioning timelines and reducing overprovisioning. Smart sensors command premium pricing; wireless mesh networking is climbing the fastest.
- Wireless Control:Bluetooth Low Energy and Zigbee protocols enable remote speed adjustment without physical wiring to building management systems. Edge computing enclosures in telecom infrastructure use wireless command inputs for thermal management of 5G base station electronics. Wireless control is expanding most quickly; PWM architectures retain the largest installed base.
- PWM Control:Pulse-width modulation delivers granular speed regulation by varying duty cycle to brushless DC motors.
- Speed Regulation:Analog voltage control and discrete step-switching provide basic airflow modulation for cost-sensitive applications.
PWM control retains the largest installed base; wireless-enabled systems are climbing the fastest.
Application:
Volume concentration in electronics cooling creates scale economies that industrial and automotive segments cannot replicate.
- Industrial:Process cooling and machinery ventilation demand continuous-duty ratings and IP65+ environmental sealing. Automotive OEMs in Baden-Württemberg specify closed-loop thermal control for electric vehicle battery packs and power electronics, where thermal runaway prevention is safety-critical. Industrial applications absorb the bulk of heavy-duty capacity; electronics cooling is expanding most quickly.
- Residential:HVAC retrofits and consumer appliances prioritize acoustic performance below 35 dBA and plug-and-play installation.
- Automotive:Under-hood thermal management requires vibration resistance, temperature extremes from -40°C to 125°C, and electromagnetic compatibility.
- Electronic Devices:Laptop, server, and telecommunications equipment cooling drives miniaturization toward 20mm and 40mm form factors. Data center REITs in Northern Virginia contract cooling capacity by kilowatt-managed rather than by fan unit, forcing OEMs toward outcome-based service models.
Industrial applications absorb the bulk of heavy-duty capacity; electronics cooling is expanding most quickly.
End User:
Customer type determines whether procurement emphasizes unit cost or lifecycle performance contracting.
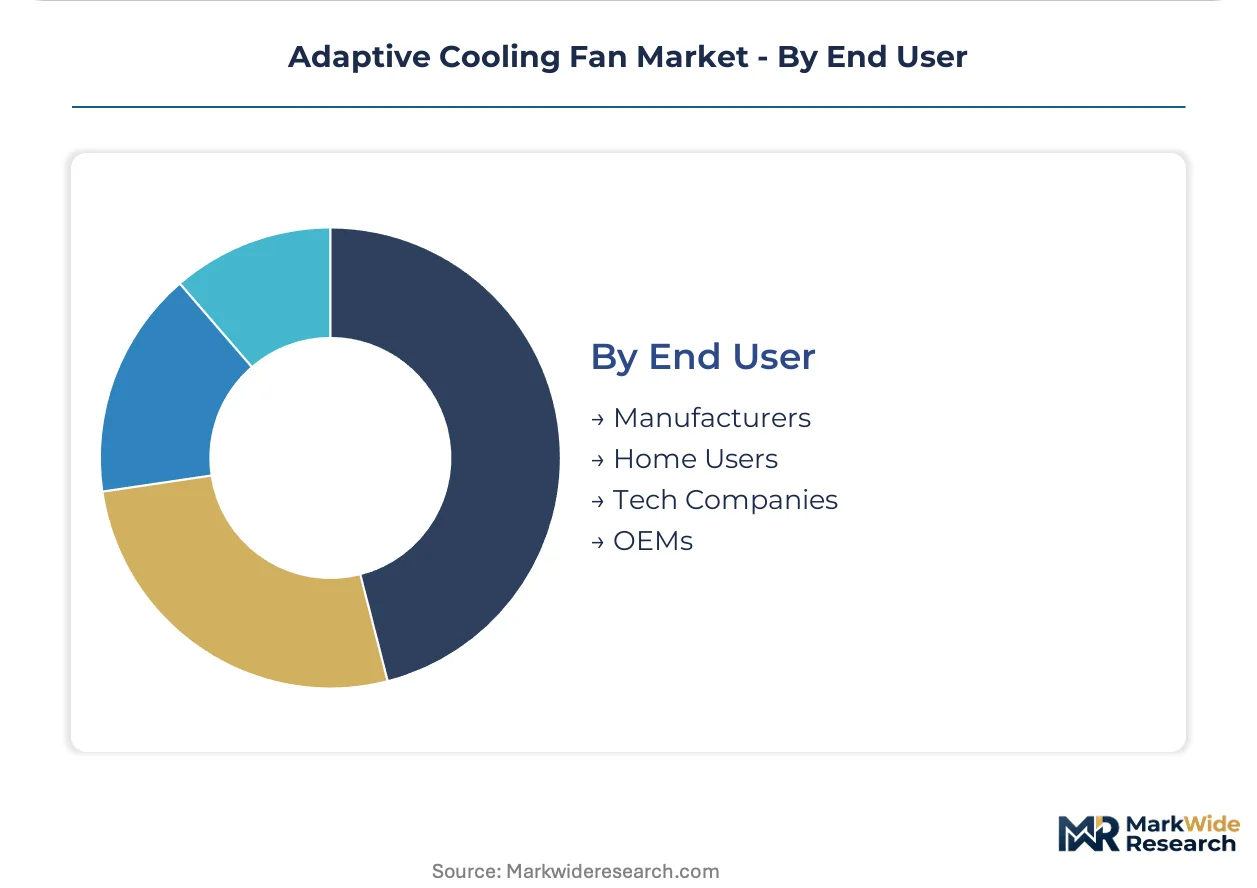
- Manufacturers:Industrial machinery builders integrate fans into capital equipment with 15-20 year service life expectations. German automation clusters in Bavaria source premium axial fans with predictive maintenance capabilities to minimize unplanned downtime in automotive production lines. Manufacturers represent the largest procurement volume; OEMs are gaining share fastest.
- Home Users:Retail channel distribution emphasizes price positioning and aesthetic differentiation for residential HVAC and consumer electronics accessories.
- Tech Companies:Hyperscale data center operators specify adaptive cooling at the rack and row level, unbundling hardware from lifecycle service contracts. Northern Virginia and Frankfurt REITs lead this shift toward outcome-based thermal performance guarantees.
- OEMs:Original equipment manufacturers demand customized form factors and firmware integration for embedded thermal management in servers, telecom equipment, and medical devices.
Manufacturers represent the largest procurement volume; OEMs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian electronics manufacturing clusters while consumption splits between North American data center expansion and European industrial automation retrofits. Supply chains route precision motors from Taiwan and Japan to assembly facilities in China and Mexico before final installation.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth Metroplex drive procurement of variable-speed cooling arrays for rack densities above 30 kW. EPA Energy Star efficiency thresholds now capture commercial fan categories previously exempt from mandatory standards. Phoenix and Atlanta emerge as secondary hubs where REITs contract cooling capacity by kilowatt-managed rather than equipment unit.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify closed-loop thermal control for electric vehicle battery packs and power electronics. EU Ecodesign Directive efficiency standards disqualify legacy fixed-speed products from commercial sale, forcing replacement cycles. Industrial automation clusters in Stuttgart and Munich absorb premium axial fan volumes for machinery ventilation.
China
Domestic server manufacturers and telecom equipment builders source compact high-RPM designs for 5G base station enclosures. GB standards for motor efficiency create compliance benchmarks that parallel IEC frameworks. Yangtze River Delta electronics assemblers in Suzhou and Shanghai integrate adaptive fans into export-bound consumer electronics.
Singapore
Tropical data center operators deploy Bluetooth Low Energy sensor-fan units for zone-level airflow optimization in raised-floor environments. The city-state's carbon neutrality mandates accelerate replacement of fixed-speed infrastructure. Changi and Tuas data center campuses compress commissioning timelines through predictive thermal management.
India
PLI scheme incentives for electronics manufacturing attract data center investments to Tamil Nadu and Telangana. Central Electricity Authority efficiency guidelines shape procurement specifications for industrial cooling. Chennai and Hyderabad industrial corridors create first-mover positioning for adaptive cooling vendors establishing local assembly.
Adaptive Cooling Fan Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the adaptive cooling fan market. Vertically integrated motor manufacturers with captive lamination and magnet assembly capabilities command supply-side leverage, while modular controller specialists capture value from firmware differentiation. Three archetypes dominate: precision motor-fan integrators, semiconductor-captive electronics houses, and compact high-RPM specialists. Consolidation pressure intensifies through strategic partnerships for IoT firmware development and geographic expansion into underpenetrated Asian markets.
Among Japanese motor specialists, Nidec Corporation exemplifies the compact high-RPM archetype serving server rack density requirements. Delta Electronics, Inc. anchors the semiconductor-captive tier through in-house production of PWM driver modules. Sanyo Denki Co., Ltd. represents precision motor-fan integration with closed-loop control capabilities. These three occupy positions that reflect divergent strategic bets on miniaturization, semiconductor integration, and industrial automation respectively.
| Leading Market Players |
|---|
| ebm-papst Mulfingen GmbH & Co. KG |
| Sanyo Denki Co., Ltd. |
| Delta Electronics, Inc. |
| Orion Fans |
| Mechatronics Fan Group |
| Nidec Corporation |
| AVC (Asia Vital Components Co., Ltd.) |
| S. Tech Corp. |
| Sunonwealth Electric Machine Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Data center REITs in Northern Virginia and Frankfurt unbundling hardware procurement from lifecycle service contracts force motor manufacturers to absorb upfront margin compression while building recurring revenue infrastructure. This procurement shift concentrates pricing power with buyers who contract cooling capacity by kilowatt-managed, compelling OEMs to redesign cost structures around outcome-based thermal performance guarantees.
Pricing Analysis
Margin tightening in standard-grade axial fans reflects EU Ecodesign Directive compliance costs and rare earth magnet price volatility. Three-tier pricing structure across premium sensor-integrated, standard PWM-controlled, and economy fixed-speed levels stratifies by certification grade and predictive maintenance capability. Pricing pressure intensifies in the standard tier as Taiwanese electronics assemblers compete on volume scale. OEM procurement teams exhibit highest price sensitivity; data center operators with long-term REIT contracts show least.
Supply Chain Analysis
Neodymium and dysprosium magnet supply rests on Chinese rare earth processors and Japanese specialty metal refiners, creating input cost volatility for brushless DC motor production. Precision motor laminations draw from Taiwan and Japan, while PWM driver semiconductor fabrication concentrates in South Korea and China. Single-source vulnerability in rare earth magnet supply poses structural risk. Distribution runs through Mexico and China-based assembly facilities serving North American and European end-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive creates a cost-of-compliance barrier that consolidates supplier tiers around vertically integrated producers with captive lamination and magnet assembly capabilities.
For Market Incumbents: Anticipate liquid cooling substitution above 50 kW rack densities by deepening firmware differentiation and predictive maintenance algorithm development. Defend margin position through backward integration into rare earth magnet supply and captive semiconductor production for PWM modules. For New Entrants and Emerging Players: Launch via local assembly partnerships in Tamil Nadu and Telangana to capture PLI scheme incentives attracting data center investments. Target underpenetrated India market with compact high-RPM designs for 5G base station enclosures and edge computing micro data centers. For Investors and Strategic Acquirers: The window for entry favors semiconductor-captive electronics houses with in-house PWM driver production and IoT firmware development capabilities. Long-term viability hinges on adaptive cooling vendors' ability to transition hardware-only transactions to subscription-enabled thermal management platforms. Watch hyperscale data center capex announcements as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Sensor-integrated firmware transforms fans from passive components into active data nodes within facility optimization systems. |
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates brushless DC motor production from Chinese export restriction volatility. |
| Local Assembly Establishment in India | PLI scheme incentives in Tamil Nadu create first-mover positioning for adaptive cooling vendors serving Asian data center expansion. |
| Wireless Mesh Networking Integration | Bluetooth Low Energy and Zigbee protocols enable remote thermal management without proprietary BMS protocol dependencies. |
| Outcome-Based Service Contract Structuring | Kilowatt-managed cooling capacity contracts shift vendor economics from equipment sales to recurring thermal performance revenue. |
Research Methodology
Trade databases, IEC efficiency standard filings, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with data center REIT procurement directors, HVAC systems integrators, motor manufacturing plant managers, and electronics OEM thermal engineers. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations derived from server rack density projections and industrial automation investment flows.
Historical trendline analysis of fan efficiency standard adoption curves and variable-speed cooling penetration rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, control technology sophistication, application power density tier, and end-user procurement archetype. CAGRs derived from regression analysis of replacement cycle timing and regulatory mandate phase-in schedules, with specific inputs from EPA Energy Star threshold evolution and EU F-Gas Regulation refrigerant-phase-down timelines.
Rare earth supply disruption, liquid cooling technology substitution acceleration, and IEC 60335-2-80 certification timeline compression are the dominant revision risks. Forecasts reflect assumptions around regulatory enforcement consistency and hyperscale data center buildout continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Solar Fan Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Thawing System Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Process Chillers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Cryogenic Systems Market