
 Portable Power Station Market | 2026-2036
Portable Power Station Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Power Station Market Analysis
Lithium iron phosphate is restructuring cost-performance trade-offs across the portable power station category, displacing conventional lithium-ion cells in mid-range and premium units. EcoFlow leverages proprietary battery management systems to sustain rapid-charge positioning in North American channels. Jackery anchors mass-market volume through compact form factors optimized for recreational vehicle integration. Anker differentiates via consumer electronics heritage and dense retail distribution in Asia-Pacific markets.
A portable power station is a self-contained electrochemical energy storage device with integrated AC inverters, DC outputs, and solar charge controllers, typically rated between 500W and 2000W continuous output for off-grid or backup electricity delivery. The 1000W to 1500W power output bracket now captures the largest margin pool as consumers trade up from entry-level capacity for whole-appliance runtime during outages. Lithium-ion battery type configurations still dominate unit economics, though lithium iron phosphate variants are gaining fastest in segments prioritizing cycle life and thermal stability. Home use and emergency backup applications together generate the majority of replacement-driven revenue as grid reliability concerns persist across storm-exposed regions.
FCC certification requirements govern electromagnetic emissions for all units sold in the United States, while EPA standards on particulate matter from fossil-fuel alternatives indirectly expand addressable demand for battery-based substitutes. The EU Battery Directive and CE marking obligations shape material sourcing disclosures and recyclability mandates for European market access. Stakeholders must monitor evolving inverter efficiency standards and state-level energy storage incentives that will determine which product configurations achieve favorable total-cost positioning against conventional generators.
Market Dynamics
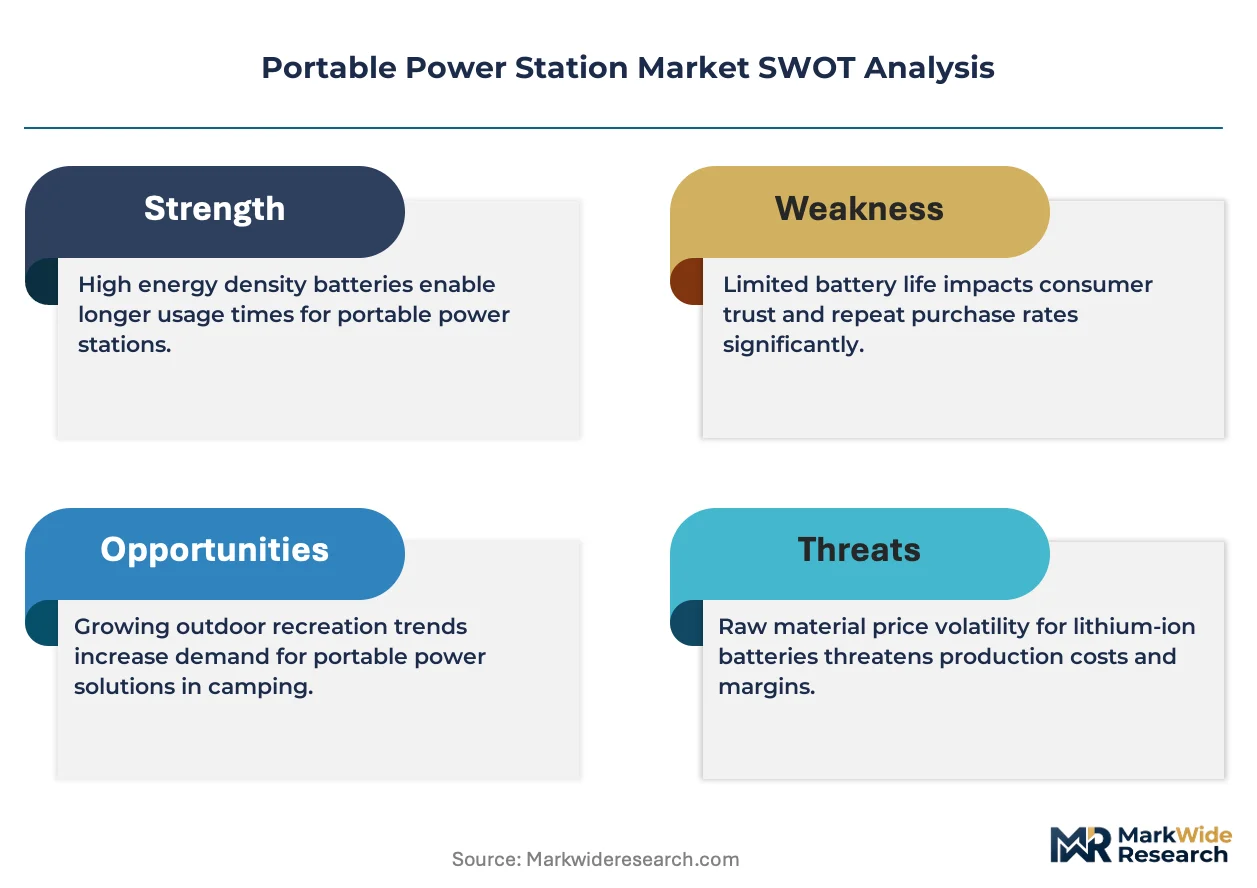
Lithium iron phosphate cell chemistry is restructuring cost-performance trade-offs across the portable power station category, compressing cycle-life premiums and forcing incumbent lithium-ion configurations into narrower price brackets.
Growth Catalysts
- EPA Emissions Constraints:Stricter EPA particulate matter rules on diesel generator runtime at remote worksites are redirecting construction crews toward battery-based alternatives.
- Storm-Exposed Grid Fragility:Hurricane-prone Gulf Coast states are concentrating emergency backup purchases as grid reliability concerns persist across residential end-users.
- Solar Charge Controller Integration:MPPT controller embeddedness is expanding addressable use cases for off-grid recreational vehicle owners seeking seamless panel-to-battery workflows.
Market Restraints
- Lithium Carbonate Volatility:Raw material input costs for cathode active materials create margin compression risks for mid-tier manufacturers without captive supply arrangements.
- Cell Supply Geographic Concentration:Cylindrical and prismatic cell production clusters in East Asia expose brands to logistics chokepoint vulnerabilities and tariff exposure.
- Energy Density Ceiling:Lithium iron phosphate gravimetric limitations constrain watt-hour-per-kilogram ratios for aviation and ultralight backpacking segments.
Strategic Opportunities
- Remote Construction Electrification:Australian mining and infrastructure projects are creating pull-through demand for ruggedized high-capacity units with IP65 ingress protection.
- State-Level Storage Incentives:California SGIP and similar programs are subsidizing residential battery purchases that compete with portable alternatives for home backup share.
- Bi-Directional Vehicle Integration:V2L capability convergence with electric pickup trucks is opening campsite and job-site power access without dedicated station ownership.
Industry Challenges
- FCC Certification Timelines:Electromagnetic emissions testing for inverter switching frequencies creates 8-14 week launch delays for new SKU introductions.
- Thermal Management Talent Scarcity:Battery pack engineering expertise for passive and active cooling architectures concentrates among a narrow pool of mobility-sector veterans.
- EU Battery Directive Compliance:Material sourcing disclosure and end-of-life recyclability mandates are forcing supply chain re-documentation for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Power Station Market |
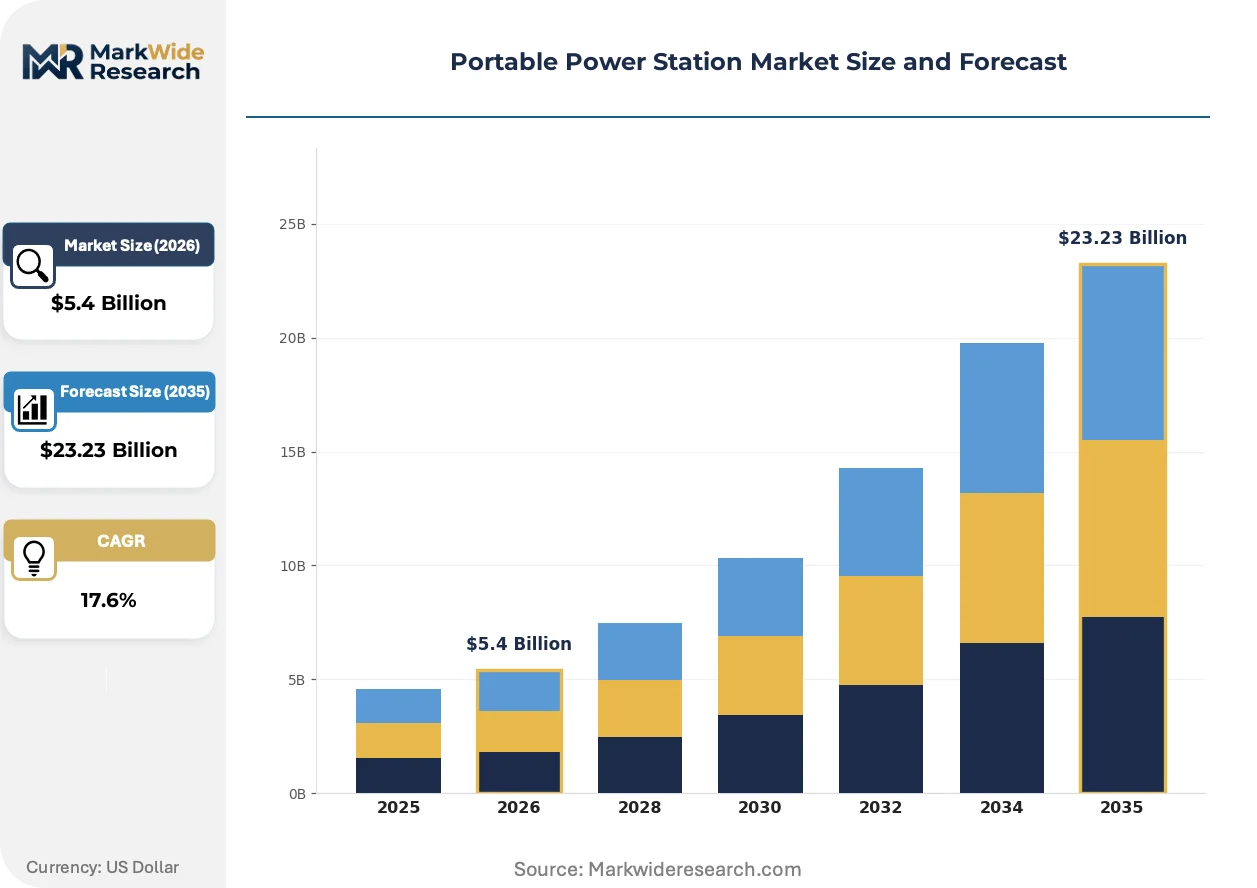
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $23.23 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Output: 500W, 1000W, 1500W, 2000W Battery Type: Lithium-ion, Lead-acid, Lithium-polymer, NiMH Application: Camping, Emergency Backup, Outdoor Events, Home Use Portability Features: Weight, Form Factor, Handle Type, Wheel Mechanism |
| Companies Covered | Bluetti, DJI, EcoFlow, Dakota Lithium, Oupes, Jackery, Goal Zero, Lion Energy, Anker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Power Station Market Emerging Trajectories
Product architecture is fragmenting into stackable and expandable configurations. This shift enables runtime customization without forcing upfront capacity commitments from buyers.
Stackable battery expansion systems are modularizing how residential and commercial users scale storage capacity. RV owners and home backup purchasers are adopting add-on satellite packs at accelerating rates. This architecture is modularizing the traditional single-unit purchase model into recurring accessory revenue streams.
REACH substance restrictions and RoHS recast directives are tightening cadmium and lead thresholds in battery assemblies and inverter components. European market entry now requires supply chain documentation that many Asia-Pacific contract manufacturers cannot yet provide. Premium brands with pre-certified component libraries are capturing shelf space faster than compliance-lagged competitors.
Direct-to-consumer channel preference is displacing traditional outdoor retail distribution for sub-1000W units. Younger recreational buyers research via video platforms and purchase through manufacturer-operated storefronts rather than REI or Bass Pro Shops. This behavior concentrates most visibly in United States coastal metropolitan markets where same-day delivery logistics are densest.
Portable Power Station Market Segmentation
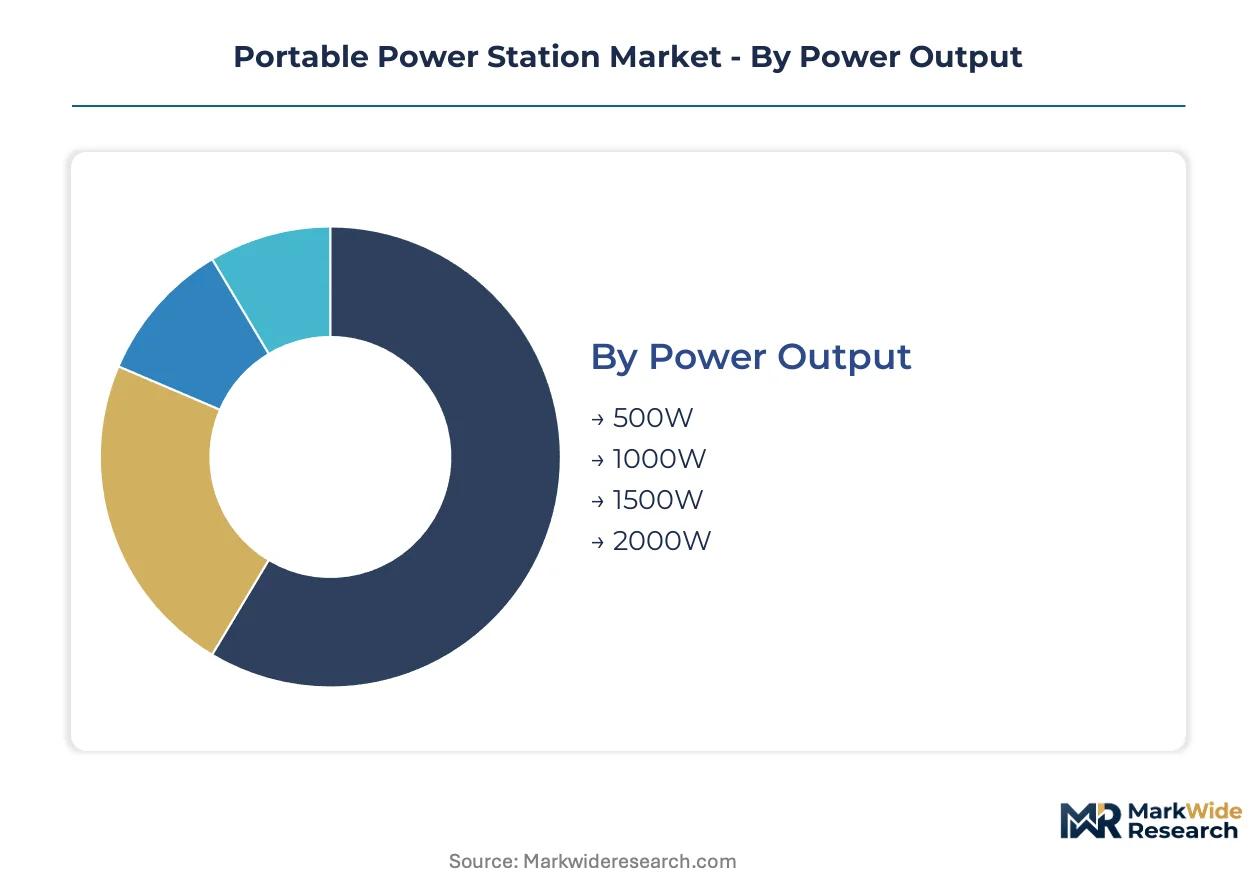
Portable power station purchasing decisions split sharply between recreational buyers optimizing for transportability and residential users prioritizing runtime duration. Manufacturers must align R&D investment with these divergent performance hierarchies rather than pursuing one-size-fits-all specifications.
Power Output:
The volume versus premium divide separates entry-level weekend campers from whole-home backup purchasers seeking appliance-grade continuous delivery.
- 1000W:Mid-range continuous output rating supporting simultaneous small-appliance operation. Demand concentrates in United States Gulf Coast states where hurricane-driven blackout preparedness drives replacement of gasoline generators with silent alternatives.
- 1500W:Threshold capacity enabling refrigerator and medical device runtime during extended grid failures. Australian remote construction crews under EPA emissions constraints favor this bracket for diesel substitution at off-grid worksites.
- 500W:Compact rating for personal electronics and LED lighting loads. Backpackers and festival attendees in California coastal metros purchase through direct-to-consumer channels bypassing traditional outdoor retail.
- 2000W:Professional-grade continuous output with surge tolerance for power tool startup loads. Mining contractors and film production units in Western Australia specify IP65-ingress-protected variants.
Today's leader: 1000W. Tomorrow's challenger: 1500W.
Battery Type:
Cost tier stratification separates commodity lead-acid replacements from advanced lithium chemistries commanding cycle-life premiums.
- Lithium iron phosphate:Cathode chemistry delivering thermal stability and 3000+ cycle durability. Premium residential backup installations in storm-exposed Florida and Texas markets favor this variant despite gravimetric density penalties.
- Lithium-ion:Conventional NMC cathode configuration dominating unit economics through established cylindrical cell supply chains. Mass-market recreational vehicle integration relies on this chemistry for cost-accessible entry points.
- Lead-acid:Mature flooded and AGM architectures retained in price-sensitive emerging markets. Weight and maintenance requirements exclude this chemistry from aviation and ultralight portability segments.
- Lithium-polymer:Pouch cell format enabling thin-form-factor industrial designs. Medical device backup and drone ground station applications specify this chemistry for packaging flexibility.
- NiMH:Nickel-metal hydride cells surviving in legacy tool battery compatibility niches. Environmental regulations under EU Battery Directive accelerate displacement by lithium alternatives.
Current cost leader: Lithium-ion. Cycle-life champion gaining share: Lithium iron phosphate.
Application:
Customer type segmentation distinguishes recreational discretionary spending from resilience-motivated residential investment.
- Emergency Backup:Grid-failure preparedness driving replacement purchases across hurricane corridors. United States Gulf Coast state households trade up from entry-level capacity following repeated multi-day outages.
- Home Use:Daily off-grid or supplementary power for remote properties and solar self-consumption. California SGIP-subsidized residential battery competition constrains portable alternative positioning here.
- Camping:Recreational vehicle and tent-based outdoor power for lighting, cooling, and device charging. Younger buyers research via video platforms and purchase through manufacturer direct channels.
- Outdoor Events:Vendor power for festivals, markets, and mobile food service. Noise ordinances in urban Australian and United States municipalities accelerate diesel displacement.
Revenue concentration sits with: Emergency Backup. Fastest-climbing trajectory: Home Use.
Portability Features:
Physical design attributes determine channel placement and margin structure across recreational versus professional use cases.
- Weight:Gravimetric specification governing backpack versus vehicle-borne transport decisions. Sub-10kg thresholds dominate direct-to-consumer sub-1000W unit sales.
- Form Factor:Envelope dimensions determining storage compatibility with RV compartments and residential closets. Stackable modular architectures enable runtime customization without upfront capacity commitment.
- Handle Type:Ergonomic carry solutions for short-distance portage. Integrated versus fold-away designs signal recreational versus professional positioning.
- Wheel Mechanism:Rolling transport for 20kg+ high-capacity units. Australian mining and infrastructure projects specify all-terrain caster systems for ruggedized field deployment.
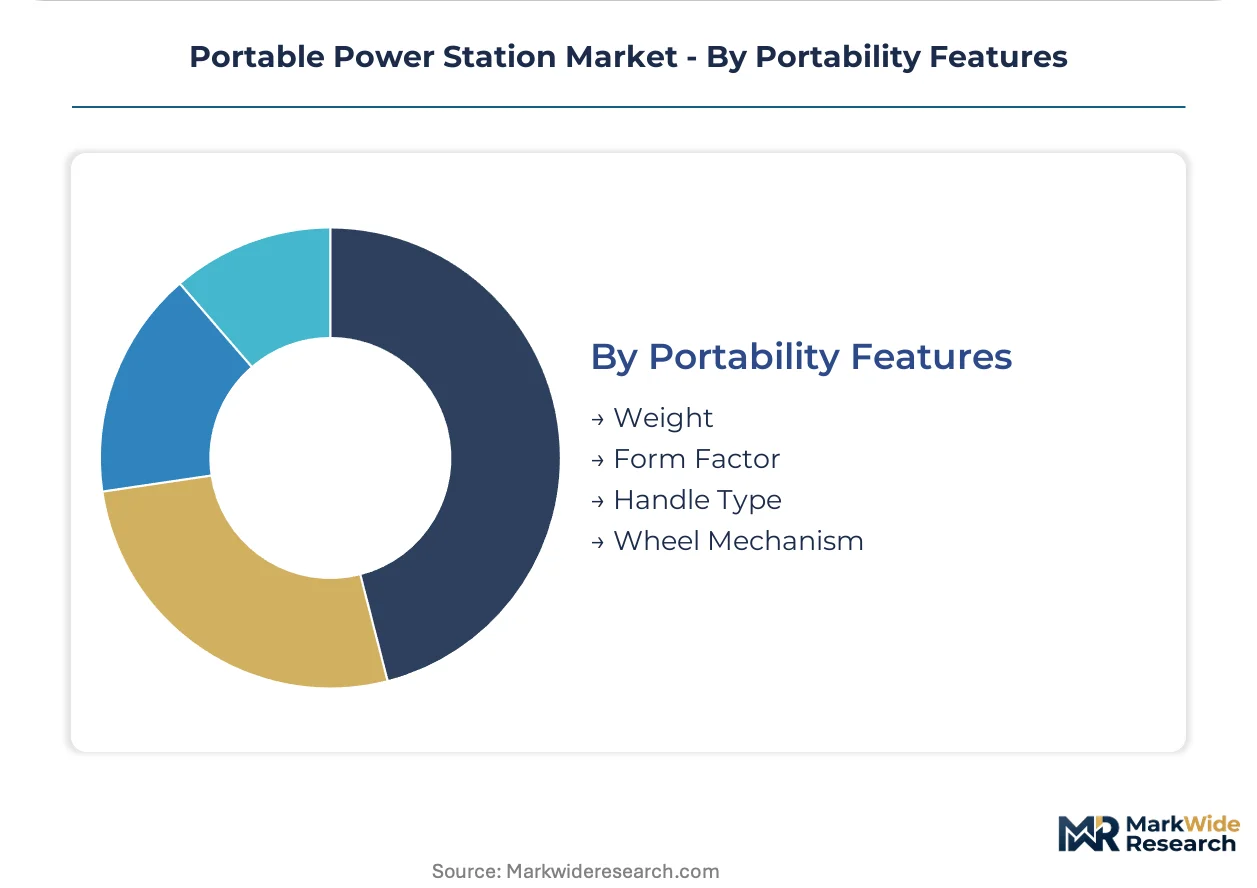
Current standard-setter: Weight. Emerging differentiator: Form Factor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor supplies the majority of lithium iron phosphate cells and integrated inverter assemblies serving portable power station brands worldwide, with component flows reaching assembly plants across three continents.
United States
Hurricane-driven blackout preparedness concentrates demand in Gulf Coast states, where EPA emissions constraints on diesel generators accelerate battery substitution at remote construction sites. FCC certification timelines for electromagnetic emissions testing create 8-14 week launch delays for new product introductions. Austin and Dallas-Fort Worth host expanding assembly operations for brands targeting residential backup segments.
Germany
REACH substance restrictions and RoHS recast directives tighten cadmium and lead thresholds in battery assemblies, forcing supply chain re-documentation for market access. The EU Battery Directive mandates material sourcing disclosures and end-of-life recyclability protocols. Bavaria's industrial automation sector supplies precision manufacturing equipment for European-bound production lines.
Australia
Remote mining and infrastructure projects in Western Australia generate pull-through demand for ruggedized high-capacity units with IP65 ingress protection. Stricter EPA emissions rules limit diesel generator runtime at worksites, redirecting crews toward battery alternatives. Perth serves as the distribution hub for Pacific region deployment.
China
Dual carbon goals under MIIT policy frameworks accelerate displacement of lead-acid architectures by lithium iron phosphate alternatives in domestic and export production. Cylindrical and prismatic cell production clusters in the Yangtze River Delta and Pearl River Delta expose brands to logistics chokepoint vulnerabilities. Shenzhen anchors BMS firmware development and rapid-charge controller engineering.
Japan
METI efficiency standards for inverter architectures shape product development priorities for premium residential backup units. JIS certification requirements govern electrical safety for units sold in domestic channels. Osaka-Kobe industrial corridor hosts specialized thermal management component suppliers serving high-cycle-life battery pack assemblers.
Portable Power Station Market Vendor Landscape
Global majors compete with regional champions across certification speed and channel access dimensions, producing a tiered structure where premium brands with pre-certified component libraries capture shelf space faster than compliance-lagged competitors. The vendor base splits between integrated system designers, contract manufacturing specialists, and component technology licensors. Three archetypes dominate: vertically integrated electronics conglomerates with captive battery supply, pure-play power station brands scaling through direct-to-consumer channels, and industrial equipment crossover players leveraging ruggedization expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrated in battery management system IP and thermal engineering talent acquisition.
Within the premium-tier vector, EcoFlow and Jackery exemplify divergent positioning strategies, with the former representing rapid-charge technology anchoring and the latter compact form-factor mass-market penetration. Anker occupies a position bridging consumer electronics heritage with dense retail distribution capabilities. Bluetti and Goal Zero sit within the ruggedized high-capacity specialist tier, targeting remote worksite and expeditionary use cases where IP ratings and cycle durability command price premiums. DJI represents the industrial equipment crossover archetype, leveraging drone battery expertise toward portable power applications. Dakota Lithium, Oupes, and Lion Energy anchor the lithium iron phosphate specialization segment, where thermal stability and extended cycle life drive residential backup purchasing decisions.
| Leading Market Players |
|---|
| Bluetti |
| DJI |
| EcoFlow |
| Dakota Lithium |
| Oupes |
| Jackery |
| Goal Zero |
| Lion Energy |
| Anker |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot volatility cascades through cathode active material costs into finished product pricing, with cylindrical cell supply from the Yangtze River Delta feeding premium-tier residential backup units while prismatic alternatives anchor mass-market recreational vehicle configurations.
Pricing Analysis
Input-cost pass-through from lithium iron phosphate cathode materials compresses margins for mid-tier manufacturers lacking captive supply arrangements. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified home backup systems from FCC-compliant recreational units and entry-level personal electronics chargers. Pricing pressure stems from lithium carbonate volatility and tariff exposure on East Asian cell imports. Mass-market recreational buyers in California coastal metros exhibit highest price sensitivity, while storm-exposed Gulf Coast residential purchasers prioritize cycle-life specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Rotterdam, and Singapore manage hub-and-spoke fulfillment patterns for finished units, with Shenzhen's BMS firmware clusters and Osaka-Kobe thermal management component suppliers feeding assembly operations in Texas and Bavaria. Raw material dependencies center on lithium carbonate from South American salares, copper foil from Chinese smelters, and semiconductor-grade silicon for inverter controllers. Single-source vulnerability concentrates in cylindrical cell production clusters along the Pearl River Delta. Distribution runs through direct-to-consumer storefronts for sub-1000W units and specialized industrial distributors for IP65-rated mining specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where EPA emissions constraints in the United States and Australia accelerate diesel displacement faster than European markets constrained by REACH documentation burdens, creating margin expansion opportunities for pre-certified brands.
For Market Incumbents: To counter bi-directional vehicle integration threatening dedicated station ownership, incumbents should deepen backward integration into lithium iron phosphate cell supply and accelerate FCC certification pipelines to compress 8-14 week launch delays. Control over thermal management engineering talent pools represents the critical defensive lever against industrial equipment crossover entrants.
For New Entrants and Emerging Players: Launch via direct-to-consumer video platform marketing targeting younger recreational buyers in United States coastal metropolitan markets, bypassing REI and Bass Pro Shops channel saturation. White-space concentration sits with stackable modular architectures for RV owners seeking runtime customization without upfront capacity commitment, plus ruggedized IP65 units for Australian mining contractors under EPA emissions constraints.
For Investors and Strategic Acquirers: Consolidation pressure builds where battery management system IP scarcity concentrates among mobility-sector veterans with passive and active cooling architecture expertise. Long-term viability favors vertically integrated positions with captive lithium iron phosphate supply and pre-certified component libraries for EU Battery Directive compliance. Watch California SGIP subsidy expansion as the inflection signal for residential battery versus portable alternative competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Supply | Captive cathode material sourcing insulates margins from lithium carbonate volatility in Yangtze River Delta markets. |
| FCC Certification Pipeline Investment | Compressed electromagnetic emissions testing timelines accelerate SKU introduction velocity in United States channels. |
| Direct-to-Consumer Channel Expansion | Manufacturer-operated storefronts capture younger recreational buyers researching via video platforms in coastal metros. |
| Stackable Modular Architecture Development | Add-on satellite packs transform single-unit purchases into recurring accessory revenue streams for RV owners. |
| IP65 Ruggedization Program | Ingress protection ratings command price premiums from Australian mining contractors under EPA emissions constraints. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with portable power station product managers, lithium cell procurement leads at downstream assemblers, FCC certification consultants, and RV dealership operations heads with secondary validation against EIA grid reliability data, EPA emissions enforcement records, United States customs import manifests, and EU Battery Directive implementation guidance. Bottom-up unit shipment modeling and top-down addressable market sizing triangulated volume estimates across the analysis window.
Comparable historical reference periods anchored the projection framework, with segmentation modeling across power output tiers, battery chemistry configurations, application use cases, and regional regulatory clusters. CAGRs derived from logistic diffusion curves fitted to substitution patterns against diesel generators and residential stationary batteries. Forecast inputs incorporated lithium carbonate price trajectory assumptions and state-level energy storage incentive program evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption scenarios or abrupt EPA emissions rule relaxation. Outputs reflect documented assumptions about cell cost curves and certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Romania Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
United States Power Rental Market
Power Equipment
Europe Power Rental Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Global Power System Simulator Market
Power Equipment
China Power EPC Market
Power Equipment
Air Preheater Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Global Power Supply Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Power Conditioning Services Market