
 Industrial Embedded Systems Market | 2026-2036
Industrial Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Embedded Systems Market Outlook
Aftermarket service revenue is fragmenting across hardware maintenance, firmware update subscriptions, and remote diagnostics platforms. Intel Corporation leverages its foundry partnerships to sustain manufacturing scale in high-performance computing modules. Renesas Electronics Corporation anchors its position through deep specialization in automotive-grade microcontrollers. STMicroelectronics competes by extending its portfolio into edge-AI accelerators for factory floors.
Industrial embedded systems integrate processors, memory, and I/O interfaces into purpose-built computing platforms operating across temperature extremes from minus 40 to 85 degrees Celsius, designed for deterministic real-time control in mission-critical environments. Microcontrollers and FPGAs capture the dominant margin pools where long product lifecycles and qualification rigor protect incumbent positions. IoT-enabled embedded software represents the fastest-expanding segment as factories deploy wireless sensor networks for predictive maintenance and energy optimization.
IEC 61508 functional safety standards and ISO 26262 automotive adaptations shape hardware design rules, certification timelines, and supplier qualification barriers across European and North American supply chains. The EPA's energy efficiency directives and China's GB standards for industrial equipment further constrain component selection and thermal design choices. Stakeholders must monitor how real-time operating system vendors and silicon foundries coordinate security patch lifecycles as connected factory deployments expand attack surfaces.
Market Dynamics
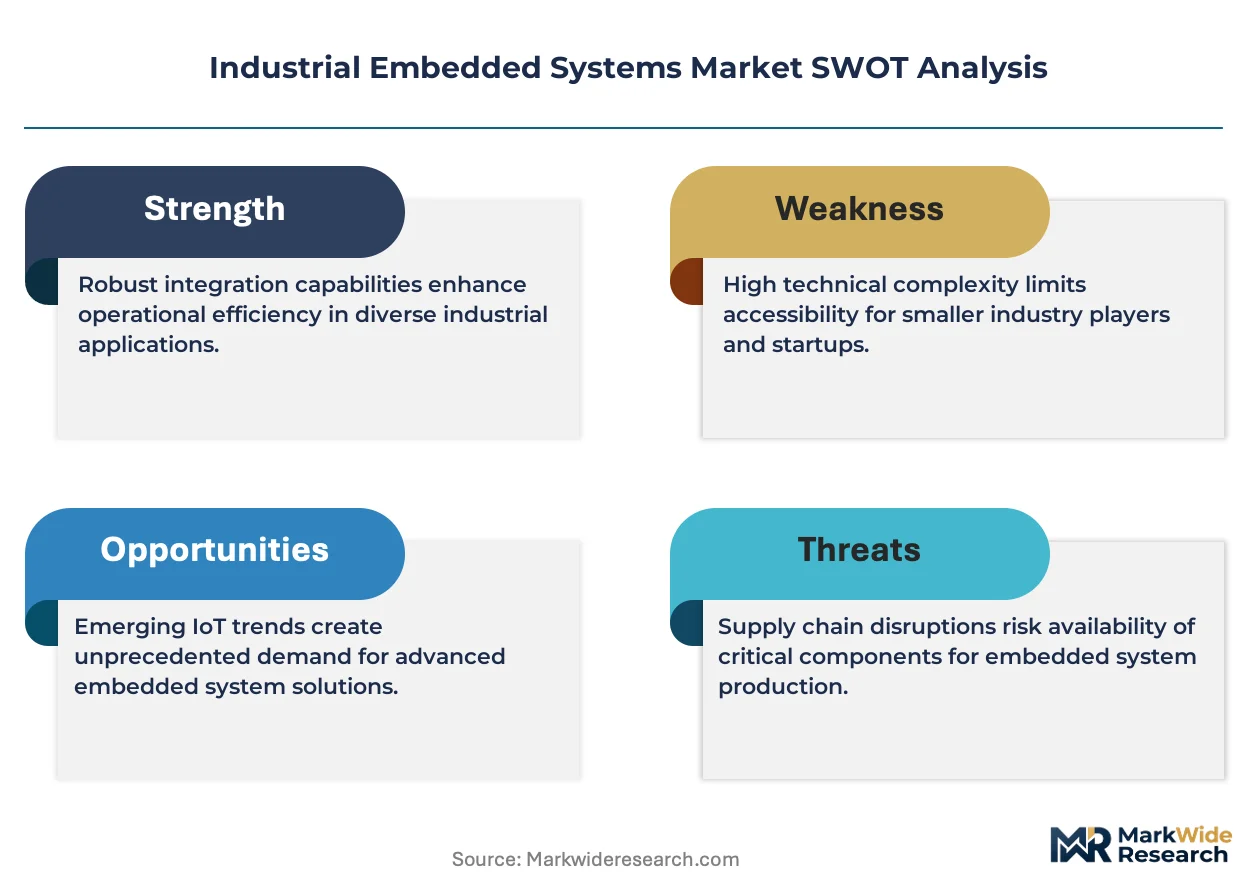
Functional safety mandates under IEC 61508 are compressing hardware certification timelines while concentrating procurement among pre-qualified suppliers. Semiconductor foundry capacity allocation for automotive-grade silicon is tightening supply availability for industrial automation OEMs.
Growth Catalysts
- IEC 61508 certification requirements:European machinery directives mandate SIL-rated components for process control systems, expanding addressable market for pre-certified microcontroller suppliers.
- Robotics OEM semiconductor demand:Collaborative robot deployments in automotive assembly lines require deterministic real-time processors capable of sub-millisecond response cycles.
- Edge-AI accelerator integration:Factory floor vision inspection systems are embedding neural network inference engines directly into PLC modules, creating new silicon content per unit.
Market Restraints
- Automotive-grade foundry allocation:Taiwan-based semiconductor fabrication capacity prioritizes automotive MCU contracts, extending lead times for industrial embedded processors.
- ISO 26262 adaptation costs:Hardware vendors face dual-track certification burden when serving both automotive and industrial verticals simultaneously.
- Legacy fieldbus protocol persistence:PROFIBUS and Modbus RTU installations in brownfield manufacturing sites slow Ethernet-APL and TSN adoption cycles.
Strategic Opportunities
- India PLI scheme for industrial automation:Production-linked incentives for electronic components manufacturing attract embedded system assembly investments in Gujarat and Tamil Nadu corridors.
- Wireless sensor network convergence:Bluetooth Low Energy mesh combined with energy harvesting eliminates cabling in rotating equipment monitoring applications.
- EPA energy efficiency directives:Industrial equipment power consumption thresholds drive demand for ultra-low-power microcontroller architectures in motor control systems.
Industry Challenges
- Functional safety engineer scarcity:SIL verification and FMEDA analysis expertise concentrates among semiconductor vendors with decade-long certification track records.
- Security patch lifecycle coordination:Real-time operating system vendors and silicon foundries must synchronize vulnerability disclosure timelines across multi-year deployed device fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Embedded Systems Market |
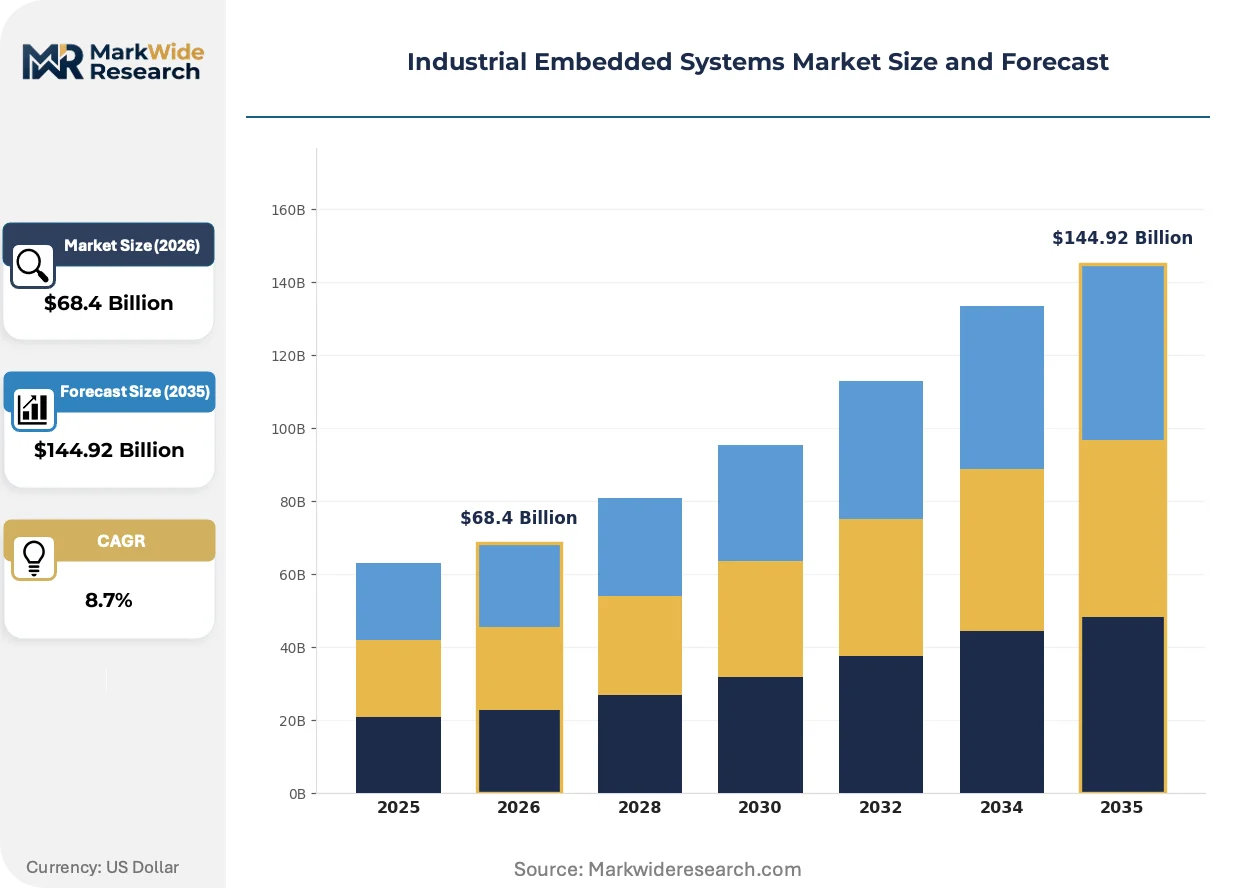
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, DSPs, FPGAs, Single-Board Computers End User: Manufacturing, Automotive, Aerospace, Robotics Technology: IoT, Real-Time Systems, Wireless, Embedded Software Application: Process Control, Machine Automation, Smart Grids, Predictive Maintenance |
| Companies Covered | Intel Corporation, Renesas Electronics Corporation, STMicroelectronics, NXP Semiconductors, Infineon Technologies, Texas Instruments, Analog Devices, Microchip Technology, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Embedded Systems Market Strategic Shifts
Industrial embedded architectures are converging around software-defined control planes that decouple hardware lifecycle from application logic updates. This shift compresses traditional seven-to-ten-year platform stability expectations.
Time-sensitive networking (TSN) silicon is hybridizing deterministic Ethernet traffic scheduling with standard IT infrastructure, enabling single-cable architectures for motion control and safety systems. German automotive suppliers are deploying TSN-enabled servo drives at volume scale. The technology is compressing the installed base of proprietary fieldbus networks by unifying control and information planes.
China's GB standards for industrial equipment energy efficiency are mandating standby power limits and dynamic load management capabilities in motor control systems. Domestic OEMs must redesign thermal architectures and power stage topologies to comply. The regulation most acutely affects variable frequency drive manufacturers targeting heavy machinery segments.
Aftermarket service unbundling is separating hardware maintenance contracts from firmware subscription tiers and remote diagnostics platforms. German industrial automation corridors around Munich and Stuttgart show the most pronounced shift toward recurring software revenue models. Machine builders now procure embedded platforms based on total lifecycle service value rather than unit hardware cost.
Industrial Embedded Systems Market Segmentation
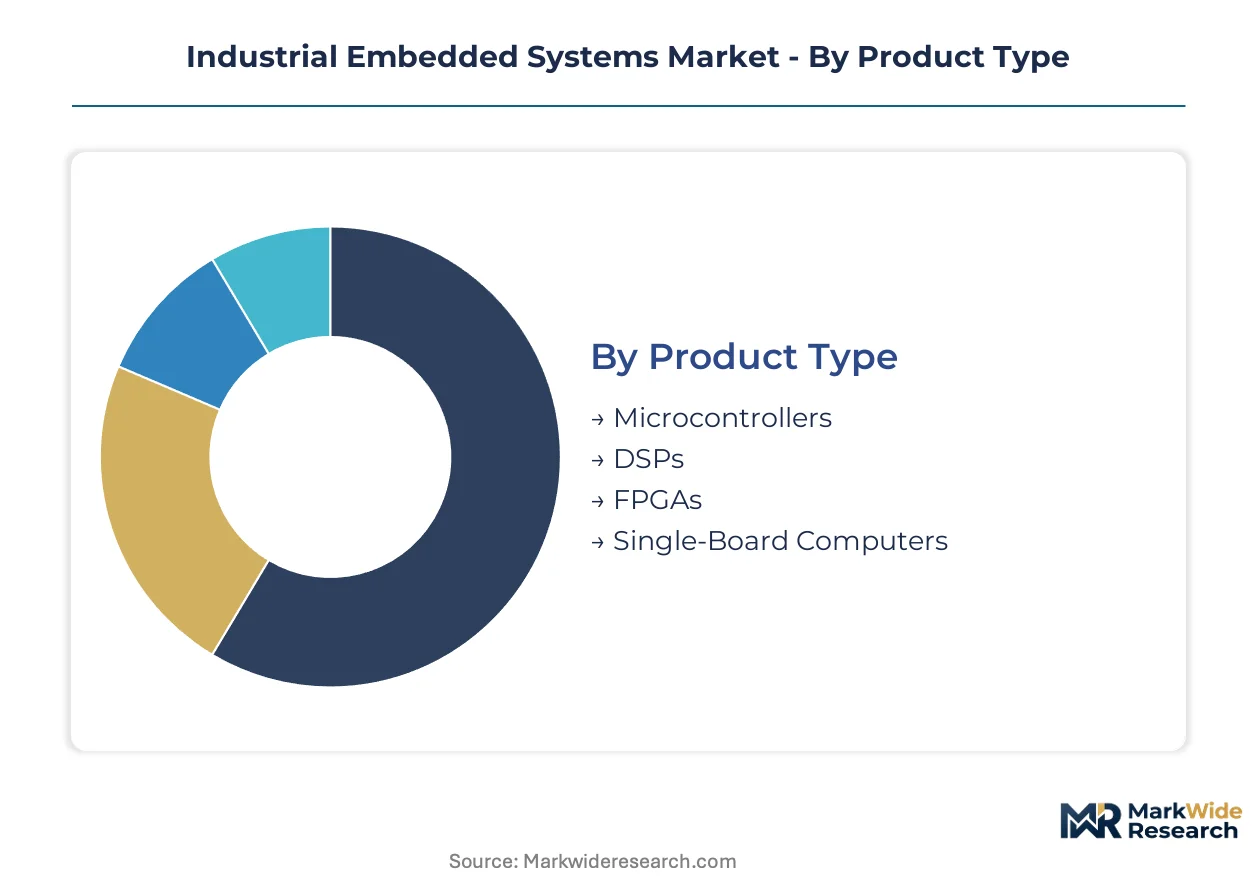
Segmentation in industrial embedded systems reveals how hardware specialization, software integration depth, and end-use reliability requirements create distinct procurement patterns. Buyers prioritize deterministic performance in robotics and aerospace, while manufacturing segments balance cost against longevity guarantees.
Product Type:
Mature architectures dominate revenue, yet emerging programmable logic is capturing design wins in adaptive control applications.
- Microcontrollers:These integrated processors combine CPU core, memory, and peripherals on single silicon dies optimized for deterministic real-time response. Automotive assembly lines in Germany's Stuttgart corridor specify automotive-grade MCUs for powertrain control modules where IEC 61508 SIL ratings are mandatory.
- FPGAs:Field-programmable gate arrays enable hardware-level parallelism for vision inspection and motion control algorithms. Robotics OEMs in Japan's Kanagawa prefecture deploy FPGAs for sub-millisecond servo loop closure in collaborative robot joints.
- DSPs:Digital signal processors execute mathematical operations on streaming sensor data for vibration analysis and motor control.
- Single-Board Computers:Compact system-on-module platforms integrate application processors with industrial I/O for edge gateway deployments.
Microcontrollers handle the majority of throughput; FPGAs are gaining share fastest in motion control applications.
End User:
Application requirements split sharply between continuous-process reliability demands and discrete-manufacturing flexibility needs.
- Manufacturing:Factory automation systems deploy embedded controllers across PLC racks, distributed I/O modules, and human-machine interface panels. German machinery builders around Munich specify extended-temperature components for foundry and forging environments.
- Robotics:Collaborative and industrial robot controllers demand real-time kinematics processing with functional safety certification. Japanese automotive suppliers integrate IEC 61508-compliant processors into six-axis articulated arm controllers.
- Automotive:Powertrain, chassis, and body electronics modules require AEC-Q100 qualified components with ISO 26262 safety ratings.
- Aerospace:Avionics and satellite systems specify radiation-hardened or high-reliability screened components with decades-long supply guarantees.
Manufacturing commands the largest installed base; robotics is expanding most quickly on new cobot deployment rates.
Technology:
Connectivity layers are displacing standalone architectures as factories converge operational and information technology infrastructure.
- Real-Time Systems:Deterministic operating systems guarantee bounded response latencies for safety-critical control loops. Process industries in the US Gulf Coast petrochemical corridor specify RTOS platforms with IEC 61508 certification evidence.
- IoT:Network-connected embedded devices stream telemetry to cloud analytics platforms for condition monitoring. German automotive suppliers deploy IoT-enabled vibration sensors on stamping press lines.
- Embedded Software:Firmware stacks abstract hardware complexity while enabling over-the-air security patch deployment.
- Wireless:Bluetooth Low Energy mesh and proprietary radio protocols eliminate cabling in rotating and mobile equipment.
Real-Time Systems anchor current procurement volumes; IoT is climbing the fastest on predictive maintenance adoption.
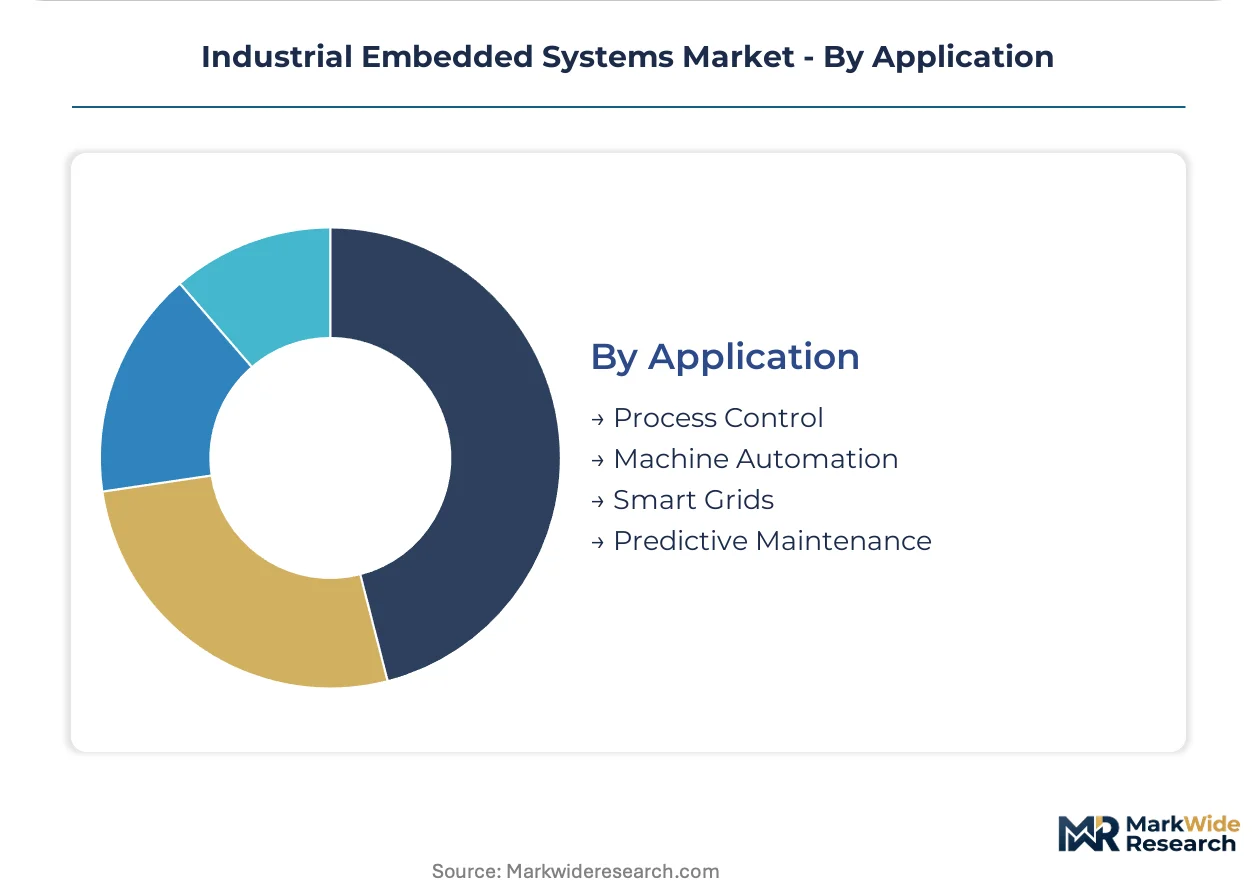
Application:
Control hierarchy level determines processing performance, connectivity bandwidth, and safety integrity requirements.
- Process Control:Distributed control systems regulate continuous chemical, oil, and power generation processes with 99.999% availability targets. US EPA emissions monitoring mandates drive embedded analyzer integration in refinery flare systems.
- Machine Automation:Discrete manufacturing cells coordinate motion, sequencing, and quality inspection through embedded PLC and CNC controllers. Japanese machine tool builders embed edge-AI accelerators for real-time tool wear prediction.
- Smart Grids:Power distribution automation requires synchronized phasor measurement and fault isolation capabilities.
- Predictive Maintenance:Condition-based monitoring systems analyze vibration, thermal, and electrical signatures to schedule maintenance before failure.
Process Control generates the steadiest replacement demand; Machine Automation shows the steepest expansion trajectory on smart factory investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's industrial automation corridor exhibit the lowest price elasticity, prioritizing IEC 61508 certification and supply continuity over unit cost. Procurement teams in India's emerging manufacturing belts remain highly price-sensitive, driving volume concentration at standard-grade microcontroller tiers.
Germany
Machinery builders around Munich and Stuttgart demand SIL-rated components for process control and collaborative robotics. The EU Machinery Directive and CE marking requirements enforce functional safety compliance across European supply chains. Bavaria's automotive suppliers anchor demand for deterministic real-time processors in powertrain and assembly line controllers.
United States
Petrochemical operators along the US Gulf Coast specify RTOS platforms with EPA emissions monitoring integration for refinery flare systems. EPA energy efficiency directives constrain component selection for motor control applications. Houston's process automation cluster drives replacement demand for distributed control system hardware.
China
Domestic OEMs redesign thermal architectures to comply with GB standards for industrial equipment energy efficiency and standby power limits. MIIT's industrial internet initiatives accelerate edge-AI accelerator deployment in smart factories. The Yangtze River Delta concentration of machine tool builders embeds neural network inference engines for real-time quality inspection.
Japan
Collaborative robot OEMs in Kanagawa prefecture require sub-millisecond servo loop closure for six-axis articulated arm controllers. METI's Society 5.0 roadmap prioritizes deterministic Ethernet and TSN silicon for unified control planes. Nagoya's automotive supplier ecosystem integrates IEC 61508-compliant processors at volume scale.
India
Electronic component manufacturers target Gujarat and Tamil Nadu corridors under the PLI scheme for industrial automation. BIS certification requirements and domestic content mandates reshape supplier qualification criteria. Chennai's emerging embedded system assembly cluster attracts contract manufacturing investments from global semiconductor vendors.
Industrial Embedded Systems Market Competitive Environment
Capability concentration sits with specialized semiconductor architects holding decade-long functional safety certification track records; scale advantage sits with diversified foundry operators sustaining manufacturing volume across automotive and industrial verticals. The vendor base organizes around three archetypes: automotive-grade MCU specialists, programmable logic fabricators, and edge-AI accelerator designers. Dominant competitive moves include foundry partnership restructuring for capacity allocation and portfolio extension into software-defined control platforms.
Within the automotive-grade tier, Renesas Electronics Corporation and Infineon Technologies exemplify suppliers with deep specialization in safety-critical microcontroller architectures. STMicroelectronics occupies a position bridging industrial automation and automotive qualification requirements. Intel Corporation anchors the scale-driven segment through foundry partnerships sustaining high-performance computing module production. Texas Instruments represents the diversified analog and embedded processing archetype with broad vertical coverage.
| Leading Market Players |
|---|
| Intel Corporation |
| Renesas Electronics Corporation |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| Texas Instruments |
| Analog Devices |
| Microchip Technology |
| Qualcomm Technologies |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity across Taiwan and South Korea compresses silicon availability for industrial automation OEMs, forcing buyers into multi-year offtake commitments and elevating pricing power among pre-qualified automotive-grade MCU suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement for IEC 61508-certified components, with spot-market exposure limited to non-safety-critical commodity microcontrollers. Pricing stratifies across SIL-rated, automotive-grade, and standard industrial tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-grade tiers intensifies as Indian contract manufacturers scale assembly capacity. Foundry customers in Germany's Munich-Stuttgart corridor exhibit lowest price sensitivity, prioritizing supply continuity over unit economics.
Supply Chain Analysis
Upstream silicon wafer supply draws from Taiwan, South Korea, and Japan, with advanced node capacity concentrated at TSMC and Samsung foundries. Raw material dependencies span 300mm silicon wafers, ABF substrate laminates, and rare-earth elements for high-temperature packaging. Single-source vulnerability in automotive-grade MCU fabrication creates systemic risk for European machinery builders. Distribution runs through authorized distributors and direct OEM contracts, bypassing open-market commodity channels for safety-critical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where IEC 61508 certification entrenchment creates decade-long switching costs for incumbent semiconductor architects.
For Market Incumbents: Insulate certification portfolios by accelerating FMEDA documentation for emerging edge-AI accelerator categories. Deepen backward integration into ABF substrate supply through captive partnerships with Japanese laminators. Counter margin pressure from Indian contract assemblers by bundling firmware subscription tiers with hardware platforms.
For New Entrants and Emerging Players: Build out wireless sensor network convergence capabilities in India's Gujarat and Tamil Nadu corridors, where PLI incentives reduce effective capital barriers. Target energy-harvesting Bluetooth mesh applications in rotating equipment monitoring, the most penetrable white-space segment. Pursue foundry partnerships with second-tier Taiwanese fabricators seeking industrial diversification beyond automotive allocation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-AI accelerator design houses as neural network inference IP development consumes R&D budgets. Long-term viability favors suppliers with dual-track automotive-industrial qualification capabilities. Watch for inflection in TSN silicon adoption rates among German automotive suppliers as signal of control-plane unification momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | IEC 61508 SIL documentation creates procurement preference among Munich machinery builders. |
| Foundry Partnership Restructuring | Capacity allocation agreements with Taiwan fabricators secure automotive-grade silicon supply. |
| Edge-AI Accelerator Portfolio Extension | Neural network inference engines embedded in PLC modules expand silicon content per unit. |
| Firmware Subscription Tier Unbundling | Recurring software revenue models shift procurement criteria from hardware cost to lifecycle value. |
| Wireless Sensor Network Convergence | Bluetooth Low Energy mesh eliminates cabling costs in rotating equipment monitoring applications. |
Study Parameters
Operator-level perspectives from embedded system procurement managers, functional safety engineering leads, semiconductor foundry planning officers, and industrial automation OEM technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, SEMI wafer shipment data, and EU Machinery Directive implementation reports. Bottom-up demand modeling triangulated against top-down industry association revenue aggregates.
Scenario-bracketing around foundry capacity allocation, IEC 61508 certification timeline compression, and edge-AI adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions spanned product architecture, end-use vertical, functional safety tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new deployment velocity in robotics and predictive maintenance applications.
Sensitivities concentrate around Taiwan semiconductor fabrication utilization rates, EPA energy efficiency directive enforcement intensity, and India PLI scheme extension decisions. Cross-checking against SEMI capital equipment spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe ICS Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global SCADA Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Industrial Human-Machine Interface Market