
 Global Discrete Automation Market | 2026-2036
Global Discrete Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Discrete Automation Market Intelligence
The convergence of operational technology (OT) and information technology (IT) is tilting the architecture of factory floors away from isolated systems. This shift favors vendors with comprehensive digital twin and simulation capabilities. Siemens AG leverages its extensive Digital Enterprise Suite to offer integrated solutions. Rockwell Automation Inc. competes through its Connected Enterprise framework, focusing on data analytics and smart manufacturing. ABB Ltd. differentiates with its Ability platform, which connects devices, systems, and services across industrial environments.
Discrete automation involves the use of control systems and robotics to manage manufacturing processes for distinct, countable items. These systems typically employ Programmable Logic Controllers (PLCs) to execute sequential logic with cycle times measured in milliseconds, ensuring high-speed, repeatable production. While PLCs remain a foundational component, the robotics segment is experiencing significant expansion. Demand from consumer electronics manufacturing and pharmaceutical production applications is driving innovation in both machine vision and motion control technologies, which are critical for high-precision assembly.
Product design and market access are shaped by stringent safety and interoperability standards. Compliance with the EU's Machinery Directive, OSHA regulations in the United States, and China's GB standards for industrial equipment is mandatory for vendors. These frameworks dictate requirements for machine safety, electrical integrity, and risk assessment. Navigating the fragmented landscape of regional certifications and cybersecurity protocols remains a central challenge for system integrators and OEMs.
Market Dynamics
The central structural force shaping the market is the convergence of operational technology (OT) and information technology (IT). This integration, driven by demand for data-rich manufacturing environments, is compelling a shift from isolated components to holistic, software-defined automation platforms.
Growth Catalysts
- Artificial Intelligence in Machine Vision:The integration of AI algorithms is enhancing the precision and speed of defect detection in high-volume manufacturing, particularly for semiconductor wafer inspection and electronics assembly applications.
- Pharmaceutical Sector Demand:Requirements for product serialization and high-speed, sterile packaging are driving investment in advanced robotics and integrated control systems to ensure compliance and production efficiency.
- Advanced Manufacturing Policies:Government initiatives in manufacturing hubs, including China's programs for semiconductor self-sufficiency, provide direct incentives and subsidies for adopting sophisticated discrete automation technologies.
Market Restraints
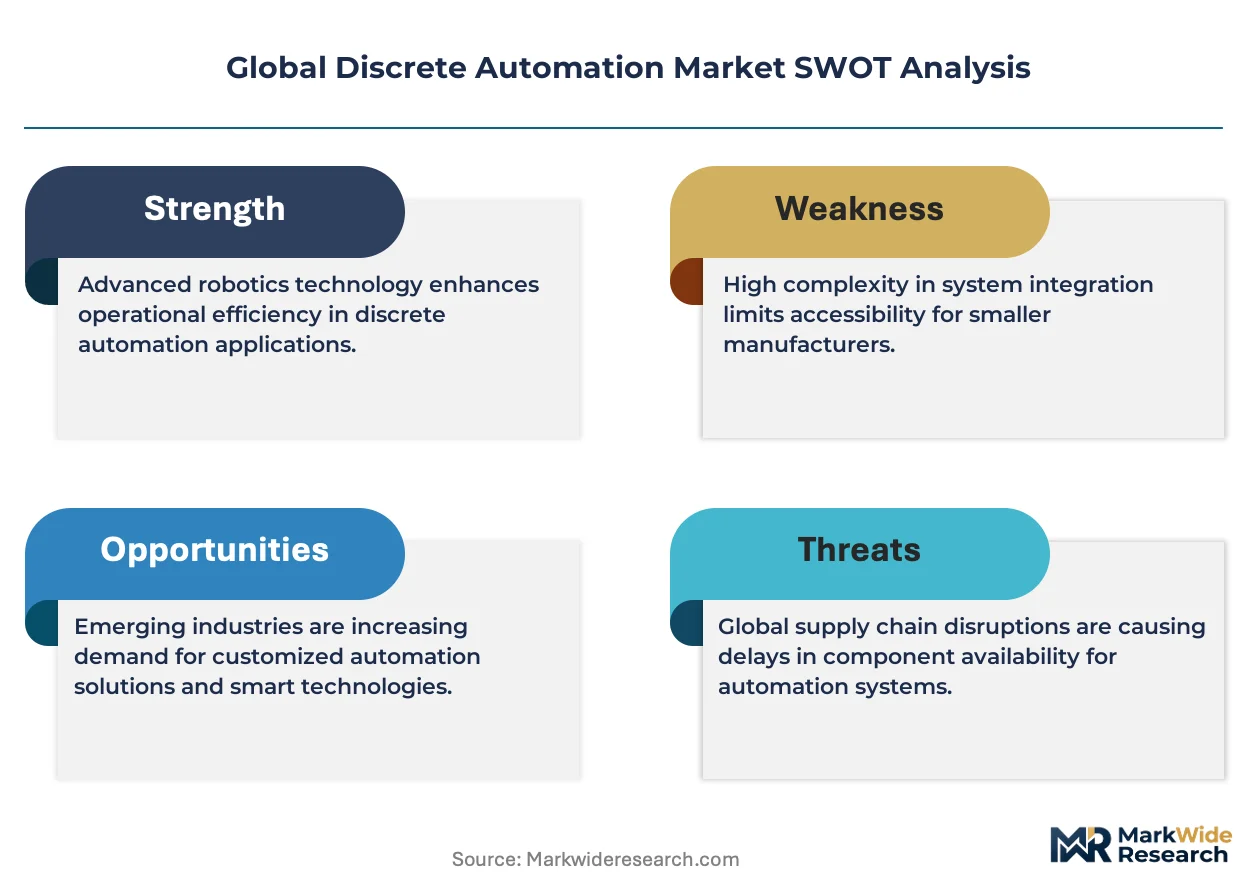
- High Capital Expenditure:The significant upfront investment required for advanced robotics, PLCs, and integrated control systems acts as a substantial barrier for small and medium-sized enterprises (SMEs) seeking to automate.
- Proprietary System Interoperability:A lack of standardization among vendor-specific control protocols creates significant integration challenges and vendor lock-in, increasing the complexity and cost of building multi-vendor production lines.
- Fragmented Regulatory Compliance:Navigating disparate regional safety standards, such as the EU's Machinery Directive and OSHA regulations in the US, complicates product design and adds significant overhead for global OEMs.
Strategic Opportunities
- Food and Beverage Automation:There is significant white space for applying high-speed robotics and vision systems in food processing for tasks like sorting, grading, and packaging of distinct items, improving hygiene and throughput.
- Software-Defined Automation:The development of platforms that decouple control software from proprietary hardware creates an opportunity for vendors to offer more flexible, scalable, and interoperable solutions.
- Expansion in Southeast Asia:Underpenetrated markets in Vietnam, Thailand, and Malaysia present a key growth vector, especially in supporting the expanding electronics, automotive, and textile manufacturing sectors.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with the expertise to program, integrate, and maintain complex robotics and PLC-based automation systems constrains deployment and operational uptime.
- Cybersecurity for Connected Systems:Securing networked industrial control systems from cyber threats is a critical challenge, as greater OT-IT integration expands the potential attack surface on the factory floor.
- Legacy System Integration:The cost and complexity of integrating modern automation technologies with aging, non-networked machinery on existing factory floors slows the pace of brownfield facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Discrete Automation Market |
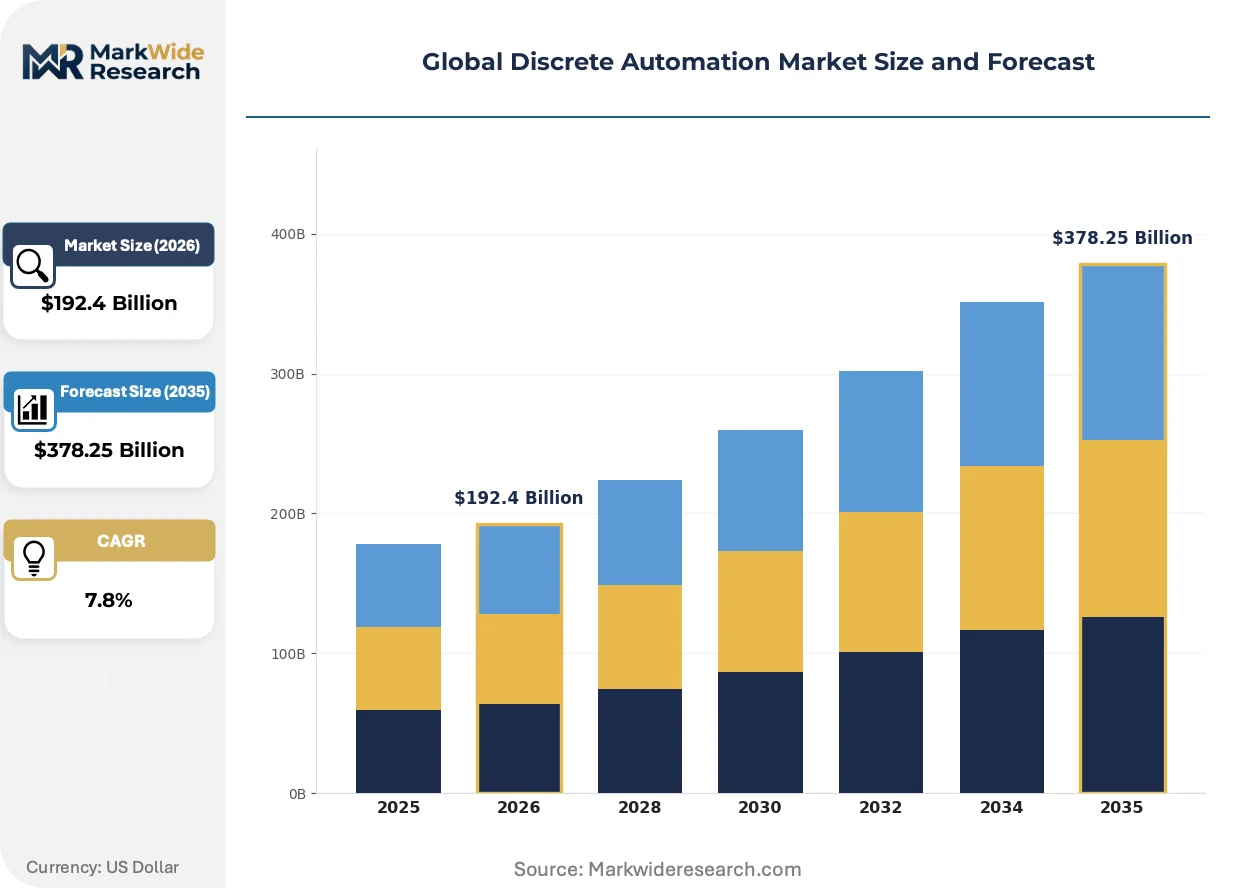
| Market Size in 2026 | $192.4 Billion |
| Market Size in 2035 | $378.25 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Distributed Control Systems, Human Machine Interface, Supervisory Control and Data Acquisition, Robotics Technology: Motion Control, Vision Systems, Machine Safety, Industrial Communication, Embedded Systems Application: Consumer Electronics Manufacturing, Semiconductor Fabrication, Aerospace Assemblies, Pharmaceutical Production, Packaging Lines End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Contract Manufacturers |
| Companies Covered | Mitsubishi Electric Corporation, Schneider Electric, Siemens AG, Omron Corporation, Emerson Electric Co., Rockwell Automation Inc., Honeywell International Inc., Fanuc Corporation, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Discrete Automation Market Strategic Shifts & Innovations
The evolution toward intelligent and flexible production is reshaping competitive positioning. This movement prioritizes modularity, data connectivity, and software-centric control, moving the industry away from rigid, hardware-defined automation architectures toward more adaptive and resilient factory models.
Digital twin technology creates a virtual, real-time model of a physical asset or an entire production line. Automotive and aerospace manufacturers are primary adopters, using these simulations to optimize line commissioning and enable predictive maintenance. This technology is digitizing the complete asset lifecycle, from initial system design and virtual testing to ongoing operational performance analysis.
The EU AI Act introduces a risk-based legal framework for artificial intelligence systems, directly impacting machine vision and AI-driven robotic controls. This regulation establishes stringent requirements for data quality, transparency, and human oversight for applications deemed high-risk. Consequently, vendors supplying the European market are re-architecting software and enhancing documentation to demonstrate compliance with these new mandates.
A demand-side shift is underway from purchasing discrete components toward acquiring integrated automation platforms that bundle hardware with a unified software environment. This transition disadvantages component specialists and favors suppliers offering a cohesive ecosystem. This pattern is most visible within the battery manufacturing and consumer electronics sectors, where system-level performance and rapid deployment are paramount.
Global Discrete Automation Market Segmentation
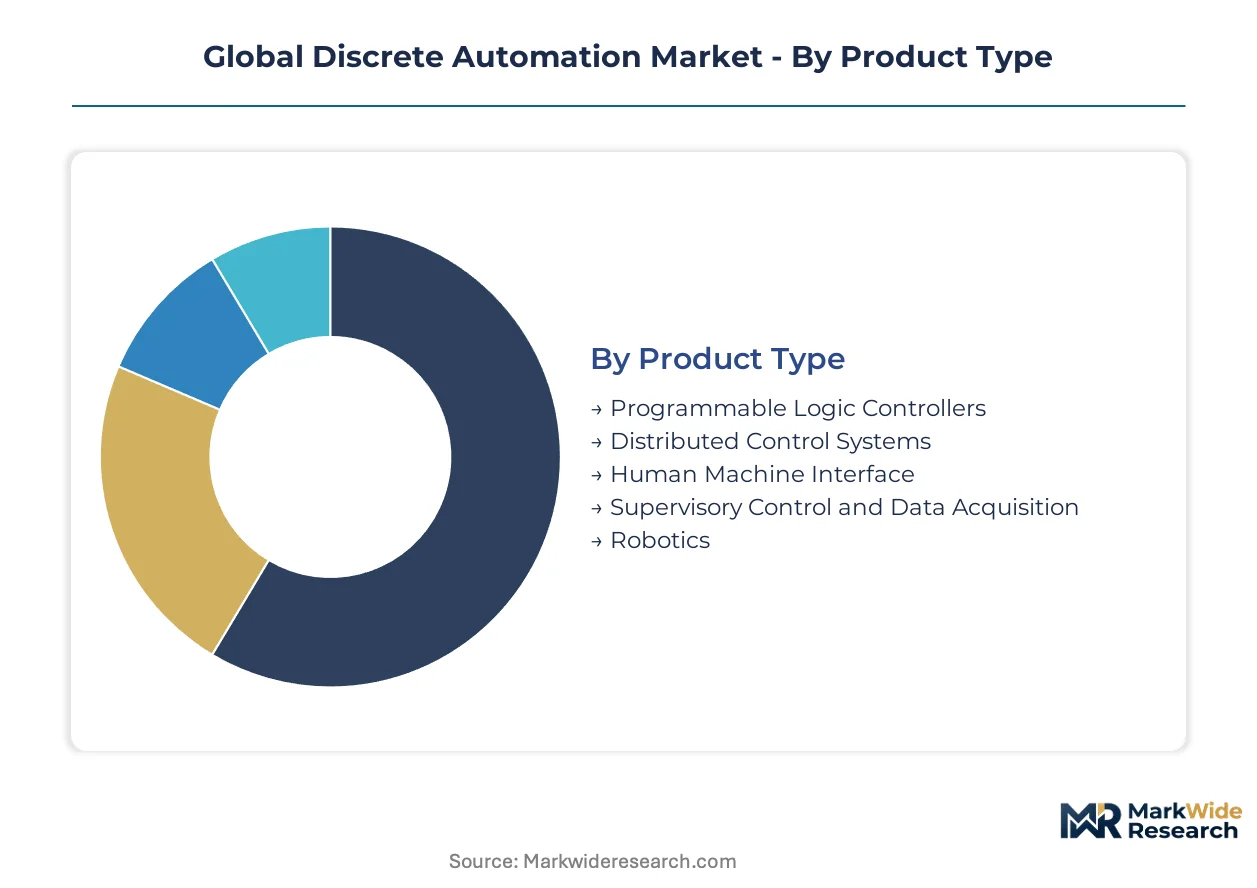
Understanding the discrete automation market through its segmentation reveals the specialized requirements and technological dependencies across various industrial processes. This granular view helps identify specific growth pockets and the distinct challenges faced by different product types, technologies, applications, and end-user industries. Strategic decisions regarding product development and market entry depend heavily on this detailed breakdown.
Product Type:
The maturity spectrum within product types ranges from foundational control systems to rapidly expanding robotic solutions. Robotics represents an emerging segment with significant innovation, while Programmable Logic Controllers remain a mature, indispensable component of automation architectures.
- Robotics:These systems consist of articulated or collaborative arms designed for repetitive, high-precision tasks such as assembly, material handling, and welding. Demand is concentrating in consumer electronics manufacturing and automotive assembly for enhanced throughput and quality.
- Programmable Logic Controllers:PLCs are industrial digital computers adapted for the control of manufacturing processes, executing sequential logic with millisecond cycle times. Semiconductor fabrication facilities rely on PLCs for precise process orchestration and machine control.
- Distributed Control Systems:DCS platforms manage complex, continuous industrial processes through geographically distributed control elements and a centralized operator interface.
- Human Machine Interface:HMI panels provide graphical user interfaces for operators to monitor and control industrial processes in real-time.
- Supervisory Control and Data Acquisition:SCADA systems collect real-time data from remote locations, allowing for centralized monitoring and control of industrial operations.
Robotics handles the majority of throughput; Programmable Logic Controllers is the fastest mover on share.
Technology:
The integration requirements of various discrete automation applications define the technology segment's structure. Each technology addresses specific functional needs, from precise movement to critical safety protocols, impacting overall system performance and reliability.
- Vision Systems:These technologies use cameras and image processing software for inspection, guidance, and identification tasks in automated production lines. The integration of AI algorithms significantly enhances defect detection accuracy in electronics assembly.
- Motion Control:Motion control systems precisely regulate the speed, torque, and position of electric motors and mechanical components. High-precision assembly operations in medical device manufacturing depend on advanced motion control capabilities.
- Machine Safety:Machine safety technologies, including light curtains, safety interlocks, and emergency stops, protect personnel from hazardous machine movements and comply with regulations like the EU Machinery Directive.
- Industrial Communication:These protocols and networks facilitate data exchange between control systems, sensors, and actuators on the factory floor, enabling real-time operational visibility.
- Embedded Systems:Embedded systems are dedicated computer systems designed to perform specific functions within larger mechanical or electrical systems, often found in smart sensors and actuators.
Innovation in Vision Systems drives functionality across the entire automation stack, while Machine Safety represents a critical layer for system reliability.
Application:
The volume and precision requirements of manufacturing operations dictate the segmentation by application. Each application demands tailored automation solutions to meet specific production goals and quality standards.
- Consumer Electronics Manufacturing:This segment involves high-volume assembly and testing of devices such as smartphones, laptops, and wearables, requiring rapid, precise robotic handling and vision inspection. Demand is concentrating in manufacturing hubs within China for advanced assembly lines.
- Semiconductor Fabrication:Semiconductor fabrication requires ultra-precise motion control, cleanroom robotics, and advanced machine vision for wafer handling, inspection, and packaging. Government incentives in countries like China support investment in this critical sector.
- Aerospace Assemblies:Automation in aerospace focuses on large-scale component assembly, drilling, and inspection, emphasizing accuracy and traceability for critical structural elements.
- Pharmaceutical Production:This application involves sterile handling, precise dosing, and high-speed packaging of pharmaceutical products, driven by serialization requirements and compliance needs.
- Packaging Lines:Automation in packaging ensures high-speed sorting, filling, sealing, and labeling of diverse products, enhancing efficiency and reducing manual labor.
Consumer Electronics Manufacturing consistently demands the highest levels of speed, and Semiconductor Fabrication requires the most stringent environmental controls.
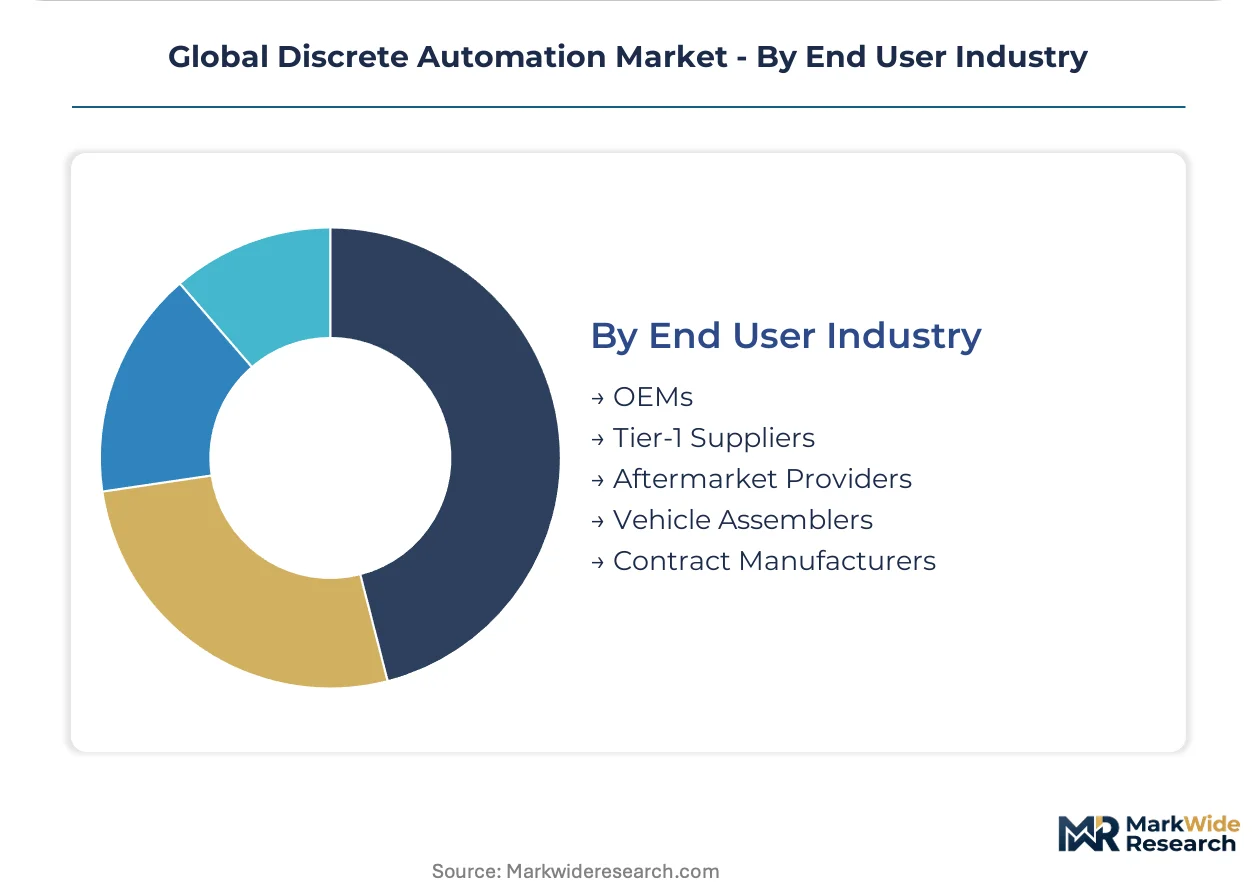
End User Industry:
The discrete automation market's end-user segmentation reflects distinct roles within the manufacturing value chain. Each industry segment presents unique purchasing behaviors and integration challenges for automation vendors.
- OEMs:Original Equipment Manufacturers integrate discrete automation components into their machinery and systems before selling them to end-users. These companies influence product design and feature sets significantly.
- Contract Manufacturers:Contract manufacturers produce goods for other companies, often requiring flexible and scalable automation solutions to handle diverse product lines and high-volume orders. This segment drives adoption of standardized, high-volume solutions.
- Tier-1 Suppliers:These suppliers provide major sub-assemblies or components directly to OEMs, often requiring specialized automation for their specific manufacturing processes.
- Aftermarket Providers:Aftermarket providers offer spare parts, maintenance, and upgrade services for existing automation systems, ensuring continued operational efficiency.
- Vehicle Assemblers:This segment includes companies that assemble automobiles, trucks, and other vehicles, heavily relying on robotics and integrated control systems for body shops, paint shops, and final assembly.
OEMs influence product specifications significantly, whereas Contract Manufacturers are gaining share fastest through volume production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Discrete automation market demand concentrates in regions with established high-volume manufacturing capabilities. Buyer archetypes for advanced robotics and control systems are prevalent in consumer electronics, automotive, and semiconductor industries. These sectors require precision and speed for complex assembly processes.
China
Demand for discrete automation in China stems from its vast consumer electronics manufacturing and advanced semiconductor ambitions. Government initiatives, including programs for semiconductor self-sufficiency, provide significant incentives for adopting sophisticated automation technologies. Manufacturing hubs like Shenzhen are rapidly deploying advanced robotics for electronics assembly and wafer inspection.
United States
The United States drives discrete automation adoption through its aerospace assemblies and medical device manufacturing sectors. OSHA regulations mandate stringent safety standards for industrial machinery, influencing automation system design. Silicon Valley and other tech corridors focus on integrating AI into machine vision for advanced manufacturing applications.
Germany
Germany's discrete automation market is propelled by its strong automotive industry and precision engineering requirements. Compliance with the EU's Machinery Directive is mandatory for vendors, ensuring high safety and quality standards. Industrial clusters in Bavaria and Baden-Württemberg are centers for robotic innovation and integrated control systems.
Japan
Japan maintains robust demand for discrete automation in its automotive and industrial machinery sectors, emphasizing precision and reliability. METI policies support advanced manufacturing technologies, fostering innovation in robotics and motion control. Tokyo and Osaka Bay areas host numerous factories integrating PLCs for complex production lines.
South Korea
South Korea's discrete automation market is fueled by its leadership in semiconductor fabrication and consumer electronics production. The country's national industrial policies encourage smart factory deployments and research and development in AI-driven automation. Manufacturing zones around Seoul and Gyeonggi Province showcase extensive use of high-speed robotics.
Global Discrete Automation Market Key Industry Players
Channel-controlling players compete with product-specialist players across the discrete automation market, creating a dynamic competitive environment. This market exhibits a tiered structure, ranging from global conglomerates offering comprehensive digital solutions to specialized component manufacturers. Three strategic archetypes emerge: integrated solution providers, niche technology specialists, and regional system integrators focused on localized needs. Portfolio diversification, strategic partnerships, and targeted acquisitions are dominant competitive moves among these diverse players, aiming to capture market share.
On the integrated platform vector, Siemens AG, a German multinational conglomerate, exemplifies comprehensive digital enterprise solutions, leveraging its extensive suite to offer integrated solutions. Rockwell Automation Inc., a US-based corporation, occupies a significant position focused on connected enterprise frameworks, emphasizing data analytics and smart manufacturing capabilities. ABB Ltd., a Swiss-Swedish multinational corporation, represents a key player differentiating with its Ability platform, connecting diverse devices, systems, and services across industrial environments. These major entities are characterized by their extensive global reach and broad product portfolios, addressing complex automation needs.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Schneider Electric |
| Siemens AG |
| Omron Corporation |
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Fanuc Corporation |
| ABB Ltd. |
| Others |
Cost & Logistics Intelligence
Upstream concentration in China's manufacturing hubs, particularly for consumer electronics and semiconductors, directly influences the cost structure and margin capture for discrete automation solution providers. This geographic focus creates both efficiencies and potential vulnerabilities within the broader market for control systems and robotics.
Pricing Analysis
Cost-plus contracts, often indexed to component costs like microcontrollers and specialized sensors, govern many long-term agreements for discrete automation systems. Price differentiation stems from customization levels for specific factory layouts and the breadth of comprehensive after-sales service packages. Pricing pressure stems from increased competition among integrated solution providers, particularly for high-volume standard components. OEMs are typically less price-sensitive due to long-term operational costs, while contract manufacturers demand more competitive pricing for scale.
Supply Chain Analysis
Contract manufacturing concentration in Taiwan and South Korea for advanced semiconductors forms the core of the discrete automation supply chain. Raw material dependencies include specialized rare earth elements for magnets in motion control systems and high-grade silicon for PLC microprocessors. Single-source vulnerability for critical components poses a significant structural risk. Distribution runs through a network of regional system integrators and direct sales channels to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The discrete automation market is experiencing a cyclical recovery, driven by renewed capital expenditure in advanced manufacturing sectors. This rebound reflects increased investment in factory modernization and efficiency upgrades across key industrial geographies.
For Market Incumbents: Build ecosystem lock-in through integrated software platforms and extensive service networks. Diversify beyond hardware by enhancing AI-driven vision systems to counter commoditization pressure from new component specialists. Invest in certification for compliance with the EU AI Act to mitigate regulatory threats in European markets.
For New Entrants and Emerging Players: Build out specialized software-defined automation solutions for niche applications like food and beverage processing. Target underpenetrated markets in Southeast Asia, particularly Vietnam's expanding electronics sector, with flexible, modular robotics. A go-to-market angle emphasizing rapid deployment and lower total cost of ownership for SMEs could gain traction.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap software companies specializing in industrial AI and digital twin capabilities. The discrete automation market offers long-term viability, underpinned by persistent demand for efficiency and precision across manufacturing. A key signal to watch is the increasing adoption rate of open-source industrial communication protocols, indicating greater interoperability and market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse hardware components under a common software environment, enhancing operational efficiency. |
| AI-Driven Vision System Development | Improves defect detection precision in semiconductor fabrication and consumer electronics assembly lines. |
| Geographic Expansion into Southeast Asia | Captures new demand from expanding electronics and automotive manufacturing sectors in Vietnam and Malaysia. |
| Digital Twin Capability Enhancement | Optimizes line commissioning and enables predictive maintenance for automotive and aerospace manufacturers. |
| Cybersecurity Service Offerings | Secures networked industrial control systems against increasing cyber threats in OT-IT integrated environments. |
Research Approach
The analysis maps discrete automation sub-sectors, each validated through industrial automation engineers, plant managers, and procurement specialists. This process combined primary interviews with extensive secondary validation from sources like SEC 10-K filings, national manufacturing statistics from METI, and EU Machinery Directive compliance reports. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Assumptions for the forecast held macroeconomic stability fixed but varied technological adoption rates and regulatory compliance costs across the modeling period. Segmentation dimensions included product type, technology, application, end-user industry, and regional manufacturing capacity. Compound annual growth rates were derived from historical data trends and projected industry investment cycles. Industrial capital expenditure and semiconductor fabrication output served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated solution providers or new AI-focused startups would shift outcomes. Forecasts reflect current market dynamics, acknowledging that unforeseen supply chain disruptions or significant policy changes, like new GB standards, could revise projections. Quarterly review of industrial production indices and technology patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Middle East and Africa Machine Control System Market