
 Geosteering Technology Market | 2026-2036
Geosteering Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Geosteering Technology Market Analysis
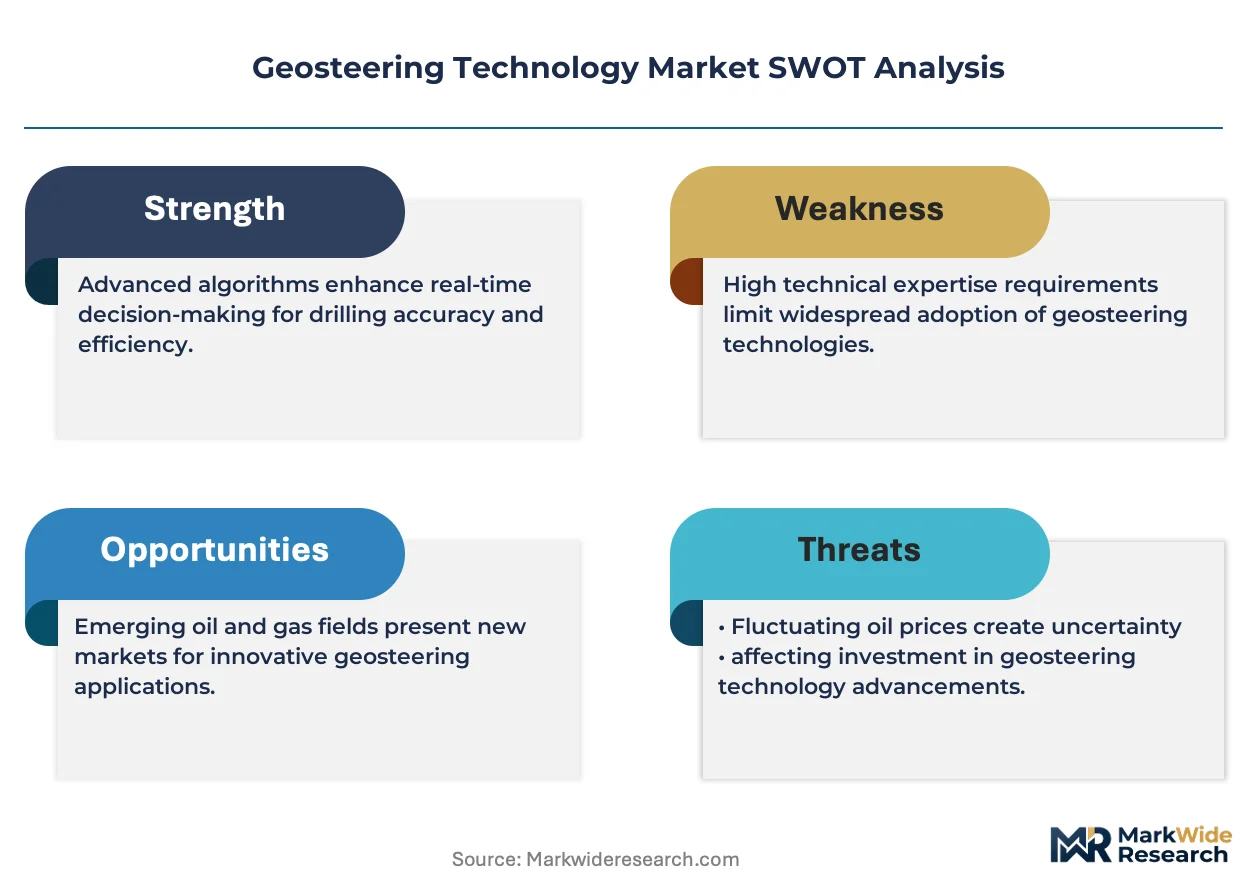
Modular hardware-software bundles is decoupling from traditional integrated service contracts, giving operators flexibility to mix vendors. Schlumberger Limited leverages its deep R&D pipeline to sustain technology leadership in resistivity logging-while-drilling tools. Baker Hughes Company anchors its position through proprietary rotary steerable systems that compete on directional accuracy in complex shale formations.
Geosteering technology comprises directional drilling instrumentation, real-time telemetry links, and subsurface interpretation algorithms that adjust wellbore trajectories based on gamma ray, resistivity, and acoustic measurements while drilling. Its primary purpose places hydrocarbon-producing wellbores within optimal reservoir zones to maximize recovery and minimize non-productive footage. Software Solutions and Real-Time Data Analysis segments lead margin capture, as recurring license fees and cloud-based analytics subscriptions outpace capital-intensive hardware sales in profitability. Automated Systems represents the fastest-expanding technology category, with drill-optimization algorithms reducing human-in-the-loop latency from minutes to seconds.
The US EPA and state-level oil and gas commissions shape demand through methane intensity standards and wellbore integrity rules that mandate precise geolocation of producing intervals. OSHA drilling safety requirements and the Bureau of Land Management's lease stipulations further tighten operational tolerances on federal lands. Stakeholders must weigh build-versus-buy decisions on automated geosteering stacks as vendor consolidation and open-source telemetry protocols redraw competitive boundaries.
Market Dynamics
Modular hardware-software bundles are decoupling from traditional integrated service contracts, giving operators flexibility to mix vendors and compress procurement cycles while tightening vendor accountability on individual component performance.
Growth Catalysts
- US EPA methane intensity standards:The agency's tightened emissions rules mandate precise geolocation of producing intervals, forcing operators to upgrade telemetry density and real-time steering precision.
- Unconventional shale operators:Permian and Bakken basin producers in Texas and North Dakota drive adoption of real-time subsurface navigation tools to maximize lateral landing accuracy.
- Cloud-based analytics subscriptions:Recurring license fees for automated drill-optimization algorithms outpace capital-intensive hardware sales in profitability, pulling vendors toward software-centric revenue models.
Market Restraints
- High-precision sensor supply concentration:Advanced resistivity and gamma ray logging-while-drilling tools depend on specialized semiconductor foundries concentrated in East Asia, creating single-source vulnerability.
- Proprietary rotary steerable system lock-in:Baker Hughes and Schlumberger maintain closed telemetry protocols that block third-party algorithm integration, fragmenting automated stack assembly.
- Extended certification timelines:Bureau of Land Management lease stipulations on federal lands require multi-stage wellbore integrity verification, stretching deployment schedules.
Strategic Opportunities
- Open-source telemetry protocols:Emerging industry standards for data interchange between directional drilling instrumentation and subsurface interpretation algorithms enable vendor-agnostic automation stacks.
- Carbon capture and storage applications:Salt cavern and depleted reservoir sequestration projects in Alberta and Saskatchewan require geosteering precision for injection well placement, opening adjacent demand.
- OSHA drilling safety mandates:Updated blowout prevention and well control requirements create pull for integrated real-time monitoring systems that fuse downhole measurements with surface safety interlocks.
Industry Challenges
- Petrophysicist and drilling engineer shortage:Interpretation of resistivity, acoustic, and gamma ray logs for automated trajectory adjustment demands scarce cross-trained talent.
- Legacy SCADA integration friction:Brownfield drilling rigs running decades-old control architectures resist seamless incorporation of cloud-connected geosteering modules without costly retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geosteering Technology Market |
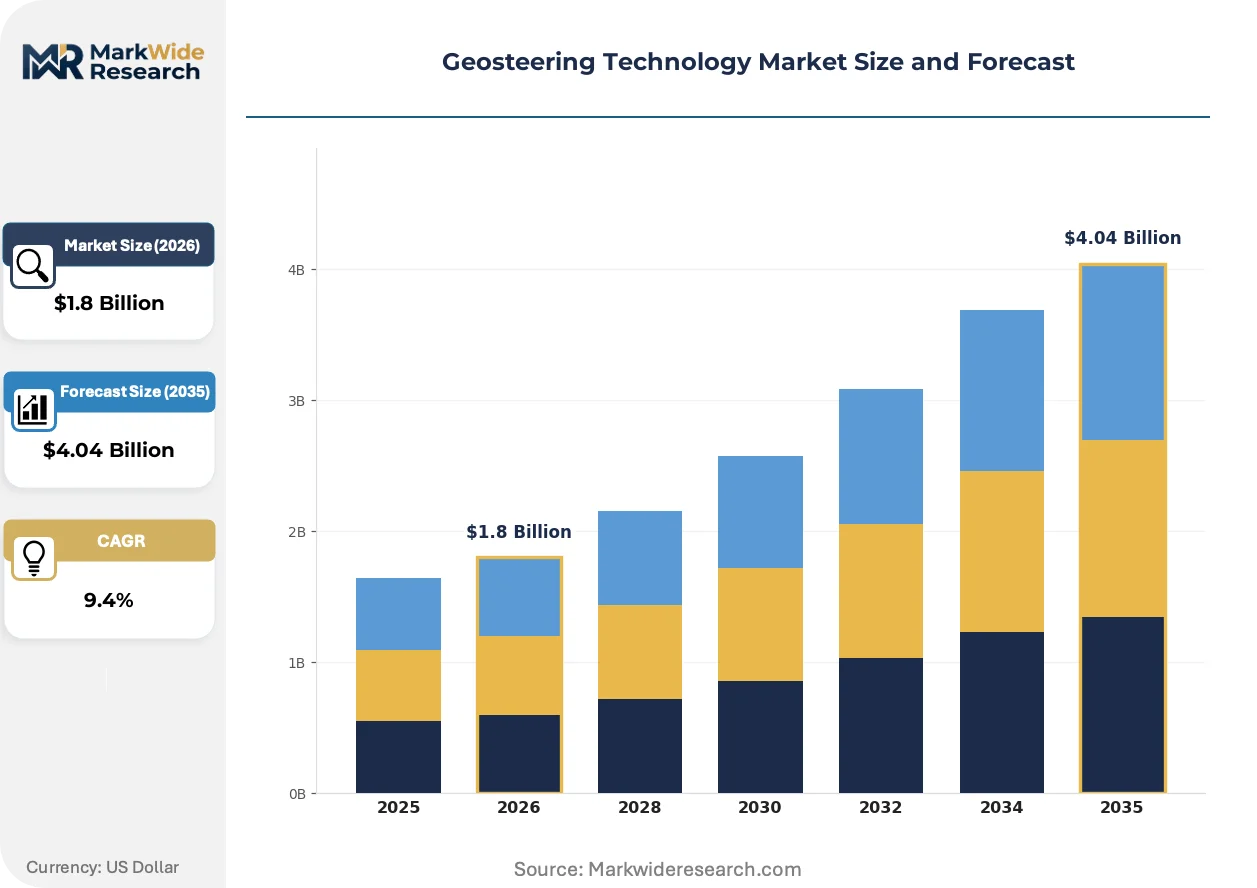
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Services, Hardware, Tools Technology: Real-Time Data Analysis, Imaging, Drill Optimization, Automated Systems Application: Oil Exploration, Gas Production, Underground Mining, Geothermal Energy End User: Energy Companies, Mining Operators, Construction Firms, Environmental Consultants |
| Companies Covered | Schlumberger Limited, Halliburton Energy Services, Inc., Baker Hughes Company, Weatherford International PLC, National Oilwell Varco, Emerson Paradigm Holding LLC, ROGII Inc., HMG Software LLC, Cougar Drilling Solution Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geosteering Technology Market Emerging Trajectories
Automation is compressing human-in-the-loop latency from minutes to seconds while regulatory pressure tightens operational tolerances, reshaping how vendors architect their technology stacks and pricing models.
Machine learning-based formation evaluation is converging with edge-computing telemetry nodes. Unconventional shale operators in the Permian Basin deploy these systems to process resistivity and gamma ray signatures locally rather than transmitting raw data to surface servers. The convergence is collapsing interpretation delays and enabling sub-minute steering corrections that keep laterals within optimal reservoir zones.
REACH chemical registration requirements in the European Union now cover drilling fluid additives and sensor encapsulation materials. Manufacturers must document full substance toxicity profiles for gamma ray detector housings and high-temperature electronics potting compounds. Service companies operating in the North Sea and onshore Netherlands are reformulating their supply chains to exclude restricted substances ahead of enforcement deadlines.
After-sales service unbundling is fragmenting traditional integrated contracts. North American shale operators now procure directional drilling instrumentation, telemetry links, and interpretation software from separate vendors, then contract fourth-party specialists for integration support. The shift is visible most acutely in Texas, where independent producers mix Schlumberger resistivity tools with Baker Hughes rotary steerable systems and third-party cloud analytics platforms.
Geosteering Technology Market Segmentation
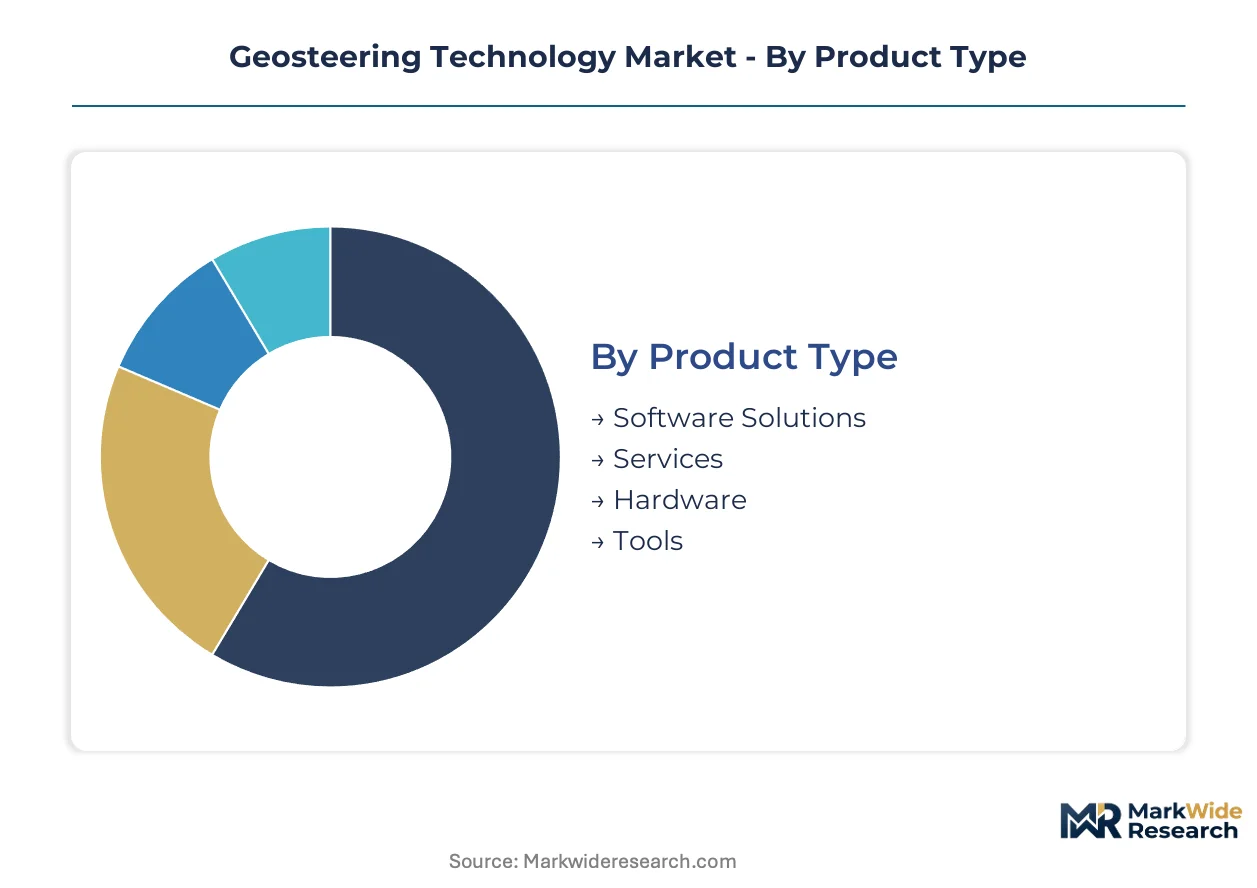
Geosteering technology vendors architect their portfolios around four intersecting dimensions. Product configuration determines capital intensity and margin structure. Technology sophistication dictates automation depth and regulatory compliance posture.
Product Type:
Supply concentration clusters around software stacks and proprietary hardware bundles, with services and tools exhibiting more fragmented vendor landscapes.
- Software Solutions:Cloud-based subsurface interpretation platforms process gamma ray and resistivity measurements through algorithmic trajectory adjustment. Permian Basin operators in Texas subscribe to these systems for recurring license revenue that outpaces hardware profitability. US EPA methane intensity standards mandate precise geolocation capabilities that software vendors embed as core features.
- Hardware:Directional drilling instrumentation and telemetry links require specialized semiconductor foundries concentrated in East Asia. North Dakota Bakken producers depend on these components for real-time data transmission from downhole sensors to surface control systems.
- Services:Integration support and field engineering for mixed-vendor deployments. Independent Texas producers contract fourth-party specialists to combine resistivity tools with rotary steerable systems.
- Tools:Consumable drilling accessories and sensor housings subject to REACH chemical registration for encapsulation materials. North Sea operators reformulate supply chains to exclude restricted substances.
Software Solutions absorbs the bulk of installed capacity; Hardware is expanding most quickly.
Technology:
Cost tier differentiation separates premium automation stacks from baseline imaging and analysis modules.
- Automated Systems:Drill-optimization algorithms compress human-in-the-loop latency from minutes to seconds through edge-computing telemetry nodes. Unconventional shale operators deploy these for sub-minute steering corrections in complex formations.
- Real-Time Data Analysis:Streaming interpretation of resistivity, acoustic, and gamma ray logs enables trajectory adjustments while drilling proceeds. Bakken lateral wells rely on this capability to maximize reservoir contact.
- Imaging:Subsurface visualization tools for pre-drill planning and post-drill verification. Geothermal projects in Nevada use these for reservoir characterization.
- Drill Optimization:Parameter recommendation engines for rate-of-penetration and directional control. Mining operators in Saskatchewan apply these to potash extraction efficiency.
Real-Time Data Analysis commands the largest deployment base; Automated Systems shows the steepest expansion trajectory.
Application:
Volume concentration tracks hydrocarbon basins, with emerging energy transition applications diversifying demand geography.
- Oil Exploration:Lateral well placement in unconventional shale reservoirs demands precise geosteering to minimize non-productive footage. Texas Permian operators drive procurement intensity here.
- Gas Production:Tight gas and coalbed methane development requires wellbore integrity verification under Bureau of Land Management lease stipulations on federal lands.
- Underground Mining:Ore body delineation and tunnel steering for potash and salt operations. Saskatchewan mining corridors adopt adapted oilfield telemetry for extraction precision.
- Geothermal Energy:Injection and production well placement for enhanced geothermal systems. Nevada and Utah projects require geosteering precision for fractured reservoir targeting.
Oil Exploration retains dominant share; Geothermal Energy is gaining share fastest.
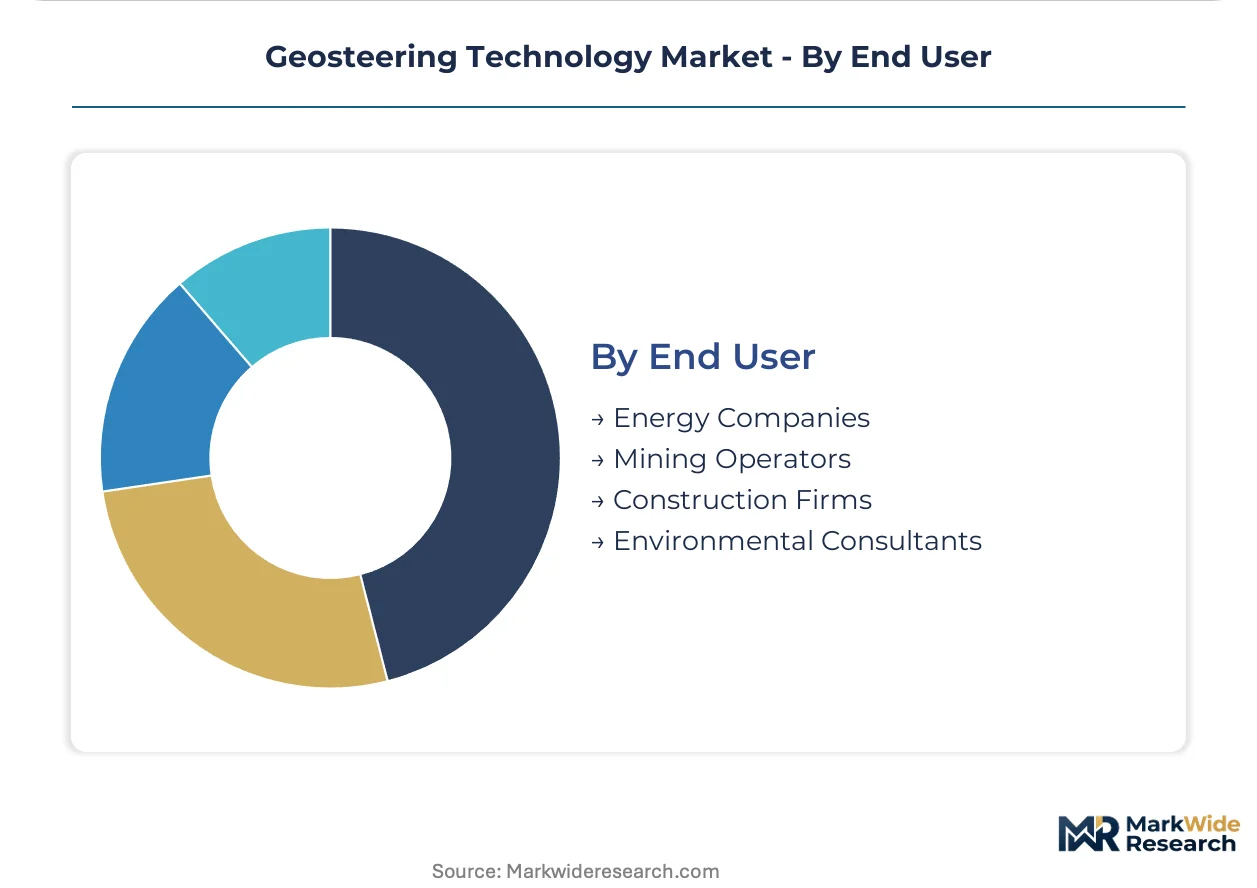
End User:
Customer type determines procurement sophistication and vendor relationship structure.
- Energy Companies:Integrated and independent operators with capital budgets for bundled technology stacks. Bakken and Permian producers lead modular procurement experimentation.
- Mining Operators:Extractive firms adapting oilfield geosteering for ore body navigation. Saskatchewan potash corridors represent the primary adoption cluster.
- Construction Firms:Tunnel boring and underground infrastructure projects requiring subsurface navigation. Urban corridor projects in California face OSHA drilling safety requirements.
- Environmental Consultants:Carbon capture and storage project developers steering injection wells into salt caverns and depleted reservoirs. Alberta and Saskatchewan sequestration sites create adjacent demand.
Energy Companies account for the majority of current deployments; Environmental Consultants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the bulk of geosteering technology output while specialized semiconductor foundries in East Asia supply critical sensor components. This production-consumption divide shapes procurement strategies and supply chain risk profiles across major drilling jurisdictions.
United States
Unconventional shale operators in the Permian Basin of Texas and the Bakken formation in North Dakota drive demand intensity. The US EPA's methane intensity standards mandate precise geolocation of producing intervals, forcing upgrades to telemetry density. Houston hosts the largest concentration of service company headquarters and integration engineering capacity.
Canada
Carbon capture and storage projects in Alberta and Saskatchewan require geosteering precision for injection well placement into salt caverns and depleted reservoirs. Health Canada and provincial regulators enforce wellbore integrity verification timelines that stretch deployment schedules. Calgary anchors the domestic vendor ecosystem and field engineering talent pool.
Norway
North Sea operators deploy advanced automated systems for complex reservoir navigation in mature offshore fields. REACH chemical registration requirements cover drilling fluid additives and sensor encapsulation materials used in subsea environments. Stavanger concentrates subsea technology R&D and specialist engineering services.
China
Domestic shale gas development in Sichuan Basin and coalbed methane projects create demand for real-time telemetry and directional drilling instrumentation. The Ministry of Ecology and Environment enforces dual carbon goals that tighten drilling precision requirements for methane control. Beijing and Tianjin host state-owned oilfield service company headquarters and technology import partnerships.
Saudi Arabia
Unconventional gas development in the Jafurah Basin drives adoption of automated geosteering stacks for tight gas reservoir targeting. The national oil company mandates localization requirements that reshape vendor partnership structures. Dhahran concentrates domestic engineering capabilities and technology transfer agreements with international service providers.
Geosteering Technology Market Vendor Landscape
The competitive structure tilts toward integrated oilfield service conglomerates with captive technology portfolios. Schlumberger Limited, Baker Hughes Company, and Halliburton Energy Services, Inc. anchor the premium tier through proprietary rotary steerable systems and resistivity logging-while-drilling tools. Independent software vendors and regional specialists occupy fragmented niches in cloud analytics and integration support. Consolidation pressure operates through vendor consolidation of automated stack providers and open-source telemetry protocol initiatives that redraw competitive boundaries.
Within the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify the closed-protocol model that blocks third-party algorithm integration. Halliburton Energy Services, Inc. occupies a position between full vertical integration and modular component supply. Weatherford International PLC and National Oilwell Varco sit within the diversified equipment segment with broader drilling product portfolios. Emerson Paradigm Holding LLC and ROGII Inc. represent the software-centric archetype with recurring license revenue models. HMG Software LLC and Cougar Drilling Solution Inc. anchor the regional specialist category focused on North American shale basins.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Energy Services, Inc. |
| Baker Hughes Company |
| Weatherford International PLC |
| National Oilwell Varco |
| Emerson Paradigm Holding LLC |
| ROGII Inc. |
| HMG Software LLC |
| Cougar Drilling Solution Inc. |
| Others |
Supply Flow & Price Mechanics
Operator preference for modular hardware-software procurement is fragmenting traditional bundled contracts and forcing vendors to unbundle pricing while maintaining component interoperability. This shift compresses margins on standalone hardware sales while elevating recurring software license values.
Pricing Analysis
Margin tightening in hardware tiers reflects East Asian semiconductor foundry concentration and single-source sensor vulnerability. Three-tier pricing structure across premium automation stacks, standard real-time analysis modules, and economy imaging tools differentiates by algorithm sophistication and telemetry density. Cost-down pressure on resistivity logging-while-drilling components accelerates because operators now mix vendors and demand component-level accountability. Independent shale producers in Texas exhibit highest price sensitivity; integrated national oil companies show lowest.
Supply Chain Analysis
Dual-sourcing qualification requirements from North American operators are reshaping procurement patterns for directional drilling instrumentation. Advanced gamma ray detectors and high-temperature electronics potting compounds draw from specialized foundries in Taiwan, South Korea, and Japan. Supply chain risk centers on tariff exposure for semiconductor components crossing Pacific trade routes. Distribution runs through Houston-based service company headquarters and Calgary integration engineering hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation and open-source telemetry protocol initiatives are compressing viable competitive positions, forcing subscale automated stack providers toward exit or acquisition.
For Market Incumbents: Lock in proprietary rotary steerable system dominance through backward integration into specialized semiconductor sourcing and exclusive edge-computing telemetry node development. Cement resistivity logging-while-drilling tool leadership via R&D investment in sub-minute steering correction algorithms. Closed-protocol lock-in blocks third-party algorithm integration and defends against modular unbundling pressure. For New Entrants and Emerging Players: Environmental consultants steering carbon capture injection wells represent an underserved buyer archetype with limited incumbent penetration. Carbon sequestration projects in Alberta and Saskatchewan offer white-space expansion with lower competitive intensity than Permian shale. Open-source telemetry protocol adoption enables vendor-agnostic automation stack assembly without proprietary rotary steerable system development costs. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric automated stack specialists given EPA methane intensity standard enforcement accelerating precision geolocation demand. Five-to-ten year viability favors recurring license revenue models over capital-intensive hardware manufacturers. Watch Bureau of Land Management lease stipulation expansion as inflection indicator for federal land drilling precision requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Rotary Steerable System Development | Schlumberger and Baker Hughes anchor premium tier through closed-protocol directional accuracy in complex shale formations. |
| Open-Source Telemetry Protocol Adoption | Industry standards for data interchange enable vendor-agnostic automation stack assembly and fragment integrated service contracts. |
| Edge-Computing Telemetry Node Deployment | Permian Basin operators process resistivity signatures locally rather than transmitting raw data to surface servers. |
| Carbon Capture and Storage Application Expansion | Alberta and Saskatchewan salt cavern sequestration projects require geosteering precision for injection well placement. |
| Cloud-Based Analytics Subscription Migration | Recurring license fees for automated drill-optimization algorithms outpace capital-intensive hardware sales in profitability. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this geosteering technology assessment. Primary interviews with drilling engineers, petrophysicists, directional drilling contractors, and oilfield procurement managers combined with bottom-up and top-down triangulation. Secondary validation drew from US EPA methane emissions documentation, Bureau of Land Management lease stipulations, and state-level oil and gas commission records.
Segment-level modeling addressed product configuration, technology sophistication, application type, and end-user category across the projection horizon. Deployment model differentiation separated cloud-based analytics subscriptions from capital hardware sales. Analytical framework derived CAGRs from telemetry density adoption curves and regulatory compliance cost trajectories. Forecast inputs incorporated EPA enforcement timeline assumptions and unconventional shale lateral well completion rates.
Revisions become necessary when semiconductor foundry capacity constraints, REACH chemical registration enforcement expansion, or OSHA drilling safety mandate updates materialize. Deviation in East Asian sensor component availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Utility Automation Market
Industrial Automation
Mining Automation Systems Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Connected Worker Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market