
 Industrial Cloud Market | 2026-2036
Industrial Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cloud Market Outlook
Multi-source cloud procurement is realigning how industrial enterprises distribute workloads across hyperscale and specialized providers. Microsoft Corporation leverages its Azure Industrial IoT stack to anchor manufacturing deployments with deep OT-IT integration. Siemens AG competes through its MindSphere platform and native automation heritage, while IBM Corporation differentiates via hybrid cloud consulting and mainframe-connected edge architectures.
Industrial cloud denotes the delivery of computing, storage, and analytics services purpose-built for operational technology environments, typically requiring sub-50ms latency guarantees and IEC 62443 cybersecurity certification to support real-time process control. Its primary commercial purpose is to virtualize SCADA, MES, and predictive maintenance systems without disrupting physical production continuity. Infrastructure as a Service dominates current spending as manufacturers retrofit brownfield plants with scalable compute, yet Platform as a Service captures expanding margin pools by embedding low-code analytics and digital twin frameworks. Hybrid Cloud deployment is accelerating fastest among energy and mining operators balancing sovereignty mandates with burst capacity needs.
FDA 21 CFR Part 11, EU Cyber Resilience Act, and China's GB/T 22239 standards collectively tighten data integrity and cross-border transfer requirements for industrial cloud vendors serving regulated sectors. These frameworks compel providers to certify region-specific instances, fragmenting architecture roadmaps and inflating compliance costs. Stakeholders must weigh captive edge investments against third-party platform dependencies as sovereignty rules harden and AI inference shifts toward plant-floor proximity.
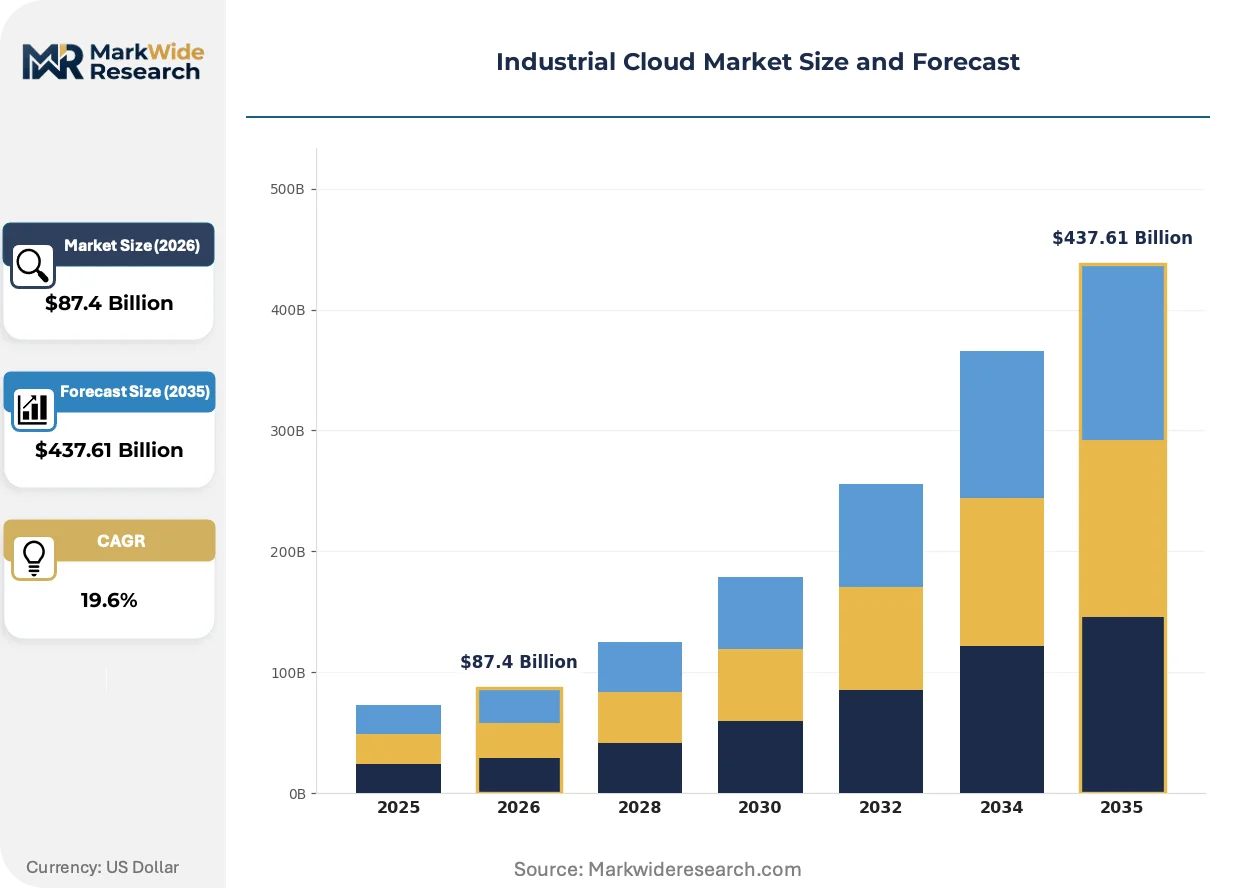
Market Dynamics
Edge-to-cloud workload orchestration is compressing latency requirements below 50 milliseconds, forcing industrial operators to re-architect data pipelines around real-time process control rather than batch analytics.
Growth Catalysts
- EU AI Act compliance mandates:Industrial data platforms must now certify algorithmic transparency for predictive maintenance systems, accelerating replacement of legacy SCADA architectures.
- Automotive battery gigafactories:Cell production lines require sub-10ms quality inspection loops that only edge-cloud hybrid stacks can deliver, pulling platform spending forward.
- Digital twin deployment:Physics-based simulation of entire plant floors demands elastic compute bursts that brownfield infrastructure cannot supply, creating IaaS pull-through.
Market Restraints
- Silicon supply concentration:Advanced edge processors for industrial gateways depend on TSMC's 7nm capacity, creating 26-week lead time volatility for automation vendors.
- IEC 62443 certification costs:Third-party security validation for multi-tenant platforms adds $400K-$800K per product line, freezing mid-tier software vendors from market entry.
- On-premise data gravity:Latency-sensitive MES workloads resist full cloud migration, capping addressable spend to hybrid architectures only.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab buildouts will create captive demand for sovereign cloud infrastructure serving electronics manufacturing clusters.
- Carbon accounting convergence:CSRD-mandated Scope 3 reporting is forcing industrial buyers to procure platforms with embedded emissions tracking, opening margin pools for analytics modules.
- 5G private networks:Ultra-reliable low-latency communication slices enable new AR-assisted maintenance applications previously impossible over Wi-Fi or public cellular.
Industry Challenges
- OT-IT skill bifurcation:Plant engineers lack cloud architecture expertise while DevOps teams misunderstand safety instrumented systems, slowing deployment timelines.
- Brownfield integration complexity:1980s-era PLC protocols require protocol gateway layers that introduce failure points and inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cloud Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $437.61 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Cloud Storage Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Manufacturing, Energy, Transportation, Mining Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, Siemens AG, ABB Ltd., Schneider Electric SE, Oracle Corporation, Alibaba Group Holding Limited, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cloud Market Strategic Shifts
Time-series database architectures are displacing relational stores for industrial telemetry, compressing query latency from seconds to milliseconds for predictive analytics workloads.
Digital twin middleware is electrifying how process manufacturers simulate heat exchanger fouling and distillation column behavior before physical commissioning. Chemical operators in Germany and the US Gulf Coast are deploying these twins at pilot scale, collapsing six-month startup schedules to eight weeks. The technology is electrifying competitive differentiation for system integrators who can bind physics engines to live SCADA feeds.
China's GB/T 22239 cybersecurity classification now mandates air-gapped backups for critical information infrastructure, including smart manufacturing platforms. This fragments cloud architecture roadmaps as providers must deploy region-specific instances with data sovereignty guarantees. Energy and mining operators in Shanxi and Inner Mongolia are accelerating hybrid deployments to satisfy these requirements while retaining burst capacity access.
Buyers are unbundling predictive maintenance contracts from capital equipment purchases, preferring subscription access to algorithmic failure detection over perpetual software licenses. This compresses vendor cash conversion cycles and shifts risk to platform providers who must guarantee uptime SLAs. The pattern is most visible among German automotive suppliers and Japanese precision equipment makers restructuring procurement frameworks.
Industrial Cloud Market Segmentation
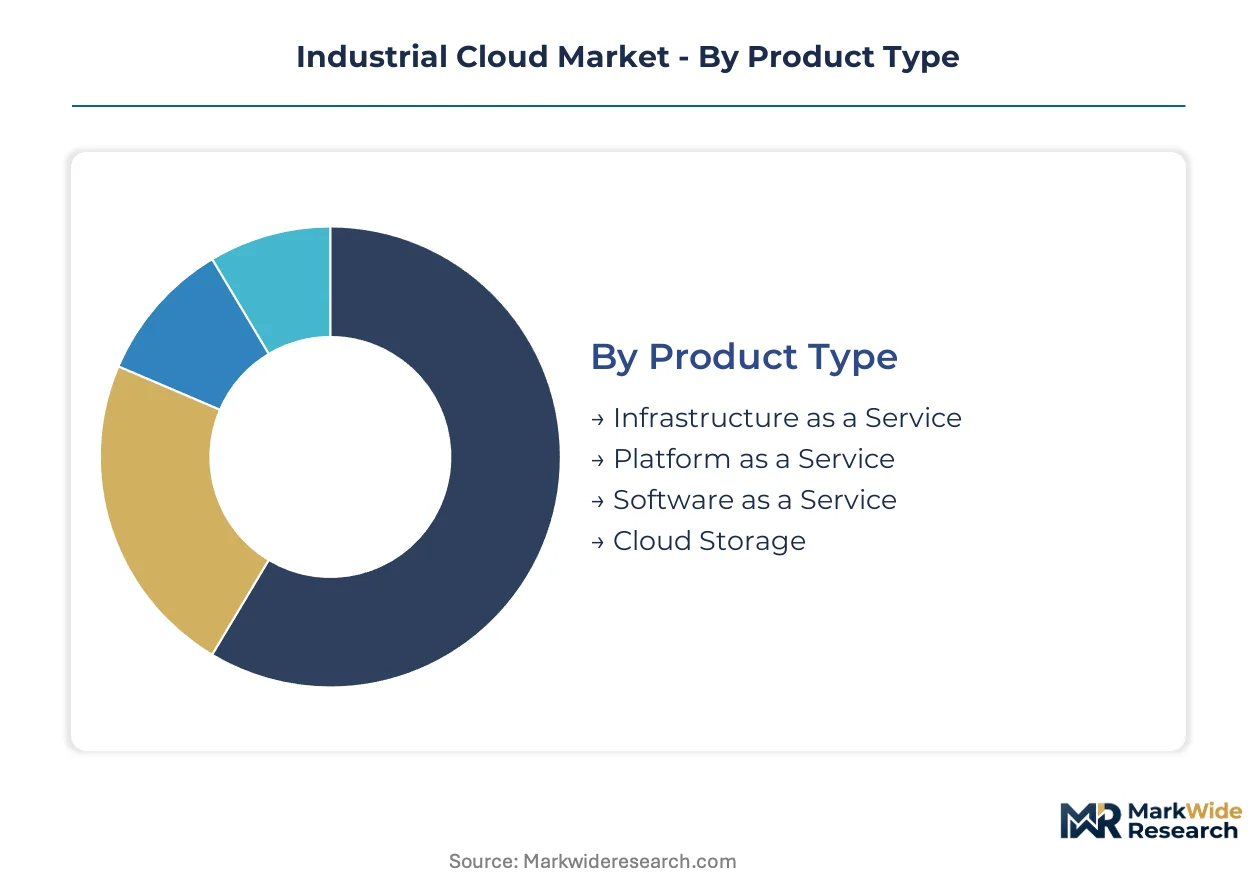
Industrial cloud procurement patterns diverge sharply between capital-intensive brownfield retrofits and greenfield smart factory builds. Understanding these splits enables vendors to align pricing architectures with customer technical maturity and compliance exposure.
Product Type:
Volume concentration sits with raw compute rental, while premium margin pools accrue to embedded analytics and middleware layers.
- Infrastructure as a Service:Bare-metal compute, storage, and networking resources delivered via hyperscale data centers with IEC 62443-certified edge nodes. German automotive suppliers and US Gulf Coast chemical operators dominate current spend as they virtualize legacy SCADA infrastructure without disrupting continuous batch processes.
- Platform as a Service:Low-code environments, digital twin frameworks, and time-series database services that abstract OT protocol complexity. Demand is concentrating among Japanese precision equipment makers and Chinese battery gigafactories seeking rapid deployment of predictive maintenance algorithms without building internal DevOps capabilities.
- Software as a Service:Subscription-based MES, quality management, and energy optimization applications delivered through multi-tenant architectures.
- Cloud Storage:Tiered object and block storage with air-gapped backup options for China's GB/T 22239 compliance requirements.
Mature deployment sits with Infrastructure as a Service. Newer deployment is concentrated in Platform as a Service.
Deployment:
Architectural choices track data sovereignty mandates and latency tolerance rather than pure cost optimization.
- Public Cloud:Shared infrastructure with burst capacity and global CDN reach, suitable for non-critical analytics and supply chain visualization workloads. European manufacturers under CSRD reporting pressure are adopting public tiers for Scope 3 emissions calculation, accepting cross-border data transfer risks for computational elasticity.
- Hybrid Cloud:Split orchestration between on-premise edge nodes and hyperscale backhaul, mandatory for sub-50ms process control loops. Energy operators in Alberta and Western Australia are accelerating these deployments to satisfy both FERC-style reliability mandates and carbon accounting convergence timelines.
- Private Cloud:Single-tenant infrastructure with dedicated physical isolation for regulated pharmaceutical and defense manufacturing.
- Multi-Cloud:Workload distribution across competing hyperscalers to mitigate vendor lock-in and negotiate pricing leverage.
Established configurations favor Hybrid Cloud. Expanding most quickly are Multi-Cloud strategies among risk-averse industrial conglomerates.
End User:
Application intensity varies with asset criticality and downtime cost exposure across physical production environments.
- Manufacturing:Discrete and process production facilities deploying edge-to-cloud architectures for digital twin and predictive quality applications. German machine builders and South Korean electronics assemblers anchor this segment, driven by EU AI Act algorithmic transparency requirements and automotive battery gigafactory buildouts.
- Energy:Upstream extraction, midstream transport, and downstream refining operations balancing sovereign data mandates with burst simulation capacity. Operators in Norway's North Sea and Texas Permian Basin are pioneering these architectures for reservoir modeling and pipeline integrity monitoring.
- Transportation:Rail, maritime, and logistics hubs requiring mobile edge connectivity and intermittent synchronization.
- Mining:Remote pit operations with limited terrestrial connectivity and extreme environmental durability requirements.
Deep operational integration characterizes Manufacturing. Steepest expansion trajectory is visible in Energy as carbon accounting mandates tighten.
Service Type:
Revenue mix shifts from project-based implementation toward recurring managed services as industrial buyers internalize cloud operational complexity.
- Consulting:OT-IT convergence strategy, cloud architecture design, and regulatory compliance roadmap development. US-based system integrators and German automation specialists capture premium pricing for brownfield migration planning that addresses 1980s-era PLC protocol gateway requirements.
- Integration:Protocol translation layer deployment, SCADA-MES-cloud data pipeline construction, and cybersecurity hardening. Indian IT services firms are expanding these practices to serve domestic electronics manufacturing clusters benefiting from PLI scheme incentives.
- Support:24/7 operational assistance with guaranteed response SLAs for production-critical workloads.
- Maintenance:Patch management, version upgrades, and infrastructure lifecycle refresh services.
Contracted revenue concentrates in Consulting. Subscription conversion is advancing fastest in Support as uptime SLA guarantees become standard procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors the hardware substrate for industrial cloud deployments, while data center buildouts concentrate in jurisdictions with favorable power pricing and regulatory clarity.
United States
Automotive battery gigafactories in Michigan and Tennessee are pulling edge-cloud hybrid investments for sub-10ms quality inspection loops. FERC reliability mandates and EPA emissions reporting requirements are tightening procurement criteria for energy sector platforms. Texas Permian Basin operators are deploying reservoir modeling workloads that balance sovereign data controls with burst compute access.
Germany
Machine builders in Bavaria and Baden-Württemberg are retrofitting brownfield plants with IEC 62443-certified infrastructure. EU AI Act algorithmic transparency rules are accelerating replacement of legacy SCADA architectures across automotive supplier networks. Chemical operators on the US Gulf Coast and in Germany's Ruhr region are piloting digital twin deployments that collapse commissioning schedules from months to weeks.
China
Battery cell production lines in Fujian and Jiangsu are driving demand for edge-to-cloud stacks with sub-50ms latency guarantees. GB/T 22239 cybersecurity classifications mandate air-gapped backups for critical manufacturing platforms. Smart factory deployments in Shanxi and Inner Mongolia are accelerating hybrid cloud adoption to satisfy data sovereignty requirements while retaining elastic capacity.
India
Electronics manufacturing clusters in Karnataka and Tamil Nadu are expanding under PLI scheme incentives, creating captive demand for sovereign cloud infrastructure. BIS certification requirements for industrial IoT devices are reshaping vendor qualification criteria. System integrators in Hyderabad and Bengaluru are building protocol translation practices to serve brownfield retrofit demand.
Japan
Precision equipment makers in Nagoya and Osaka are restructuring procurement frameworks toward subscription-based predictive maintenance access. METI industrial data space initiatives are promoting interoperability standards for cross-factory analytics. Automotive suppliers in Toyota City are deploying time-series database architectures to compress query latency for quality optimization workloads.
Industrial Cloud Market Competitive Environment
Global majors compete with regional champions across deployment scale and regulatory certification depth. The vendor base separates into hyperscale cloud providers with industrial IoT stacks, automation heritage companies with native OT integration, and consulting-led systems integrators bridging brownfield complexity. Three archetypes dominate: infrastructure-centric platforms, OT-native middleware specialists, and hybrid cloud advisors. Competitive moves concentrate on strategic partnerships between semiconductor vendors and cloud operators, plus vertical capability acquisitions to deepen OT protocol expertise.
Within the hyperscale infrastructure tier, Microsoft Corporation and Amazon Web Services, Inc. occupy positions defined by global data center footprint and manufacturing-specific service catalogs. Siemens AG anchors the OT-native archetype through its automation heritage and plant-floor protocol depth. IBM Corporation sits within the consulting-led segment, exemplifying the hybrid cloud advisory model that addresses mainframe-connected edge architectures for regulated industries.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Oracle Corporation |
| Alibaba Group Holding Limited |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
German automotive suppliers and Japanese precision equipment makers concentrate procurement power in the industrial cloud market, driving subscription-based pricing models that unbundle predictive maintenance from capital equipment purchases. This buyer concentration compresses vendor cash conversion cycles and shifts uptime risk to platform providers.
Pricing Analysis
Warranty and service bundling separates premium-tier industrial cloud contracts from standard offerings, with IEC 62443-certified platforms commanding sustained premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and SLA guarantees rather than raw compute capacity. Pricing pressure stems from mid-tier software vendors freezing at market entry due to validation cost burdens, while hyperscale providers absorb certification overhead through volume. German machine builders exhibit lowest price sensitivity due to downtime cost exposure, whereas Indian electronics manufacturing clusters under PLI scheme incentives prioritize cost minimization over feature depth.
Supply Chain Analysis
Dual-sourcing requirements for advanced edge processors mandate qualification of both TSMC-fabricated and Samsung-foundry alternatives, though 7nm capacity concentration in Taiwan creates persistent qualification gaps. The hardware substrate draws from Taiwan, South Korea, and United States fabrication networks, while industrial gateway assembly rests on China, Mexico, and Germany manufacturing footprints. Single-source vulnerability in TSMC's leading-edge node capacity generates 26-week lead time volatility for automation vendors. Distribution runs through direct OEM partnerships and systems integrator channels, with Indian IT services firms expanding protocol translation practices to serve domestic electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial cloud market functions as a vertical-integration race where control over edge processor supply and OT protocol stacks determines margin capture. Players are pursuing backward integration into semiconductor sourcing and captive automation heritage assets.
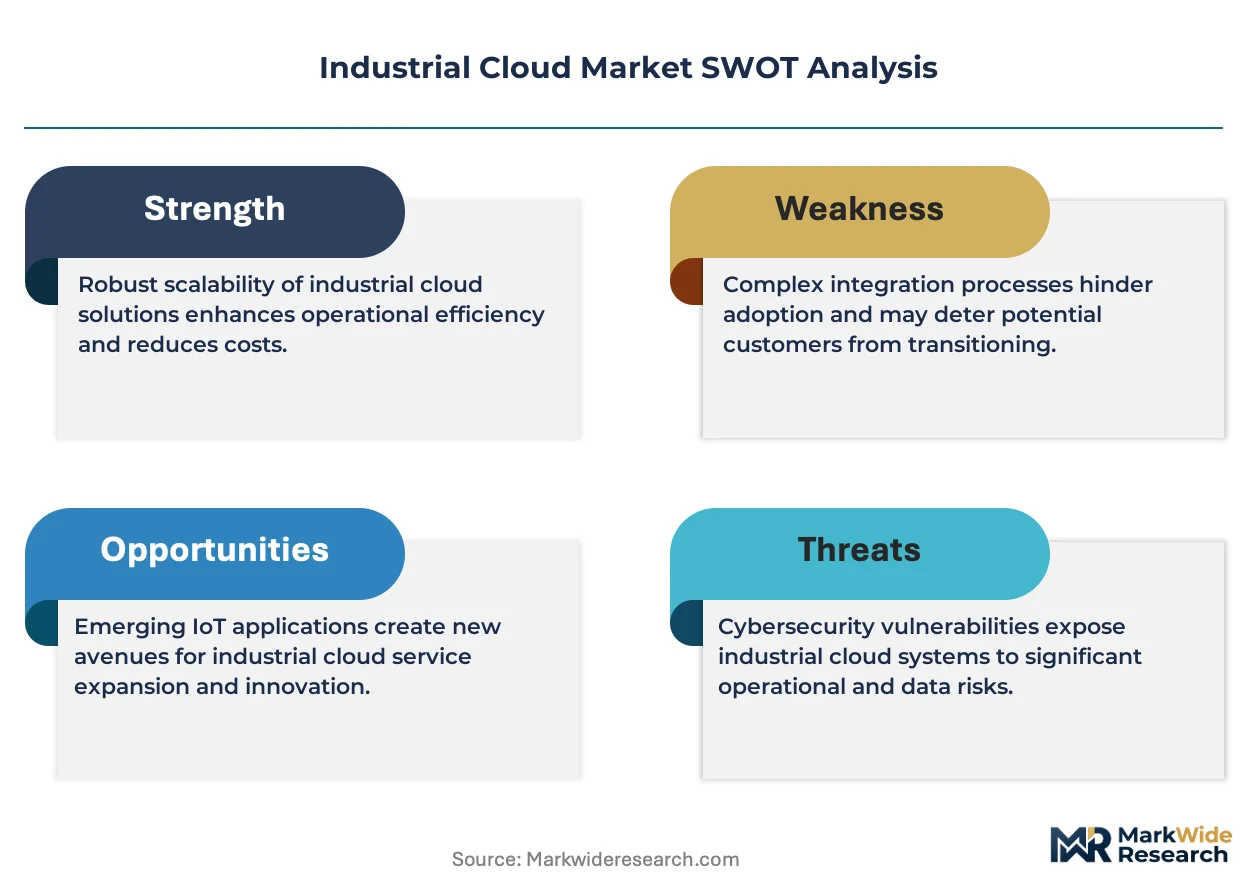
For Market Incumbents: Acquire edge processor supply agreements to secure allocation priority during foundry capacity constraints. Hyperscale cloud providers face displacement risk from OT-native platforms with deeper plant-floor protocol expertise. Incumbents should consolidate automation heritage assets that embed native SCADA-MES integration capabilities, locking in brownfield retrofit demand through protocol gateway control. For New Entrants and Emerging Players: Begin with India's electronics manufacturing clusters under PLI scheme expansion, where sovereign cloud infrastructure demand outpaces qualified vendor supply. White-space concentration sits in protocol translation services for 1980s-era PLC brownfield environments. Target carbon accounting convergence as entry wedge, embedding emissions tracking modules that satisfy CSRD-mandated Scope 3 reporting for European industrial buyers. For Investors and Strategic Acquirers: The window for entry favors OT-native middleware specialists with IEC 62443 certification depth and established German automotive supplier relationships. Long-term viability hinges on positioning ahead of EU AI Act algorithmic transparency enforcement waves. Watch for inflection in 5G private network deployment velocity as signal for AR-assisted maintenance application readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure Industrial IoT stack anchors manufacturing deployments through deep OT-IT convergence. |
| Acquisition of Specialist Firm | Siemens AG consolidates automation heritage assets to defend MindSphere's native protocol advantage. |
| Strategic Partnership | IBM Corporation bridges mainframe-connected edge architectures for regulated pharmaceutical manufacturing. |
| Geographic Expansion | Indian IT services firms build protocol translation practices for PLI-scheme electronics clusters. |
| Product Launch | Time-series database architectures displace relational stores for predictive analytics workload compression. |
Study Parameters
Multi-period observation of hyperscaler capex disclosures, IEC 62443 certification timelines, and edge processor lead time volatility anchored the trend analysis, supplemented by interviews with plant engineers, OT-IT convergence specialists, cloud procurement officers at German automotive suppliers, and systems integrators serving brownfield retrofit demand. Secondary validation drew from SEC 10-K filings, EU AI Act implementation guidance, China's GB/T 22239 cybersecurity classifications, and customs data on industrial gateway imports. Bottom-up and top-down triangulation reconciled vendor shipment data with end-user procurement surveys.
Segment-weighting across deployment models, end-user verticals, and regional regulatory clusters shaped the analytical framework over the projection horizon. The model incorporated platform adoption curves for manufacturing, energy, and mining verticals alongside compliance cost trajectories for EU AI Act and ISO 27001 frameworks. CAGRs were derived from elasticity-adjusted demand curves and substitution dynamics between IaaS and PaaS tiers.
Underlying measurement precision varies by segment; hybrid cloud deployment data carries tighter precision than multi-cloud strategies due to definitional ambiguity in workload distribution reporting. Forecasts reflect assumptions on foundry capacity expansion, regulatory enforcement timing, and OT-IT skill convergence rates. A model refresh is warranted upon material change in TSMC's 7nm allocation policy or EU AI Act algorithmic transparency certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Calling Market
Cloud Computing
VM Service Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market