
 Conveyor Sorting Systems Market | 2026-2036
Conveyor Sorting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Sorting Systems Market Outlook
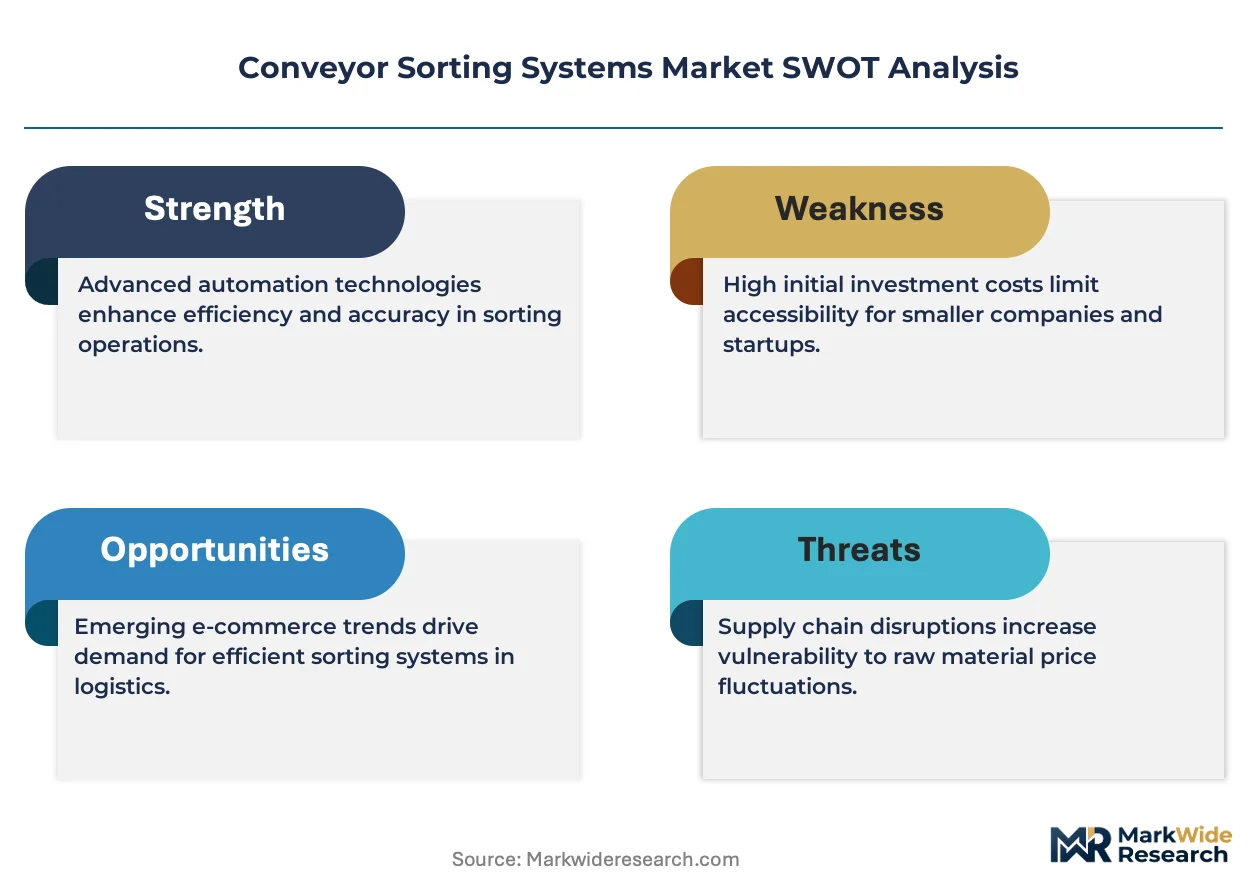
The capital-intensity divergence between players is bifurcating the competitive landscape into turnkey integrators and component specialists. Daifuku Co. Ltd. leverages its vertical manufacturing base in Japan to control core sorter mechanics and reduce procurement risk. SSI Schaefer AG anchors its position through dense European warehouse automation deployments, while Honeywell Intelligrated competes on software-integrated controls for North American distribution networks.
Conveyor sorting systems are material-handling installations that use linear, modular, tilt-tray, or cross-belt architectures to direct items to predetermined destinations based on barcode, weight, or optical recognition parameters, typically operating at speeds exceeding two meters per second in high-throughput environments. Their primary purpose is to replace manual sortation with repeatable, traceable material flows in facilities processing thousands of items hourly. Cross-belt sorters now capture premium margin pools in parcel and postal applications where gentle handling and bidirectional discharge justify higher capital outlays, while modular conveyor configurations lead installation volumes by allowing phased warehouse expansions without full system shutdowns.
The EU Machinery Directive and CE marking framework mandate functional safety validation and risk assessments for automated sortation equipment sold across member states, elevating compliance costs for non-European suppliers. In the United States, OSHA lockout/tagout standards and FCC electromagnetic compatibility rules shape control panel design and wireless sensor integration. Stakeholders must monitor how evolving battery-electric vehicle plant layouts in automotive manufacturing reshape conveyor footprint requirements and throughput specifications.
Market Dynamics
E-commerce fulfillment networks are compressing order cycle times to same-day and next-day delivery windows, forcing warehouse operators to replace batch-based manual sortation with continuous-flow automated architectures capable of processing 15,000-25,000 parcels per hour.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for functional safety validation are accelerating replacement cycles of legacy equipment across German, French, and Italian distribution hubs.
- Cross-belt sorter technology maturation:Bidirectional discharge capabilities and gentle handling profiles are capturing premium applications in pharmaceutical and electronics fulfillment where damage rates must stay below 0.1 percent.
- Automotive battery-electric vehicle plant expansion:New assembly layouts in Germany and the United States require reconfigurable conveyor footprints that adapt to modular skateboard chassis production.
Market Restraints
- Steel and aluminum input cost volatility:Frame fabrication and modular track components face margin compression when commodity prices spike, particularly affecting mid-tier system integrators without captive metalworking capacity.
- Control system semiconductor supply concentration:PLC and servo drive sourcing remains concentrated among East Asian foundries, exposing European and North American integrators to 20-30 week lead time extensions.
- High-voltage cross-belt sorter energy density limits:Power consumption thresholds in existing facilities constrain throughput upgrades without electrical infrastructure overhaul.
Strategic Opportunities
- India warehouse automation underpenetration:Third-party logistics providers in Mumbai and Bangalore are initiating first-phase sortation deployments as GST compliance drives inventory centralization.
- AI Act compliance services:European integrators can bundle CE marking documentation with machine-learning-based barcode recognition validation to capture compliance-adjacent revenue streams.
- Autonomous mobile robot convergence:Tetherless AMR fleets feeding fixed sorter induction points are creating hybrid architectures that reduce fixed conveyor footprint by 30-40 percent in greenfield facilities.
Industry Challenges
- Mechatronics technician scarcity:Integration of servo drives, pneumatic diverters, and vision systems requires cross-trained maintenance staff that German and Japanese automotive clusters compete aggressively to retain.
- Legacy WMS integration complexity:Brownfield deployments must reconcile 1990s-era warehouse management protocols with OPC-UA and MQTT data standards, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Sorting Systems Market |
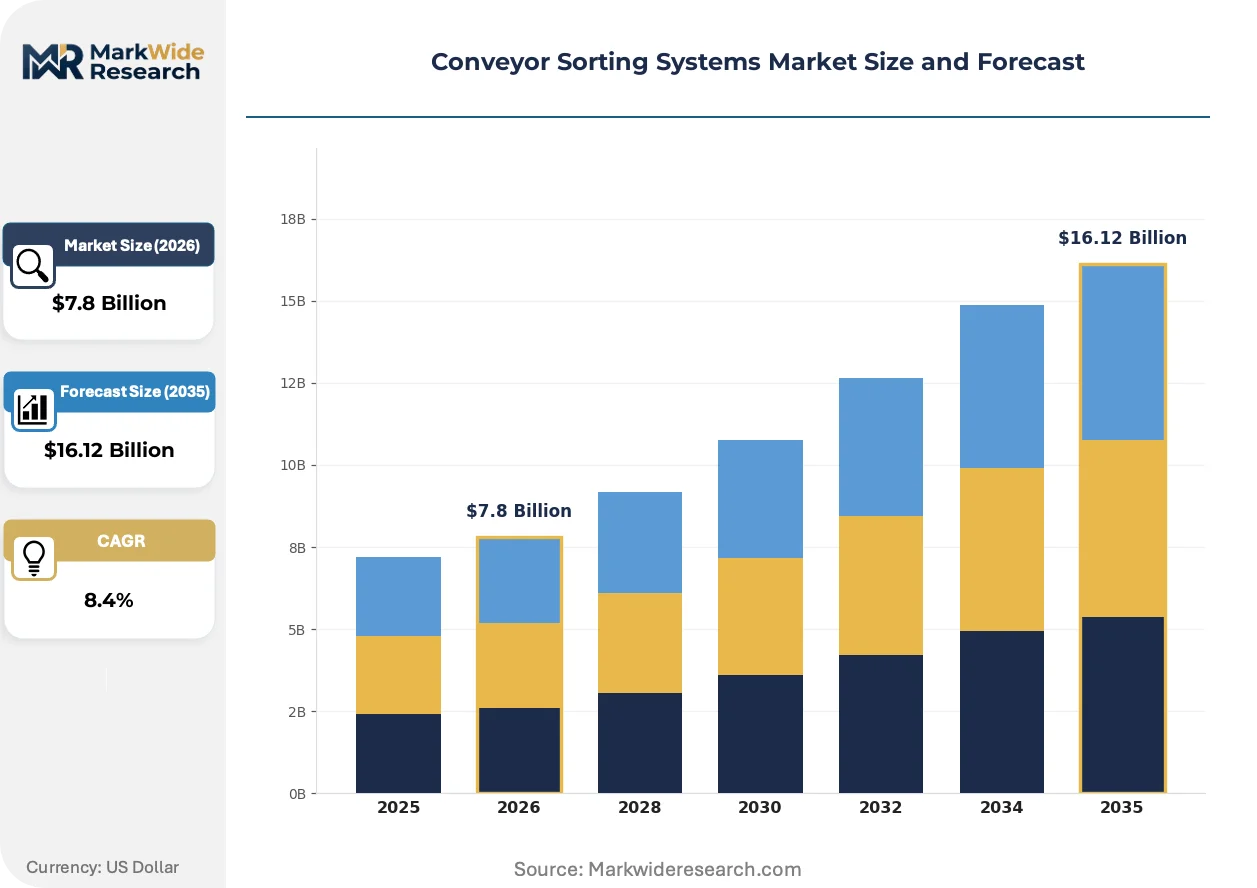
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Conveyor, Modular Conveyor, Tilt-tray Sorter, Cross-belt Sorter Technology: Pneumatic, Electric, Mechanical, Optical End User: Retail, E-commerce, Manufacturing, Warehousing Installation: On-site, Pre-assembled, Modular, Customizable |
| Companies Covered | Bastian Solutions, Beumer Group, Daifuku Co. Ltd., Honeywell Intelligrated, Dematic, Vanderlande, SSI Schaefer AG, Siemens Logistics, Fives Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Sorting Systems Market Strategic Shifts
Sensor fusion and edge computing architectures are compressing decision latency in sortation systems from 50 milliseconds to under 10 milliseconds, enabling real-time rerouting based on dynamic downstream capacity.
Modular linear induction motor technology is bifurcating the mid-market segment. Parcel carriers in the Netherlands and South Korea are deploying these contactless drive systems to eliminate mechanical wear points and extend maintenance intervals beyond 50,000 operating hours. The technology is bifurcating procurement patterns between operators prioritizing total cost of ownership over initial capital expenditure.
OSHA lockout/tagout standard revisions are tightening control panel access protocols for automated material handling equipment. Distribution centers in California and Texas are retrofitting existing installations with RFID-enabled energy isolation verification. Food and beverage cold chain facilities face the steepest compliance costs due to frequent sanitation cycles requiring repeated lockout procedures.
Outcome-based maintenance contracts are displacing time-based service agreements among North American third-party logistics providers. Carrier networks now pay per successfully sorted parcel rather than fixed annual fees, transferring operational risk to equipment vendors. This model concentrates fastest in parcel hubs processing over 100,000 units daily where downtime costs exceed $10,000 per hour.
Conveyor Sorting Systems Market Segmentation
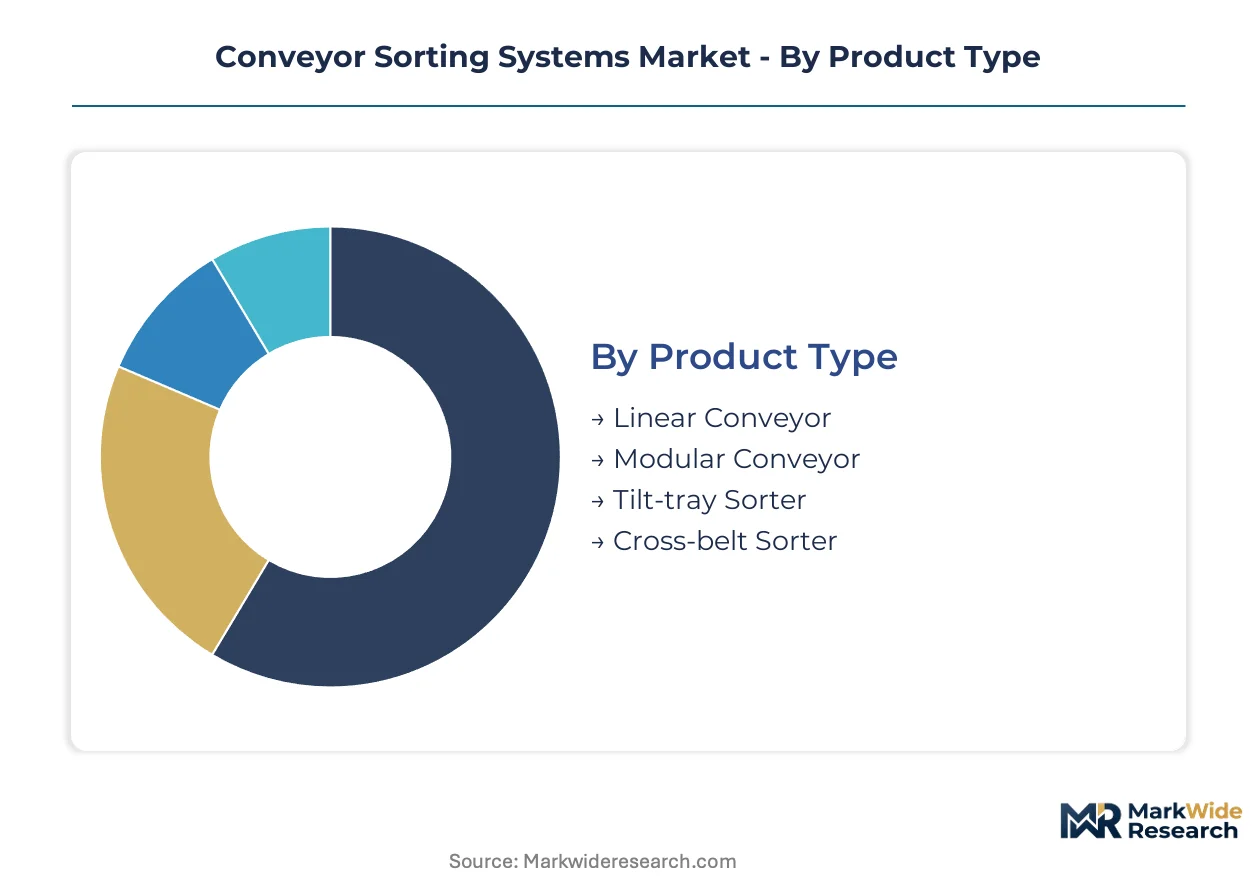
Conveyor sorting system procurement patterns diverge sharply across product architectures, with capital intensity and throughput requirements driving distinct buyer behaviors. Segment selection directly determines facility footprint, energy consumption profiles, and integration complexity with upstream automation layers.
Product Type:
Linear conveyor configurations face the strongest substitution pressure from autonomous mobile robot induction systems, while cross-belt sorters defend their position through irreplaceable gentle-handling performance in high-value parcel streams.
- Linear Conveyor:Belt-driven continuous transport systems operate at fixed speeds with minimal mechanical complexity, serving as induction feeders and accumulation buffers. Demand concentrates in German automotive supplier parks where just-in-sequence delivery mandates predictable material flow timing.
- Modular Conveyor:Reconfigurable track segments enable phased warehouse expansion without operational shutdown. E-commerce fulfillment centers in the Netherlands deploy these architectures to accommodate seasonal volume spikes while preserving capital deployment flexibility.
- Tilt-tray Sorter:Pivoting carrier mechanisms discharge items at angled chutes. Postal operators in France leverage this technology for mixed-mail processing where item geometry varies significantly.
- Cross-belt Sorter:Dual-belt carrier cells enable bidirectional discharge and minimal contact handling. Pharmaceutical distribution hubs in Switzerland specify these systems to maintain damage rates below 0.1 percent for temperature-sensitive biologics.
Linear conveyor retains volume leadership; cross-belt sorter holds the steepest expansion curve.
Technology:
Technology selection maps directly to facility energy infrastructure and maintenance staffing capabilities, with electric drive systems commanding premium positioning in greenfield European deployments.
- Pneumatic:Compressed-air actuation powers diverter arms and pushers in legacy installations. Food and beverage cold chain facilities in Italy retain this technology for explosion-proof compliance in refrigerated zones.
- Electric:Servo motor precision enables variable speed control and regenerative braking. Battery-electric vehicle plants in Germany specify electric drives to align with corporate carbon neutrality commitments.
- Mechanical:Cam-driven and gravity-based mechanisms minimize control system dependency. Southeast Asian textile exporters favor this approach where technical support infrastructure remains limited.
- Optical:Camera arrays and laser triangulation enable dimensioning and defect detection at conveyor speeds exceeding two meters per second. Electronics fulfillment centers in South Korea integrate optical layers for real-time quality verification.
Electric technology captures the margin premium; optical integration is expanding most quickly.
End User:
End-user verticals exhibit divergent throughput requirements and damage tolerance thresholds, with e-commerce operators driving the fastest specification evolution toward continuous-flow architectures.
- Retail:Store replenishment and returns processing dominate applications. Fashion distributors in Spain deploy sortation to consolidate fragmented supplier shipments into store-ready assortments.
- E-commerce:Same-day delivery windows mandate parcel processing rates of 15,000-25,000 units hourly. Third-party logistics providers in India initiate first-phase automation as GST compliance drives inventory centralization.
- Manufacturing:Work-in-progress tracking and finished goods consolidation shape requirements. Automotive battery pack assembly lines in the United States require reconfigurable footprints for evolving skateboard chassis designs.
- Warehousing:Cross-dock operations and inventory put-away drive demand. Distribution centers in Texas prioritize modular installations to accommodate SKU proliferation without facility expansion.
E-commerce commands the steepest technology upgrade cycle; manufacturing retains the longest replacement intervals.
Installation:
Installation modality selection reflects facility lifecycle stage and operational continuity requirements, with pre-assembled systems gaining traction in constrained urban logistics sites.
- On-site:Component-level delivery and field assembly accommodate irregular building geometries. Brownfield retrofits in France adopt this approach to navigate heritage structure limitations.
- Pre-assembled:Factory-integrated modules reduce commissioning timelines and site labor requirements. Urban parcel hubs in Japan specify pre-assembled cells to minimize disruption in dense industrial zones.
- Modular:Standardized plug-and-play sections enable capacity expansion in operational facilities. Cold storage operators in Canada deploy modular architectures to isolate maintenance zones from temperature-controlled areas.
- Customizable:Application-specific engineering addresses unique material handling challenges. Aerospace component manufacturers in Germany commission customized systems for oversized and irregularly shaped airframe sections.
Modular installation retains volume leadership; pre-assembled delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in automated material handling equipment are reshaping regional deployment patterns, with manufacturing hubs in Asia supplying European and North American fulfillment networks while importing specialized control systems from Germany and Japan.
United States
E-commerce fulfillment centers in Texas and California are driving cross-belt sorter installations to meet same-day delivery mandates. OSHA lockout/tagout standard revisions are forcing retrofits of existing control panels with RFID-enabled energy isolation. The Dallas-Fort Worth metroplex anchors the densest concentration of third-party logistics automation deployments.
Germany
Automotive battery-electric vehicle plants in Bavaria and Baden-Württemberg require reconfigurable conveyor footprints for modular skateboard chassis production. The EU Machinery Directive and CE marking requirements are accelerating replacement cycles of legacy equipment in distribution hubs. The Stuttgart logistics cluster leads European adoption of linear induction motor technology for maintenance interval extension.
China
Domestic e-commerce operators in the Yangtze River Delta are scaling automated sortation to handle surging parcel volumes from live-streaming commerce. GB standards and MIIT industrial automation directives shape local equipment certification pathways. The Shanghai-Suzhou corridor concentrates the highest density of tilt-tray sorter manufacturing capacity serving Southeast Asian export markets.
Japan
Urban parcel hubs in Tokyo and Osaka specify pre-assembled modular systems to minimize disruption in dense industrial zones. METI energy efficiency regulations are pushing adoption of regenerative braking electric drives. The Nagoya automotive supplier belt maintains demand for linear conveyor configurations serving just-in-sequence delivery mandates.
India
Third-party logistics providers in Mumbai and Bangalore are initiating first-phase sortation deployments as GST compliance drives inventory centralization. BIS certification requirements for industrial machinery are elevating compliance costs for imported equipment. The Delhi-NCR warehousing corridor is attracting modular conveyor installations from cold chain operators expanding pharmaceutical distribution capacity.
Conveyor Sorting Systems Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized material handling integrators competing across technology tiers. The vendor base separates into turnkey system providers delivering end-to-end warehouse automation and component specialists supplying modular track segments and control subsystems. Strategic moves center on backward integration into servo drive manufacturing and geographic expansion through local assembly partnerships in high-growth Asian markets.
Among Japanese and German industrial groups, Daifuku Co. Ltd. and SSI Schaefer AG occupy positions reflecting contrasting geographic anchoring strategies, while Honeywell Intelligrated represents the North American software-integrated controls archetype. These three exemplify how competitive positioning diverges between vertical manufacturing depth and regional deployment density.
| Leading Market Players |
|---|
| Bastian Solutions |
| Beumer Group |
| Daifuku Co. Ltd. |
| Honeywell Intelligrated |
| Dematic |
| Vanderlande |
| SSI Schaefer AG |
| Siemens Logistics |
| Fives Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese and German sorter manufacturing bases creates scale economies that compress unit costs for cross-belt and modular architectures while elevating price floors for smaller integrators lacking captive metalworking. This concentration feeds into procurement patterns where automotive OEMs and e-commerce operators command volume discounts that mid-tier third-party logistics providers cannot replicate.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures where three-tier pricing separates CE-certified premium systems from standard modular configurations and economy-grade mechanical alternatives. Price differentiation rests on certification tier and after-sales service bundling, with CE-marked European installations commanding premiums over OSHA-compliant North American equivalents. Cost compression in the economy tier is intensifying because Southeast Asian textile exporters prioritize capital expenditure minimization over total cost of ownership. E-commerce fulfillment operators exhibit the lowest price sensitivity due to downtime costs exceeding operational thresholds, while cold chain food and beverage distributors face the steepest budget constraints.
Supply Chain Analysis
Strategic stockpiling of servo drives and PLC modules dominates inventory strategy among European integrators exposed to East Asian semiconductor sourcing delays, while just-in-time steel and aluminum procurement persists for frame fabrication at German automotive supplier parks. Geographic supply concentration centers on China for tilt-tray sorter manufacturing, Japan for precision servo components, and Germany for control system engineering. Raw material dependencies draw from steel coil, aluminum extrusion, and rare-earth magnet feeds. Single-source vulnerability in East Asian foundry capacity for motion control semiconductors represents the dominant structural risk. Distribution runs through direct OEM relationships for large turnkey projects and regional integrator networks for modular component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conveyor sorting systems constitute a defensive-moat market where regulatory entrenchment through CE marking and OSHA compliance creates sticky relationships that resist supplier switching. The installed base of validated safety architectures generates recurring aftermarket revenue streams that new entrants struggle to penetrate.
For Market Incumbents: Shield market position by deepening backward integration into servo drive manufacturing to reduce East Asian foundry dependency, while accelerating CE marking documentation services to capture compliance-adjacent revenue from EU Machinery Directive mandates. Autonomous mobile robot substitution threats in greenfield facilities require hybrid architecture development that preserves fixed sorter relevance.
For New Entrants and Emerging Players: CE marking fast-track services for brownfield retrofit applications open immediate revenue windows in French and Italian distribution hubs burdened by legacy equipment replacement cycles. India's underpenetrated third-party logistics sector offers the most penetrable geography, with Mumbai and Bangalore warehouse automation initiations creating first-mover positioning. A software-integrated controls go-to-market angle bypasses capital-intensive mechanical manufacturing barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive control system IP over pure-play integrators vulnerable to margin compression. Long-term viability over the projection horizon rests on servo drive and edge computing software assets rather than mechanical track manufacturing. Acquisition targets should display dense regional deployment footprints in Germany or Japan. The signal to watch is AMR-to-sorter convergence adoption rates in greenfield e-commerce facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drives | Reduces 20-30 week lead time exposure from East Asian semiconductor foundries. |
| CE Marking Documentation Services | Captures compliance-adjacent revenue from EU Machinery Directive replacement cycles. |
| Hybrid AMR-Sorter Architecture Development | Preserves fixed conveyor relevance against tetherless mobile robot substitution. |
| India Local Assembly Partnership | Navigates BIS certification costs for GST-driven warehouse automation demand. |
| Outcome-Based Maintenance Contracts | Transfers operational risk to vendors in parcel hubs processing 100,000+ units daily. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM procurement disclosures. Primary interviews engaged warehouse automation directors, mechatronics maintenance heads, OEM procurement teams, and aftermarket service managers across German automotive clusters and North American e-commerce fulfillment networks. Secondary validation drew from EU Machinery Directive documentation, OSHA standard revisions, SEC equipment supplier filings, and industrial automation trade association reports. Bottom-up installation data triangulates against top-down market sizing across product architectures and end-use verticals.
Segmentation dimensions modeled span product type, drive technology, end-user vertical, and installation modality across the analysis window. The quantitative framework projects volume and value outputs through unit economics analysis of cross-belt, tilt-tray, linear, and modular configurations. CAGRs derive from replacement cycle timing, greenfield automation penetration, and technology substitution curves. Forecast inputs incorporate automotive battery-electric vehicle plant layout evolution and e-commerce same-day delivery mandate compression.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply normalization or abrupt commodity price spikes would require recalibration. Forecasts reflect assumptions regarding EU regulatory enforcement continuity and North American e-commerce capital expenditure trajectories. Revision becomes warranted when AMR-to-sorter convergence adoption crosses critical thresholds in greenfield facility design.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Global SCADA Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Intralogistics Market
Industrial Automation
Pick and Place Machines Market