
 Middle East and Africa Process Automation Market | 2026-2036
Middle East and Africa Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Process Automation Market Foresight
Aftermarket service revenue is fragmenting across the Middle East and Africa as end-users seek localized support contracts and predictive maintenance subscriptions rather than bundled OEM agreements. Siemens AG anchors its regional position through an extensive service network spanning Saudi Arabia and the UAE. Honeywell International Inc. competes by leveraging its installed base in oil and gas refineries to extend lifecycle service engagements. ABB Ltd differentiates through specialized marine and offshore automation support capabilities concentrated in Qatar and Oman.
Process automation encompasses the use of control systems, instrumentation, and software algorithms to monitor and regulate industrial operations with minimal human intervention, typically achieving response times measured in milliseconds for safety-critical loops. Its primary purpose centers on optimizing throughput, ensuring regulatory compliance, and protecting capital-intensive assets across continuous and batch process industries. Hardware components, including distributed control systems and field instrumentation, currently command the largest share of regional procurement budgets due to greenfield refinery and desalination investments. Services, particularly system integration and commissioning support, represent the fastest-expanding segment as local workforce development initiatives in Saudi Arabia and the UAE reduce reliance on expatriate engineering teams.
Saudi Arabia's Standards, Metrology and Quality Organization (SASO) mandates IEC 61511 compliance for safety instrumented systems in hydrocarbon processing, directly shaping vendor product certification requirements and procurement specifications. The UAE's Emirates Authority for Standardization and Metrology (ESMA) enforces conformity assessment protocols for electrical equipment deployed in hazardous area classifications, creating market access barriers for uncertified suppliers. Stakeholders must monitor evolving local content regulations across Gulf Cooperation Council member states, as procurement preferences for domestically sourced automation engineering increasingly influence contract award decisions in government-linked industrial projects.
Market Dynamics
Saudi Arabia's localization mandates under the Saudi Authority for Industrial Cities and Technology Zones are forcing foreign automation vendors to transfer engineering capabilities to domestic joint ventures, fundamentally restructuring how control systems are procured across Gulf hydrocarbon projects.
Growth Catalysts
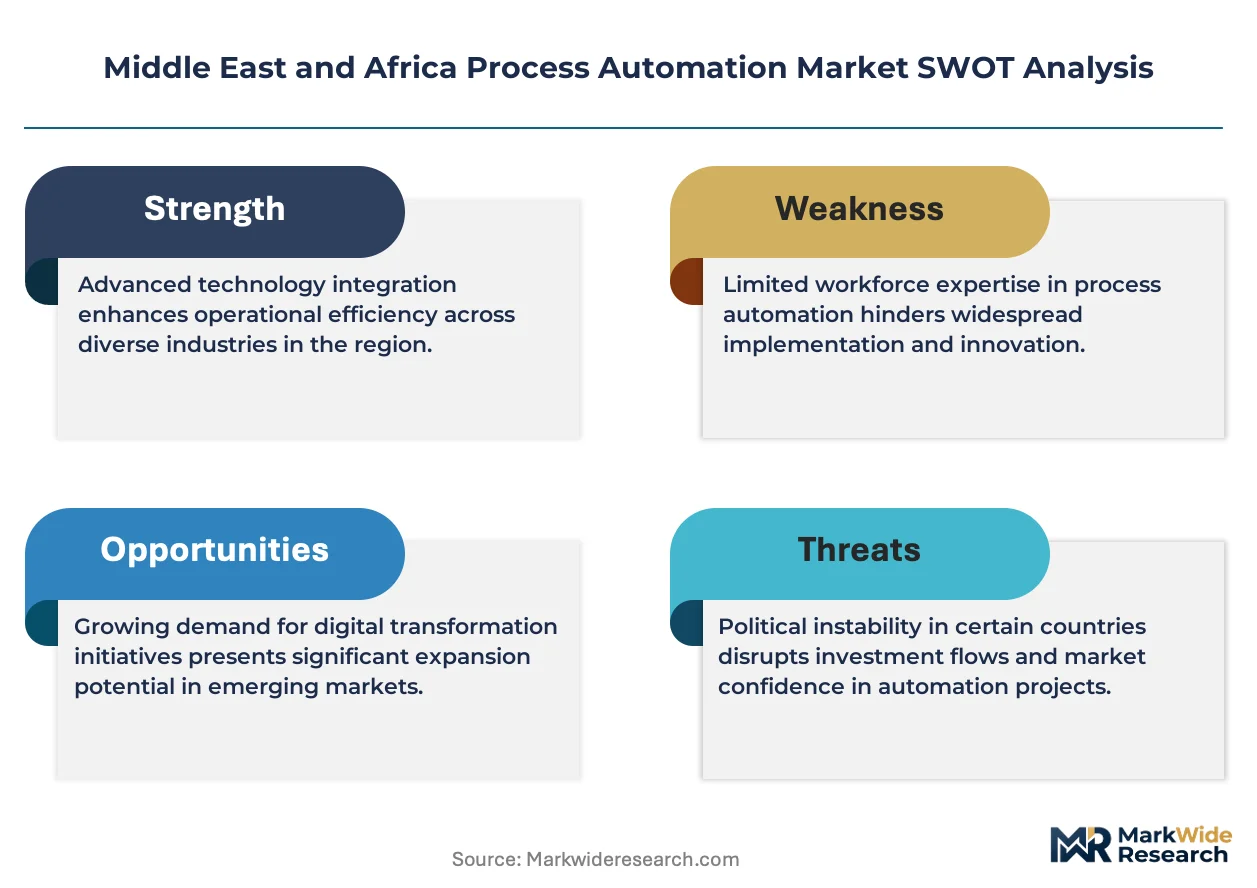
- IEC 61511 Compliance Mandates:SASO's safety instrumented system requirements in Saudi Arabia are accelerating replacement cycles for legacy protection layers in refinery expansions.
- Upstream Throughput Optimization:Oil and gas operators across Kuwait and Qatar are deploying advanced process control to maximize output from mature offshore fields.
- Smart Manufacturing Initiatives:Dubai's Industrial Strategy 2030 is channeling automation investment into food processing and pharmaceutical batch operations.
Market Restraints
- Engineering Talent Scarcity:Reliance on expatriate commissioning specialists inflates project timelines and service costs across Oman and Bahrain.
- Certification Fragmentation:Divergent hazardous area standards between ESMA in the UAE and SASO in Saudi Arabia force dual product testing regimes.
- Capital Intensity of Brownfield Retrofit:Legacy DCS architectures in Egyptian fertilizer plants require complete I/O subsystem replacement rather than modular upgrade.
Strategic Opportunities
- Predictive Maintenance Subscriptions:Unbundled service models are displacing bundled OEM agreements as Nigerian petrochemical operators seek localized support.
- Desalination Automation:Reverse osmosis membrane monitoring systems represent underpenetrated demand in Jordan and Morocco water infrastructure.
- Marine and Offshore Specialization:Qatar's North Field expansion is creating specialized automation requirements for LNG loading and floating production storage.
Industry Challenges
- Cybersecurity Certification Delays:IEC 62443 compliance timelines for control system networks are extending project handover dates in Abu Dhabi industrial free zones.
- Intergenerational System Integration:Proprietary legacy protocols in 1990s-era Saudi refineries obstruct seamless data exchange with modern analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Process Automation Market |
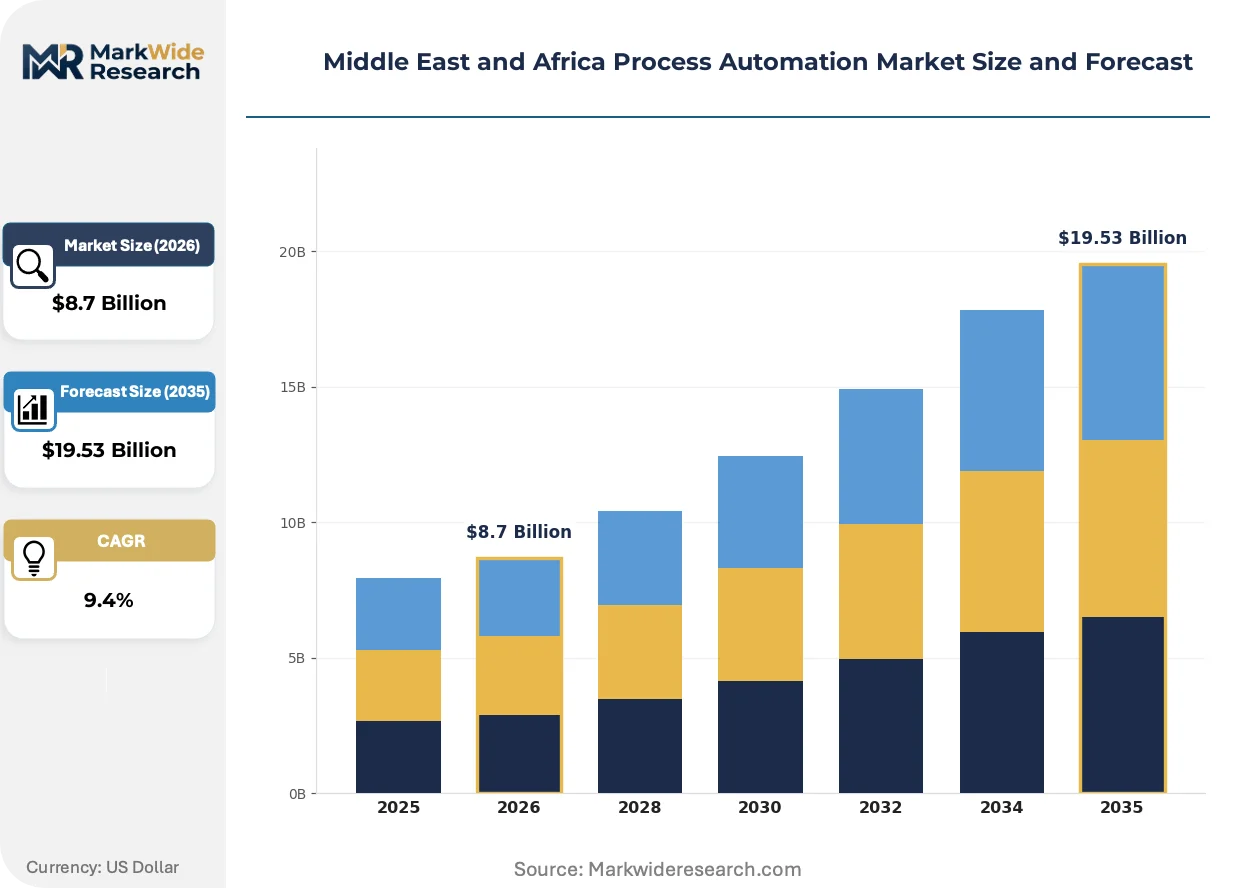
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration Technology: AI, Machine Learning, RPA, Cloud Computing Industry Vertical: Manufacturing, Oil & Gas, Utilities, Healthcare End User: Enterprises, SMEs, Government, Industrial Organizations |
| Companies Covered | Honeywell International Inc., General Electric, ABB Ltd, Yokogawa Electric Corporation, Mitsubishi Electric Corporation, Siemens AG, Emerson Electric Co., Rockwell Automation Inc., Schneider Electric, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Process Automation Market Shifts & Advancements
Digital twin architectures are virtualizing how process operators validate control strategies before physical commissioning, compressing project risk windows across Middle Eastern megaprojects.
Edge computing nodes with embedded analytics are virtualizing traditional DCS hierarchy by pushing inferential control algorithms directly to field devices. Abu Dhabi's downstream operators are piloting these architectures in hydrocracker units. The technology is virtualizing the boundary between field instrumentation and central control rooms, enabling sub-100-millisecond response loops without dedicated safety PLC hardware.
SASO's technical regulations for industrial cybersecurity are mandating segmented network architectures with encrypted device authentication for all new hydrocarbon installations. The policy is forcing vendors to redesign controller firmware with built-in certificate management. Greenfield projects in Jubail Industrial City are experiencing 15-20% engineering cost premiums to meet these requirements.
Aftermarket service unbundling is fragmenting long-term vendor relationships as procurement teams separate hardware warranties from predictive maintenance subscriptions. Dubai's aluminum smelters and Riyadh's chemical complexes are negotiating multi-vendor service portfolios rather than single-source lifecycle contracts. The shift is most pronounced in the UAE, where free zone procurement regulations enable competitive tendering for each service layer.
Middle East and Africa Process Automation Market Segmentation
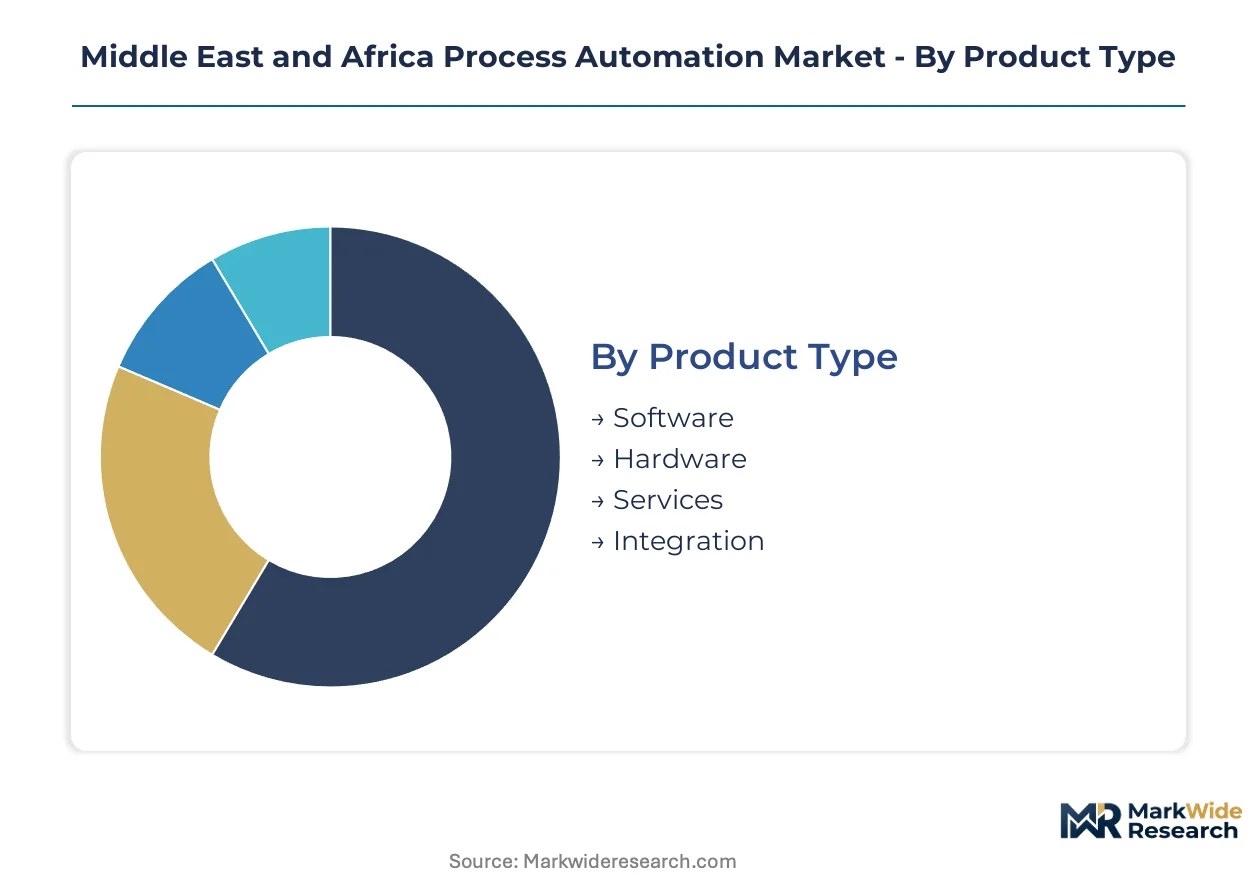
Process automation procurement across the Middle East and Africa fragments sharply by replacement velocity. Hardware assets in hydrocarbon facilities operate on 15-20 year depreciation cycles while software licenses turn over every 3-5 years, creating fundamentally different vendor engagement models and margin profiles across each segment category.
Product Type:
Replacement cycles stretch from quarterly software patches to decadal control system overhauls, with service contracts bridging the gap through predictive maintenance subscriptions.
- Hardware:Distributed control systems, safety instrumented systems, and field instrumentation constitute the capital-intensive foundation of regional automation deployments. Procurement concentrates in Saudi Arabia's Jubail Industrial City and Abu Dhabi's downstream complexes where greenfield refinery investments demand IEC 61511-certified protection layers. SASO mandates are accelerating replacement of pre-2010 safety systems in existing hydrocarbon facilities.
- Services:System integration, commissioning support, and lifecycle maintenance represent the fastest-expanding revenue pool as localization requirements force foreign vendors to build domestic engineering capabilities. Saudi Arabia's industrial cities authority mandates joint venture structures that transfer commissioning expertise to local partners, compressing project timelines previously dependent on expatriate specialists.
- Software:Advanced process control algorithms, operator training simulators, and manufacturing execution systems enable inferential control and batch optimization. Deployment accelerates in Dubai's pharmaceutical and food processing sectors under smart manufacturing initiatives.
- Integration:Multi-vendor system interoperability and legacy protocol translation address brownfield retrofit complexity in 1990s-era Egyptian fertilizer plants and Kuwaiti refineries.
Hardware anchors the volume base while services gains share at the steepest rate.
Technology:
Technology selection follows a maturity-cost gradient, with proven architectures dominating safety-critical applications while experimental platforms penetrate non-operational decision support.
- AI:Machine vision for quality inspection and predictive models for equipment failure detection are penetrating Abu Dhabi aluminum smelters and Riyadh chemical complexes. Edge deployment of neural networks for inferential property estimation is compressing laboratory analysis cycles in Qatar's LNG trains.
- Machine Learning:Pattern recognition algorithms optimize combustion efficiency in Saudi power generation and desalination facilities. Model retraining requirements create ongoing service revenue streams distinct from initial deployment fees.
- RPA:Robotic process automation targets back-office engineering workflows and regulatory documentation in UAE free zone procurement operations.
- Cloud Computing:Remote monitoring architectures and centralized data lakes face cybersecurity certification delays under IEC 62443 compliance timelines, constraining adoption in hydrocarbon processing despite operational efficiency gains.
Machine learning commands the largest installed base while AI expands most quickly through edge computing pilots.
Industry Vertical:
Vertical concentration mirrors regional economic structure, with hydrocarbon dominance creating technology spillover effects into adjacent process industries.
- Oil & Gas:Upstream throughput optimization, downstream yield maximization, and LNG loading automation constitute the highest-value application set. Qatar's North Field expansion and Saudi Aramco's maintained production targets sustain demand for advanced process control and safety instrumented systems.
- Utilities:Desalination automation represents underpenetrated demand in Jordan and Morocco water infrastructure, with reverse osmosis membrane monitoring systems requiring specialized instrumentation.
- Manufacturing:Dubai's Industrial Strategy 2030 channels investment into food processing batch operations and pharmaceutical serialization compliance.
- Healthcare:Sterile manufacturing automation and cleanroom environmental control apply process automation principles to pharmaceutical production under MOHAP and SFDA regulatory oversight.
Oil and gas anchors the volume base while utilities climbs the fastest on water infrastructure investment.
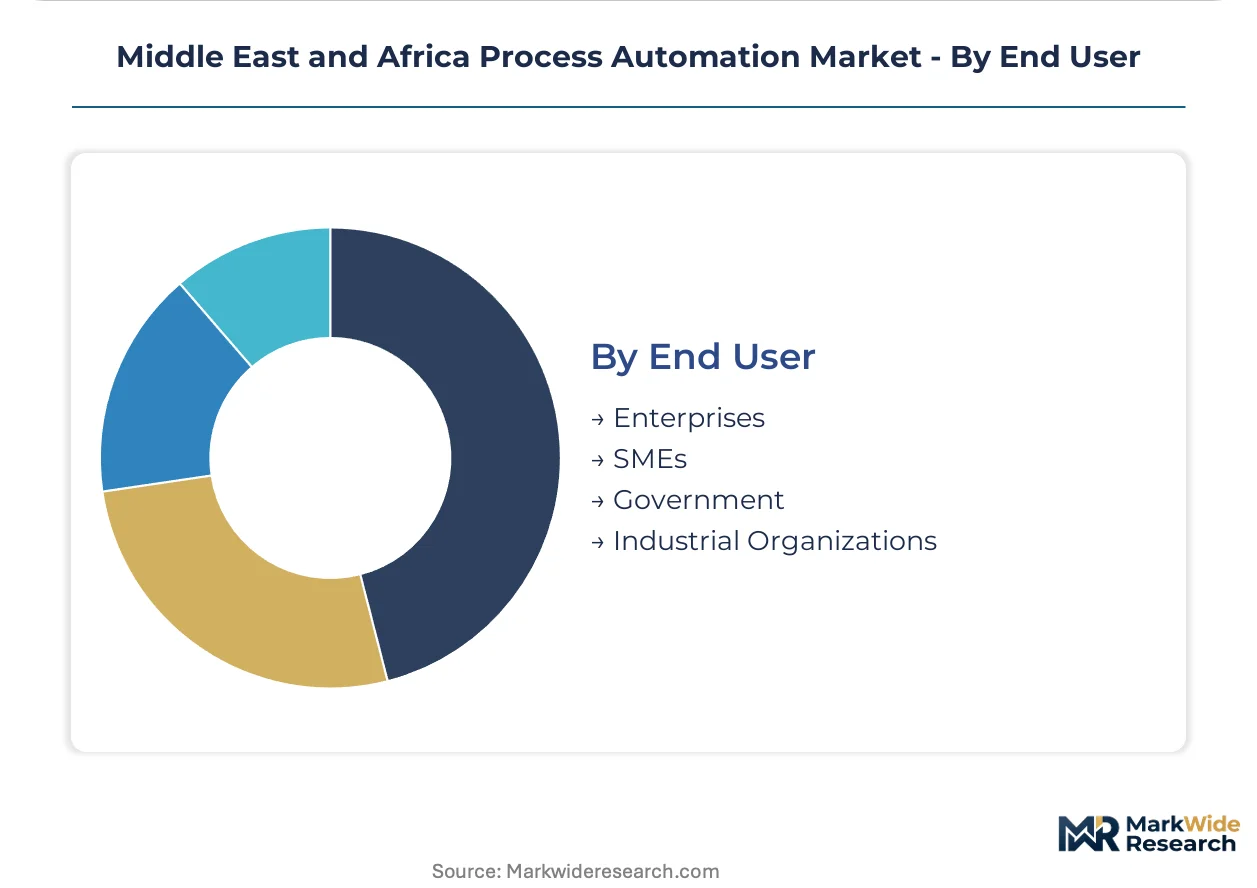
End User:
Procurement sophistication varies dramatically by organizational scale, with government-linked entities leveraging localization mandates while private operators prioritize total cost of ownership.
- Industrial Organizations:State-affiliated petrochemical complexes and aluminum smelters command the largest individual contract values. Procurement teams in Saudi Arabia's SABIC and UAE's Emirates Global Aluminum negotiate multi-vendor service portfolios rather than single-source lifecycle agreements.
- Government:Municipal water authorities and national oil companies embed local content requirements directly into tender specifications, favoring joint ventures with domestic engineering partners.
- Enterprises:Privately held manufacturing groups in Dubai's free zones exercise competitive tendering flexibility unavailable to government-linked entities.
- SMEs:Smaller process operators in Omani and Bahraini industrial zones rely on distributor networks and standardized packaged automation solutions rather than customized system integration.
Industrial organizations anchor the volume base while government entities drive steepest contract value growth through megaproject scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Egypt and Nigeria exhibit acute price sensitivity on hardware procurement, while Saudi Aramco and ADNOC-linked entities in the Gulf prioritize lifecycle reliability over upfront capital expenditure.
Saudi Arabia
Jubail Industrial City and Yanbu drive demand for safety instrumented systems in refinery expansions. SASO mandates IEC 61511 compliance for all new hydrocarbon installations, forcing legacy system replacements. Riyadh's chemical complexes are negotiating multi-vendor service portfolios rather than single-source contracts.
United Arab Emirates
Abu Dhabi's downstream complexes and Dubai's smart manufacturing initiatives attract vendor investment at divergent price points. ESMA enforces hazardous area conformity assessments that create certification barriers for uncertified suppliers. Dubai Industrial City food processing plants deploy batch automation under the Industrial Strategy 2030.
Qatar
North Field LNG expansion sustains demand for advanced process control and marine loading automation. The national regulator mandates cybersecurity segmentation aligned with IEC 62443 frameworks. Ras Laffan Industrial City concentrates specialized offshore automation engineering for floating production systems.
Egypt
Fertilizer plants in Alexandria and Suez require brownfield retrofit of 1990s-era DCS architectures. The national standards body enforces electrical equipment certification for hazardous environments. Egyptian General Petroleum Corporation facilities face capital constraints that favor modular upgrades over complete I/O replacement.
Nigeria
Port Harcourt petrochemical operators seek localized predictive maintenance subscriptions to displace bundled OEM agreements. The Department of Petroleum Resources enforces safety system standards for onshore production facilities. Lagos-based engineering services firms are capturing commissioning contracts previously held by expatriate teams.
Middle East and Africa Process Automation Market Competitive Landscape
Capability concentration sits with European and Japanese specialists in safety-critical applications; scale advantage sits with diversified industrial conglomerates offering bundled hardware-service portfolios. The vendor base structures into three tiers: integrated automation platforms, specialized safety system providers, and regional system integrators. Siemens AG and ABB Ltd anchor the premium tier through extensive service networks. Competitive moves center on joint venture formation with domestic engineering partners and unbundled service model introduction.
Within the integrated platform tier, Honeywell International Inc., Siemens AG, and ABB Ltd exemplify contrasting geographic anchoring strategies. Honeywell leverages its installed base in Gulf refineries to extend lifecycle engagements. Siemens maintains position through service network density spanning Saudi Arabia and the UAE. ABB occupies a specialized niche in marine and offshore automation support concentrated in Qatar and Oman.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| General Electric |
| ABB Ltd |
| Yokogawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Jubail Industrial City's concentration of safety instrumented system manufacturing compresses hardware margins for foreign vendors while amplifying pricing power for domestic joint ventures with SASO certification pathways.
Pricing Analysis
Aftermarket service subscriptions now drive lifetime value capture as Nigerian petrochemical operators and Dubai aluminum smelters unbundle predictive maintenance from hardware warranties. Three-tier pricing structure across IEC 61511-certified premium systems, standard DCS architectures, and economy-grade field instrumentation reflects divergent certification investment levels. Cost compression in the economy tier intensifies as Omani and Bahraini SMEs source standardized packaged solutions through distributor networks. Government-linked entities in Saudi Arabia and Abu Dhabi exhibit lowest price sensitivity, prioritizing lifecycle reliability and localization compliance over upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from 60 to 120 days dominate procurement negotiations as Abu Dhabi downstream operators and Riyadh chemical complexes leverage project scale for supplier financing concessions. Controller hardware and safety PLC modules draw primarily from Germany, Japan, and the United States, while specialized marine automation components for Qatar's North Field expansion source from European offshore specialists. Single-source vulnerability concentrates in IEC 62443-compliant cybersecurity firmware where SASO mandates have thinned certified supplier pools. Distribution runs through regional system integrators in Dubai's free zones and domestic joint ventures in Saudi Arabia's industrial cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against cloud-native automation platforms that bypass traditional DCS hierarchies through edge computing architectures, threatening incumbent hardware-service bundling models.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance algorithms directly into legacy controller firmware, creating switching costs for Abu Dhabi refineries and Jubail petrochemical complexes. Accelerate joint venture engineering capability transfers ahead of tightening Saudi localization mandates to defend against emerging regional system integrators capturing commissioning contracts. For New Entrants and Emerging Players: Desalination automation in Jordan and Morocco represents the most penetrable white-space target, with reverse osmosis membrane monitoring systems underserved by incumbent marine specialists. Target predictive maintenance subscriptions for Nigerian and Egyptian brownfield facilities where legacy DCS architectures obstruct seamless vendor upgrades, leveraging Lagos and Cairo-based engineering partnerships for localized commissioning credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized safety system providers with IEC 61511 certification depth and marine automation expertise concentrated in Qatar and Oman. Long-term viability hinges on cybersecurity segmentation capabilities as IEC 62443 compliance extends from hydrocarbon processing into water infrastructure and pharmaceutical manufacturing. Watch SASO technical regulation expansion beyond hydrocarbons as the inflection signal for certification-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Saudi localization mandates force foreign vendors to transfer engineering capabilities to domestic partners in Jubail and Yanbu. |
| Predictive Maintenance Unbundling | Separating hardware warranties from service subscriptions captures recurring revenue from Dubai aluminum smelters and Riyadh chemical complexes. |
| IEC 62443 Certification Investment | Cybersecurity firmware redesign opens procurement pathways into greenfield hydrocarbon projects facing 15-20% engineering cost premiums. |
| Edge Computing Pilot Expansion | Sub-100-millisecond control loops without dedicated safety PLC hardware threaten traditional DCS hierarchy in Abu Dhabi hydrocracker units. |
| Desalination Specialization | Reverse osmosis membrane monitoring systems address underpenetrated demand in Jordan and Morocco water infrastructure procurement. |
Research Methodology
The analysis maps distributed control systems, safety instrumented systems, field instrumentation, and aftermarket services, each validated through control system engineers, plant managers at hydrocarbon facilities, procurement leads at national oil companies, and aftermarket service directors. Primary interview intelligence triangulates against SASO technical regulations, ESMA conformity assessment protocols, IEC 61511 and IEC 62443 standards documentation, and trade flow data from regional industrial free zones. Bottom-up project pipeline assessment and top-down macroeconomic overlay generate convergent market sizing.
Assumption sets held oil price scenarios and localization policy enforcement timelines fixed while varying greenfield capital expenditure cycles and brownfield retrofit urgency across the projection horizon. Segmentation dimensions modeled include product type, technology maturity, industry vertical, and end-user procurement sophistication. CAGRs derive from replacement cycle velocity differentials between hardware depreciation schedules and software license turnover. Forecast inputs incorporate safety system regulatory compliance deadlines and smart manufacturing initiative funding allocations in Dubai and Riyadh.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles, Gulf state localization policy enforcement intensity, or cybersecurity certification timeline extensions would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and industrial diversification funding continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Latin America HMI Market