
 Assembly Automation Systems Market | 2026-2036
Assembly Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Assembly Automation Systems Market Analysis
Asset-light leasing models for robotic workcells is narrowing the capital barrier for mid-tier manufacturers seeking automation. ABB leverages its integrated robot-controller-software stack to dominate high-mix automotive lines. FANUC Corporation sustains its position through captive servo motor and CNC supply chains. Bosch Rexroth AG differentiates via hydraulic-electric hybrid actuation for heavy-payload assembly stations.
Assembly automation systems integrate programmable manipulators, precision conveyance, and sensor feedback loops to execute repetitive joining, fastening, and material handling operations with cycle-time repeatability below 50 milliseconds. Their primary purpose is to replace manual labor in high-volume production environments where dimensional tolerance and throughput consistency determine unit economics. Robotic arms command the largest installed base but face margin compression from Chinese actuator suppliers. Machine vision adoption is accelerating fastest among electronics contract assemblers inspecting micro-component placement. AI integration sits at the premium tier where predictive fault detection commands pricing premiums from pharmaceutical OEMs.
The EPA enforces energy efficiency standards on factory equipment that push US manufacturers toward regenerative-drive automation architectures. OSHA lockout-tagout rules and ISO 10218 robot safety protocols dictate guard design and collaborative robot speed limits across North American and European installations. The EU AI Act's risk classification for autonomous industrial systems will reshape validation requirements for self-optimizing assembly lines. Stakeholders must weigh regulatory compliance costs against the operational flexibility gains from modular, reconfigurable automation platforms.
Market Dynamics
Automotive OEMs are consolidating robotic assembly lines around electric vehicle battery pack production, while EU Green Deal industrial emissions benchmarks force factory retrofit cycles that compress equipment replacement timelines from seven to four years.
Growth Catalysts
- EU Green Deal benchmarks:Industrial emissions mandates in Germany and France are accelerating demand for energy-efficient turnkey automation cells that cut per-unit carbon intensity.
- Micro-component inspection:Electronics contract assemblers in Taiwan and South Korea are deploying machine vision systems to verify placement tolerances below 0.1 millimeters.
- Predictive fault detection:Pharmaceutical OEMs are paying premiums for AI-integrated assembly lines that preemptively flag servo motor degradation before throughput drops.
Market Restraints
- Servo motor cost volatility:Rare earth magnet price swings constrain margin stability for mid-tier robotic workcell producers dependent on Chinese neodymium supply.
- Technical limitation of collaborative robots:ISO 10218 speed caps and force-limiting requirements prevent cobot deployment in heavy-payload fastening applications above 15 kilograms.
- Regulatory friction from EU AI Act:Risk classification protocols for self-optimizing assembly lines are extending validation timelines by 12-18 months for autonomous industrial system vendors.
Strategic Opportunities
- Asset-light leasing models:Mid-tier manufacturers in Mexico and Poland are accessing robotic workcells through usage-based contracts that eliminate seven-figure capex barriers.
- Hydraulic-electric hybrid actuation:Heavy-payload assembly stations for construction equipment and agricultural machinery are opening demand for actuation systems that combine precision with force density.
- Modular reconfigurable platforms:FDA validation requirements for pharmaceutical packaging lines are driving demand for automation architectures that swap end-effectors without full requalification.
Industry Challenges
- Controls integration specialists:The shortage of engineers fluent in both PLC programming and ROS-based robot middleware is delaying commissioning timelines for hybrid automation projects.
- Legacy SCADA interoperability:Brownfield automotive plants running 1990s-era Allen-Bradley networks face protocol translation costs that erode projected ROI on new robotic cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assembly Automation Systems Market |
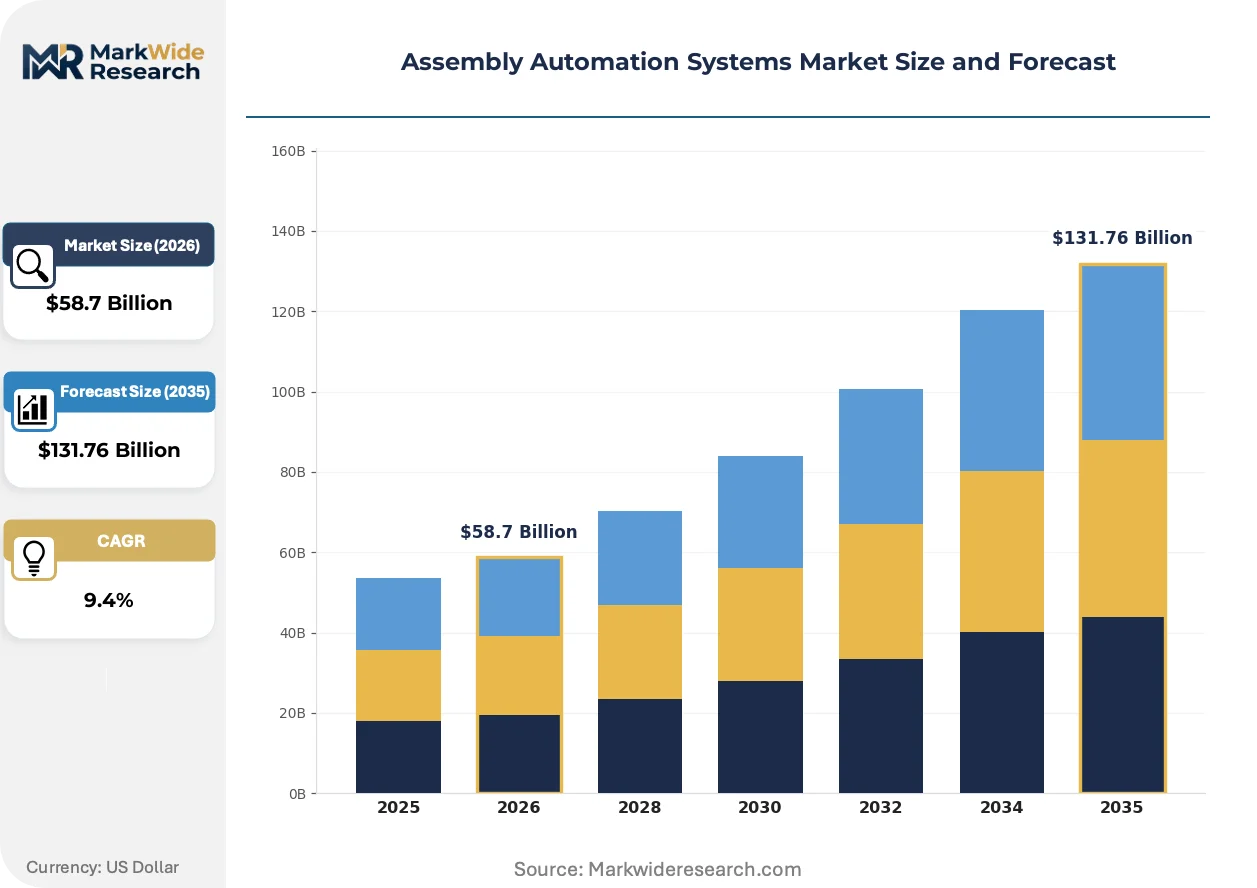
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Conveyors, Automated Guided Vehicles, Pick and Place Systems Technology: Machine Vision, AI Integration, HMI, IoT Connectivity Industry Vertical: Electronics, Automotive OEMs, Pharmaceuticals, Consumer Goods End User: Manufacturers, Tier-1 Suppliers, Contract Assemblers, System Integrators |
| Companies Covered | ABB, Siemens AG, FANUC Corporation, Rockwell Automation, Yaskawa Electric, KUKA AG, Bosch Rexroth AG, Schneider Electric SE, JR Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assembly Automation Systems Market Emerging Trajectories
Software-defined automation architectures are displacing fixed mechanical configurations, while regulatory pressure on embodied carbon and energy intensity reshapes equipment specification criteria across procurement departments.
Digital twin platforms are rendering obsolete physical prototype commissioning for complex multi-robot cells. Automotive OEMs in Stuttgart and Detroit are deploying virtual commissioning environments that compress integration timelines from months to weeks. This shift is rendering obsolete the traditional site acceptance test model that required full production runs before final payment release.
The EPA's energy efficiency standards for factory equipment are pushing US manufacturers toward regenerative-drive architectures that capture and reuse deceleration energy. Industrial motor systems above 200 horsepower now face mandatory efficiency tiers that disqualify conventional VFD configurations. Metalworking and heavy machinery producers in Ohio and Michigan are retrofitting servo axes with shared DC bus topologies to meet these thresholds.
Leasing structures are displacing outright purchase for robotic workcells among capital-constrained manufacturers. Mid-tier automotive suppliers in Mexico and Eastern Europe are accessing ABB and FANUC equipment through five-year operational expenditure contracts that bundle maintenance and software updates. This model is most visible in contract electronics manufacturing, where volume volatility makes asset ownership risk-prohibitive.
Assembly Automation Systems Market Segmentation
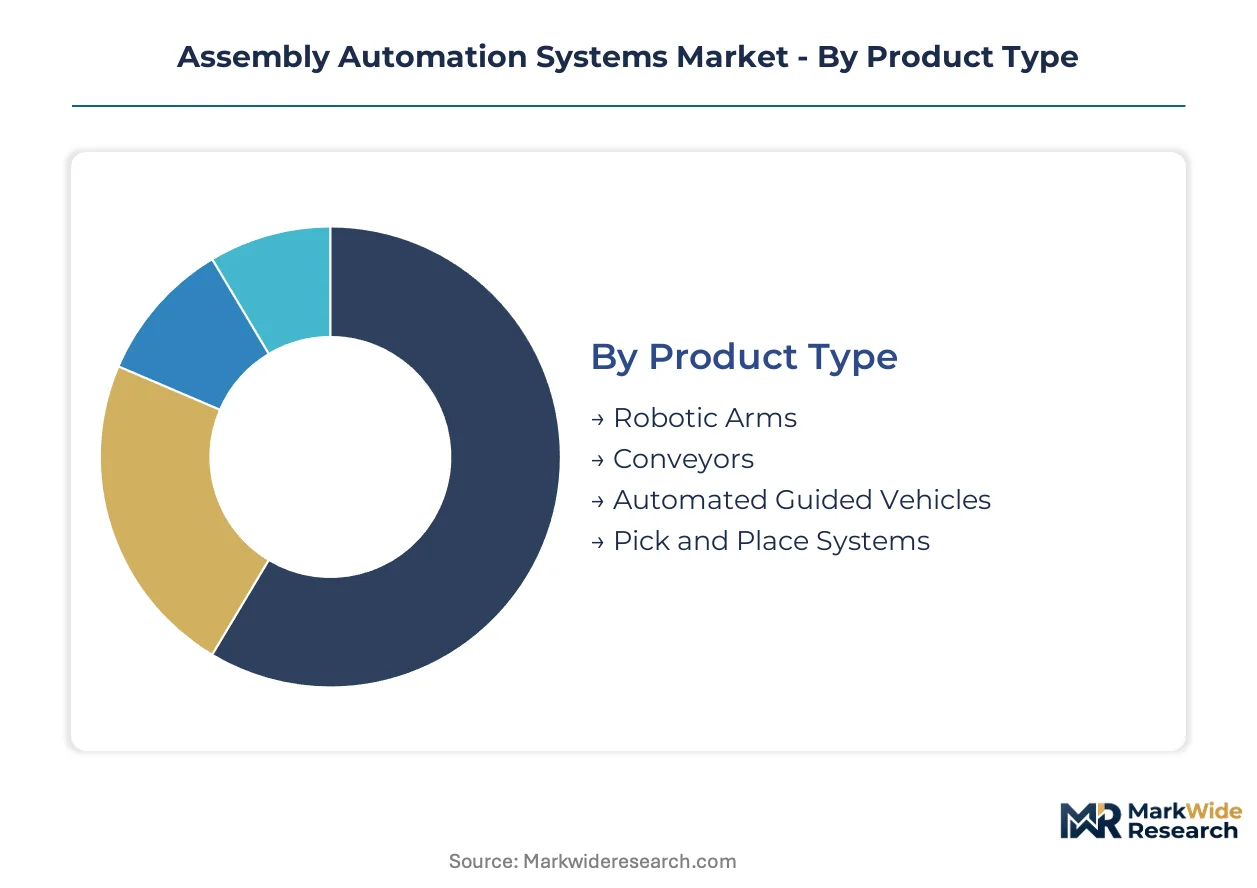
Assembly automation systems exhibit divergent service lifecycle economics across product configurations. Equipment complexity and integration depth determine aftermarket revenue intensity. Procurement patterns vary sharply by buyer technical sophistication and capital structure.
Product Type:
After-sales service intensity peaks with multi-axis kinematic systems requiring precision calibration. Spare parts availability and field engineering density shape total cost of ownership calculations for capital equipment buyers.
- Robotic Arms:Six-axis articulated manipulators with servo motor drives dominate automotive body-in-white welding and EV battery module assembly. Demand concentrates among German automotive OEMs retrofitting Stuttgart and Wolfsburg plants for electric powertrain platforms. Preventive maintenance contracts generate recurring revenue streams that offset initial hardware margin compression.
- Conveyors:Precision belt and pallet-based transport systems synchronize cycle times across multi-station cells. Electronics contract assemblers in Taiwan and South Korea specify magnetic levitation variants for cleanroom semiconductor packaging lines. These configurations demand minimal field intervention beyond belt replacement intervals.
- Automated Guided Vehicles:Laser-guided and vision-navigated mobile platforms execute inter-station material logistics. Manufacturing campuses in Michigan and Ohio deploy fleet management software for coordinated traffic control.
- Pick and Place Systems:Cartesian and SCARA architectures handle high-speed component orientation. Consumer goods packagers in Poland prioritize delta robots for confectionery sorting operations.
Robotic arms hold the largest share; momentum sits with automated guided vehicles.
Technology:
Software-enabled capabilities command pricing premiums that hardware commoditization cannot sustain. Licensing structures and update cadences differentiate vendor profitability in technology-heavy configurations.
- Machine Vision:Camera-lens-illumination subsystems with sub-pixel edge detection algorithms verify assembly tolerances. Electronics assemblers in South Korea deploy 12-megapixel area scan cameras for micro-SD card placement verification. Inspection throughput requirements drive parallel processing architectures.
- AI Integration:Neural network-based fault prediction models analyze servo motor current signatures. Pharmaceutical OEMs in Switzerland pay premiums for FDA-validated anomaly detection that preempts batch contamination.
- HMI:Touch-panel and augmented reality interfaces reduce operator training burdens. Tier-1 suppliers in Mexico adopt multilingual operator terminals for workforce flexibility.
- IoT Connectivity:OPC-UA and MQTT protocol stacks enable cloud-based performance monitoring. System integrators in Japan bundle edge computing gateways with predictive analytics subscriptions.
Machine vision commands installed base leadership; AI integration is climbing the fastest.
Industry Vertical:
Regulatory validation burdens and contamination control standards fragment equipment specifications. Cleanroom compatibility and traceability requirements separate premium from standard tier procurement.
- Electronics:Surface-mount technology lines and semiconductor packaging equipment demand micron-level placement accuracy. Taiwan-based contract manufacturers specify vibration-isolated granite bases for flip-chip bonding operations. Miniaturization trends compress cycle times below 300 milliseconds per component.
- Automotive OEMs:Electric vehicle battery pack assembly drives demand for heavy-payload collaborative systems. German manufacturers in Bavaria integrate force-torque sensing for cell stacking operations. Welding fume extraction and thermal management add system complexity.
- Pharmaceuticals:Aseptic filling and parenteral packaging lines require stainless steel construction and SIP/CIP protocols. Swiss packaging specialists validate automation cells against US FDA 21 CFR Part 11.
- Consumer Goods:High-speed cartoning and case-packing equipment prioritize changeover speed over precision. Polish food processors specify IP69K washdown ratings for dairy packaging environments.
Automotive OEMs represent the dominant vertical; pharmaceuticals is gaining share fastest.
End User:
Technical integration capability and capital access stratify buyer behavior. Direct manufacturers prioritize uptime guarantees; intermediaries emphasize financing flexibility.
- Manufacturers:Captive engineering teams specify custom automation architectures aligned with proprietary processes. US-based metalworking operations in Ohio deploy hydraulic-electric hybrid actuation for forging press tending. In-house maintenance capabilities reduce service contract attach rates.
- Tier-1 Suppliers:Seating and drivetrain specialists face OEM price-down pressures that favor leased equipment models. Mexican automotive suppliers access FANUC workcells through five-year operational expenditure contracts.
- Contract Assemblers:Volume volatility drives demand for reconfigurable platforms with rapid end-effector swap capability. Electronics manufacturing services in Eastern Europe specify modular cells for smartphone model transitions.
- System Integrators:Turnkey project vendors bundle hardware procurement with controls engineering and commissioning. Japanese integrators dominate pharmaceutical validation expertise for global deployments.
Manufacturers hold the largest share; contract assemblers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese electronics manufacturers concentrate the highest procurement volumes for turnkey automation cells, while mid-tier suppliers in Mexico and Poland access equipment through emerging leasing structures.
United States
Metalworking operations in Ohio and Michigan drive demand for heavy-payload robotic cells serving forging and press-tending applications. The EPA enforces energy efficiency standards on factory equipment above 200 horsepower that mandate regenerative-drive architectures. Detroit-area automotive plants retrofit aging lines with collaborative systems for electric powertrain assembly.
Germany
Bavarian battery manufacturers integrate force-torque sensing for EV cell stacking operations requiring micron-level precision. The EU Green Deal's industrial emissions benchmarks compress equipment replacement timelines from seven to four years. Stuttgart and Wolfsburg plants anchor European demand for six-axis welding manipulators and modular automation platforms.
Japan
System integrators bundle edge computing gateways with predictive analytics subscriptions for pharmaceutical validation projects. METI standards shape domestic procurement specifications for cleanroom-compatible assembly architectures. Nagoya-area automotive suppliers deploy fleet management software for coordinated AGV traffic across multi-building campuses.
South Korea
Electronics contract assemblers specify 12-megapixel machine vision systems for micro-SD card placement verification below 0.1 millimeters. The MFDS regulates pharmaceutical packaging line validation requirements that favor modular, reconfigurable automation architectures. Seoul Capital Area semiconductor packaging facilities demand vibration-isolated granite bases for flip-chip bonding operations.
Mexico
Tier-1 automotive suppliers access FANUC and ABB workcells through five-year operational expenditure contracts that eliminate capital barriers. OSHA lockout-tagout rules and ISO 10218 safety protocols dictate collaborative robot speed limits across maquiladora installations. Nuevo León-based seating and drivetrain specialists favor leased equipment models under sustained OEM price-down pressure.
Assembly Automation Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated stack vendors hold pricing power over component suppliers. The vendor base separates into three strategic archetypes: full-stack automation houses with captive controller-software integration, precision component specialists with deep servo motor or actuator expertise, and regional system integrators bundling procurement with commissioning services. Dominant competitive moves include backward integration into critical components and geographic expansion through local integrator partnerships.
Within the full-stack tier, ABB and FANUC Corporation exemplify integrated architectures that combine robotic hardware with proprietary control systems. Bosch Rexroth AG occupies a distinct position through hybrid actuation technologies serving heavy-payload industrial applications. These three anchors represent divergent strategic postures: European-Japanese scale-driven consolidation versus German precision-engineering specialization.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| FANUC Corporation |
| Rockwell Automation |
| Yaskawa Electric |
| KUKA AG |
| Bosch Rexroth AG |
| Schneider Electric SE |
| JR Automation |
| Others |
Supply Flow & Price Mechanics
Stuttgart's concentration of six-axis robotic manufacturing anchors European pricing power for precision automation cells, with capacity utilization at German actuator foundries directly conditioning margin structures for downstream system integrators serving automotive OEMs.
Pricing Analysis
Certification level creates the primary spread across assembly automation procurement, with FDA-validated pharmaceutical lines commanding substantial premiums over standard ISO 10218 configurations for general manufacturing. Three-tier pricing structure across premium, standard, and economy levels reflects software-defined capability depth, from predictive AI modules to basic PLC-controlled sequences. Pricing pressure stems from Chinese servo motor suppliers compressing hardware margins for mid-tier robotic workcell producers. Contract assemblers exhibit highest price sensitivity due to volume volatility, while pharmaceutical OEMs prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Rare earth magnet feedstock from Chinese mining operations and Japanese refining facilities anchors servo motor cost structures for robotic actuator producers worldwide. German precision gear manufacturing and Taiwanese semiconductor fabrication for machine vision sensors constitute critical component inputs. Single-source vulnerability concentrates in neodymium supply chains subject to export restriction risk. Distribution runs through authorized system integrator networks bundling hardware procurement with commissioning services, particularly dominant in pharmaceutical validation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Assembly automation is approaching a platform-economics inflection where software-defined architectures and OPC-UA interoperability standards are displacing proprietary control stacks, rewarding vendors who capture developer ecosystems rather than hardware market share alone.
For Market Incumbents: Build captive controller-software integration moats through backward integration into edge computing hardware and predictive analytics subscriptions. Defensive consolidation should target machine vision specialists in South Korea and system integrators with pharmaceutical validation expertise. Threat from Chinese actuator suppliers demands in-house production of servo motors to preserve margin stability. For New Entrants and Emerging Players: Poland's mid-tier automotive supplier base offers underpenetrated demand for leased robotic workcells under OEM price-down pressure. White-space targets include hydraulic-electric hybrid actuation for agricultural machinery and modular reconfigurable platforms for electronics contract assemblers. Go-to-market through usage-based operational expenditure contracts eliminates capital barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-heavy configurations over hardware-commoditized segments, with AI-integrated predictive fault detection commanding durable pricing premiums. Acquisition archetypes include regional system integrators with FDA validation capabilities and edge computing gateway specialists. Signal to watch: EU AI Act risk classification enforcement accelerating validation timeline compression for autonomous industrial system vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motors | Captive neodymium supply chains insulate margin structures from Chinese export volatility. |
| Software-Defined Automation Platform | OPC-UA interoperability displaces proprietary control stacks across multi-vendor installations. |
| Asset-Light Leasing Model Expansion | Five-year operational expenditure contracts unlock mid-tier manufacturer demand in Mexico and Poland. |
| Digital Twin Virtual Commissioning | Automotive OEMs in Stuttgart compress integration timelines from months to weeks. |
| Pharmaceutical Validation Specialization | FDA 21 CFR Part 11 expertise commands pricing premiums from Swiss packaging specialists. |
Methodological Framework
A standing panel of plant engineers, OEM procurement managers, system integrators, and aftermarket service heads provided ongoing calibration across primary fieldwork and secondary validation. Interview sources combined with SEC 10-K filings, customs and trade data, IHS Markit vehicle production databases, and FDA 510(k) submission records. Bottom-up equipment shipment analysis triangulated against top-down industrial automation spending estimates from national statistical agencies.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling robotic arm, conveyor, AGV, and pick-and-place configurations by technology tier, industry vertical, and end-user technical sophistication. CAGRs derived from segment-level growth rate reconciliation against macroeconomic industrial production indices. Forecast inputs incorporated EU Green Deal emissions benchmark compliance costs and EPA energy efficiency standard adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese actuator suppliers or accelerated EU AI Act enforcement would shift outcomes. Cross-checking against national industrial automation import statistics and OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Intralogistics Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Global SCADA Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Latin America Laboratory Automation Market