
 Mining Automation Solutions Market | 2026-2036
Mining Automation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Automation Solutions Market Intelligence
Edge-to-cloud connectivity architectures is reconfiguring how automation layers integrate across pit-to-port operations. ABB leverages its electrification portfolio to anchor power-delivery systems for autonomous fleets. Komatsu dominates ultra-class haul truck automation through its FrontRunner system deployed across multiple continents. Sandvik AB specializes in underground drill rig autonomy, competing on precision in confined orebody extraction.
Mining automation solutions encompass integrated hardware-software systems that enable semi-autonomous or fully autonomous operation of extraction, haulage, and processing equipment, typically incorporating LiDAR, GNSS positioning, and machine-vision algorithms operating within 10-centimeter path accuracy tolerances. Their primary commercial purpose centers on removing human operators from hazardous zones while sustaining 24-hour production cycles. Autonomous Vehicles within the Technology dimension leads capital allocation due to the multi-million-dollar per-unit economics of retrofitting haul fleets. Software Solutions within Product Type represents the fastest-expanding margin pool as vendors shift from perpetual licenses to recurring analytics subscriptions.
OSHA mandates in the United States, the Australian Work Health and Safety Act administered by state regulators, and Chile's Superintendencia de Minería standards collectively tighten requirements for remote-operation capabilities in hazardous classifications. These frameworks directly shape procurement specifications, disqualifying non-compliant vendors from tier-one mining corporation tenders. Stakeholders must monitor convergence between autonomous equipment standards and evolving cybersecurity protocols for operational technology networks.
Market Dynamics
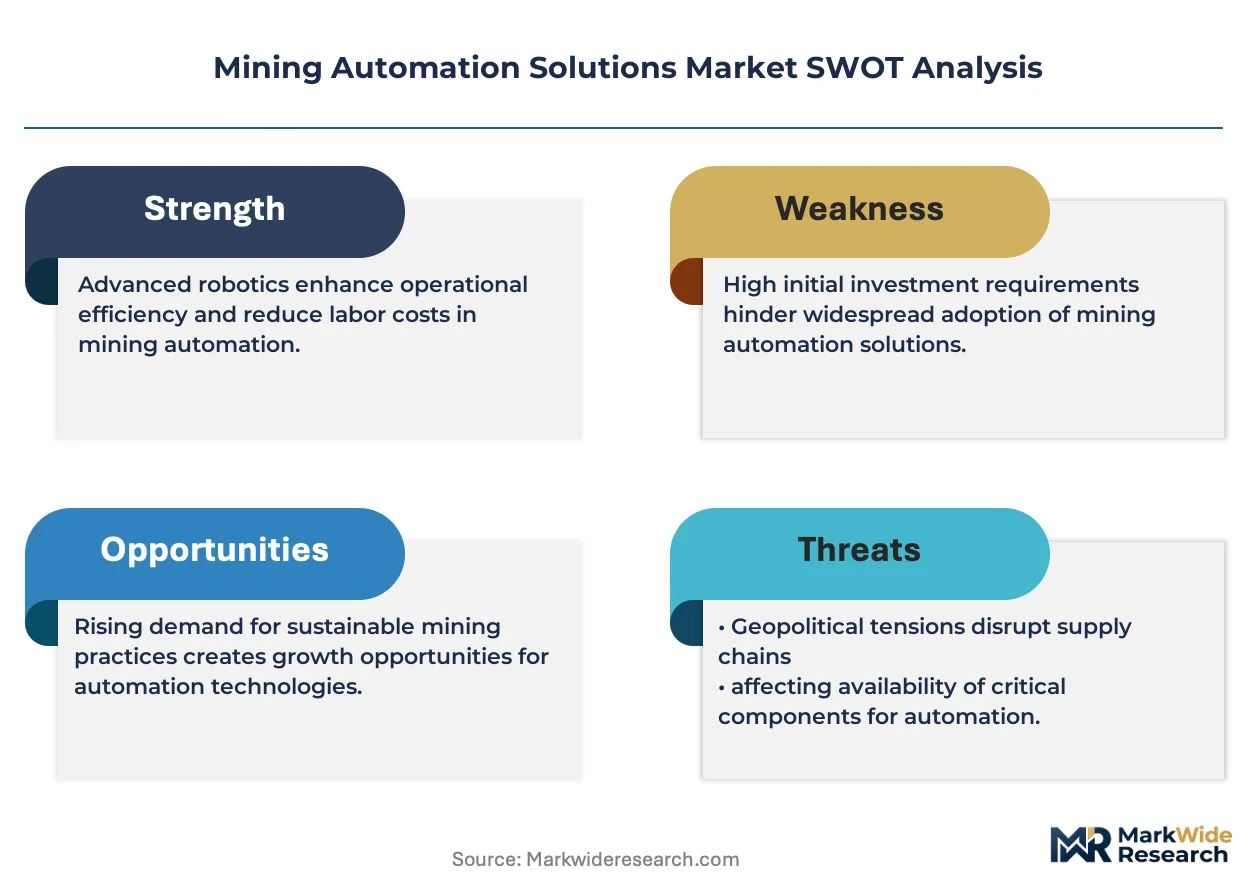
Underground mining operators are accelerating fleet replacement cycles as stricter safety mandates from OSHA, Australia's state regulators, and Chile's Superintendencia de Minería compel capital expenditure on remote-operated equipment. The shift from manned to autonomous haulage is compressing procurement timelines and reshaping vendor qualification criteria.
Growth Catalysts
- OSHA confined-space mandates:US underground metal mines must deploy remote-operated drilling equipment to eliminate human entry into hazardous zones, triggering replacement demand for legacy manned rigs.
- LiDAR-GNSS sensor fusion:Path accuracy improvements to 10-centimeter tolerances enable fully autonomous haul truck operation in GPS-denied underground environments, expanding addressable mine types.
- Pilbara iron ore cluster:Australia's tier-one miners operate the world's largest proven fleet of driverless trucks, creating reference architectures that accelerate adoption across copper and gold operations.
Market Restraints
- Copper cabling infrastructure:Retrofitting decades-old shaft power distribution for electrified autonomous fleets requires capital outlays that marginal underground operations cannot absorb.
- Single-source LiDAR dependency:High-specification mining-grade sensors concentrate among two dominant suppliers, creating procurement bottlenecks during fleet-scale deployments.
- Chilean environmental licensing:Expansion permits for new open-pit autonomous zones face multi-year review timelines under updated glacier protection protocols, freezing greenfield automation budgets.
Strategic Opportunities
- Canadian potash belt:Saskatchewan's deep shaft mines remain underpenetrated by autonomous haulage, presenting first-mover advantage for vendors with cold-climate battery-electric systems.
- Analytics-as-a-service:Vendors are displacing perpetual software licenses with recurring telemetry subscriptions, capturing lifetime value from fleet-wide predictive maintenance data.
- EU battery raw materials security:The Critical Raw Materials Act mandates accelerated domestic lithium and graphite extraction, incentivizing automation investment to offset European labor cost premiums.
Industry Challenges
- OT cybersecurity certification:Autonomous fleet networks require IEC 62443 compliance validation that extends deployment timelines by 8-14 months for tier-one mining corporations.
- Legacy SCADA integration:Proprietary communication protocols from 1990s-era control systems resist seamless interfacing with modern autonomous vehicle management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Automation Solutions Market |
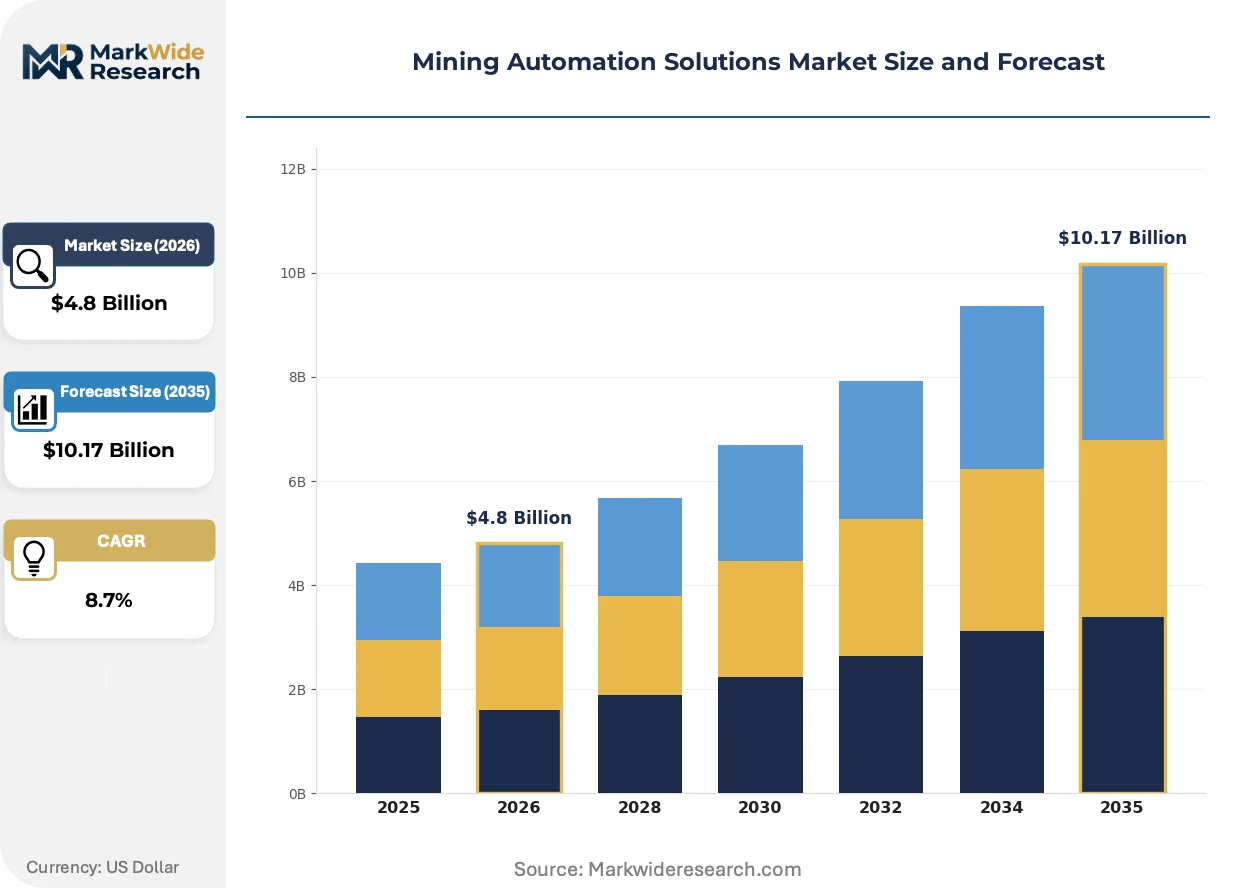
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous Vehicles, Remote Control Systems, AI & Machine Learning, Sensor Technologies Application: Drilling, Blasting, Material Handling, Site Preparation End User: Mining Corporations, Construction Firms, Equipment Manufacturers, Service Providers Product Type: Control Systems, Software Solutions, Heavy Machinery, Communication Equipment |
| Companies Covered | Epiroc AB, ABB, Caterpillar, Rockwell Automation, Hexagon, Komatsu, Hitachi Construction Machinery, Plotlogic, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Automation Solutions Market Strategic Shifts & Innovations
Edge-to-cloud connectivity architectures are reconfiguring how automation layers integrate across pit-to-port operations, compressing decision latency and enabling centralized fleet orchestration from surface control centers.
Digital-twin simulation platforms are hybridizing physical and virtual mine environments for pre-deployment validation of autonomous haul routes. Tier-one iron ore operators in Western Australia now require digital-twin certification before approving capital expenditure on new fleet automation, compressing vendor sales cycles while raising technical qualification barriers for smaller competitors.
Australia's Work Health and Safety Act administered by state regulators now mandates autonomous-equipment interoperability standards for emergency shutdown protocols. This framework forces vendors to open proprietary control interfaces, eroding software lock-in advantages and accelerating procurement evaluation cycles for mining corporations seeking multi-vendor fleet flexibility.
Subscription-based fleet analytics are displacing perpetual license models as the dominant software procurement pattern. Tier-one miners in Chile's copper belt now demand usage-based pricing tied to equipment availability metrics, transferring performance risk to vendors while capturing operational data for in-house optimization teams.
Mining Automation Solutions Market Segmentation
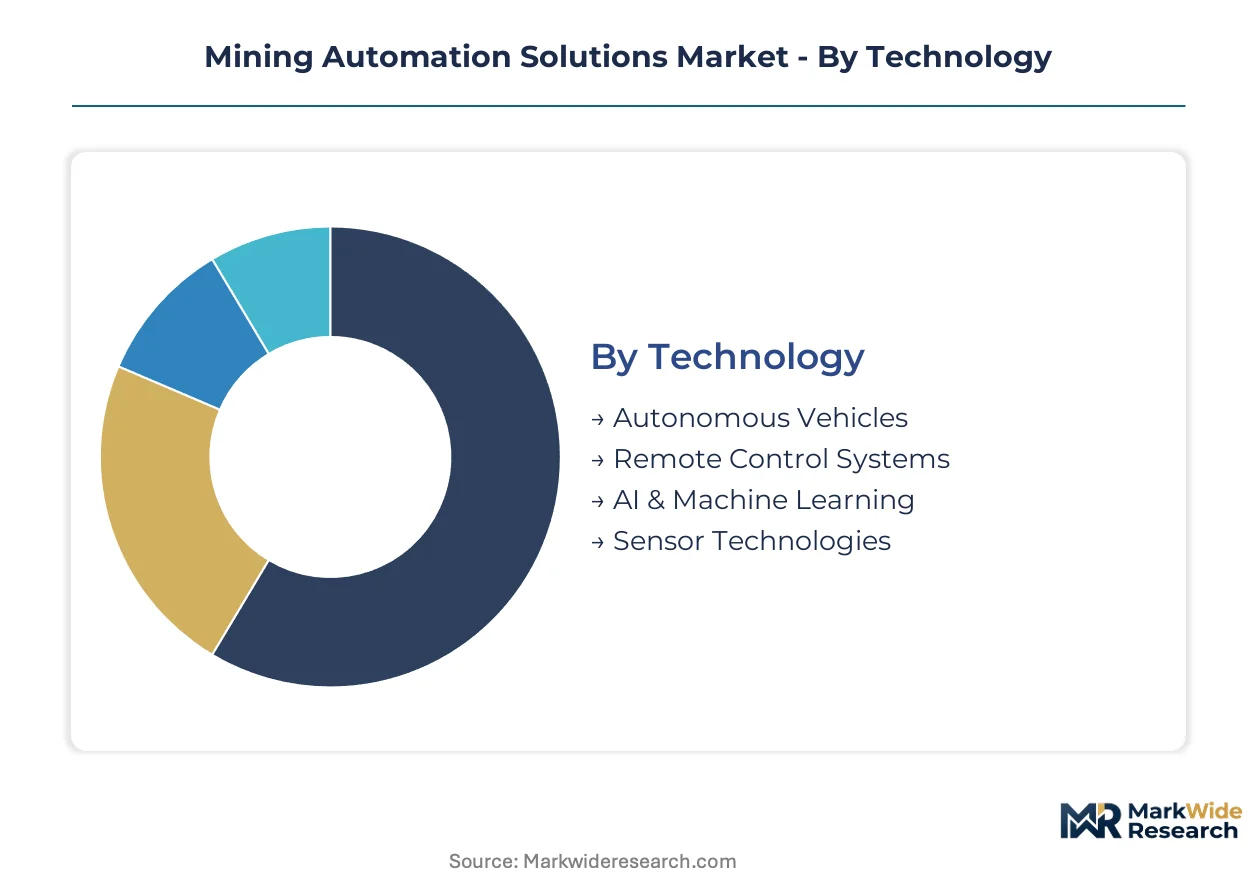
Segmentation in mining automation solutions reveals how capital flows cluster around proven technologies versus emerging capabilities. Procurement patterns diverge sharply between surface and underground applications, while software monetization models are displacing hardware-centric revenue streams.
Technology:
Mature autonomous platforms anchor current deployment volumes, while AI and sensor fusion represent emerging layers commanding premium pricing.
- Autonomous Vehicles:Self-driving haul trucks and drill rigs operate through LiDAR-GNSS fusion achieving 10-centimeter path accuracy. Australia's Pilbara iron ore district hosts the world's largest proven fleet, with tier-one miners expanding orders to copper and gold operations.
- AI & Machine Learning:Predictive maintenance algorithms and fleet optimization engines process telemetry from thousands of connected assets. Chile's Superintendencia de Minería now requires AI-enabled hazard detection for underground emergency protocols, accelerating procurement timelines.
- Remote Control Systems:Teleoperation interfaces enable human operators to manage equipment from surface control centers, eliminating confined-space exposure.
- Sensor Technologies:Mining-grade LiDAR, radar, and machine-vision arrays provide environmental perception for autonomous navigation.
Autonomous Vehicles handles the majority of throughput; AI & Machine Learning is expanding most quickly on share.
Application:
Cost tier segmentation separates capital-intensive autonomous haulage from lower-barrier remote drilling entry points.
- Material Handling:Autonomous haul truck fleets dominate capital allocation, with single-unit economics exceeding several million dollars per retrofit. Western Australia's tier-one iron ore operators require digital-twin certification before approving expenditure, compressing vendor sales cycles.
- Drilling:Underground drill rig autonomy eliminates human entry into hazardous zones, directly addressing OSHA confined-space mandates for US metal mines. Sandvik AB competes on precision in confined orebody extraction.
- Blasting:Automated drilling and charging systems reduce explosive handling risks while improving blast pattern consistency.
- Site Preparation:Autonomous dozers and graders establish haul roads and bench configurations with GNSS-guided precision.
Material Handling captures the largest equipment budgets; Drilling is climbing the fastest as safety mandates tighten.
End User:
Customer type determines procurement authority, with mining corporations controlling fleet-scale decisions versus equipment manufacturers seeking embedded automation partnerships.
- Mining Corporations:Tier-one miners in Australia, Chile, and Canada specify multi-vendor interoperability standards, eroding vendor lock-in advantages. Komatsu's FrontRunner system deploys across multiple continents to serve this segment.
- Equipment Manufacturers:OEMs integrate automation modules into new-build machinery, partnering with technology vendors for sensor and software stacks.
- Construction Firms:Quarry and civil earthmoving operators adopt adapted mining automation for repetitive material movement tasks.
- Service Providers:Contract mining and equipment rental companies procure automation to meet client safety specifications.
Mining Corporations drive fleet-scale deployment; Equipment Manufacturers are gaining procurement influence through embedded partnerships.
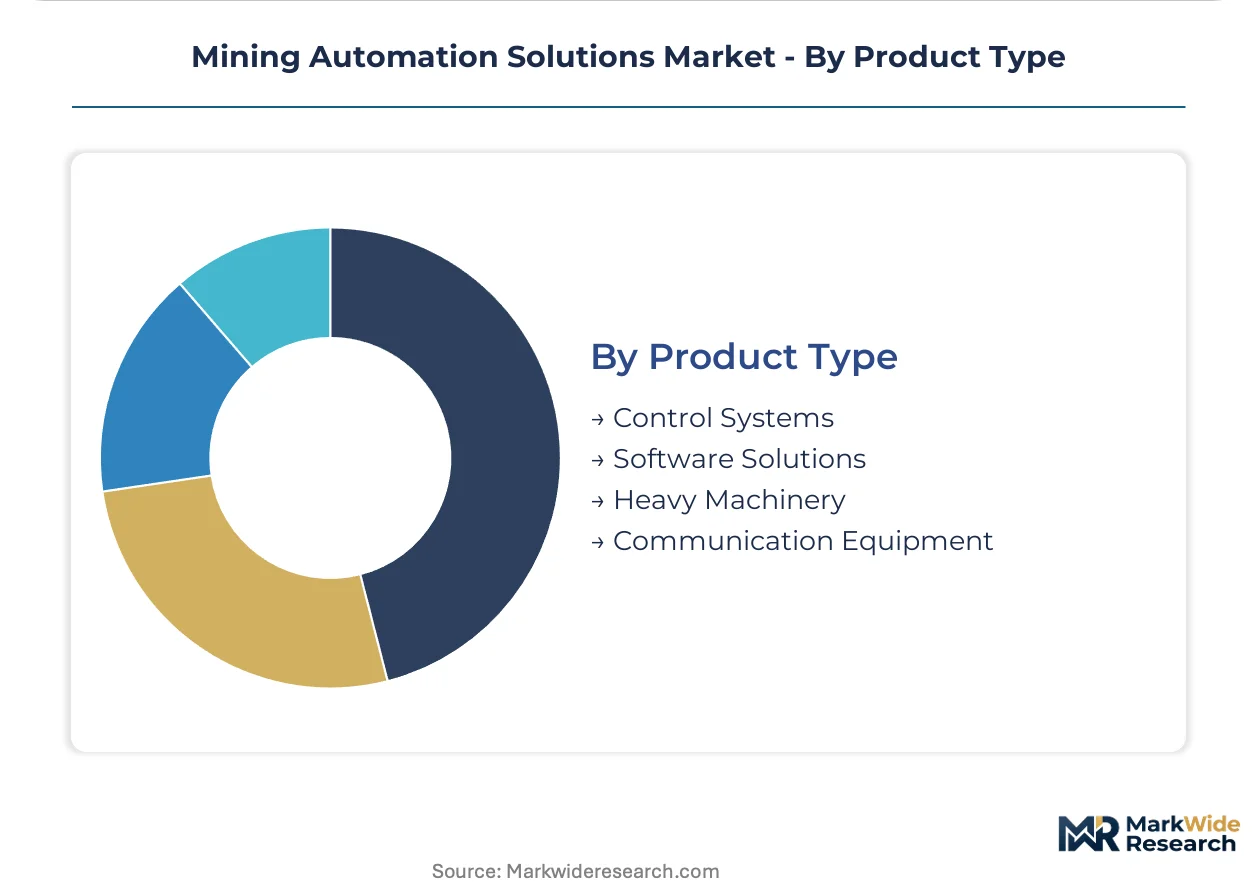
Product Type:
Margin structure separates recurring software subscriptions from one-time hardware and control system sales.
- Software Solutions:Telemetry analytics and fleet management platforms shift from perpetual licenses to recurring subscriptions. Tier-one miners in Chile's copper belt now demand usage-based pricing tied to equipment availability metrics.
- Heavy Machinery:Autonomous haul trucks, drill rigs, and auxiliary equipment represent the largest capital outlay category. ABB leverages its electrification portfolio to anchor power-delivery systems for these fleets.
- Control Systems:Vehicle management platforms and safety controllers coordinate multi-vendor fleet operations.
- Communication Equipment:Edge-to-cloud networking infrastructure enables centralized fleet orchestration from surface control centers.
Heavy Machinery absorbs the largest capital share; Software Solutions is gaining share fastest as vendors pivot to recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian iron ore exports to Chinese steel mills anchor the trade corridor for autonomous haulage systems. Pilbara-based tier-one miners operate the world's largest proven fleet of driverless trucks, creating reference architectures that accelerate procurement across copper and gold operations worldwide.
Australia
Western Australia's Pilbara district hosts concentrated autonomous haulage deployment, with tier-one miners expanding fleet orders to copper and gold sites. State regulators administer the Work Health and Safety Act, mandating autonomous-equipment interoperability standards for emergency shutdown protocols. Perth-based control centers now orchestrate pit-to-port operations across multiple mine sites simultaneously.
Chile
Copper belt operators accelerate underground fleet replacement as safety mandates tighten operational requirements. The Superintendencia de Minería standards compel capital expenditure on remote-operated equipment in hazardous classifications. Antofagasta and Calama mining clusters drive demand for AI-enabled hazard detection in underground emergency protocols.
United States
Underground metal mines deploy remote-operated drilling equipment to eliminate human entry into confined spaces. OSHA mandates directly shape procurement specifications, disqualifying non-compliant vendors from tier-one corporation tenders. Arizona and Nevada copper-gold districts concentrate autonomous retrofit activity as legacy manned rigs reach replacement cycles.
Canada
Saskatchewan's deep shaft potash mines remain underpenetrated by autonomous haulage, presenting first-mover opportunities for cold-climate battery-electric systems. Provincial safety regulators align with federal standards for remote-operation capabilities in hazardous zones. Saskatoon-based engineering firms specify multi-vendor interoperability to avoid single-source dependencies.
China
Domestic mining corporations accelerate automation procurement to offset labor cost pressures in remote western provinces. National standards under MIIT and GB certification frameworks shape vendor qualification for autonomous vehicle deployments. Inner Mongolia and Xinjiang coal districts concentrate fleet-scale trials of electrified autonomous haul trucks.
Mining Automation Solutions Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. The vendor base concentrates around electrification systems, ultra-class haulage platforms, and underground precision equipment, with each cluster defending distinct technical moats. Strategic archetypes span integrated industrial conglomerates, automation-focused technology vendors, and specialized mining equipment manufacturers. Competitive moves center on strategic partnerships for sensor fusion stacks and portfolio diversification into predictive analytics subscriptions.
Within the integrated industrial tier, ABB leverages its electrification portfolio to anchor power-delivery systems for autonomous fleets. Komatsu occupies a dominant position in ultra-class haul truck automation through its FrontRunner system deployed across multiple continents. Sandvik AB exemplifies the underground precision specialist archetype, competing on accuracy in confined orebody extraction where path tolerances compress to 10-centimeter specifications.
| Leading Market Players |
|---|
| Epiroc AB |
| ABB |
| Caterpillar |
| Rockwell Automation |
| Hexagon |
| Komatsu |
| Hitachi Construction Machinery |
| Plotlogic |
| Sandvik AB |
| Others |
Cost & Logistics Intelligence
Western Australia's Pilbara mining cluster concentrates autonomous haul truck deployment capacity, with tier-one operators leveraging fleet-scale procurement to compress unit pricing from Komatsu and Caterpillar. This geographic supply concentration amplifies buyer power while sensor component bottlenecks upstream create asymmetric margin pressure on mid-tier vendors.
Pricing Analysis
Cost-plus contracts indexed to LiDAR sensor pricing and battery-electric drivetrain commodities dominate fleet-scale negotiations. Three-tier pricing structure across premium automation tiers, standard retrofit packages, and economy remote-control configurations separates vendors by certification grade and interoperability compliance. Pricing pressure stems from Chilean copper belt miners demanding usage-based SaaS models tied to equipment availability metrics. Tier-two underground operators exhibit highest price sensitivity due to capital constraints, while Pilbara iron ore majors prioritize technical qualification over unit cost.
Supply Chain Analysis
High-specification mining-grade LiDAR sensors concentrate among suppliers in Germany and the United States, with solid-state radar components sourced from South Korean and Japanese electronics manufacturers. Autonomous fleet production draws from copper cabling infrastructure in China, battery cell supply from South Korean producers, and GNSS positioning modules from European specialists. Single-source vulnerability in LiDAR procurement creates fleet-deployment bottlenecks during scale-up phases. Distribution runs through OEM-integrated channels for new-build equipment and specialized retrofit contractors for legacy fleet conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Australia's interoperability mandates for emergency shutdown protocols are dissolving vendor lock-in advantages. The shift from perpetual software licenses to recurring telemetry subscriptions restructures lifetime value capture toward analytics-native entrants.
For Market Incumbents: Insulate embedded base positions by deepening backward integration into sensor fusion hardware and securing IEC 62443 cybersecurity certification ahead of procurement qualification timelines. Komatsu and Sandvik AB must accelerate predictive analytics subscription penetration to offset eroding software lock-in from open-interface mandates. Capacity addition in Saskatchewan's potash belt and Chile's copper districts defends geographic share against battery-electric specialists.
For New Entrants and Emerging Players: Saskatchewan's deep shaft potash mines present first-mover whitespace for cold-climate battery-electric autonomous haulage systems currently underpenetrated by incumbent fleets. Canadian provincial safety regulators' multi-vendor interoperability specifications lower qualification barriers for new automation stacks. Target analytics-as-a-service entry through usage-based pricing models that transfer performance risk from capital-constrained mid-tier miners.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled hazard detection specialists with Chilean Superintendencia de Minería certification and underground drill rig autonomy precision capabilities. Long-term viability hinges on recurring revenue share from telemetry subscriptions rather than hardware shipment volumes. Monitor convergence between autonomous equipment standards and IEC 62443 cybersecurity protocols as inflection signal for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital-Twin Certification | Western Australian tier-one miners now require virtual validation before fleet automation capital approval. |
| Sensor Fusion Partnership | LiDAR-GNSS integration alliances compress path accuracy to 10-centimeter tolerances for GPS-denied environments. |
| Interoperability Standard Adoption | Australia's emergency shutdown protocol mandates force proprietary interface opening across vendor ecosystems. |
| Cold-Climate Battery-Electric Development | Saskatchewan potash applications demand thermal management systems absent from incumbent desert-optimized fleets. |
| Analytics Subscription Pivot | Chilean copper belt usage-based pricing transfers availability risk to vendors while capturing lifetime data value. |
Research Approach
A standing panel of mine operations directors, autonomous fleet managers, OEM procurement leads, and mining safety regulators provided ongoing calibration across primary interview cycles. This practitioner input combined with secondary validation from SEC 10-K filings, Australian state regulatory submissions, Chilean Superintendencia de Minería standards documentation, and customs trade data for autonomous vehicle components. Bottom-up unit economics modeling and top-down industry aggregation triangulated volume and value estimates.
Scenario-bracketing around copper price volatility, battery-electric adoption curves, and regulatory compliance timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology maturity tier, surface versus underground application, software monetization model, and regional safety regulatory cluster. CAGRs derived from fitted growth curves incorporating fleet replacement cycle data and capital expenditure pipeline visibility from tier-one mining corporations.
Practitioners should monitor LiDAR sensor supply allocation, IEC 62443 certification queue lengths, and Chilean glacier protection permitting timelines for early signals of forecast revision. Quarterly review of OEM order backlogs, mining corporation automation capital guidance, and battery-electric pilot program conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Motion Control Centers Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Europe Industrial Embedded Systems Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Drilling Automation Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Global Industrial Control and Factory Automation Market