
 Global SCADA Market | 2026-2036
Global SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
Global SCADA Market Outlook
Project finance and operational leasing for industrial automation infrastructure is rewriting competitive dynamics in the Global SCADA Market. Schneider Electric SE leverages its integrated software-hardware stack to anchor long-term service contracts with energy utilities. Siemens AG competes through deep manufacturing scale across PLC and HMI product lines. Honeywell International Inc. differentiates via specialized cybersecurity layers embedded within its control architectures.
Supervisory Control and Data Acquisition (SCADA) denotes a centralized industrial control system that aggregates real-time data from remote terminal units (RTUs) and programmable logic controllers (PLCs) through human-machine interfaces (HMIs), typically operating with sub-100 millisecond response cycles for critical process commands. Its primary purpose is enabling continuous monitoring, automated control, and exception-based alerting across geographically dispersed physical infrastructure. Cloud-based deployment is expanding fastest as operators seek to reduce capital intensity, though on-premises architectures still dominate where air-gapped security remains mandatory. Within end-user verticals, energy and water utilities command the largest installed base, while manufacturing applications are generating disproportionate margin pools through advanced analytics integration.
The US EPA enforces Safe Drinking Water Act mandates that compel municipal utilities to deploy continuous monitoring and remote-control capabilities, directly expanding SCADA procurement scope. In Europe, the EU Cybersecurity Act and IEC 62443 standards are reshaping product certification requirements, forcing vendors to redesign architectures for encrypted communications and supply-chain traceability. Stakeholders must monitor how diverging national cybersecurity frameworks affect cross-border system interoperability and vendor qualification pathways.

Market Dynamics
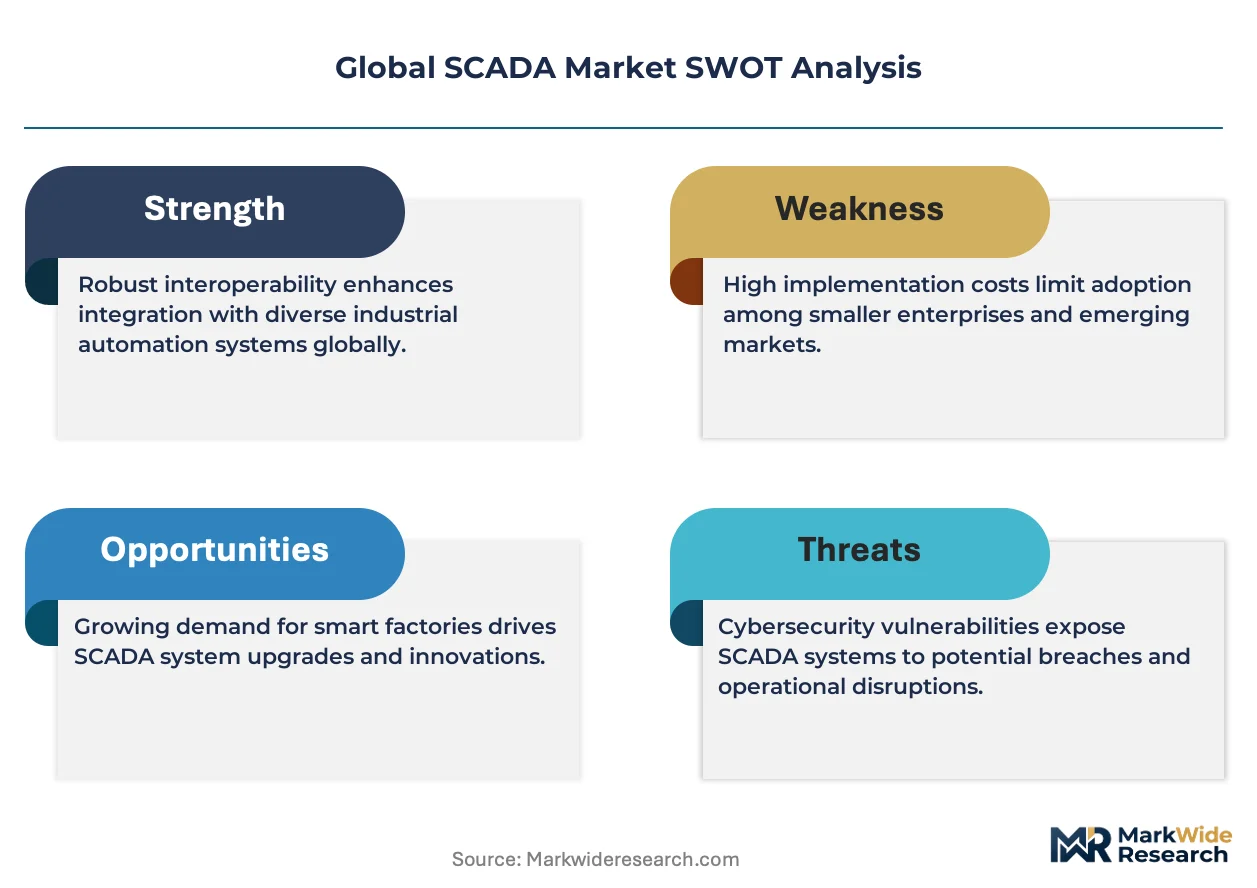
Legacy SCADA architectures face forced obsolescence as encrypted, interoperable designs mandated by the EU Cybersecurity Act and NIS2 Directive displace proprietary protocols across European utilities.
Growth Catalysts
- EU NIS2 Directive:Infrastructure operators must upgrade legacy systems with encrypted architectures, expanding procurement scope for compliant vendors.
- Water utilities:US EPA Safe Drinking Water Act mandates compel municipal operators to deploy continuous monitoring and remote-control capabilities.
- Cloud-based deployment:Operators seek reduced capital intensity, accelerating adoption where air-gapped security is not mandatory.
Market Restraints
- Semiconductor supply concentration:PLC and RTU production depends on concentrated Asian foundry capacity, creating vulnerability to trade friction.
- Legacy protocol lock-in:Proprietary communication standards in installed bases impede interoperability with modern encrypted architectures.
- Extended certification timelines:IEC 62443 compliance testing stretches vendor product launch cycles by 12-18 months.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives and CEA grid modernization mandates create underpenetrated demand for utility-scale SCADA.
- Edge-to-cloud convergence:Integration of field-level analytics with centralized SCADA platforms enables predictive maintenance services.
- Brazil water infrastructure:ANVISA environmental compliance requirements and federal sanitation programs drive greenfield SCADA deployment.
Industry Challenges
- OT cybersecurity talent scarcity:Utilities and manufacturers compete for engineers credentialed in both industrial control systems and threat detection.
- Multi-vendor integration complexity:Operators struggle to unify PLC, HMI, and RTU assets from disparate suppliers under single monitoring architectures.
- Air-gapped system migration:Critical infrastructure operators face operational risk when transitioning isolated legacy networks to connected architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SCADA Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
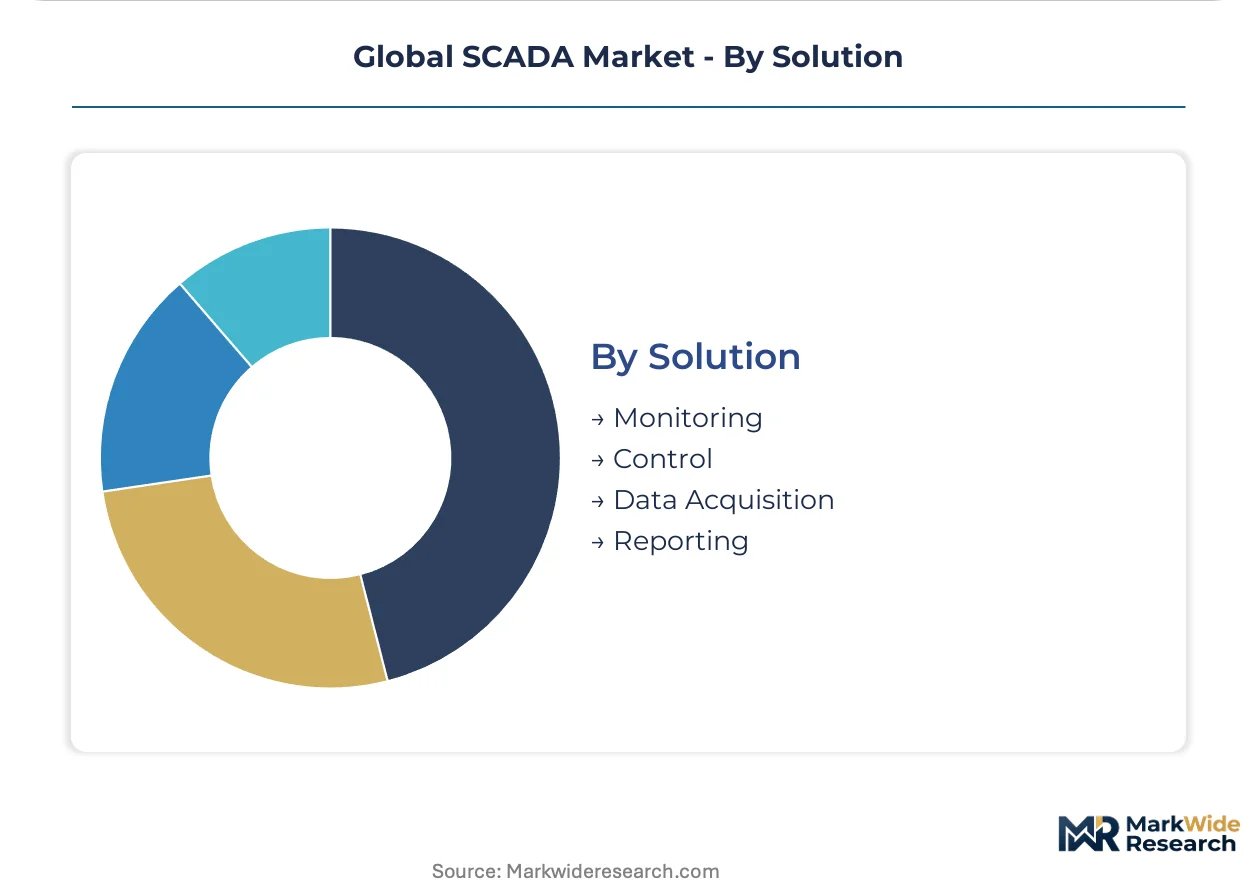
| Segmentation | Technology: SCADA Software, RTU, PLC, HMI, IoT Devices End User: Manufacturing, Energy, Water & Wastewater, Transportation Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution: Monitoring, Control, Data Acquisition, Reporting |
| Companies Covered | Schneider Electric SE, Honeywell International Inc., ABB Ltd., Yokogawa Electric Corporation, General Electric Co., Emerson Electric Co., Siemens AG, Omron Corporation, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SCADA Market Strategic Shifts
SCADA functionality is fragmenting across edge, fog, and cloud layers as operators demand localized decision-making without sacrificing centralized visibility.
Edge-native SCADA nodes with embedded analytics is collapsing the traditional hierarchy where all data flowed to centralized servers. Water treatment facilities in Germany deploy these units for real-time contaminant detection. The architecture compresses response latency from seconds to milliseconds for critical process commands.
The EU Cybersecurity Act mandates Common Criteria certification for critical infrastructure components. Vendors redesign hardware with secure boot chains and encrypted firmware update channels. German utility procurement specifications now exclude uncertified suppliers from tender participation.
Buying committees now unbundle hardware procurement from long-term service contracts, reversing historical bundled sales models. Energy utilities in Texas and California negotiate separate agreements for PLC supply, software licensing, and cybersecurity monitoring. This pattern fragments vendor revenue streams and elevates specialized cybersecurity providers.
Global SCADA Market Segmentation

SCADA procurement patterns diverge sharply across technology layers and deployment architectures. Understanding these fault lines reveals where vendor margins concentrate and which integration pathways dominate customer buying cycles.
Technology:
Cost tier determines how procurement committees structure vendor evaluation and long-term service contracting.
- SCADA Software:Platform layers orchestrate data aggregation, visualization, and alarm management across distributed assets. German utilities now mandate Common Criteria certification for software procurement, disqualifying uncertified vendors from tender participation.
- RTU:Remote terminal units execute field-level data collection and command relay with hardened environmental ratings. Water treatment operators in Texas prioritize RTU deployments that satisfy EPA Safe Drinking Water Act continuous monitoring mandates.
- PLC:Programmable logic controllers deliver deterministic process control with sub-millisecond cycle times.
- HMI:Human-machine interfaces render operational dashboards for control room operators.
- IoT Devices:Wireless sensors and actuators extend SCADA reach into previously unmonitored physical infrastructure.
SCADA Software commands the established base. The steepest expansion runs through IoT Devices.
End User:
Application-specific compliance pressures reshape how each vertical evaluates system architecture and cybersecurity posture.
- Energy:Power generation and transmission operators deploy SCADA for grid stability management and distributed asset coordination. US FERC reliability standards and EU NIS2 Directive compliance timelines are accelerating replacement of legacy proprietary protocols.
- Water & Wastewater:Municipal utilities require continuous contaminant monitoring and remote valve control to satisfy environmental discharge permits. Brazilian federal sanitation programs and ANVISA requirements are driving greenfield SCADA installation across treatment facilities.
- Manufacturing:Discrete and process industries integrate SCADA with MES and ERP layers for production optimization.
- Transportation:Rail signaling, tunnel ventilation, and port cargo handling systems depend on SCADA for safety-critical automation.
Energy commands the established base. Water & Wastewater is climbing the fastest.
Deployment:
Customer type—specifically critical infrastructure versus commercial manufacturing—dictates acceptable risk profiles for network connectivity.
- Cloud-Based:Centralized hosting reduces capital intensity and enables predictive analytics at scale. European manufacturing clusters adopt cloud SCADA where IEC 62443 security level certification satisfies insurance underwriters.
- On-Premises:Air-gapped architectures remain mandatory for nuclear, defense, and certain water treatment applications. Indian CEA grid codes explicitly require on-premises control systems for transmission substations above specified voltage thresholds.
- Hybrid:Architectures partition sensitive control functions locally while pushing analytics workloads to cloud infrastructure.
- Edge Computing:Field-native processing collapses response latency for time-critical automation loops.
On-Premises commands the established base. Edge Computing is gaining share fastest.
Solution:
Margin structure varies with solution maturity—monitoring and control functions commoditize while integrated analytics command premium pricing.
- Control:Closed-loop automation executes setpoint adjustments and emergency shutdown sequences. German industrial clusters specify control solutions with embedded IEC 62443-3-3 zone segmentation for cyber resilience.
- Data Acquisition:Sensor integration, protocol conversion, and time-series database management form the SCADA data foundation. US EPA enforcement of Safe Drinking Water Act mandates is expanding acquisition system scope for municipal utilities.
- Monitoring:Real-time visualization and exception-based alerting for operational personnel.
- Reporting:Regulatory compliance documentation and performance analytics for external stakeholders.
Control commands the established base. Data Acquisition shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global SCADA Market exhibits a pronounced export-import imbalance, with European and North American vendors supplying encrypted control architectures to infrastructure operators across Asia-Pacific and Latin America while importing specialized semiconductor components from East Asian foundries.
United States
Municipal water utilities and independent grid operators drive procurement volume. EPA Safe Drinking Water Act enforcement mandates continuous monitoring systems for treatment facilities serving populations above 10,000. Texas energy utilities negotiate unbundled contracts for PLC hardware, software licensing, and cybersecurity monitoring separately.
Germany
Industrial clusters in Bavaria and North Rhine-Westphalia concentrate demand for IEC 62443-certified architectures. The EU Cybersecurity Act and NIS2 Directive force replacement of proprietary protocols with encrypted, interoperable designs. Utility procurement specifications now exclude uncertified vendors from tender participation entirely.
China
State Grid Corporation modernization programs and CEA grid codes create demand for transmission substation automation above specified voltage thresholds. Domestic PLC and RTU production scales rapidly, though advanced control software still imports from European suppliers. Yangtze River Delta manufacturing clusters deploy edge-native SCADA nodes for real-time process optimization.
India
PLI scheme incentives and CEA grid modernization mandates generate underpenetrated demand for utility-scale SCADA across industrial corridors. Gujarat and Maharashtra host concentrated procurement for water treatment automation. Federal programs prioritize on-premises architectures for critical infrastructure air-gap requirements.
Brazil
ANVISA environmental compliance requirements and federal sanitation programs accelerate greenfield SCADA deployment across water treatment facilities. São Paulo and Rio de Janeiro metropolitan utilities modernize legacy systems to meet discharge permit mandates. Procurement concentrates on integrated monitoring and control solutions with localized Portuguese-language support.
Global SCADA Market Competitive Environment
On the supply side, the industry is consolidating around integrated software-hardware stacks that anchor long-term service contracts. Tiered vendor structures separate full-stack industrial conglomerates from specialized cybersecurity layer providers and regional PLC fabricators. Two dominant competitive moves are reshaping positioning: vendors acquire edge analytics startups to collapse response latency, and European players restructure product lines to satisfy Common Criteria certification timelines.
Within the full-stack tier, Schneider Electric SE, Siemens AG, and Honeywell International Inc. exemplify divergent strategic anchors. Schneider Electric SE occupies a position centered on integrated software-hardware stacks with energy utilities. Siemens AG represents manufacturing-scale depth across control product lines. Honeywell International Inc. exemplifies differentiation through embedded cybersecurity architectures. These three anchors illustrate how vendor archetypes map to distinct procurement committee evaluation criteria across utility and manufacturing verticals.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc. |
| ABB Ltd. |
| Yokogawa Electric Corporation |
| General Electric Co. |
| Emerson Electric Co. |
| Siemens AG |
| Omron Corporation |
| Rockwell Automation Inc. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp industrial corridor freight differential compresses margins for PLC and RTU imports from East Asian foundries while amplifying price spreads between IEC 62443-certified and uncertified SCADA architectures. German utilities exploit this logistics chokepoint to negotiate volume discounts on encrypted control systems, forcing vendors to absorb tariff exposure or cede tender participation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under IEC 62443 and volume scale drive price differentiation, with air-gapped on-premises deployments commanding substantial premiums over cloud-based alternatives. Pricing pressure stems from semiconductor supply concentration as Asian foundry capacity constraints elevate PLC and RTU input costs. Municipal water utilities exhibit acute price sensitivity due to EPA compliance mandates stretching capital budgets, while German energy operators prioritize certification over cost.
Supply Chain Analysis
Silicon wafer and industrial-grade microcontroller supply draws from Taiwan, South Korea, and Japan. PLC and RTU production rests on concentrated foundry capacity, specialized memory components, and hardened enclosure materials. Single-source vulnerability in advanced node semiconductor fabrication creates exposure to trade friction and export licensing restrictions. Distribution runs through authorized system integrators and direct vendor relationships with national utility procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCADA market is approaching a platform-economics inflection where interoperability standards mandated by the EU Cybersecurity Act are collapsing proprietary protocol moats and redistributing value toward certified software layers.
For Market Incumbents: Insulate service revenue streams by embedding predictive analytics into long-term maintenance contracts before edge-native competitors disintermediate centralized platforms. Accelerate IEC 62443-3-3 zone segmentation certification across product lines to disqualify uncertified rivals from German utility tenders. Deepen backward integration into secure boot chain hardware to control firmware update channel integrity. For New Entrants and Emerging Players: Pursue white-space opportunities in Brazil's ANVISA-mandated water treatment modernization and India's CEA-grid-code transmission substation automation. Brazilian federal sanitation programs offer the most penetrable geography due to localized Portuguese-language support gaps among incumbent vendors. Establish beachheads through edge-native SCADA nodes with embedded contaminant detection analytics, selling direct to municipal operators bypassing traditional system integrator channels. For Investors and Strategic Acquirers: The EU NIS2 Directive implementation timeline reshapes the acquisition landscape by compressing vendor qualification windows and elevating certified architecture premiums. Five-to-ten year viability favors targets with demonstrated Common Criteria certification velocity and recurring software revenue above forty percent of total. Monitor German utility tender exclusion rates for uncertified suppliers as the inflection signal indicating certification scarcity value.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Acquisition | Collapsing response latency from seconds to milliseconds secures German water treatment contracts. |
| Common Criteria Certification Investment | IEC 62443 compliance qualifies vendors for EU critical infrastructure procurement participation. |
| Long-term Service Contract Unbundling | Texas energy utilities now negotiate PLC supply, software licensing, and cybersecurity monitoring separately. |
| Regional System Integrator Partnership | Portuguese-language support capabilities unlock Brazilian ANVISA-mandated sanitation program opportunities. |
| Secure Boot Chain Hardware Integration | Encrypted firmware update channels satisfy EU Cybersecurity Act supply-chain traceability mandates. |
Study Parameters
Cross-validation between utility procurement committee interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged control system engineers, municipal water utility directors, energy grid operators, and industrial automation procurement leads across Germany, the United States, Brazil, India, and China. Secondary sources encompassed FERC reliability standard documentation, EPA Safe Drinking Water Act enforcement records, EU NIS2 Directive implementation guidance, and CEA grid code technical specifications. Bottom-up vendor revenue triangulation against top-down infrastructure investment forecasts validated segmentation splits.
Calibration against historical certification timeline data and infrastructure replacement cycle patterns shaped the projection framework. Segmentation dimensions modeled include technology layer, deployment architecture, end-user vertical, and regional regulatory cluster. CAGRs were derived from infrastructure investment elasticity to compliance mandate intensity and vendor pricing response to semiconductor input cost movements. Forecast inputs incorporated utility capital expenditure survey data and foundry capacity expansion announcements.
Sensitivities concentrate around EU Cybersecurity Act enforcement velocity, foundry capacity allocation shifts, and air-gap security requirement persistence in critical infrastructure. Forecasts reflect assumptions regarding certification timeline compression and interoperability standard adoption rates. Cross-checking against IEA grid modernization investment benchmarks and national utility procurement database tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Grippers Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Robotic Paint Booth Market