
 Global Industrial Wireless Automation Market | 2026-2036
Global Industrial Wireless Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Wireless Automation Market Outlook
Industrial-grade wireless certification is bifurcating the competitive landscape into hardened-device specialists and general-purpose networking vendors. ABB Ltd. leverages its IEC 62443-compliant portfolio to anchor premium positioning in hazardous-environment deployments. Siemens AG sustains technology leadership through its integrated wireless IO systems for process industries. Schneider Electric SE differentiates via edge-to-cloud architectures that extend control beyond traditional plant boundaries.
Industrial wireless automation encompasses radio-frequency communication systems engineered for real-time data acquisition, distributed control, and asset monitoring in production environments, typically operating across unlicensed ISM bands or licensed cellular spectra with latency thresholds below 50 milliseconds for closed-loop control. These systems replace or augment wired fieldbus networks to enable mobile equipment tracking, predictive maintenance telemetry, and flexible line reconfiguration without cable infrastructure overhead. Wireless sensor networks lead product-type revenue contribution due to their penetration across rotating equipment health monitoring and environmental compliance applications. Edge computing deployments represent the fastest-expanding deployment architecture as manufacturers localize analytics to reduce backhaul dependency and cloud latency. LoRa technology occupies a distinct growth corridor in geographically dispersed asset monitoring where ultra-low power consumption outweighs bandwidth requirements.
The International Electrotechnical Commission shapes device interoperability through IEC 62443 cybersecurity frameworks, while the European Telecommunications Standards Institute governs spectrum allocation for industrial 5G private networks. In the United States, the Federal Communications Commission's CBRS spectrum licensing has unlocked private LTE deployments for manufacturing campuses without carrier dependency. China's Ministry of Industry and Information Technology accelerates domestic adoption through dedicated 5G industrial frequency assignments and GB standards convergence. Stakeholders must monitor evolving spectrum policy fragmentation across jurisdictions, as divergent national allocations for unlicensed industrial bands will determine whether multi-site wireless architectures require region-specific hardware configurations or unified global platforms.
Market Dynamics
Industrial wireless automation faces a structural compression between legacy fieldbus replacement cycles and accelerated cybersecurity mandates from IEC 62443 and the EU Cyber Resilience Act, forcing manufacturers to recertify installed bases while greenfield deployments demand native compliance.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security-by-design requirements for connected devices are accelerating hardware refresh cycles across European process industries.
- Oil and gas pipeline monitoring:Operators in remote extraction regions are deploying wireless sensor networks to eliminate trenching costs for fiber optic cable runs.
- LoRa technology:Ultra-low power wide-area protocols are penetrating geographically dispersed asset monitoring where cellular backhaul remains uneconomical.
Market Restraints
- Semiconductor supply concentration:Industrial-grade radio frequency chip fabrication clusters in Taiwan create vulnerability for hardened-device lead times.
- Spectrum fragmentation:Divergent national allocations for unlicensed industrial bands force hardware variants that inflate inventory and certification costs.
- Limited battery chemistry options:Primary lithium thionyl chloride cells face shipping restrictions that complicate wireless sensor network deployment logistics.
Strategic Opportunities
- India heavy manufacturing modernization:PLI scheme incentives for advanced process control are opening greenfield wireless automation adoption in steel and cement.
- Private 5G industrial networks:Germany's dedicated campus spectrum licenses enable latency-critical closed-loop control without carrier dependency.
- Edge-to-cloud architecture convergence:Integration of wireless IO systems with containerized analytics creates service revenue streams beyond hardware sales.
Industry Challenges
- IEC 62443 certification timelines:Multi-stage security level assessments extend product launch windows by 12-18 months for process industry vendors.
- OT-IT integration skill scarcity:Control engineers with simultaneous expertise in industrial protocols and enterprise cybersecurity command premium compensation that strains project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Wireless Automation Market |
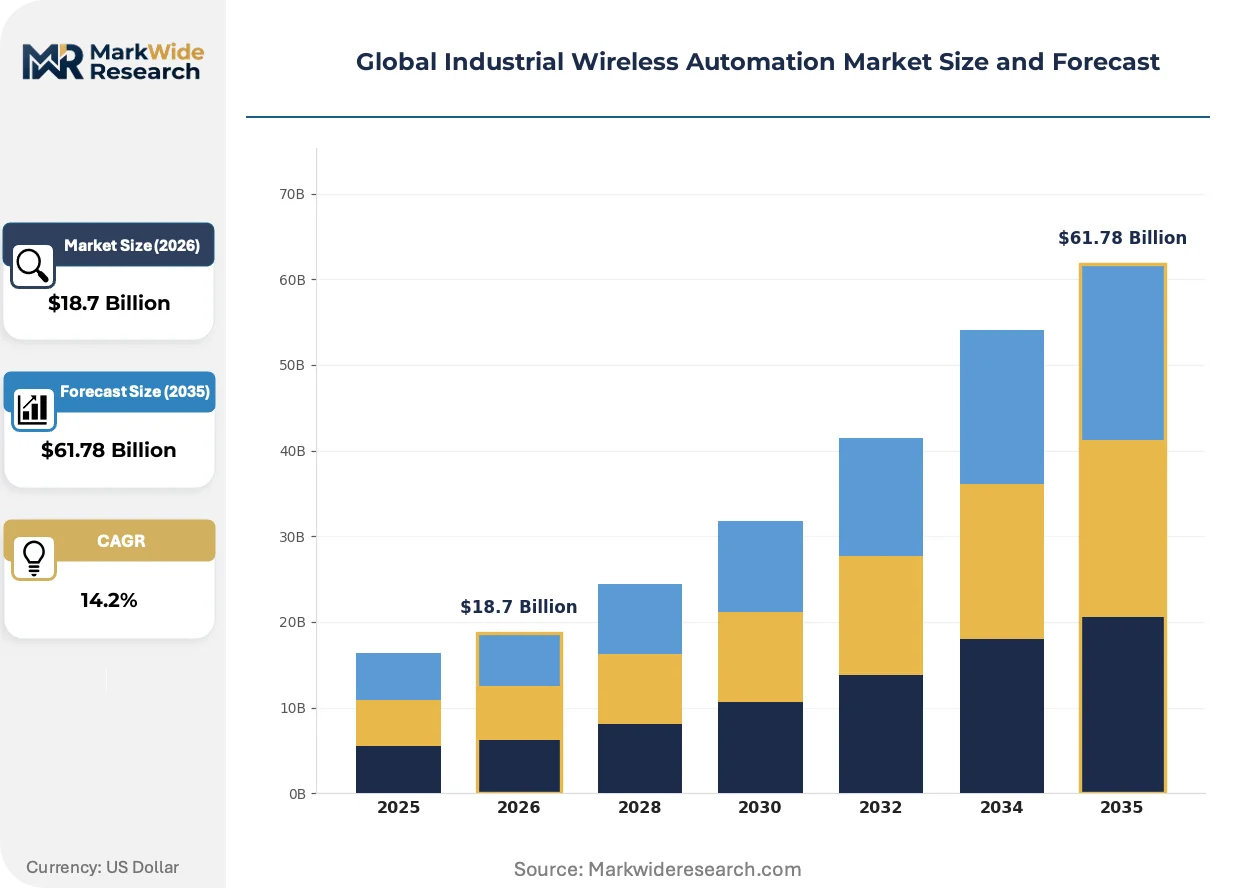
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Wireless Control Systems, Wireless Transmitters, Wireless Networks Technology: Wi-Fi, Zigbee, Bluetooth, LoRa End User: Manufacturing, Oil & Gas, Mining, Chemicals Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Schneider Electric SE, ABB Ltd., Siemens AG, Emerson Electric Co., Rockwell Automation Inc., Cisco Systems Inc., Honeywell International Inc., Omron Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Wireless Automation Market Strategic Shifts
Wireless automation architectures are bifurcating between latency-optimized private cellular and power-optimized LPWAN deployments, with edge computing localization emerging as the dominant response to cloud dependency risks.
Time-Sensitive Networking over wireless is fragmenting real-time control applications previously monopolized by wired fieldbus systems. Process manufacturers in Germany and the United States are piloting 802.11-based deterministic protocols for mobile robot coordination. This fragmentation is compressing the addressable market for traditional Profibus and Foundation Fieldbus gateway hardware.
China's MIIT 5G industrial frequency assignments are mandating domestic security modules that diverge from global 3GPP standards. Equipment vendors must maintain parallel hardware SKUs for Chinese deployments versus other markets. State-owned refineries and chemical complexes are accelerating adoption under government-directed modernization quotas.
Asset-as-a-service contracting is displacing capital purchase models for wireless sensor networks in rotating equipment monitoring. Vibration analysis vendors in the United States now bundle hardware, connectivity, and predictive algorithms under per-asset monthly fees. This shift is most pronounced in pulp and paper mills seeking to convert fixed automation costs to variable operating expenses.
Global Industrial Wireless Automation Market Segmentation
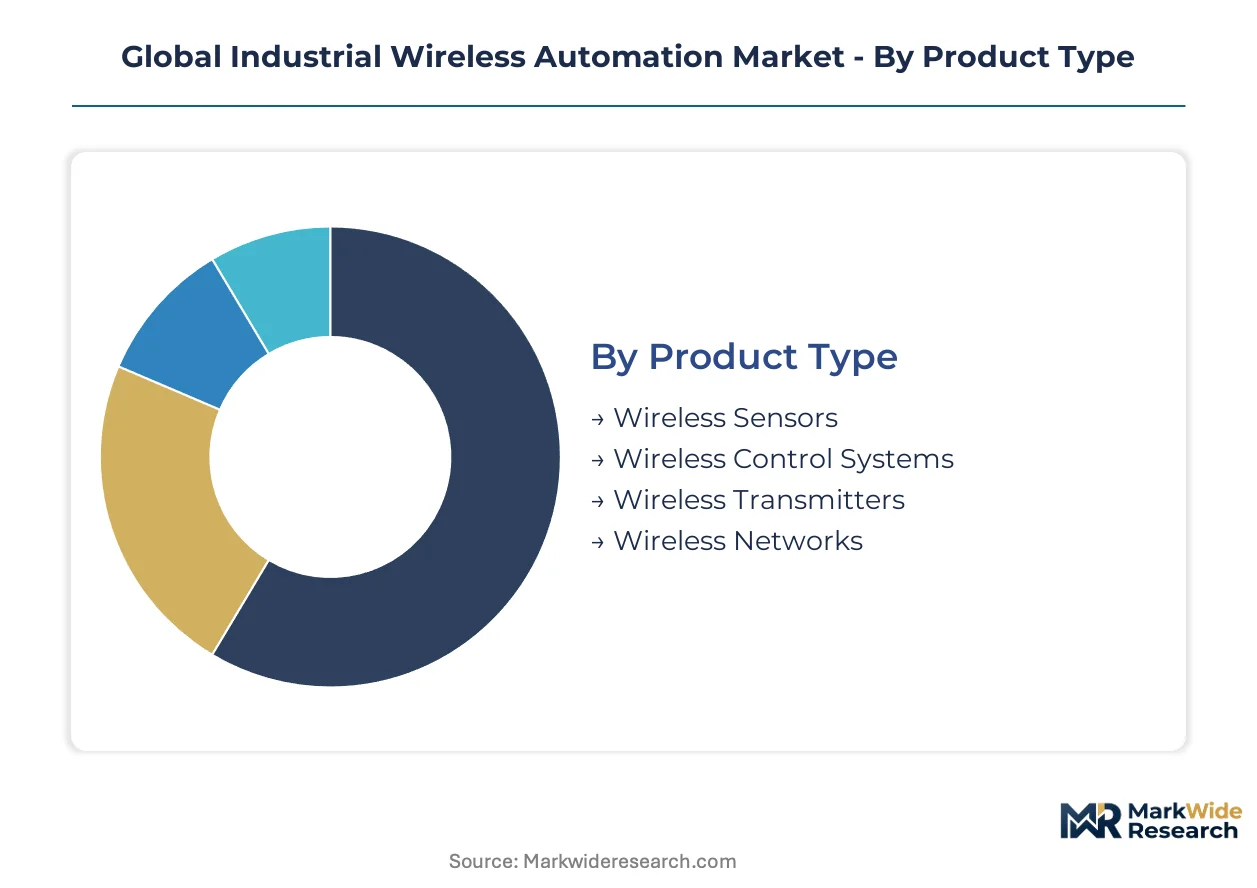
Industrial wireless automation segments diverge sharply in margin structure. Product type stratification separates commodity sensor hardware from premium control systems with embedded cybersecurity. Technology choice determines power-latency tradeoffs that reshape deployment economics across process industries.
Product Type:
Margin pools concentrate in control systems with integrated safety certification, while sensor hardware faces commoditization pressure from Asian module suppliers.
- Wireless Sensors:Battery-powered devices measuring vibration, temperature, pressure, and flow parameters transmit data via low-power protocols. Demand clusters in German automotive paint shops and US Gulf Coast refineries where predictive maintenance programs justify hardware refresh cycles under IEC 62443 mandates.
- Wireless Control Systems:Programmable automation controllers with hardened radio modules execute closed-loop regulation without wired fieldbus dependency. Oil and gas operators in Norway's North Sea platforms specify these for emergency shutdown systems where latency below 20 milliseconds is mandatory.
- Wireless Transmitters:Signal conditioning devices bridge legacy 4-20mA instruments to digital wireless backbones.
- Wireless Networks:Mesh infrastructure and gateway hardware aggregate sensor traffic for plant-wide coverage.
Wireless Control Systems hold installed capacity. Wireless Sensors is rotating up the share rankings.
Technology:
Volume concentration favors Wi-Fi for indoor manufacturing, while LoRa captures the steepest expansion trajectory in geographically dispersed asset monitoring.
- Wi-Fi:IEEE 802.11-based implementations dominate indoor manufacturing deployments with throughput sufficient for video-enabled remote assistance. Chinese electronics assembly plants in Shenzhen and Chengdu deploy Wi-Fi 6E for automated guided vehicle coordination.
- LoRa:Chirp spread spectrum modulation enables 10-year battery life for sensors monitoring pipelines across Kazakhstan's Kashagan field and Australia's Pilbara iron ore rail networks. Ultra-low power consumption outweighs bandwidth constraints for non-critical telemetry.
- Zigbee:Mesh networking protocol serves building automation and lighting control within plant facilities.
- Bluetooth:Short-range connectivity supports handheld diagnostic tools and wearable safety devices.
Wi-Fi anchors current deployment volumes. LoRa is climbing the fastest among protocol choices.
End User:
Application intensity varies by hazard classification and remoteness, with oil and gas commanding premium pricing for explosion-proof certification.
- Manufacturing:Discrete automation in automotive and electronics assembly drives high-volume sensor deployment for quality tracking and line balancing. German OEMs integrate wireless IO for flexible reconfiguration between electric vehicle and internal combustion powertrain variants.
- Oil & Gas:Upstream extraction and midstream pipeline operations deploy wireless for assets unreachable by fiber trenching. US Permian Basin operators eliminate trenching costs across 50-mile gathering networks using solar-powered LoRa sensors.
- Mining:Open-pit and underground operations track fleet position and equipment health in radio-shadowed terrain.
- Chemicals:Process plants with hazardous area classifications require IECEx-certified hardware for reactor monitoring.
Manufacturing leads unit shipments. Oil & Gas commands revenue per node.
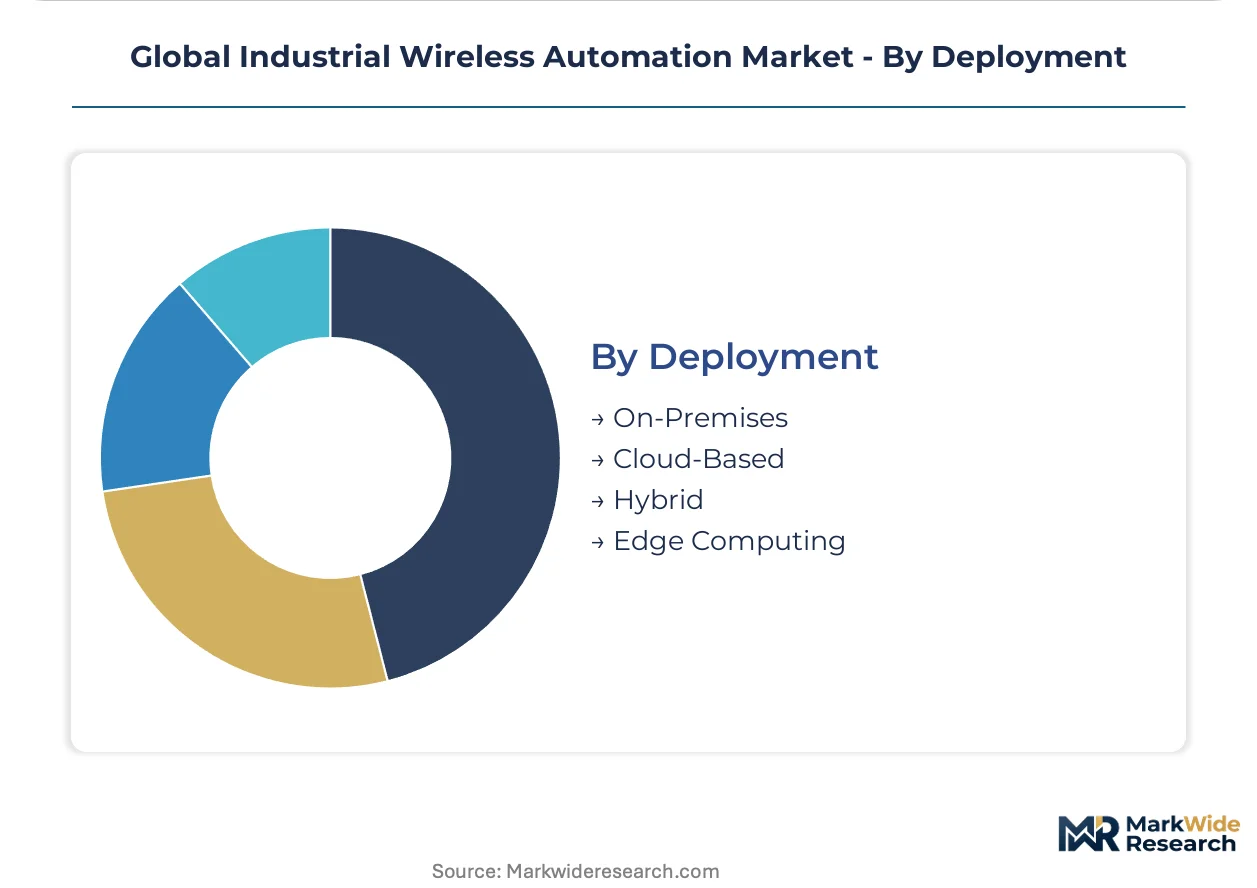
Deployment:
Architecture choice determines data sovereignty posture and ongoing service revenue potential for systems integrators.
- Edge Computing:Containerized analytics execute on ruggedized gateways within 50 meters of production equipment. Japanese automotive stamping plants in Toyota City localize defect detection to avoid cloud latency in sub-100-millisecond quality gates.
- Cloud-Based:Centralized data lakes support cross-fleet benchmarking and machine learning model training. Indian cement producers under the PLI scheme aggregate kiln telemetry from 12 regional plants for centralized process optimization.
- On-Premises:Private server infrastructure maintains air-gapped operation for defense and nuclear applications.
- Hybrid:Tiered architectures route critical control locally while pushing historical data to cloud analytics.
Edge Computing is gaining share fastest. Cloud-Based retains the broadest addressable footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for IEC 62443-certified hardware, while Indian and Chinese operators prioritize cost-optimized LoRa deployments for geographically dispersed assets.
United States
Permian Basin oil and gas operators deploy solar-powered wireless sensor networks across 50-mile gathering systems to eliminate fiber trenching costs. The FCC's CBRS spectrum licensing enables private LTE campus networks without carrier dependency. Gulf Coast refineries in Texas and Louisiana specify explosion-proof wireless transmitters for hazardous area monitoring under OSHA process safety mandates.
Germany
Automotive OEMs in Stuttgart and Munich integrate wireless IO systems for flexible reconfiguration between electric vehicle and internal combustion powertrain variants. The Federal Network Agency's dedicated 5G industrial campus spectrum licenses support latency-critical closed-loop control applications. BASF's Ludwigshafen chemical complex pilots Time-Sensitive Networking over wireless for mobile robot coordination in batch processing.
China
Electronics assembly plants in Shenzhen and Chengdu deploy Wi-Fi 6E for automated guided vehicle coordination in high-density manufacturing cells. MIIT's 5G industrial frequency assignments mandate domestic security modules that diverge from global 3GPP standards. Sinopec's state-owned refineries accelerate wireless automation adoption under government-directed dual carbon modernization quotas.
India
Steel and cement producers under the PLI scheme for advanced process control open greenfield wireless automation adoption in Maharashtra and Gujarat. The Central Electricity Authority mandates remote monitoring capabilities for grid-connected industrial loads. Tata Steel's Jamshedpur complex aggregates kiln telemetry from regional plants for centralized process optimization via cloud-based architectures.
Japan
Automotive stamping plants in Toyota City localize edge computing gateways for defect detection to avoid cloud latency in sub-100-millisecond quality gates. METI's Society 5.0 initiative funds wireless sensor deployments for predictive maintenance in aging manufacturing infrastructure. Yokogawa Electric's Kofu facility serves as a demonstration site for 5G private network integration with existing DCS infrastructure.
Global Industrial Wireless Automation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the industrial wireless automation market. The vendor base stratifies into hardened-device specialists with IEC 62443 certification depth and general-purpose networking vendors competing on deployment scale. Three archetypes dominate: integrated automation conglomerates with process industry heritage, telecom infrastructure providers pivoting into private cellular, and LPWAN module specialists serving geographically dispersed asset monitoring. Competitive dynamics center on certification timeline acceleration and edge-to-cloud architecture integration.
Among integrated automation conglomerates, ABB Ltd., Siemens AG, and Schneider Electric SE exemplify divergent strategic positioning. ABB anchors the hazardous-environment premium tier through its IEC 62443-compliant portfolio. Siemens occupies technology leadership in wireless IO systems for process industries. Schneider Electric represents the edge-to-cloud convergence archetype, extending control architectures beyond traditional plant boundaries.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd. |
| Siemens AG |
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Cisco Systems Inc. |
| Honeywell International Inc. |
| Omron Corporation |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Taiwanese RF foundries shapes both supply concentration and price floors for industrial-grade wireless modules. Scale economies in hardened-device fabrication concentrate procurement leverage among IEC 62443-certified vendors, while fragmented demand across oil and gas, automotive, and process industries sustains tiered pricing stratification.
Pricing Analysis
The EU Cyber Resilience Act dictates the pricing tier structure for connected industrial devices. Pricing stratifies across premium, standard, and economy tiers based on IEC 62443 certification level and after-sales service bundling. Cost compression in sensor hardware is intensifying because Asian module suppliers are commoditizing battery-powered telemetry units. Discrete manufacturing buyers in German automotive exhibit highest price sensitivity, while North Sea oil and gas operators absorb premium positioning for explosion-proof certification.
Supply Chain Analysis
Taiwan Strait shipping lanes underwrite critical path dependencies for industrial-grade radio frequency chip fabrication. Manufacturing concentrates in Taiwan, South Korea, and China for RF transceivers, with Japan and Germany supplying precision sensor components. Supply chain risk centers on single-source vulnerability for hardened-device ASICs subject to export licensing. Distribution runs through authorized systems integrators with IEC 62443 certification credentials rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across spectrum policy, certification timelines, and deployment architectures creates niche entry points for specialists. Divergent national frequency allocations and cybersecurity mandates are spawning regional hardware variants that favor agile mid-tier vendors over global platforms.
For Market Incumbents: Fortify certification depth as the primary defensive moat. Accelerate IEC 62443 SL-3 and SL-4 assessment pipelines to compress 12-18 month launch windows. Expand captive foundry relationships in Japan and Germany to offset Taiwan concentration risk for RF module supply.
For New Entrants and Emerging Players: Edge-to-cloud integration services represent the most penetrable white space, as incumbent automation conglomerates under-serve containerized analytics deployment. Target India's PLI-backed steel and cement modernization for greenfield wireless IO adoption. Lead with subscription-based predictive maintenance bundling to bypass capital purchase friction in pulp and paper verticals.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors LPWAN module specialists with proven LoRa deployment scale in geographically dispersed asset monitoring. Five-to-ten year viability hinges on private 5G integration capabilities and edge computing software stacks. Monitor Germany's 5G campus spectrum license uptake as inflection signal for latency-critical control application migration.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Acceleration | SL-3 and SL-4 compliance unlocks premium positioning in hazardous-environment deployments for oil and gas operators. |
| Edge-to-Cloud Architecture Convergence | Containerized analytics integration creates recurring service revenue beyond hardware sales for systems integrators. |
| Private 5G Campus Network Deployment | Germany's BNetzA spectrum licenses enable sub-20 millisecond closed-loop control without carrier dependency. |
| LoRa Network Expansion | Ultra-low power protocols capture pipeline monitoring in Kazakhstan and Australia's Pilbara where cellular backhaul fails. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for advanced process control open greenfield adoption in Maharashtra steel complexes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and spectrum allocation databases. Interviews with plant engineers, automation procurement leads, systems integrators, and aftermarket service heads informed deployment architecture preferences. Secondary validation drew from FCC spectrum licensing records, IEC 62443 certification registries, MIIT frequency assignment disclosures, and SEC filings of publicly traded automation vendors. Bottom-up sensor shipment estimates and top-down industrial automation spending aggregates were cross-referenced for triangulation.
Segmentation dimensions modeled include product type, wireless protocol technology, end-user industry vertical, and deployment architecture across the analysis window. CAGRs were derived from growth driver elasticity modeling against historical adoption curves in comparable industrial technology transitions. Forecast inputs incorporated spectrum policy divergence scenarios, cybersecurity mandate implementation timelines, and semiconductor foundry capacity expansion plans.
Underlying assumptions cover sustained regulatory enforcement of IEC 62443 and EU Cyber Resilience Act provisions, with deviation risk concentrated in Taiwan semiconductor supply disruptions and divergent national spectrum allocations. Practitioners should keep alternative scenarios live as industrial 5G private network adoption rates and battery chemistry shipping regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
United States SCADA Market
Industrial Automation
HMI Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Factory Automation Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Global SCADA Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Asia-Pacific Medical Automation Market