
 Base Station Analyzer Market | 2026-2036
Base Station Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Base Station Analyzer Market Outlook
Open RAN disaggregation is reconfiguring how base station analyzers interface with multi-vendor radio units. Keysight Technologies leverages its calibration IP to anchor test workflows across ORAN splits. Rohde & Schwarz sustains R&D intensity in mmWave signal analysis for 5G NR validation. VIAVI Solutions Inc. competes through field-portable platforms that dominate drive-test and site-acceptance workflows.
A base station analyzer is a precision RF test instrument that measures transmitter and receiver performance across cellular air interfaces, typically covering frequency ranges from sub-6 GHz to mmWave bands with resolution bandwidths down to 1 Hz. The device validates modulation accuracy, spurious emissions, and adjacent channel power ratio to ensure network equipment meets 3GPP and operator-specific performance contracts. Handheld and portable analyzers lead volume shipments for field technicians performing tower climbs and drive tests, while rack-mounted systems capture margin pools in centralized lab validation environments. Network optimization and interference mitigation applications are absorbing the fastest growth as operators densify urban 5G layers and manage coexistence between LTE anchor bands and NR carriers.
The FCC enforces Part 27 and Part 96 rules for Citizens Broadband Radio Service and 3.5 GHz priority access, which shapes analyzer frequency coverage requirements for US network deployments. ETSI and 3GPP specifications in Europe define conformance test models that equipment vendors must pass before CE marking, directly determining which measurement personalities analyzer manufacturers prioritize in firmware roadmaps. China's MIIT issues network equipment入网许可 (network access licenses) with specific RF emission thresholds that drive localized calibration standards. Stakeholders must monitor how Open RAN security specifications from O-RAN Alliance WG1 reshape the boundary between traditional conformance testing and real-time threat detection in field instruments.
Market Dynamics
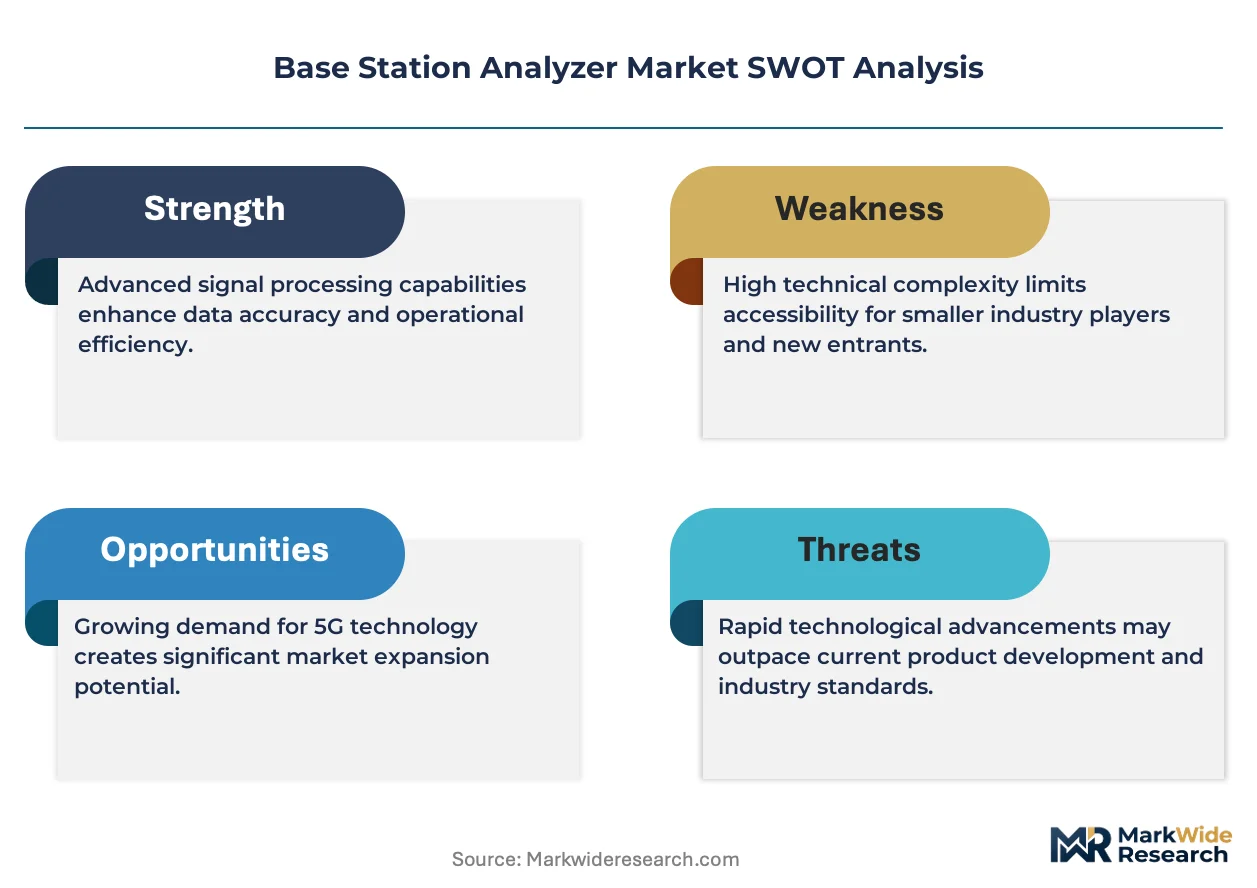
Open RAN disaggregation is fragmenting traditional test workflows, forcing analyzer vendors to support multi-vendor interoperability validation across ORAN splits while maintaining backward compatibility with legacy integrated baseband-radio architectures.
Growth Catalysts
- 5G network densification:Telecom operators in South Korea are accelerating analyzer procurement for urban small-cell deployments and indoor coverage solutions.
- FCC spectrum reallocation:Part 27 and Part 96 mandates for CBRS and 3.5 GHz priority access are forcing equipment refresh cycles across US network infrastructure.
- MIIT network access licensing:China's入网许可 requirements with specific RF emission thresholds are driving localized calibration standard adoption in Shenzhen and Beijing deployment corridors.
Market Restraints
- GaN and GaAs component supply concentration:Critical semiconductor substrates for mmWave front-end modules face sourcing bottlenecks from limited foundry capacity in East Asian supply chains.
- ETSI conformance test complexity:CE marking requirements under evolving 3GPP specifications extend firmware development cycles and increase certification costs for analyzer manufacturers.
- Handheld-portable substitution pressure:Software-defined radio platforms on commercial tablets are capturing low-end field test applications previously served by dedicated hardware.
Strategic Opportunities
- India's PLI scheme for telecom equipment:Production-linked incentives for domestic 5G manufacturing are creating localized analyzer demand for incoming quality assurance and production testing.
- O-RAN Alliance WG1 security specifications:Real-time threat detection integration into field instruments opens new revenue streams beyond traditional conformance testing.
- AI-driven network optimization convergence:Machine learning inference at the edge is hybridizing with RF analysis, enabling predictive maintenance and automated interference classification.
Industry Challenges
- mmWave signal analysis expertise scarcity:Field technicians lack training in 5G NR validation above 24 GHz, creating service delivery bottlenecks for drive-test and site-acceptance workflows.
- Multi-vendor integration complexity:ORAN split 7-2x and split 8 configurations demand simultaneous calibration across disaggregated radio units, digital units, and centralized units from different suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Station Analyzer Market |
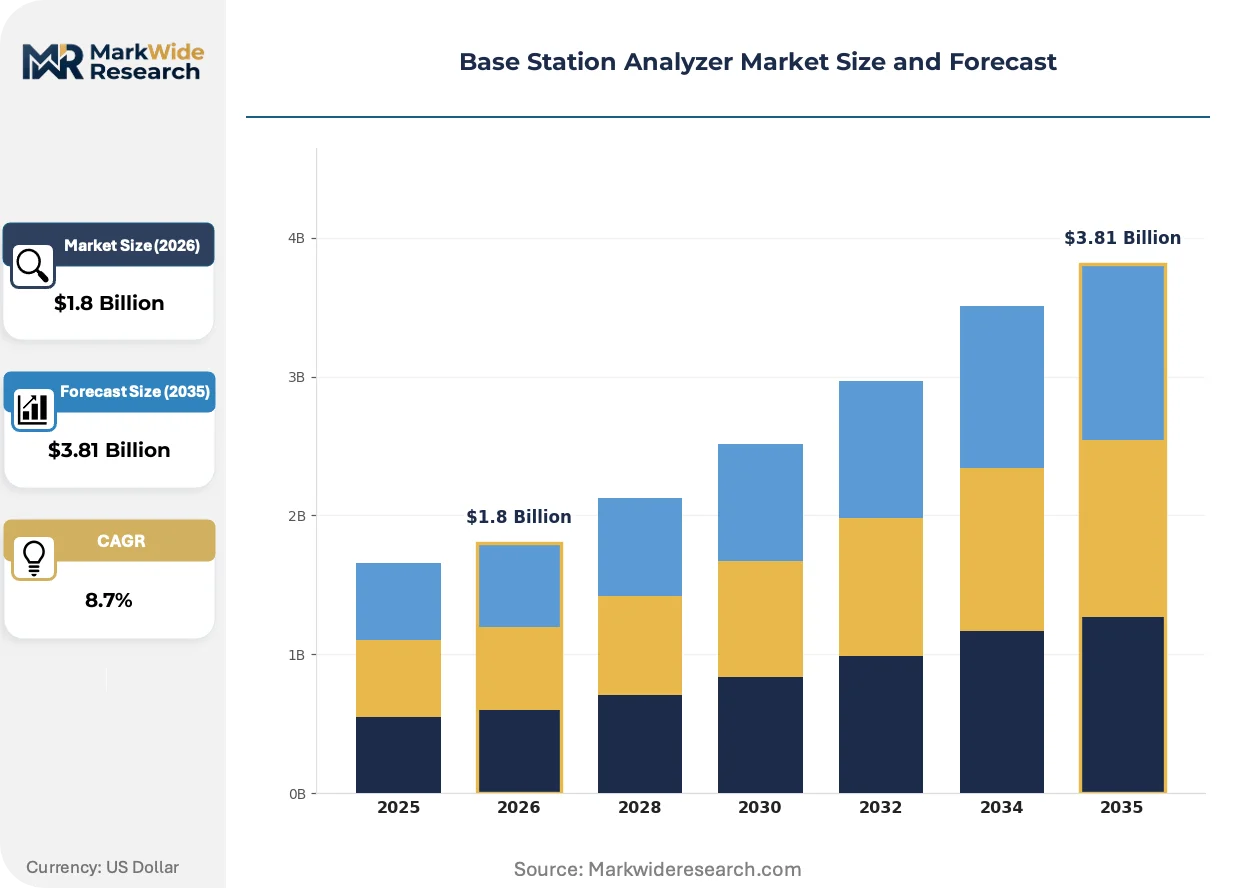
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Rack-mounted, Software-based Application: Network Optimization, Spectrum Analysis, Interference Mitigation, Signal Strength Testing End User: Telecom Operators, Network Service Providers, Government Agencies, Research Institutions Technology: LTE, 5G, Wi-Fi, Cellular |
| Companies Covered | Anritsu Corporation, Ceyear Technologies, Keysight Technologies, Rigol Technologies Inc., CommScope, Rohde & Schwarz, Spirent Communications, LitePoint, VIAVI Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Station Analyzer Market Strategic Shifts
Test instrumentation is converging with cloud-native architectures and embedded intelligence, compressing the boundary between field diagnostics and centralized network operations centers.
Cloud-native analyzer platforms are hybridizing traditional rack-mounted lab systems with edge-deployable containers. Tier-1 operators in Germany and Japan are piloting subscription-based access to centralized measurement IP, reducing capital deployment at individual cell sites while maintaining traceable calibration chains. This architecture is hybridizing how vendors monetize firmware roadmaps, shifting from perpetual licenses toward recurring revenue models tied to 3GPP release updates.
ETSI's F-Gas Regulation is phasing down hydrofluorocarbon use in thermal management systems for high-power test equipment. Analyzer manufacturers serving European markets are redesigning thermal architectures around liquid cooling and phase-change materials to maintain measurement stability without refrigerant-dependent heat exchangers. Rack-mounted systems above 40 GHz thermal dissipation thresholds face the steepest redesign timelines under the 2024-2030 phase-down schedule.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier mobile network operators. Third-party test equipment lessors in Brazil and Mexico are bundling maintenance, calibration, and firmware upgrades into per-test-hour pricing, capturing operators with constrained capex budgets. Tower companies and infrastructure-sharing ventures represent the fastest-adopting vertical under this model, prioritizing operational flexibility over asset ownership.
Base Station Analyzer Market Segmentation
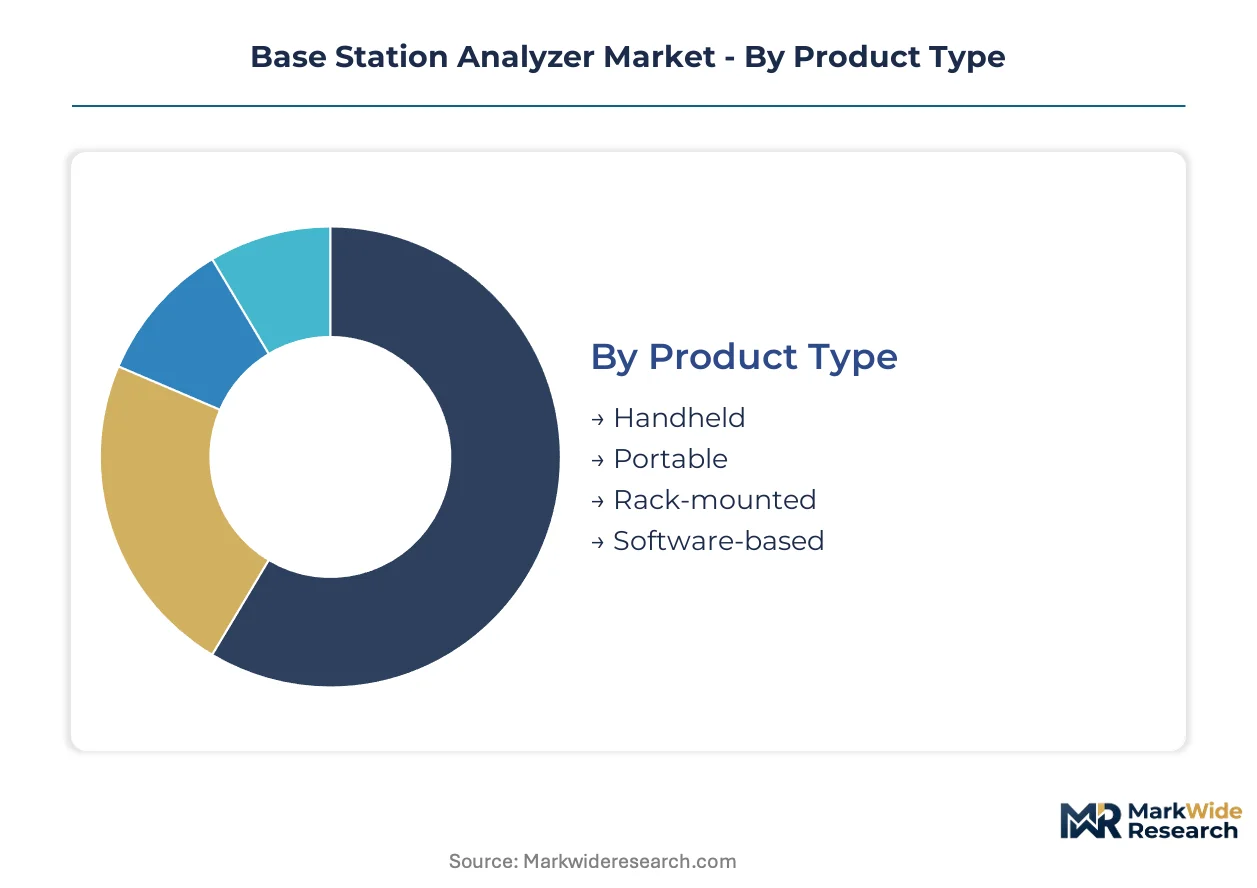
Base station analyzer procurement cycles diverge sharply across form factors and deployment contexts. Equipment refresh timelines stretch from months for field-portable units to years for centralized lab systems, creating distinct margin pools and vendor engagement models.
Product Type:
Handheld units turn over fastest at 18-24 month cycles driven by tower technician wear and battery degradation, while rack-mounted systems persist 7-10 years in carrier lab environments.
- Handheld:Battery-powered instruments under 3 kg dominate tower climb and rooftop installation workflows. Demand clusters with South Korean operators densifying urban 5G layers where technician mobility dictates instrument choice.
- Portable:Vehicle-mounted or backpack systems bridge field and lab use cases with extended frequency coverage. US drive-test contractors favor these units for FCC Part 27 compliance verification across CBRS deployments.
- Rack-mounted:Centralized validation systems anchor carrier acceptance labs and equipment vendor R&D facilities. Shenzhen and Beijing deployment corridors absorb volume for MIIT network access license testing.
- Software-based:Virtualized measurement personalities running on commercial compute hardware. German and Japanese operators pilot subscription access models reducing cell-site capital deployment.
Handheld units dominate installed base. Rack-mounted systems are where expansion concentrates.
Application:
Cost tiers separate routine maintenance workflows from high-value optimization consulting, with interference mitigation commanding premium pricing due to specialized expertise requirements.
- Network Optimization:Drive-test data collection and post-processing for coverage validation and capacity planning. Brazilian tower companies adopt equipment-as-a-service models for operational flexibility in this application.
- Spectrum Analysis:Wideband signal characterization across licensed and unlicensed bands. FCC spectrum reallocation mandates accelerate procurement for 3.5 GHz priority access verification.
- Interference Mitigation:Co-channel and adjacent-channel interference source identification in dense deployments. Urban 5G densification in Seoul and Beijing corridors drives fastest adoption.
- Signal Strength Testing:Received power measurement for coverage mapping and handoff parameter tuning. Lowest-cost application facing substitution pressure from tablet-based software-defined radio platforms.
Signal strength testing dominates installed base. Interference mitigation is climbing the fastest.
End User:
Procurement authority and technical sophistication vary dramatically, with government agencies imposing lengthiest certification cycles while research institutions drive early technology adoption.
- Telecom Operators:Mobile network operators with direct infrastructure ownership. South Korean operators lead procurement velocity for 5G NR small-cell validation.
- Network Service Providers:Third-party testing contractors and infrastructure maintenance specialists. Brazilian and Mexican lessors bundle calibration and firmware upgrades into per-test-hour pricing.
- Government Agencies:National regulators and spectrum management authorities. FCC enforcement of Part 27 and Part 96 rules shapes frequency coverage requirements.
- Research Institutions:University labs and corporate R&D centers advancing air interface evolution. Early adopters of mmWave analysis capabilities above 40 GHz.
Telecom operators dominate installed base. Network service providers are gaining share fastest.
Technology:
Technology maturity stratifies pricing, with LTE analyzers commoditizing while 5G NR validation commands calibration premiums and specialized firmware roadmaps.
- LTE:Established 4G air interface analysis with stable measurement requirements. Replacement demand concentrates in emerging markets completing initial network builds.
- 5G:New radio validation spanning sub-6 GHz and mmWave bands with beamforming analysis. ETSI conformance test models under evolving 3GPP specifications extend firmware development cycles.
- Wi-Fi:Unlicensed spectrum analysis for enterprise and residential coverage extension. Lowest-price tier with minimal regulatory compliance burden.
- Cellular:Legacy 2G/3G maintenance and interworking validation. Declining segment sustained by rural coverage obligations and machine-to-machine installed base.
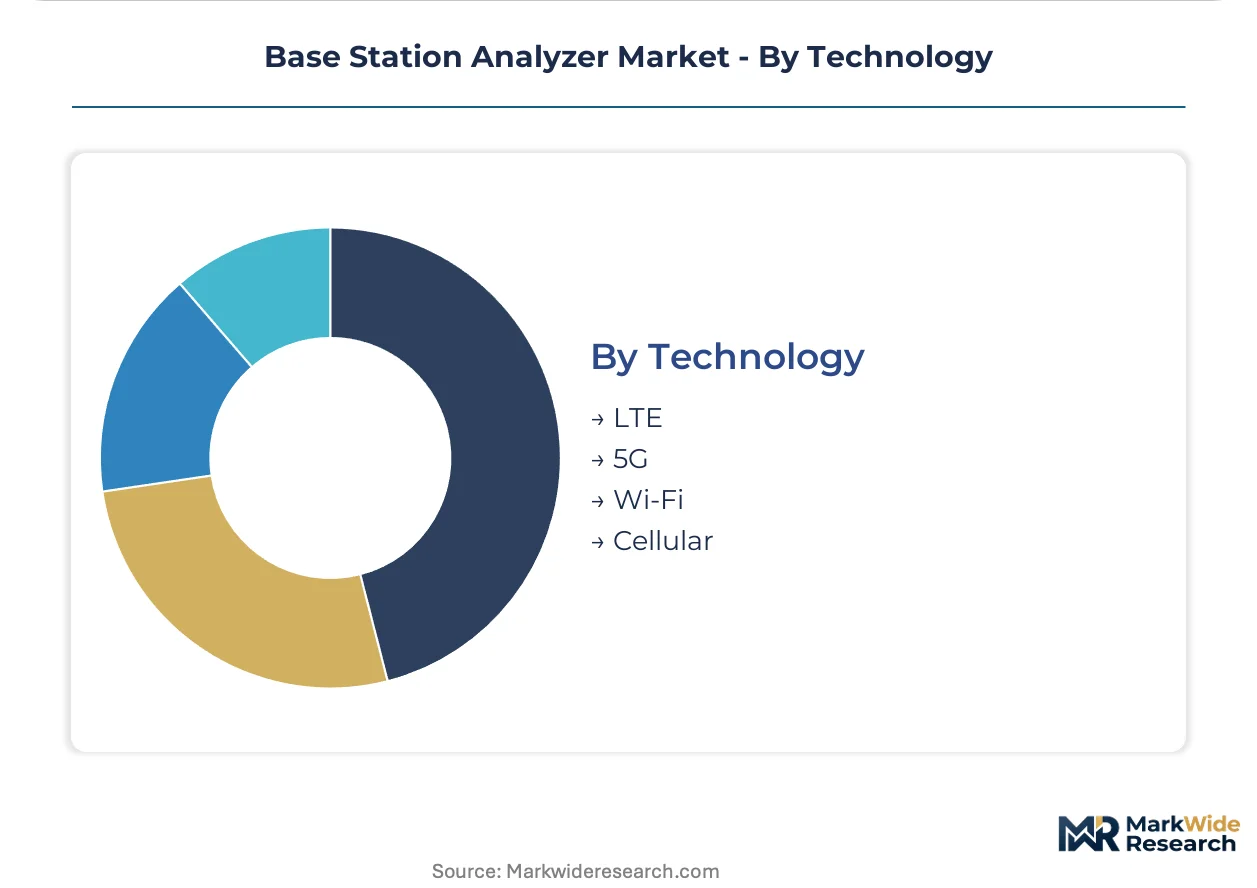
Cellular dominates installed base. 5G is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators and network infrastructure contractors concentrate analyzer procurement in jurisdictions with active 5G spectrum auctions and aggressive small-cell deployment timelines. Equipment vendors prioritize calibration service proximity to these buyer clusters.
United States
Drive-test contractors and tower companies absorb portable analyzer volumes for CBRS and 3.5 GHz priority access verification. FCC enforcement of Part 27 and Part 96 rules mandates specific frequency coverage in field instruments. Deployment corridors in Texas and California sustain concentrated demand from infrastructure-sharing ventures.
China
Domestic equipment vendors and state-owned operators drive rack-mounted system procurement for network access license testing. MIIT issues入网许可 with RF emission thresholds that require localized calibration standards. Shenzhen and Beijing deployment corridors absorb the highest analyzer volumes for 5G NR validation.
Germany
Tier-1 operators pilot cloud-native analyzer platforms with subscription-based firmware access. ETSI F-Gas Regulation forces thermal architecture redesigns for rack-mounted systems above 40 GHz. Industrial clusters in Bavaria and Baden-Württemberg anchor equipment vendor R&D facilities.
South Korea
Mobile operators accelerate handheld analyzer procurement for urban small-cell densification and indoor coverage solutions. The national spectrum regulator enforces stringent spurious emission limits that shape measurement personality roadmaps. Seoul Capital Area technicians dominate tower climb and drive-test workflows.
India
Domestic 5G equipment manufacturing under PLI scheme creates analyzer demand for production testing and incoming quality assurance. TRAI spectrum allocation timelines determine operator capex cycles. Industrial corridors in Maharashtra and Gujarat concentrate contract manufacturer facilities requiring RF validation.
Base Station Analyzer Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Tier-1 operators in developed markets consolidate purchasing through multi-year framework agreements, while mid-tier operators and tower companies fragment demand across regional distributors. Strategic archetypes split between full-stack test instrumentation conglomerates, RF measurement specialists, and software-defined platform entrants. Competitive moves concentrate on cloud-native subscription models and thermal architecture redesigns for regulatory compliance.
Among established test instrumentation conglomerates, Keysight Technologies, Rohde & Schwarz, and VIAVI Solutions Inc. occupy positions spanning handheld field instruments through rack-mounted lab systems. Keysight anchors calibration IP across Open RAN split configurations. Rohde & Schwarz exemplifies sustained R&D intensity in mmWave signal analysis. VIAVI represents field-portable platform specialization for drive-test workflows. These three entities sit within the premium-tier vendor cluster where firmware roadmap velocity determines competitive positioning.
| Leading Market Players |
|---|
| Anritsu Corporation |
| Ceyear Technologies |
| Keysight Technologies |
| Rigol Technologies Inc. |
| CommScope |
| Rohde & Schwarz |
| Spirent Communications |
| LitePoint |
| VIAVI Solutions Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Shenzhen express freight corridor anchors cost dynamics for GaN and GaAs substrate shipments, compressing margins on mmWave front-end modules while amplifying price differentiation between field-portable and rack-mounted analyzer tiers. Calibration service proximity to deployment clusters in Beijing and Seoul feeds into downstream pricing power for vendors with localized technical support infrastructure.
Pricing Analysis
Cost-plus contracts indexed to semiconductor substrate spot markets dominate procurement for rack-mounted systems above 40 GHz. Pricing stratifies across premium, standard, and economy tiers based on calibration traceability depth and firmware update bundling. Cost compression in handheld units intensifies as software-defined radio platforms on commercial tablets erode entry-level field test pricing. Tower companies and infrastructure-sharing ventures exhibit highest price sensitivity, while research institutions purchasing for mmWave R&D show lowest sensitivity to unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for analyzer manufacturers sourcing precision ADCs and FPGA components. Manufacturing concentrates in Taiwan, South Korea, and Japan for critical RF front-end semiconductors. The supply chain draws from gallium nitride substrates, high-stability oscillators, and precision connector assemblies. Single-source vulnerability persists for sub-6 GHz to mmWave frequency synthesizers from limited qualified foundries. Distribution runs through authorized technical distributors with calibration certification capabilities rather than volume electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as software-defined radio platforms on commercial tablets capture low-end field test applications previously served by dedicated hardware instruments.
For Market Incumbents: Insulate firmware roadmap velocity as the primary defensive moat by accelerating 3GPP release update cycles and embedding real-time threat detection per O-RAN Alliance WG1 specifications. Deepen backward integration into precision calibration IP to offset margin compression from tablet-based substitutes. Prioritize channel control through multi-year framework agreements with Tier-1 operators in Germany and Japan piloting cloud-native subscription models. For New Entrants and Emerging Players: Mid-market network service providers in Brazil and Mexico represent the most penetrable entry point through equipment-as-a-service contracting models that bundle maintenance, calibration, and firmware upgrades. India's PLI scheme for telecom equipment manufacturing creates localized demand for production testing analyzers with less entrenched incumbent relationships. Pursue direct partnerships with tower companies prioritizing operational flexibility over asset ownership as the primary go-to-market angle. For Investors and Strategic Acquirers: RF measurement specialists with embedded AI inference capabilities for predictive maintenance represent the highest-conviction acquisition target archetype for portfolio exposure to network optimization automation. Long-term viability hinges on convergence between traditional conformance testing and real-time edge intelligence across the analysis window. Monitor O-RAN Alliance security specification adoption curves as the critical inflection signal for field instrument revenue mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription-based firmware access reduces cell-site capital deployment for German and Japanese operators. |
| Thermal Architecture Redesign | Liquid cooling adoption addresses ETSI F-Gas Regulation phase-down for rack-mounted systems above 40 GHz. |
| AI-Driven Interference Classification | Machine learning inference at the edge enables predictive maintenance in dense urban 5G deployments. |
| Localized Calibration Infrastructure | Proximity to Shenzhen and Beijing MIIT testing corridors secures network access license validation revenue. |
| Open RAN Split Validation | Multi-vendor interoperability testing across ORAN 7-2x configurations anchors Keysight's calibration IP positioning. |
Study Parameters
A standing panel of RF test engineering directors, telecom operator procurement leads, tower company maintenance managers, and O-RAN Alliance working group participants provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation against FCC Part 27 enforcement records, MIIT network access license databases, ETSI conformance test model releases, and 3GPP specification roadmaps. Bottom-up shipment modeling by form factor and technology tier triangulated against top-down equipment vendor revenue segmentation across the analysis window.
Scenario-bracketing around spectrum auction timelines, PLI scheme implementation velocity, and Open RAN deployment curves bounded the forecast range. The analytical framework modeled product type, application, end user, and technology dimensions with regional regulatory cluster overlays. CAGRs derived from equipment refresh cycle analysis and densification capex trajectories incorporated mmWave signal analysis expertise scarcity as a constraint variable on service delivery scaling.
Macroeconomic conditions sit as an overlay; deviation in semiconductor substrate pricing, spectrum allocation delays, or trade policy shifts would shift the trajectory. Forecasts reflect documented assumptions about 5G NR small-cell deployment density and ORAN disaggregation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Multifunction Calibrators Market