
 Smart Warehouse Technologies Market | 2026-2036
Smart Warehouse Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Warehouse Technologies Market Analytics
Modular robotics bundling is realigning procurement patterns across warehouse automation buyers. Daifuku Co., Ltd. leverages its integrated material handling systems to dominate large-scale distribution center deployments. Dematic sustains technology leadership in shuttle-based storage and retrieval architectures. SSI Schaefer anchors its competitive position through deep specialization in software-integrated intralogistics solutions.
Smart warehouse technologies encompass sensor networks, autonomous mobile robots, and AI-driven orchestration platforms that coordinate inventory movement, environmental monitoring, and order processing within distribution facilities. These systems typically operate on sub-second latency requirements and integrate programmable logic controllers with cloud-based analytics layers to optimize throughput density per square meter. Warehouse Management Systems command the largest installed base among technology segments, while IoT Sensors represent the fastest-expanding margin pool as predictive maintenance contracts proliferate. Among end users, Third-Party Logistics providers occupy the most concentrated demand channel, though E-Commerce direct deployments are accelerating as fulfillment speed becomes a brand differentiator.
The EU Machinery Directive and CE marking framework shape equipment certification pathways, while OSHA standards in the United States govern worker safety around collaborative robot deployments. Japan's METI guidelines for Industry 4.0 infrastructure further influence system interoperability requirements in Asian supply chains. Stakeholders must monitor evolving liability frameworks for autonomous vehicle incidents and assess whether regional certification divergence will fragment procurement strategies or consolidate vendor selection around multi-jurisdiction compliance capabilities.
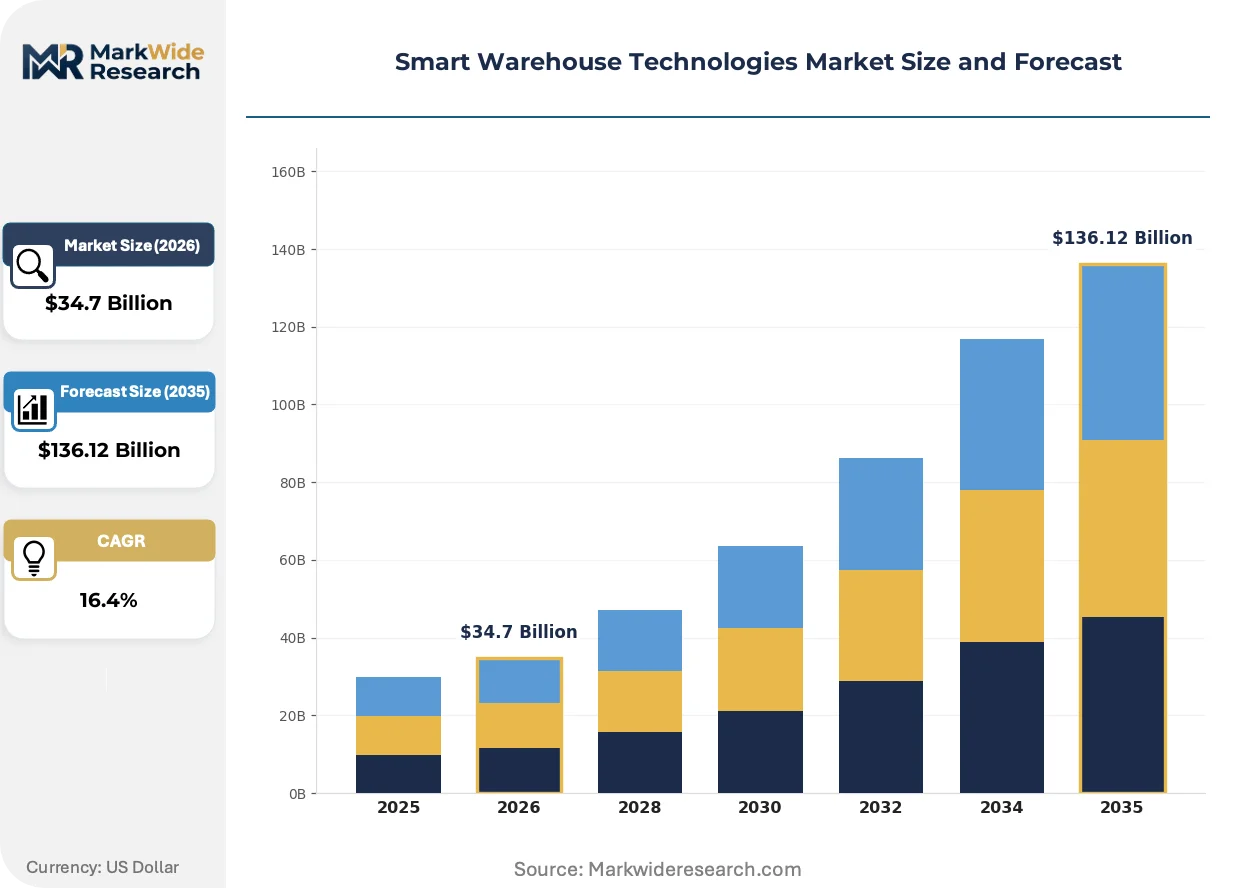
Market Dynamics
Modular robotics bundling is realigning procurement patterns across warehouse automation buyers, compressing vendor consolidation timelines as integrated system contracts displace point-solution purchases.
Growth Catalysts
- E-commerce fulfillment velocity mandates:Same-day delivery promises from major retailers are forcing distribution centers to deploy autonomous mobile robots and shuttle-based storage architectures. Third-party logistics providers in Germany are expanding automated footprints to meet pharmaceutical and automotive sector service-level agreements.
- EU Machinery Directive compliance deadlines:CE marking requirements for collaborative robots and automated guided vehicles are accelerating replacement cycles for uncertified legacy equipment. The directive's safety integrity specifications are pulling demand toward certified system integrators with proven conformity assessment track records.
- Labor cost trajectories in developed economies:Rising warehouse wage pressures across the United States and Western Europe are automating palletizing, picking, and sortation operations that previously relied on manual throughput. Food and beverage distribution networks are deploying sensor-guided depalletizers to offset seasonal workforce volatility.
Market Restraints
- Steel and semiconductor input cost volatility:Fluctuations in lithium-ion battery cell pricing and precision motor components are compressing margins for robot OEMs and stretching project payback calculations for end users.
- Vendor concentration in control systems:Dependence on a limited pool of programmable logic controller suppliers creates vulnerability in large-scale deployment timelines when chip allocation tightens.
- Interoperability protocol fragmentation:Competing communication standards between warehouse management systems and robot fleet management platforms are extending integration timelines and inflating custom engineering costs.
Strategic Opportunities
- Cold chain automation in India:Underpenetrated pharmaceutical and fresh produce distribution infrastructure presents white space for temperature-controlled automated storage and retrieval systems with integrated environmental monitoring.
- AI-orchestration convergence with digital twin platforms:Real-time simulation of warehouse operations combined with predictive analytics is enabling dynamic slotting optimization and preemptive maintenance scheduling.
- OSHA collaborative robot safety standard evolution:Clarified liability frameworks for human-robot workcell integration are reducing insurance uncertainty and accelerating pilot-to-production transitions in US-based facilities.
Industry Challenges
- Mechatronics technician scarcity:Shortfalls in skilled maintenance personnel capable of servicing combined mechanical, electrical, and software subsystems are extending mean time to repair and inflating service contract premiums.
- Legacy WMS migration complexity:Decades-old warehouse management system architectures require expensive middleware development to interface with modern robot fleet controllers, delaying automation ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Warehouse Technologies Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $136.12 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Robotic Arms, IoT Sensors, Warehouse Management Systems End User: Retailers, Third-Party Logistics, E-Commerce, Manufacturing Application: Inventory Management, Order Fulfillment, Shipping Optimization, Space Utilization Solution: Data Analytics, Real-Time Tracking, Predictive Maintenance, Cloud Integration |
| Companies Covered | Daifuku Co., Ltd., Dematic, SSI Schaefer, Honeywell Intelligrated, Swisslog, KNAPP AG, Zebra Technologies, Bastian Solutions, AutoStore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Warehouse Technologies Market Evolving Landscape
Sensor-to-cloud architecture compression is collapsing latency requirements for inventory tracking, while predictive maintenance contracts are shifting vendor revenue models from hardware shipment to operational uptime guarantees.
Autonomous mobile robots equipped with LiDAR and machine vision are automating goods-to-person workflows in e-commerce fulfillment centers. Major apparel and electronics retailers are deploying hundred-plus-unit fleets within eighteen-month implementation windows. The technology is automating labor-intensive travel time between pick locations, compressing order cycle duration by reallocating human operators to value-added packing and quality verification tasks.
The EU AI Act's risk classification framework for automated decision-making systems is reshaping vendor liability structures for warehouse orchestration software. High-risk system designations now mandate conformity assessments for AI-driven slotting algorithms that directly influence worker task allocation. European third-party logistics providers are responding by segregating AI-enabled and deterministic control pathways to limit regulatory exposure while maintaining throughput targets.
Subscription-based robotics procurement is displacing capital expenditure models among mid-market distribution operators. Equipment-as-a-service contracts bundle maintenance, software updates, and performance guarantees into per-pick pricing structures. This shift is most visible in United States food service distribution, where seasonal volume volatility makes fixed asset ownership economically unattractive compared to elastic fleet scaling.
Smart Warehouse Technologies Market Segmentation
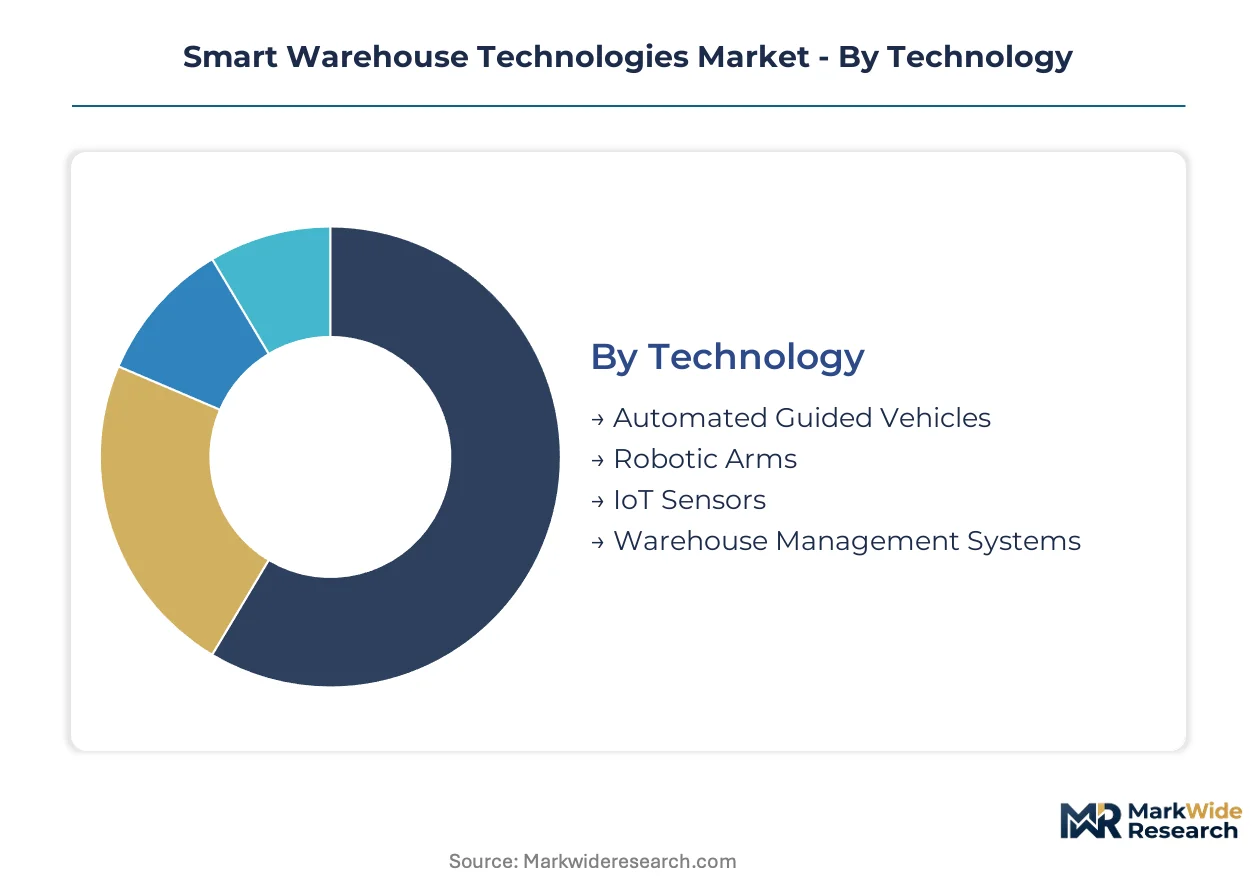
Smart warehouse technologies fragment across multiple dimensions that determine deployment economics and vendor selection criteria. Capital allocation patterns vary dramatically between infrastructure-heavy hardware segments and software-centric orchestration layers. Procurement teams weight these categories differently based on facility scale, existing system architecture, and regulatory compliance obligations.
Technology:
Capital intensity peaks with mobile robotics hardware requiring precision manufacturing and safety certification, while software platforms demand engineering talent density rather than physical asset deployment.
- Automated Guided Vehicles:Laser-guided and vision-based transport systems navigate fixed-path or dynamic routes across distribution floors. German automotive suppliers and pharmaceutical distributors in the EU deploy these for pallet movement compliance with CE-marked safety integrity standards.
- Warehouse Management Systems:Centralized software platforms coordinate inventory databases, labor allocation, and order wave planning through API-connected modules. Third-party logistics providers in the United States prioritize WMS with OSHA-compliant human-robot workcell interfaces to reduce liability exposure.
- Robotic Arms:Articulated manipulators execute pick, place, and palletizing operations with force-feedback controls.
- IoT Sensors:Environmental and positional monitoring devices feed telemetry into predictive analytics engines.
Warehouse Management Systems absorb the bulk of installed capacity; IoT Sensors are expanding most quickly.
End User:
Customer scale determines whether procurement favors integrated system bundles or modular point solutions with internal integration teams.
- Third-Party Logistics:Multi-tenant operators manage shared distribution infrastructure for diverse brand clients across contract logistics networks. Facilities in Germany face EU Machinery Directive deadlines forcing coordinated fleet upgrades across pooled asset bases.
- E-Commerce:Direct-to-consumer retailers operate dedicated fulfillment centers with same-day delivery service-level agreements. United States apparel and electronics merchants deploy hundred-plus autonomous mobile robot fleets within compressed implementation windows.
- Retailers:Brick-and-mortar chains automate regional distribution centers supporting store replenishment cycles.
- Manufacturing:Industrial producers integrate warehouse automation with production line material flow systems.
Third-Party Logistics concentrates the largest contract values; E-Commerce is climbing the fastest.
Application:
Functional priority shapes whether investment flows to upstream inventory accuracy or downstream velocity optimization.
- Order Fulfillment:Goods-to-person workflows compress pick-path travel time through autonomous mobile robot fleets and shuttle-based storage architectures. Major United States retailers reallocate human operators from walking to value-added packing tasks.
- Inventory Management:Cycle counting, slotting optimization, and stock location accuracy systems reduce shrinkage and carrying costs. Pharmaceutical distributors in Germany deploy sensor networks meeting EU AI Act risk classification requirements for automated decision-making.
- Shipping Optimization:Manifesting, label application, and carrier selection automation reduces dock door congestion.
- Space Utilization:Dense storage configurations maximize cubic throughput per square meter in high-rent logistics corridors.
Inventory Management commands the deepest installed base; Order Fulfillment is gaining share fastest.
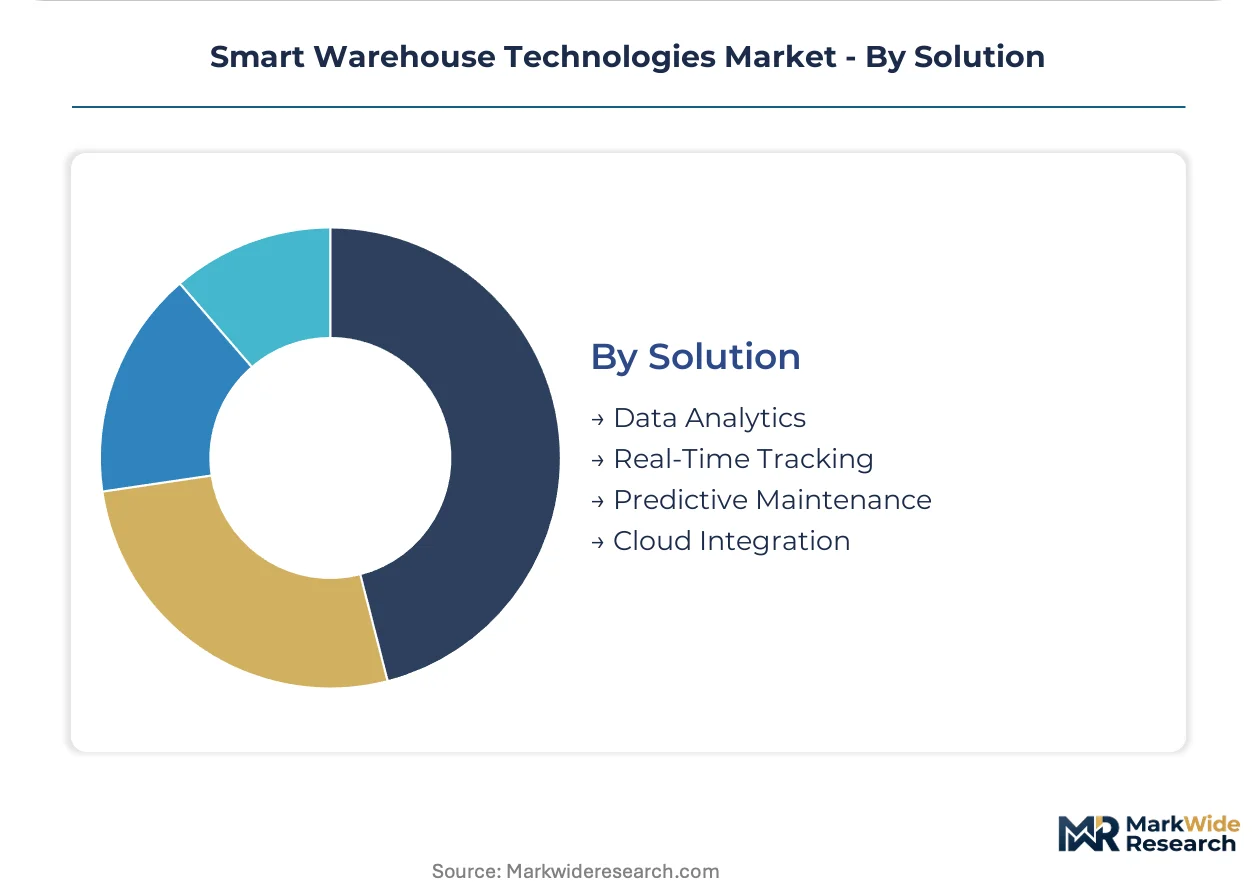
Solution:
Revenue model differentiation separates perpetual license software from subscription-based operational uptime guarantees.
- Real-Time Tracking:Sensor-to-cloud architectures collapse inventory visibility latency from batch updates to sub-second telemetry. United States food service distributors favor elastic fleet scaling over fixed asset ownership through equipment-as-a-service contracts.
- Predictive Maintenance:Machine learning models forecast component failure from vibration, temperature, and current draw signatures. Vendor revenue shifts from hardware shipment to guaranteed uptime pricing structures.
- Data Analytics:Historical throughput analysis informs capacity planning and seasonal labor forecasting.
- Cloud Integration:Hybrid edge-cloud architectures balance local control system latency with centralized analytics scale.
Real-Time Tracking anchors current procurement budgets; Predictive Maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and Japan supply automation hardware to consumption centers in the United States and China. Distribution network density and regulatory compliance timelines determine regional adoption velocity.
United States
E-commerce fulfillment velocity mandates and rising warehouse wage pressures accelerate autonomous mobile robot deployment. OSHA collaborative robot safety standards reduce insurance uncertainty for human-robot workcell integration. Major apparel and electronics retailers in the Midwest and Southeast operate hundred-plus-unit robot fleets within compressed implementation windows.
Germany
Automotive and pharmaceutical distribution networks require precision logistics infrastructure with CE-marked safety integrity. The EU Machinery Directive accelerates replacement cycles for uncertified legacy equipment. Industrial clusters in Bavaria and Baden-Württemberg deploy shuttle-based storage architectures to meet stringent service-level agreements.
China
E-commerce platform operators drive demand for dense storage configurations maximizing cubic throughput per square meter. METI guidelines for Industry 4.0 infrastructure influence system interoperability requirements in Asian supply chains. Yangtze River Delta fulfillment centers integrate sensor-to-cloud architectures for sub-second inventory visibility.
Japan
Automotive suppliers and electronics manufacturers deploy laser-guided transport systems for pallet movement compliance. METI Industry 4.0 guidelines shape system interoperability requirements across Asian supply chains. Kanto and Kansai industrial corridors concentrate integrated material handling system deployments.
India
Underpenetrated pharmaceutical and fresh produce distribution infrastructure creates white space for temperature-controlled automated storage. BIS certification requirements for industrial equipment shape procurement pathways. Maharashtra and Gujarat logistics hubs pilot equipment-as-a-service contracts to offset seasonal volume volatility.
Smart Warehouse Technologies Market Competitive Landscape
The competitive structure tilts toward integrated system bundling over point-solution procurement. Vendor consolidation timelines compress as distribution center operators favor single-source contracts covering hardware, software, and maintenance. Three archetypes dominate: Japanese integrated material handling conglomerates, European shuttle-storage specialists, and North American WMS-robotics bundlers. M&A activity concentrates on software-integrated intralogistics capabilities, while strategic partnerships address interoperability protocol fragmentation.
Within the integrated systems tier, Daifuku Co., Ltd. and Dematic exemplify scale-driven deployment architectures. SSI Schaefer anchors the European specialist position through software-integrated intralogistics solutions. These three entities occupy positions reflecting distinct geographic and technological clustering patterns rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Dematic |
| SSI Schaefer |
| Honeywell Intelligrated |
| Swisslog |
| KNAPP AG |
| Zebra Technologies |
| Bastian Solutions |
| AutoStore |
| Others |
Value Network & Pricing Analysis
EU Machinery Directive compliance deadlines are compressing procurement timelines for CE-marked automation systems, forcing buyers toward certified integrators with proven conformity assessment records and compressing price negotiation leverage for uncertified equipment vendors.
Pricing Analysis
Cost-down pressure on mid-market warehouse operators accelerates because equipment-as-a-service contracts displace capital expenditure models with per-pick subscription pricing. Three-tier pricing structure across premium, standard, and economy levels separates full-stack system integrators from modular hardware vendors and software-only orchestration platforms. Price differentiation traces to CE certification grade and after-sales service bundling. Third-party logistics providers exhibit highest price sensitivity due to multi-tenant margin pressures, while pharmaceutical distributors in Germany accept premium tiers for safety integrity guarantees.
Supply Chain Analysis
Precision motor component supply rests on German and Japanese specialty manufacturers, while lithium-ion battery cell production concentrates in China and South Korea. Steel frame fabrication and programmable logic controller chip allocation draw from Taiwan and United States semiconductor foundries. Single-source vulnerability in PLC chip supply creates deployment timeline risk when allocation tightens. Distribution runs through certified system integrators with regional service networks rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable logic controller chip scarcity props pricing power for vendors with secured foundry allocation, creating a supply-constrained environment favoring incumbent consolidation.
For Market Incumbents: To counter modular robotics bundling from Asian competitors, Daifuku Co., Ltd. and Dematic should deepen backward integration into precision motor manufacturing and expand captive service technician training programs in Germany and the United States. Certification investment in EU AI Act conformity assessment capabilities anchors pricing power against uncertified challengers. For New Entrants and Emerging Players: AI-orchestration software with digital twin simulation offers the most penetrable wedge into United States food service distribution, where seasonal volume volatility favors elastic fleet scaling over fixed asset ownership. Target mid-market third-party logistics providers in India with temperature-controlled automation for pharmaceutical cold chain white space, using equipment-as-a-service go-to-market structures to bypass capital barrier. For Investors and Strategic Acquirers: The window for entry favors software-integrated intralogistics specialists with proven WMS-robotics interoperability. Long-term viability hinges on multi-jurisdiction compliance capabilities spanning CE marking, OSHA collaborative robot standards, and METI Industry 4.0 guidelines. Watch for EU AI Act enforcement actions against high-risk warehouse orchestration systems as inflection indicator for regulatory-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | WMS-robotics bundling compresses vendor consolidation timelines for e-commerce fulfillment centers. |
| Acquisition of Specialist Firm | Software-integrated intralogistics targets address interoperability protocol fragmentation in European markets. |
| Strategic Partnership | Foundry allocation agreements with Taiwanese semiconductor producers secure PLC chip supply for large-scale deployments. |
| Geographic Expansion | Certified service networks in Bavaria and Baden-Württemberg meet EU Machinery Directive compliance deadlines. |
| Product Launch | AI-orchestration platforms with predictive maintenance contracts shift revenue from hardware to uptime guarantees. |
Research Methodology
Document review covered SEC 10-K filings from automation hardware vendors, EU Machinery Directive conformity assessment databases, and OSHA collaborative robot safety guidance, complemented by interviews with warehouse operations directors at third-party logistics providers, procurement leads at e-commerce fulfillment centers, and aftermarket service heads at system integrators. Bottom-up facility deployment counts triangulated against top-down equipment production data from German and Japanese manufacturing clusters.
Historical deployment trajectories cross-referenced against panel input from robotics OEMs and WMS platform vendors shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology tier, end-user vertical, application function, and regional regulatory cluster. CAGRs derived from equipment shipment volumes, software license bookings, and service contract values. Industry-specific forecast inputs incorporated EU AI Act risk classification timelines and METI Industry 4.0 infrastructure investment patterns.
Several conditions sit outside the modeled scope, including autonomous vehicle liability framework evolution and semiconductor trade restriction scenarios. Forecasts reflect documented assumptions about certification pathway stability and foundry allocation continuity. A small set of named triggers warrants ongoing watch: OSHA collaborative robot standard finalization, lithium-ion battery cell price volatility, and mechatronics technician training program expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Smart Factory Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Motion Control Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Human Machine Interface (HMI) Market