
 Middle East and Africa Factory Automation and Industrial Controls Market | 2026-2036
Middle East and Africa Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Factory Automation and Industrial Controls Market Foresight
The EU Green Deal is realigning compliance requirements for Middle East and Africa manufacturers serving European export markets. ABB Limited leverages its process automation heritage to anchor large hydrocarbon projects across the Gulf. Siemens AG sustains engineering depth in power generation controls and digital twin platforms. Schneider Electric differentiates through energy management software integrated with industrial hardware.
Factory automation and industrial controls encompass electromechanical systems, software platforms, and instrumentation that execute, monitor, and optimize manufacturing and process operations with precision thresholds often below 0.1% deviation. These systems govern throughput, safety interlocks, and resource efficiency across continuous and discrete production environments. Industrial robots command substantial investment allocation due to labor substitution economics in Gulf state manufacturing zones. IoT-enabled sensor networks represent the fastest-expanding technology layer as edge computing architectures proliferate across remote oilfield and mining installations. Programmable logic controllers remain the mature core of plant-floor control, with margin pools shifting toward firmware-integrated cybersecurity and predictive analytics modules.
Saudi Arabia's SFDA and the UAE's MOHAP enforce equipment safety standards that cascade into industrial control certification requirements for food-pharma adjacent manufacturing. South Africa's NRCS and Egypt's EOS maintain electrical and mechanical conformity protocols that shape import access for automation vendors. Stakeholders must monitor how Gulf sovereign industrial strategies redirect procurement preferences toward local content and technology transfer commitments.
Market Dynamics
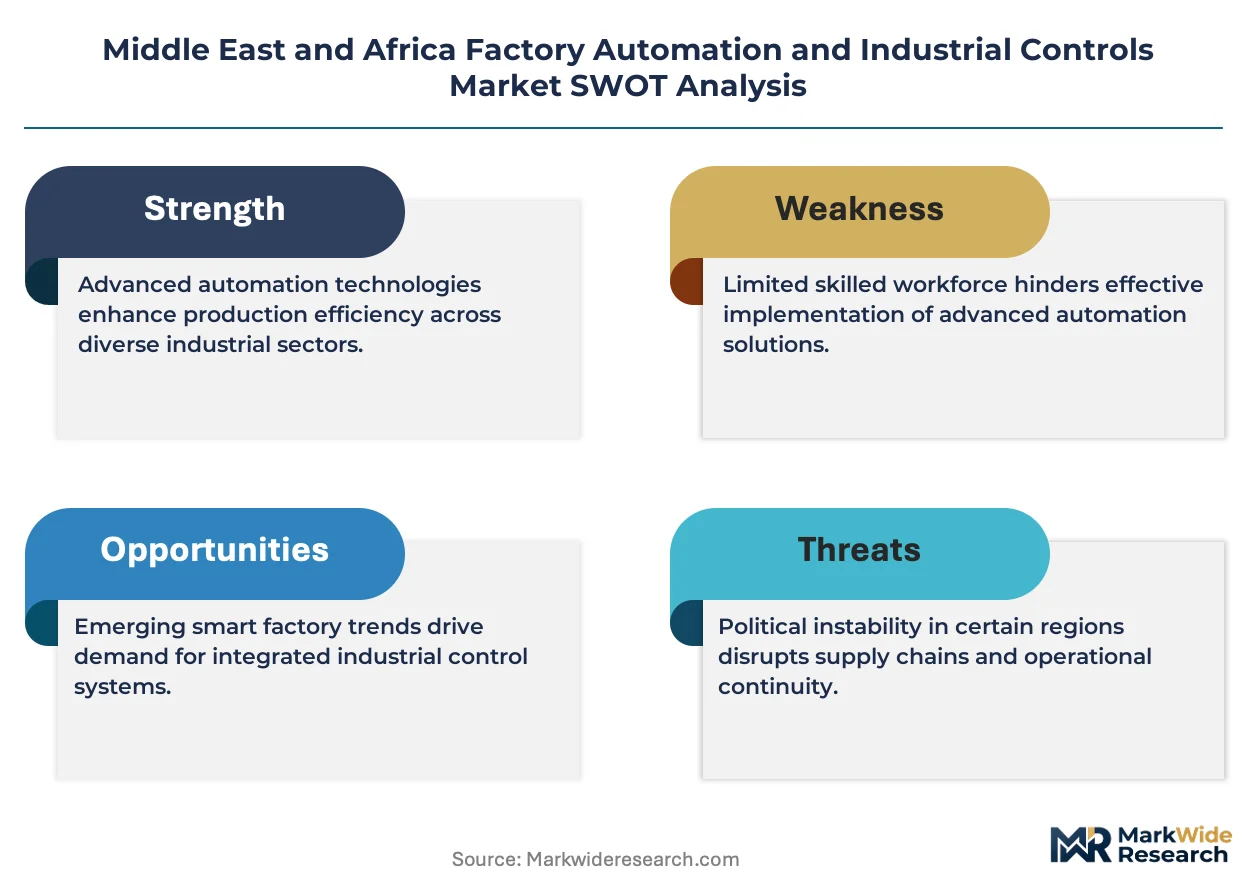
EU Green Deal carbon border adjustments are forcing MEA manufacturers to retrofit hydrocarbon processing plants with emissions monitoring and energy efficiency controls to maintain European export access.
Growth Catalysts
- SFDA Equipment Certification:Saudi Arabia's pharmaceutical safety mandates cascade into industrial control requirements for food-adjacent manufacturing, expanding automation procurement in giga-project zones.
- Digital Field Architectures:Oil and gas operators across the Gulf are deploying edge computing nodes and IoT sensor networks across remote upstream installations.
- Labor Substitution Economics:Industrial robotics command investment allocation in Gulf state manufacturing zones where wage arbitrage and workforce nationalization policies converge.
Market Restraints
- Semiconductor Input Volatility:PLC and servo drive production faces component lead time uncertainty from concentrated East Asian foundry supply.
- Technical Skills Fragmentation:Control systems integration requires scarce firmware cybersecurity and predictive analytics competencies that concentrate in South African and UAE urban centers.
- Local Content Mandates:Gulf sovereign industrial strategies redirect procurement preferences toward technology transfer commitments that complicate vendor market access.
Strategic Opportunities
- Egyptian Industrial Zones:Underpenetrated manufacturing corridors along the Suez Canal Economic Zone present automation retrofit demand from textiles and food processing.
- Edge-AI Convergence:Predictive maintenance algorithms fused with programmable logic controllers create new value pools in remote oilfield and mining installations.
- EU CBAM Compliance Services:Carbon border adjustment documentation and emissions verification systems represent emerging revenue lines for automation integrators serving export-oriented manufacturers.
Industry Challenges
- Cybersecurity Certification Timelines:IEC 62443 compliance for industrial control systems extends deployment schedules and strains vendor engineering bandwidth.
- Legacy System Integration:Brownfield manufacturing facilities across South Africa and Nigeria require protocol translation layers that increase project complexity and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Factory Automation and Industrial Controls Market |
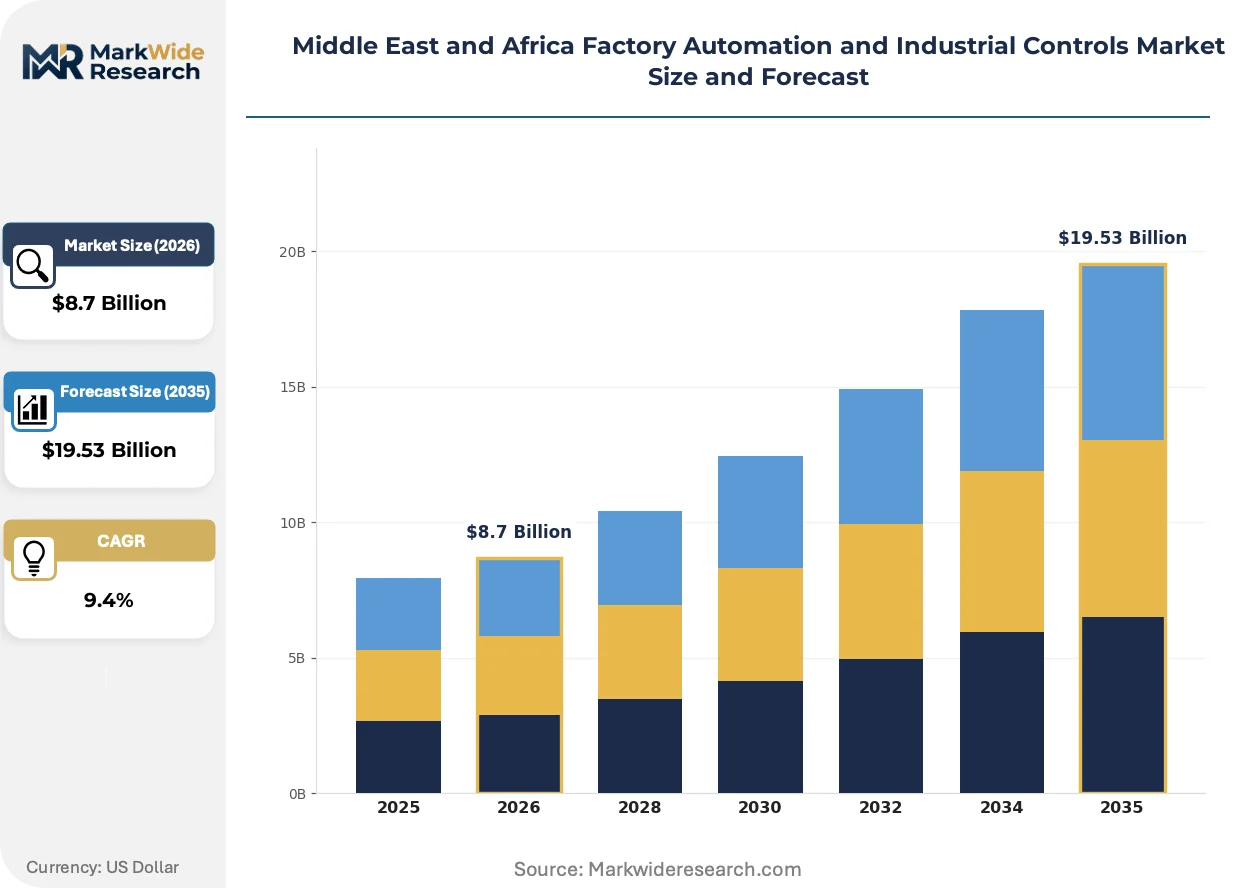
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Human Machine Interfaces, Sensors, Industrial Robots Technology: IoT, Artificial Intelligence, Machine Learning, Cloud Computing End User: Manufacturing, Oil & Gas, Mining, Water Treatment Application: Process Automation, Machine Automation, Quality Control, Predictive Maintenance |
| Companies Covered | ABB Limited, Siemens AG, Yokogawa Electric Corporation, Rockwell Automation Inc., Honeywell International Inc., Mitsubishi Electric Corporation, Schneider Electric, Emerson Electric Co., Omron Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Factory Automation and Industrial Controls Market Shifts & Advancements
Digital twin platforms are absorbing engineering workflows across hydrocarbon and power generation assets, compressing commissioning cycles and enabling remote operational support for distributed installations.
IoT-enabled sensor networks is absorbing telemetry functions previously handled by hardwired instrumentation, reducing cabling costs and enabling predictive analytics at the network edge. Mining operators in South Africa and oilfield service companies in Saudi Arabia are deploying these architectures fastest. The technology is absorbing maintenance budget allocations as condition-based monitoring displaces scheduled overhaul cycles.
EU Green Deal extraterritorial carbon border adjustments are mandating emissions monitoring integration into process control systems. MEA manufacturers serving European export markets must embed continuous emissions verification within their automation architectures. Hydrocarbon processing and metals smelting segments in Saudi Arabia and the UAE are retrofitting existing distributed control systems with carbon accounting modules.
Buyer concentration in Gulf sovereign industrial zones is compressing vendor negotiation cycles and unbundling after-sales service contracts from hardware procurement. Large-scale project developers now separate multi-year maintenance agreements from initial system purchases, forcing automation vendors to compete on discrete service line items. This pattern is most visible in Saudi Arabia's NEOM and Red Sea Project industrial corridors.
Middle East and Africa Factory Automation and Industrial Controls Market Segmentation
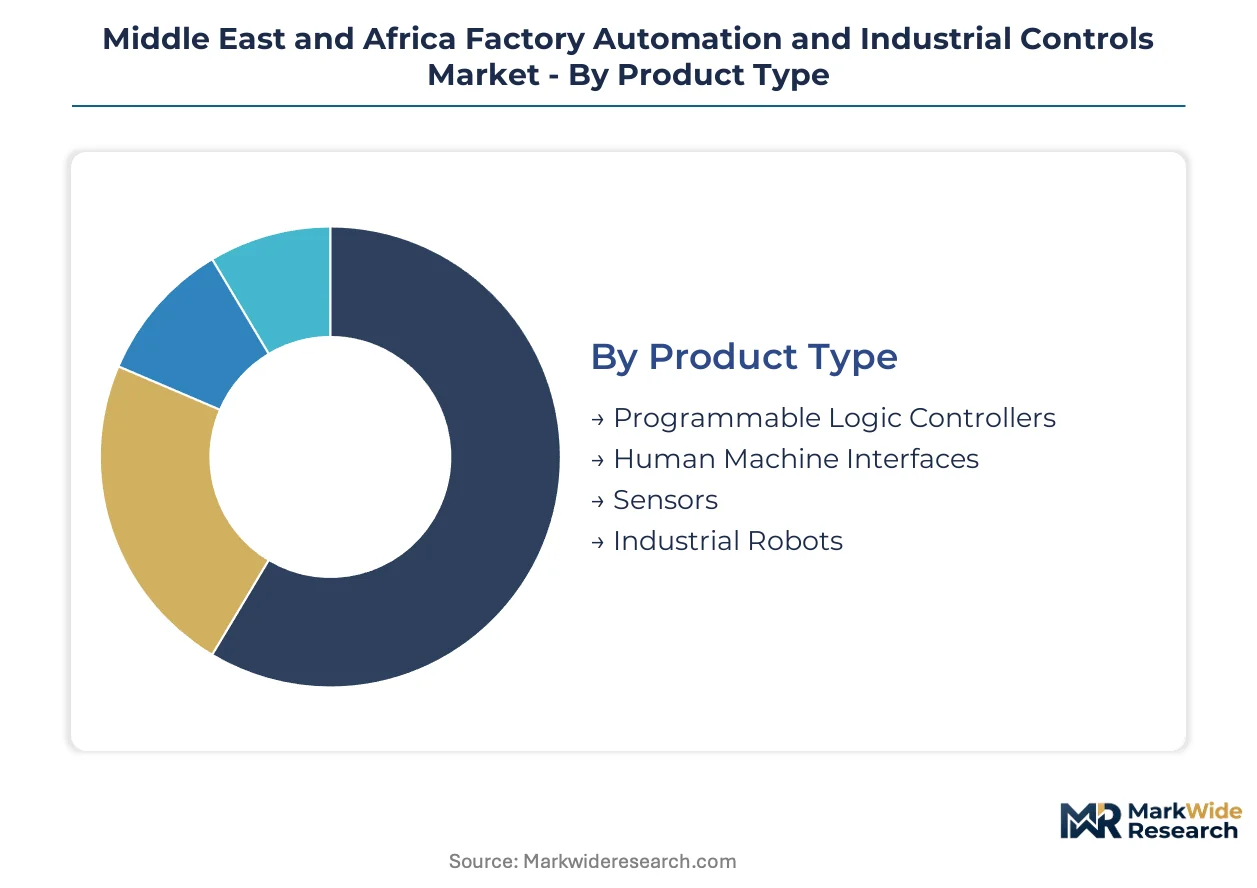
Factory automation and industrial controls in the Middle East and Africa fragment across hardware maturity curves and digital adoption gradients. Procurement patterns diverge sharply between hydrocarbon-driven Gulf states and resource-extraction economies in sub-Saharan Africa.
Product Type:
Industrial control hardware spans electromechanical execution layers through operator-facing visualization systems, with specification thresholds varying by process criticality and environmental exposure.
- Programmable Logic Controllers:Ruggedized industrial computers executing ladder logic and structured text with cycle times below 10 milliseconds. Deployment concentrates in Saudi Aramco downstream facilities and UAE aluminum smelters where SIL-rated safety interlocks are mandatory. Firmware-integrated cybersecurity modules are displacing standalone network appliances.
- Industrial Robots:Articulated and Cartesian configurations handling payloads from 3 kg to 2,300 kg with repeatability below 0.05 mm. Demand clusters in Saudi giga-project manufacturing zones where workforce nationalization policies accelerate labor substitution. Six-axis welding and material handling units command the largest capital allocations.
- Human Machine Interfaces:Touch-panel and web-based visualization layers translating PLC register data into operator dashboards.
- Sensors:Pressure, temperature, flow, and position transducers converting physical variables to 4-20 mA or digital fieldbus signals.
Mature deployment sits with Programmable Logic Controllers. Newer deployment is concentrated in Industrial Robots.
Technology:
Digital technology layers are climbing the fastest as edge architectures displace centralized SCADA hierarchies in remote oilfield and mining installations.
- IoT:Wireless sensor networks using LoRaWAN, NB-IoT, and proprietary protocols transmitting telemetry from geographically dispersed assets. Mining operators in South Africa's platinum belt and Saudi Arabia's Empty Quarter oilfields are retrofitting legacy instrumentation with battery-powered edge nodes. Network lifetime and hazardous area certification dominate procurement criteria.
- Artificial Intelligence:Neural network and rules-based inference engines optimizing setpoints and detecting anomaly patterns in real-time process data. Hydrocarbon processing plants in the UAE are piloting AI-driven distillation column optimization to reduce energy intensity ahead of EU carbon border compliance deadlines. Model training data scarcity in brownfield environments constrains rollout velocity.
- Machine Learning:Supervised and unsupervised algorithms identifying equipment degradation signatures from vibration and thermal telemetry.
- Cloud Computing:Scalable compute and storage infrastructure hosting historian databases and remote engineering access platforms.
Established architectures rely on Cloud Computing for centralized data aggregation. Frontier investment flows into Artificial Intelligence.
End User:
Vertical demand concentration tracks sovereign industrial strategies and extractive resource endowments across the regional economy.
- Oil & Gas:Upstream, midstream, and downstream automation spanning wellhead control, pipeline SCADA, and refinery distributed control systems. Saudi Arabia's Master Gas System expansion and UAE LNG capacity additions are driving large-scale procurement of safety instrumented systems and advanced process control. Digital field architectures with edge computing nodes are displacing traditional RTU hierarchies.
- Manufacturing:Discrete and process production across food, pharmaceuticals, metals, and construction materials. Egypt's Suez Canal Economic Zone textile corridors and Morocco's automotive supplier parks are retrofitting legacy relay logic with modern PLCs and servo motion systems. SFDA and MOHAP equipment certification requirements cascade into control system specifications for food-pharma adjacent facilities.
- Mining:Extraction and mineral processing automation in platinum, gold, iron ore, and phosphate operations.
- Water Treatment:Desalination, wastewater, and distribution network control systems.
Capital deployment depth remains with Oil & Gas. Fastest expansion trajectory belongs to Manufacturing.
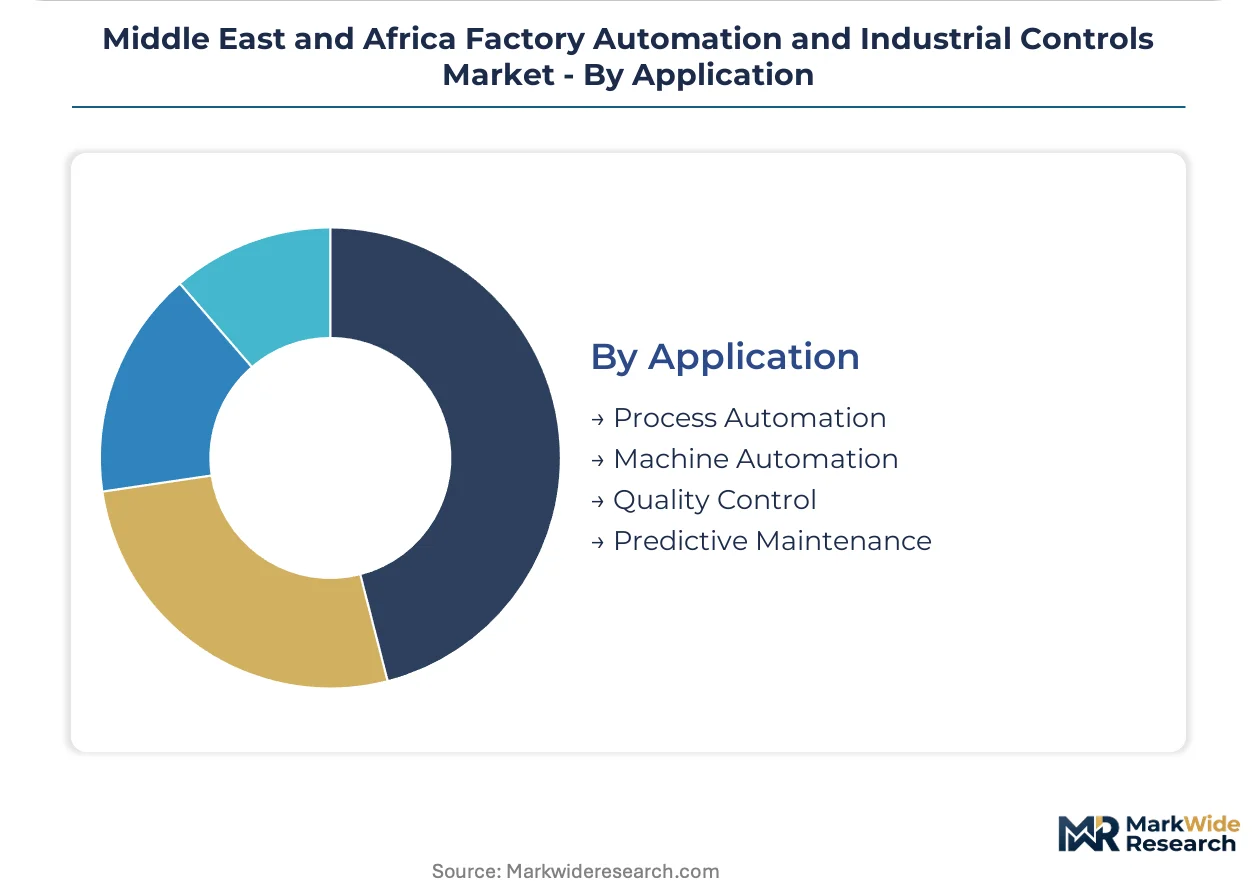
Application:
Functional automation use cases align with operational excellence priorities and regulatory compliance mandates across the regional industrial base.
- Process Automation:Continuous control of temperature, pressure, flow, and level in chemical, petrochemical, and power generation assets. Saudi Arabia's Jafurah unconventional gas development and UAE aluminum smelter expansions are commissioning integrated process control and safety systems with unified operator stations. IEC 62443 cybersecurity certification extends project timelines.
- Predictive Maintenance:Condition-based equipment monitoring replacing scheduled overhaul intervals through vibration analysis, oil analysis, and thermal imaging. South African mining houses and Saudi Aramco upstream divisions are deploying machine learning models on edge hardware to reduce unplanned shutdowns. Maintenance budget reallocation from corrective to predictive categories is accelerating.
- Machine Automation:Discrete motion control and sequencing in packaging, assembly, and material handling.
- Quality Control:Automated inspection and statistical process control in food, pharmaceutical, and metals production.
Installed base dominance rests with Process Automation. Investment momentum is shifting toward Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory automation production concentrates in European and East Asian manufacturing hubs, while consumption gravity sits with Gulf sovereign industrial zones and South African mining corridors. This divergence creates import-dependent supply chains across the Middle East and Africa region.
Saudi Arabia
NEOM and Red Sea Project industrial corridors are commissioning integrated process control systems for giga-project manufacturing zones. The SFDA enforces equipment safety standards that cascade into industrial control certification requirements for food-pharma adjacent facilities. Jubail and Yanbu industrial cities are retrofitting existing distributed control systems with carbon accounting modules ahead of EU CBAM compliance deadlines.
United Arab Emirates
UAE aluminum smelter expansions and LNG capacity additions are driving procurement of safety instrumented systems and advanced process control. MOHAP pharmaceutical equipment mandates shape automation specifications for manufacturing facilities serving domestic and export markets. Abu Dhabi National Oil Company digital field architectures are displacing traditional RTU hierarchies across upstream installations.
South Africa
Platinum belt mining operators are deploying machine learning models on edge hardware to reduce unplanned shutdowns through predictive maintenance. The NRCS maintains electrical and mechanical conformity protocols that shape import access for automation vendors. Johannesburg-Pretoria urban corridors concentrate scarce firmware cybersecurity and predictive analytics competencies.
Egypt
Suez Canal Economic Zone textile corridors are retrofitting legacy relay logic with modern PLCs and servo motion systems. The EOS electrical safety framework governs industrial control import certification and local assembly requirements. New administrative capital industrial zones are attracting automation integrators serving food processing and construction materials segments.
Israel
Defense-adjacent precision manufacturing is driving demand for motion control systems with sub-micron positioning accuracy. The country's national standards institute maintains conformity assessment protocols for industrial equipment import. Tel Aviv metropolitan technology clusters are incubating edge-AI startups targeting predictive maintenance applications for regional mining and oilfield service markets.
Middle East and Africa Factory Automation and Industrial Controls Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with process automation heritage. Vendor positioning fragments across hydrocarbon project anchors, discrete manufacturing specialists, and emerging IoT platform providers. Three archetypes dominate: European-Japanese diversified industrials with Gulf project track records, pure-play automation specialists with robotics depth, and energy-sector incumbents leveraging installed base relationships. Competitive moves concentrate on technology licensing partnerships for edge-AI modules and strategic alliances with Gulf sovereign wealth vehicles to satisfy local content mandates.
Among European-Japanese diversified industrials, ABB Limited, Siemens AG, and Yokogawa Electric Corporation exemplify the hydrocarbon project anchor archetype. These entities occupy positions shaped by decades of downstream refinery and upstream oilfield commissioning across Saudi Arabia and the UAE. Their market presence rests on safety instrumented system expertise and digital twin platform deployment rather than discrete manufacturing automation. Each represents a distinct geographic origin—Swiss-Swedish, German, and Japanese respectively—reflecting the global distribution of process automation engineering competence. Their competitive positioning depends on maintaining engineering bandwidth for IEC 62443 cybersecurity certification timelines that extend project schedules.
| Leading Market Players |
|---|
| ABB Limited |
| Siemens AG |
| Yokogawa Electric Corporation |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| Emerson Electric Co. |
| Omron Corporation |
| Others |
Supply & Pricing Matrix
Sovereign wealth-backed procurement vehicles in Saudi Arabia and the UAE concentrate buyer power across giga-project industrial zones, compressing vendor margins while enforcing multi-year service unbundling that fragments pricing structures. This ownership pattern forces automation suppliers to absorb upfront hardware cost compression while recovering margin through discrete aftermarket service lines.
Pricing Analysis
Margin tightening in safety-instrumented systems reflects IEC 62443 cybersecurity certification timelines that extend project schedules and strain vendor engineering bandwidth. Project-based pricing dominates large hydrocarbon installations, with differentiation driven by SIL certification grade and after-sales service bundling. Cost compression accelerates in standard PLC tiers as Gulf sovereign buyers separate hardware procurement from multi-year maintenance agreements. State-owned oil operators exhibit lowest price sensitivity; Egyptian textile corridors in the Suez Canal Economic Zone show highest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced semiconductor components feeding PLC and servo drive production. Raw material dependencies span rare earth magnets for servo motors, silicon carbide substrates for power electronics, and specialized aluminum alloys for ruggedized enclosures. Tariff exposure through concentrated East Asian foundry supply creates procurement risk. Distribution runs through Dubai Jebel Ali free zone logistics hubs serving Gulf project corridors, with Johannesburg-Pretoria corridors anchoring sub-Saharan aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering bandwidth scarcity for firmware cybersecurity and predictive analytics competencies props pricing power for vendors with certified delivery capabilities. This supply-constrained structure favors incumbents with established Gulf project track records.
For Market Incumbents: Hedge margin erosion in hardware tiers by deepening in-house production of edge-AI modules and predictive analytics software layers. Certify engineering teams for IEC 62443 compliance ahead of competitor capacity buildout. Anchor relationships with Saudi Aramco and ADNOC digital field architecture programs to lock out emerging IoT platform providers. For New Entrants and Emerging Players: Egyptian textile and food processing operators in Suez Canal Economic Zone corridors present underserved buyer archetypes with legacy relay logic retrofit demand. Target predictive maintenance service contracts for South African platinum belt mining houses where incumbent vendor coverage gaps persist. Lead with edge-AI pilot programs demonstrating unplanned shutdown reduction to bypass hardware procurement gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap automation integrators with established UAE MOHAP certification pathways and Egyptian EOS electrical safety framework compliance. Long-term viability hinges on technology transfer commitments satisfying Gulf local content mandates. Monitor EU CBAM implementation velocity as inflection signal for carbon accounting module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Module Development | Fuses predictive maintenance algorithms with PLC architectures for remote oilfield installations. |
| IEC 62443 Certification Investment | Accelerates project timelines for Saudi Aramco downstream safety instrumented systems. |
| Local Content Partnership | Satisfies Gulf sovereign wealth vehicle technology transfer requirements for market access. |
| Carbon Accounting Integration | Embeds emissions verification within DCS architectures for EU CBAM compliance. |
| Aftermarket Service Unbundling | Captures margin through discrete maintenance agreements separated from hardware procurement. |
Research Methodology
Independent corroboration across automation vendor engineering directors, Gulf sovereign procurement officers, and South African mining maintenance heads underwrites the qualitative findings. Primary fieldwork captured perspectives from PLC firmware developers, edge computing platform architects, and IEC certification auditors. Secondary validation drew from SEC filings of listed automation conglomerates, Saudi Aramco supplier qualification databases, and UAE MOHAP equipment safety directives. Bottom-up project pipeline assessment triangulated against top-down macro industrial investment flows.
Rate-of-change decomposition across the projection horizon isolates technology adoption curves from capacity expansion cycles. Segmentation dimensions span product type maturity curves, technology frontier investment flows, end-use vertical concentration, and application functional priorities. CAGRs derive from installed base replacement cycles overlaid with greenfield project commissioning schedules. Industry-specific forecast inputs include Gulf giga-project capital deployment timelines and EU carbon border adjustment implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain normalization and Gulf workforce nationalization policy velocity. Forecasts reflect documented assumptions around edge-AI training data availability in brownfield environments and IEC 62443 certification bandwidth expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
United States SCADA Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Global Feeder Automation Market