
 Industrial Human-Machine Interface Market | 2026-2036
Industrial Human-Machine Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Human-Machine Interface Market Foresight
Germany is tilting toward advanced HMI production capacity as industrial automation suppliers expand European engineering centers. Siemens AG leverages deep PLC integration to anchor its position in process control rooms. Rockwell Automation sustains factory automation dominance through tightly coupled software-hardware bundles. Schneider Electric SE differentiates via energy management dashboards that merge power metering with operator interfaces.
An industrial human-machine interface comprises hardware and software systems enabling real-time interaction between operators and automated machinery, typically incorporating resistive or capacitive touch layers, hardened displays rated for IP65 ingress protection, and communication protocols such as EtherNet/IP or Profinet. Touchscreen product types command the largest installed base, though voice control interfaces are gaining traction in environments where glove-wearing limits touch accuracy. Supervisory Control and Data Acquisition technology represents the most mature revenue pool, while Human-Machine Interaction Software captures expanding margin as analytics layers migrate to edge computing architectures.
FDA 21 CFR Part 11 guidelines shape HMI design in pharmaceutical batch manufacturing, demanding audit trails and electronic signature capture. The EU Machinery Directive and IEC 62061 functional safety standards constrain product entry for non-certified Asian suppliers. OSHA lockout-tagout integration requirements in US facilities drive demand for safety-rated operator terminals. Stakeholders must weigh cybersecurity certification investments against the operational risk of unpatched legacy panels in connected plant environments.
Market Dynamics
Factory floor digitization in automotive assembly plants is compressing operator panel replacement cycles from seven-year baselines to three-year refresh schedules, forcing vendors to rearchitect hardware roadmaps around software-defined functionality.
Growth Catalysts
- Automotive Electrification Mandates:Battery gigafactory construction across Germany, Hungary, and Poland is generating concentrated demand for ruggedized touch panels capable of withstanding high-voltage assembly environments.
- IEC 62443 Certification Requirements:Cybersecurity standards for operational technology networks are reshaping product certification requirements, creating replacement demand for legacy panels lacking secure boot architectures.
- Ruhr Industrial Corridor Retrofits:Legacy equipment modernization programs in Germany's steel and chemical clusters are reallocating capital toward IP65-rated operator terminals with integrated safety functions.
Market Restraints
- Semiconductor Supply Concentration:Display driver IC fabrication concentrates in Taiwan and South Korea, exposing HMI vendors to allocation volatility during foundry capacity crunches.
- Functional Safety Certification Friction:IEC 62061 compliance timelines extend eighteen to twenty-four months for new product introductions, delaying revenue recognition for Asian suppliers lacking European notified body relationships.
- Inductive Proximity Sensor Substitution:Wearable augmented reality interfaces are displacing fixed-panel installations in maintenance and inspection workflows across aerospace final assembly lines.
Strategic Opportunities
- Pharmaceutical Batch Manufacturing:FDA 21 CFR Part 11 guidelines for electronic records and signatures are creating specialized demand for audit-trail-capable HMI configurations in US generic drug production facilities.
- Edge Analytics Convergence:Integration of machine learning inference engines directly into panel processors is hybridizing operator interfaces with predictive maintenance dashboards, opening premium pricing tiers.
- OSHA Lockout-Tagout Integration:US facilities are mandating safety-rated operator terminals with embedded energy isolation verification, creating regulatory tailwind for certified product lines.
Industry Challenges
- Cybersecurity Skill Scarcity:Operational technology security engineering talent shortages are delaying secure-by-design implementations across mid-tier automation suppliers.
- Legacy Protocol Integration Complexity:Brownfield installations require bridging EtherNet/IP and Profinet networks with decades-old proprietary fieldbus architectures, inflating commissioning costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Human-Machine Interface Market |
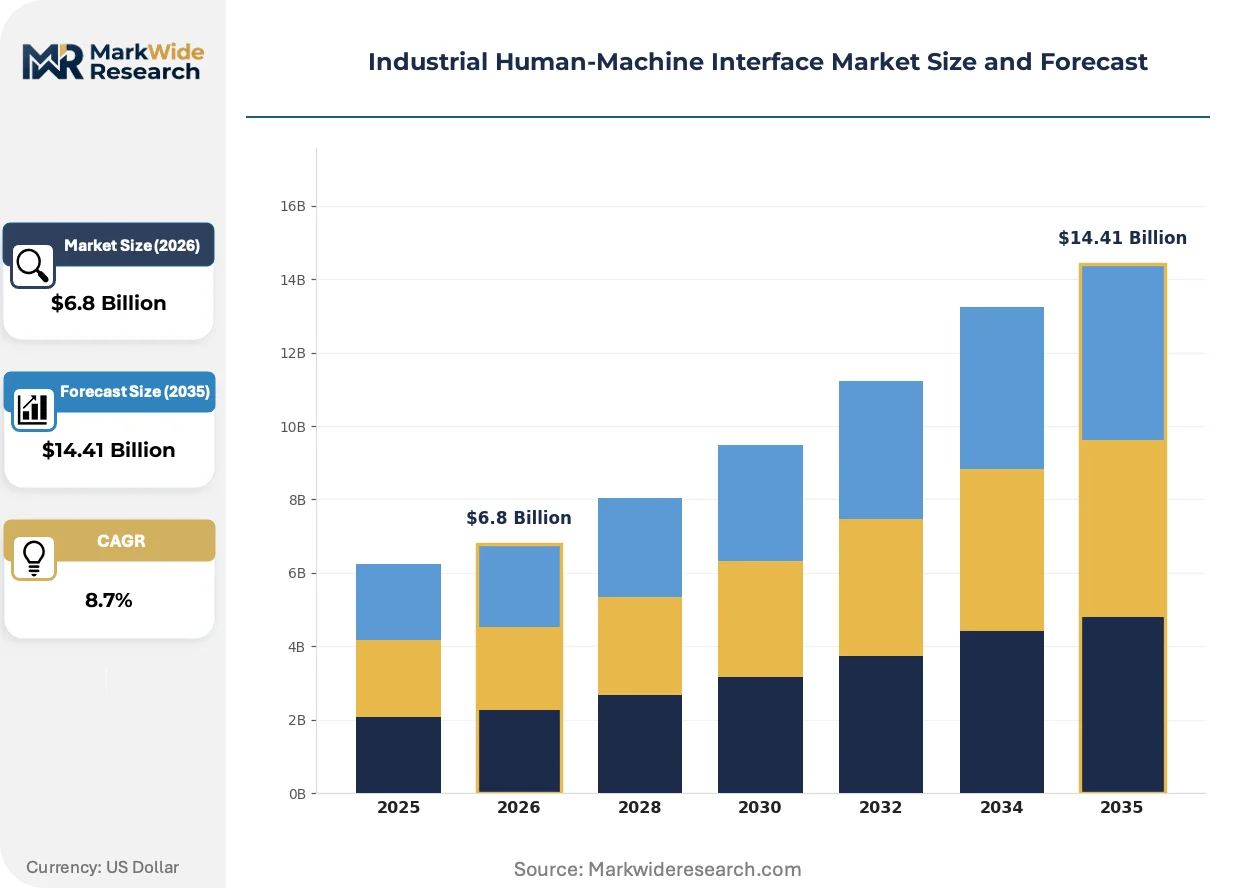
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen, Keypad, Voice Control, Gesture Control Technology: Programmable Logic Controllers, Supervisory Control and Data Acquisition, Human-Machine Interaction Software, Embedded Systems Application: Manufacturing, Oil & Gas, Automotive, Aerospace End User: Industrial Automation, Telecommunications, Consumer Electronics, Food & Beverage |
| Companies Covered | Rockwell Automation, Siemens AG, Schneider Electric SE, ABB Ltd, Honeywell International Inc., Mitsubishi Electric Corporation, Yokogawa Electric Corporation, Emerson Electric Co., Advantech Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Human-Machine Interface Market Shifts & Advancements
Voice control interfaces and edge-native analytics are fragmenting the traditional touchscreen monoculture, while regulatory pressure on operational technology cybersecurity is hardening certification requirements faster than product development cycles can absorb.
Multi-modal interaction architectures are hybridizing capacitive touch layers with voice recognition and gesture sensing to maintain operator effectiveness in glove-mandatory environments. Automotive paint shops and food processing facilities are piloting these configurations to reduce downtime from touch accuracy failures. The technology is compressing the addressable market for single-mode resistive panels while expanding total solution value through sensor fusion.
REACH restrictions on per- and polyfluoroalkyl substances are forcing display coating reformulations across European-bound product lines, with ECHA substance evaluations driving substitution timelines. Hardened glass suppliers are accelerating plasma-enhanced chemical vapor deposition alternatives to maintain oleophobic performance. Process control room deployments in German chemical plants are experiencing the most acute compliance-driven specification changes.
Buyer consolidation among contract electronics manufacturers is concentrating procurement leverage, with tier-one automotive suppliers unbundling HMI hardware from system integrator service contracts. Direct vendor relationships are replacing distributor-mediated purchasing for volume panel categories. This pattern is most pronounced in Hungary's growing automotive electronics manufacturing corridor.
Industrial Human-Machine Interface Market Segmentation
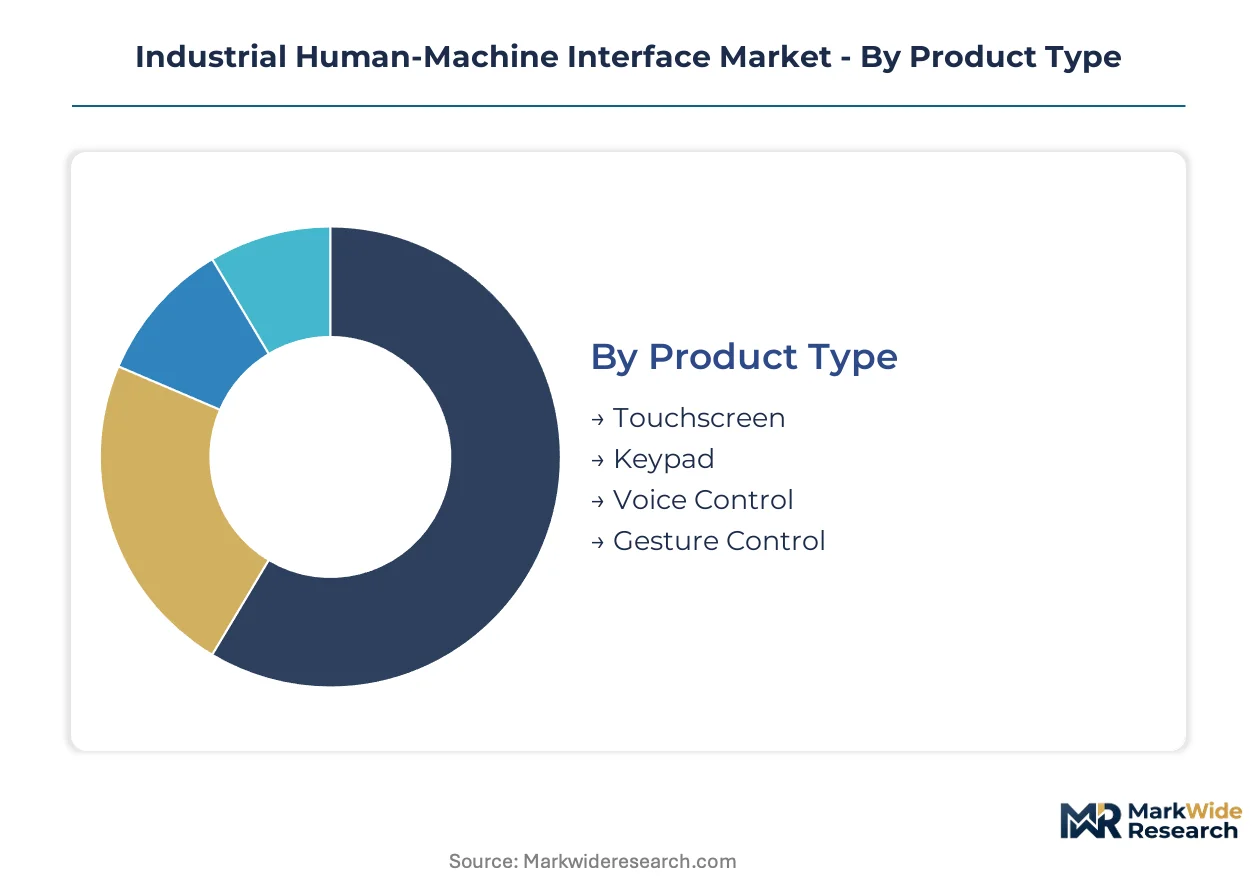
Replacement cycle compression in automotive assembly plants creates divergent velocity across interface modalities. Segmentation strategy must distinguish between hardware refresh rates measured in years versus software layers that update quarterly.
Product Type:
Touchscreen panels turn over fastest in battery gigafactory environments where resistive layers degrade under chemical exposure, while voice control installations persist longer in maintenance-light configurations.
- Touchscreen:Capacitive and resistive touch layers dominate factory floor deployments, with IP65-rated hardened displays constituting the bulk of automotive paint shop installations. Ruhr corridor steel mills are replacing seven-year baselines with three-year refresh schedules driven by digitization mandates.
- Voice Control:Speech recognition interfaces bypass glove-wearing limitations in food processing and pharmaceutical cleanrooms. Hungary's automotive electronics corridor is piloting multi-modal configurations combining voice with minimal touch backup.
- Keypad:Physical button arrays persist in safety-critical applications requiring tactile feedback without visual confirmation.
- Gesture Control:Camera-based motion sensing is penetrating aerospace final assembly lines where hands-free operation reduces foreign object debris risk.
Touchscreen dominates installed base. Voice control is where expansion concentrates.
Technology:
Margin structure varies sharply between commoditized hardware controllers and analytics software migrating to edge architectures.
- Human-Machine Interaction Software:Analytics layers running on panel processors are capturing expanding margin as machine learning inference hybridizes operator interfaces with predictive maintenance dashboards. FDA 21 CFR Part 11 compliance requirements in pharmaceutical batch manufacturing are creating specialized demand for audit-trail-capable configurations.
- Supervisory Control and Data Acquisition:SCADA represents the most mature revenue pool with established installed base across process industries. Brownfield bridging with legacy fieldbus architectures inflates commissioning costs in Germany's chemical clusters.
- Programmable Logic Controllers:Deep PLC integration anchors vendor positioning in process control rooms through tightly coupled software-hardware bundles.
- Embedded Systems:Dedicated panel processors with secure boot architectures are gaining traction as IEC 62443 certification requirements reshape procurement specifications.
SCADA retains the largest revenue base. Human-Machine Interaction Software is climbing the fastest.
Application:
Capital allocation intensity separates continuous process industries from discrete manufacturing refresh cycles.
- Automotive:Battery gigafactory construction across Germany, Hungary, and Poland is generating concentrated demand for ruggedized panels capable of withstanding high-voltage assembly environments. Electrification mandates are compressing procurement timelines.
- Manufacturing:General factory automation spans the broadest end-use spectrum with divergent safety and connectivity requirements across sub-sectors.
- Oil & Gas:Offshore platforms and refineries demand explosion-proof certifications extending product development timelines.
- Aerospace:Final assembly lines are experiencing displacement pressure from wearable augmented reality interfaces in maintenance and inspection workflows.
Manufacturing spans the widest footprint. Automotive is gaining share fastest.
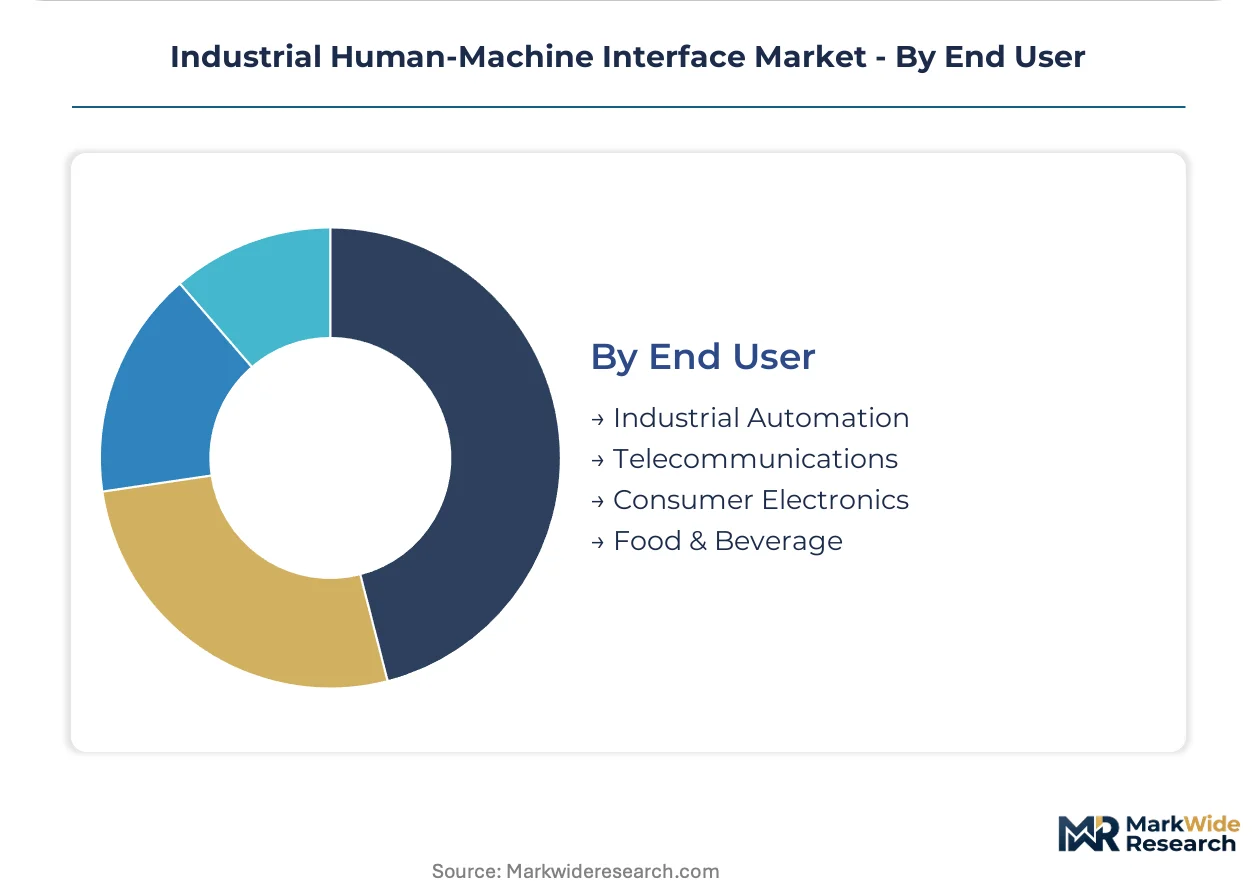
End User:
Procurement sophistication separates vertically integrated automation buyers from price-sensitive volume purchasers.
- Industrial Automation:System integrators and OEMs specify hardened panels with integrated safety functions, unbundling hardware from service contracts in tier-one automotive supplier relationships.
- Food & Beverage:Glove-mandatory environments drive multi-modal pilot programs combining touch alternatives with hygiene-rated enclosures.
- Telecommunications:Remote monitoring infrastructure demands ruggedized outdoor-rated terminals with extended temperature tolerances.
- Consumer Electronics:Contract electronics manufacturers concentrate procurement leverage, pressuring margin through direct vendor relationships.
Industrial Automation anchors volume. Food & Beverage is where specification innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display driver IC fabrication concentrates in Taiwan and South Korea, exposing industrial HMI vendors to allocation volatility during foundry capacity crunches. Regional demand patterns diverge sharply between mature automation corridors and emerging battery manufacturing clusters. Regulatory fragmentation across cybersecurity standards and functional safety certifications is reshaping procurement specifications by geography.
Germany
Ruhr industrial corridor retrofits and automotive battery gigafactory construction are driving demand for IP65-rated operator terminals with integrated safety functions. IEC 62443 cybersecurity standards and the EU Machinery Directive constrain product entry for non-certified suppliers. North Rhine-Westphalia's steel and chemical clusters are reallocating capital toward legacy equipment modernization programs.
United States
Pharmaceutical batch manufacturing and OSHA lockout-tagout integration requirements are creating specialized demand for safety-rated operator terminals. FDA 21 CFR Part 11 guidelines shape HMI design with mandatory audit trails and electronic signature capture. Michigan and Ohio automotive assembly plants are compressing operator panel replacement cycles from seven-year baselines to three-year refresh schedules.
China
Domestic battery gigafactory construction and factory floor digitization mandates are accelerating procurement timelines for ruggedized touch panels. GB standards and MIIT industrial automation policies guide local certification requirements. Yangtze River Delta manufacturing hubs are experiencing concentrated demand for high-voltage assembly environment interfaces.
Hungary
Automotive electronics manufacturing corridor expansion is generating concentrated demand for multi-modal HMI configurations combining voice with minimal touch backup. EU Machinery Directive compliance requirements filter procurement toward certified European vendors. The Budapest-Székesfehérvár industrial axis is attracting tier-one automotive supplier direct vendor relationships unbundled from system integrator contracts.
Japan
Process control room modernization and METI industrial digitization initiatives are sustaining demand for deeply integrated PLC-HMI bundles. JIS standards and functional safety certification requirements extend product development timelines for new market entrants. Kansai region chemical and steel facilities are prioritizing secure boot architectures to address operational technology cybersecurity gaps.
Industrial Human-Machine Interface Market Competitive Landscape
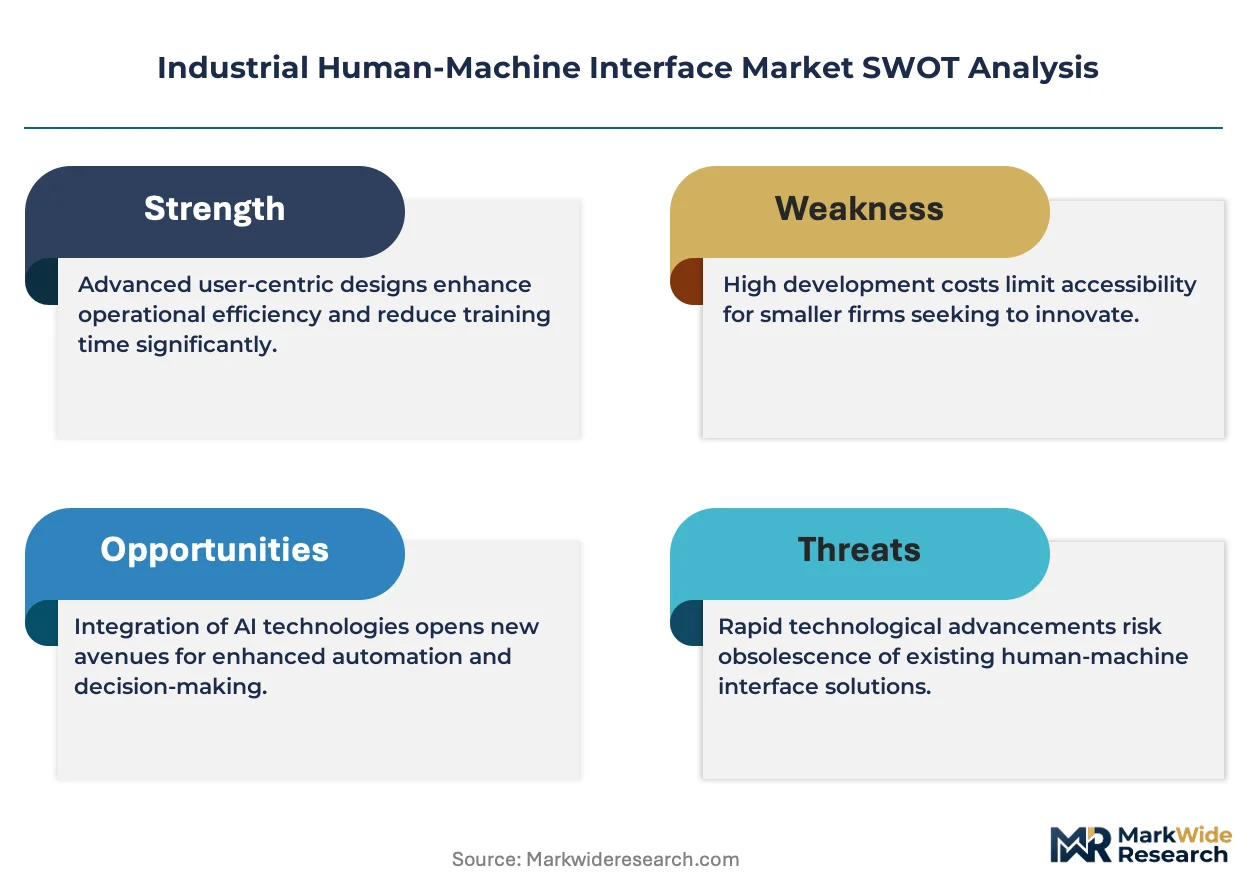
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base organizes around three structural tiers: diversified automation conglomerates with software-hardware bundles, specialized HMI hardware manufacturers, and embedded systems providers with secure-by-design architectures. Competitive positioning depends on IEC 62443 certification timelines and European notified body relationships. Primary competitive moves center on cybersecurity certification investments and edge analytics capability integration.
Among diversified automation conglomerates, Siemens AG and Rockwell Automation exemplify platform integration strategies, while Schneider Electric SE occupies a position within the energy management convergence archetype. These three companies represent the dominant competitive anchors in process control and factory automation deployment patterns. Their positioning reflects the industry-wide shift toward software-defined functionality and predictive maintenance dashboard integration.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Yokogawa Electric Corporation |
| Emerson Electric Co. |
| Advantech Co., Ltd |
| Others |
Supply & Pricing Matrix
Display driver IC fabrication concentrates in Taiwan and South Korea, anchoring margin pools in panel assembly and software licensing tiers where European vendors capture premium positioning through IEC 62443 certification. Pricing power fragments across upstream semiconductor allocation volatility and downstream buyer consolidation among tier-one automotive suppliers.
Pricing Analysis
IEC 62443 certification dictates the pricing tier structure across industrial HMI procurement, separating secure-boot embedded systems from uncertified commodity panels. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety grade, cybersecurity compliance status, and after-sales service bundling. Cost compression in standard-tier resistive panels is intensifying because buyer consolidation among contract electronics manufacturers concentrates procurement leverage. Tier-one automotive suppliers exhibit lowest price sensitivity due to unbundled direct vendor relationships, while mid-tier system integrators face margin pressure from distributor bypass.
Supply Chain Analysis
Contract electronics manufacturers including Foxconn, Jabil, and Flex hold concentrated capacity for hardened display assembly and system integration. Taiwan, South Korea, and Japan anchor upstream supply for display driver ICs, industrial-grade glass substrates, and secure microcontroller units. Single-source vulnerability in Taiwan Semiconductor Manufacturing Company foundry allocation exposes vendors to capacity crunches during automotive demand surges. Distribution runs through direct vendor relationships for volume automotive contracts and authorized distributors for fragmented industrial automation accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement functions at tier-one automotive suppliers, fragmenting margin capture across upstream component vendors and downstream system integrators.
For Market Incumbents: Entrench cybersecurity certification leadership by accelerating IEC 62443 SL2-SL3 product line completion ahead of European notified body bottlenecks. Deepen backward integration into edge analytics software stacks to defend against PLC-agnostic interface entrants. Lock in multi-year direct procurement contracts with Hungary's automotive electronics corridor before facility commissioning peaks. For New Entrants and Emerging Players: Poland's battery gigafactory construction zones offer underpenetrated demand for ruggedized high-voltage assembly panels lacking established vendor relationships. Target pharmaceutical batch manufacturing in US generic drug facilities where FDA 21 CFR Part 11 compliance creates specialized barriers incumbent automation giants address slowly. Lead with audit-trail-native software architectures and rapid certification timelines against eighteen-month European compliance baselines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-native HMI configurations requiring machine learning inference hardware and secure-by-design firmware development. Viable acquisition targets combine embedded systems expertise with existing European notified body relationships, shortening time-to-revenue for certified product introductions. Monitor IEC 62443 certification backlog durations at TÜV Rheinland and DEKRA as early signals of competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Acceleration | SL2-SL3 product lines unlock procurement eligibility in Germany's Ruhr corridor retrofits. |
| Edge Analytics Integration | Machine learning inference engines hybridize operator panels with predictive maintenance dashboards. |
| Direct Vendor Relationship Expansion | Unbundled procurement contracts in Hungary bypass distributor margin capture. |
| Multi-Modal Interface Development | Voice-gesture fusion addresses glove-mandatory environments in food processing cleanrooms. |
| Secure Boot Architecture Migration | Hardware-backed cybersecurity replaces legacy panels in connected plant environments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists; and secondary validation against SEC 10-K filings, IEC certification registries, customs/trade data, and automotive production databases. Bottom-up unit economics triangulated against top-down market sizing across touchscreen, voice control, keypad, and gesture control modalities.
Forecast inputs span product type, technology layer, application vertical, and end-user procurement sophistication across the projection horizon. Modeled segmentation incorporates interface modality, software-hardware bundling intensity, safety certification tier, and regional regulatory cluster. CAGRs derive from replacement cycle compression analysis in automotive assembly plants and brownfield modernization velocity in German chemical clusters. Edge computing adoption curves and cybersecurity compliance timelines inform growth trajectory assumptions.
Practitioners should monitor foundry capacity allocation at Taiwan Semiconductor Manufacturing Company, IEC 62443 certification backlog durations at European notified bodies, and wearable augmented reality substitution rates in aerospace maintenance workflows for early signals of forecast revision. Quarterly review of automotive electrification mandate implementation timelines and battery gigafactory construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Smart Industries Market
Industrial Automation
Asia-Pacific Medical Automation Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Europe ICS Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Intralogistics Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Programmable Logic Controller Market