
 Latin America Factory Automation and Industrial Controls Market | 2026-2036
Latin America Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Factory Automation and Industrial Controls Market Foresight
IP65-rated enclosure specifications and SIL-certified safety systems are unwinding legacy equipment cycles across Latin American plants. Schneider Electric SE leverages its regional distribution network to anchor medium-voltage automation contracts in Brazil. Siemens AG dominates process control integration for petrochemical complexes along Mexico's Gulf Coast. Rockwell Automation Inc. differentiates through its Logix platform specialization in automotive body-in-white applications.
Factory automation and industrial controls encompass electromechanical systems, programmable logic controllers, distributed control architectures, and human-machine interfaces operating across voltage classes from 24V DC to 13.8kV, designed to execute sequential logic, process regulation, and safety interlocking with response times below 10 milliseconds in critical loops. Their primary purpose centers on reducing process variability, eliminating unplanned downtime, and enforcing traceable quality gates in continuous and discrete manufacturing environments. PLC and DCS deployments represent the mature revenue base, while IoT-enabled predictive maintenance modules and AI-driven quality control applications capture the fastest expansion within the technology segment. Process control and assembly line applications generate the deepest margin pools due to long-term service contracts and spare part lock-in.
Brazil's INMETRO, Mexico's NOM standards through CONUEE, and Argentina's IRAM certification frameworks collectively mandate energy efficiency tiers and electromagnetic compatibility testing for imported industrial equipment, effectively filtering low-cost Asian suppliers from premium project bids. These compliance layers extend procurement cycles but protect incumbent European and North American vendors with established local testing partnerships. Stakeholders must weigh certification lead times against total cost of ownership when selecting automation architectures for multi-country manufacturing footprints.
Market Dynamics
IP65-rated enclosure specifications and SIL-certified safety systems are unwinding legacy equipment cycles across Latin American plants, forcing wholesale replacement of electromechanical relay systems that dominated prior decades.
Growth Catalysts
- Automotive export mandates:Mexican and Brazilian automotive manufacturers are expanding robotic assembly lines to meet North American and European quality benchmarks for precision welding and paint application.
- INMETRO certification acceleration:Brazil's mandatory energy efficiency tiers for industrial electrical equipment are shortening replacement cycles for motor control centers and variable frequency drives.
- Bajío corridor concentration:Mexico's automotive manufacturing belt around León and Querétaro is generating concentrated demand for body-in-white automation and coordinated motion control systems.
Market Restraints
- Copper price volatility:Fluctuations in copper conductor costs directly compress margins for medium-voltage switchgear and motor control center manufacturers serving Brazilian petrochemical clients.
- Import dependency concentration:Seventy percent of precision motion control components originate from German and Japanese suppliers, exposing Latin American integrators to extended lead times and currency hedge costs.
- Legacy protocol incompatibility:Proprietary fieldbus systems installed during the 1990s lack native Ethernet/IP or PROFINET translation, forcing expensive gateway architectures or full rip-and-replace decisions.
Strategic Opportunities
- Colombian underpenetration:Colombia's manufacturing base retains eighty percent relay-based control architecture, creating first-mover advantage for PLC and HMI vendors establishing local application engineering.
- CONUEE incentive alignment:Mexico's national energy efficiency agency offers accelerated depreciation for NOM-certified variable frequency drive installations, tilting procurement toward premium efficiency tiers.
- Edge-AI convergence:Integration of machine vision inference engines directly into safety-rated PLCs is enabling real-time defect detection without separate industrial PC infrastructure, reducing panel complexity.
Industry Challenges
- Certification timeline compression:IRAM electromagnetic compatibility testing in Argentina requires six-to-nine month lead times, forcing project planners to front-load procurement decisions before final site readiness confirmation.
- Multiprotocol integration complexity:Plants mixing Siemens S7, Rockwell ControlLogix, and Schneider Modicon architectures face escalating engineering costs for unified SCADA visualization and cross-platform safety interlocking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Factory Automation and Industrial Controls Market |
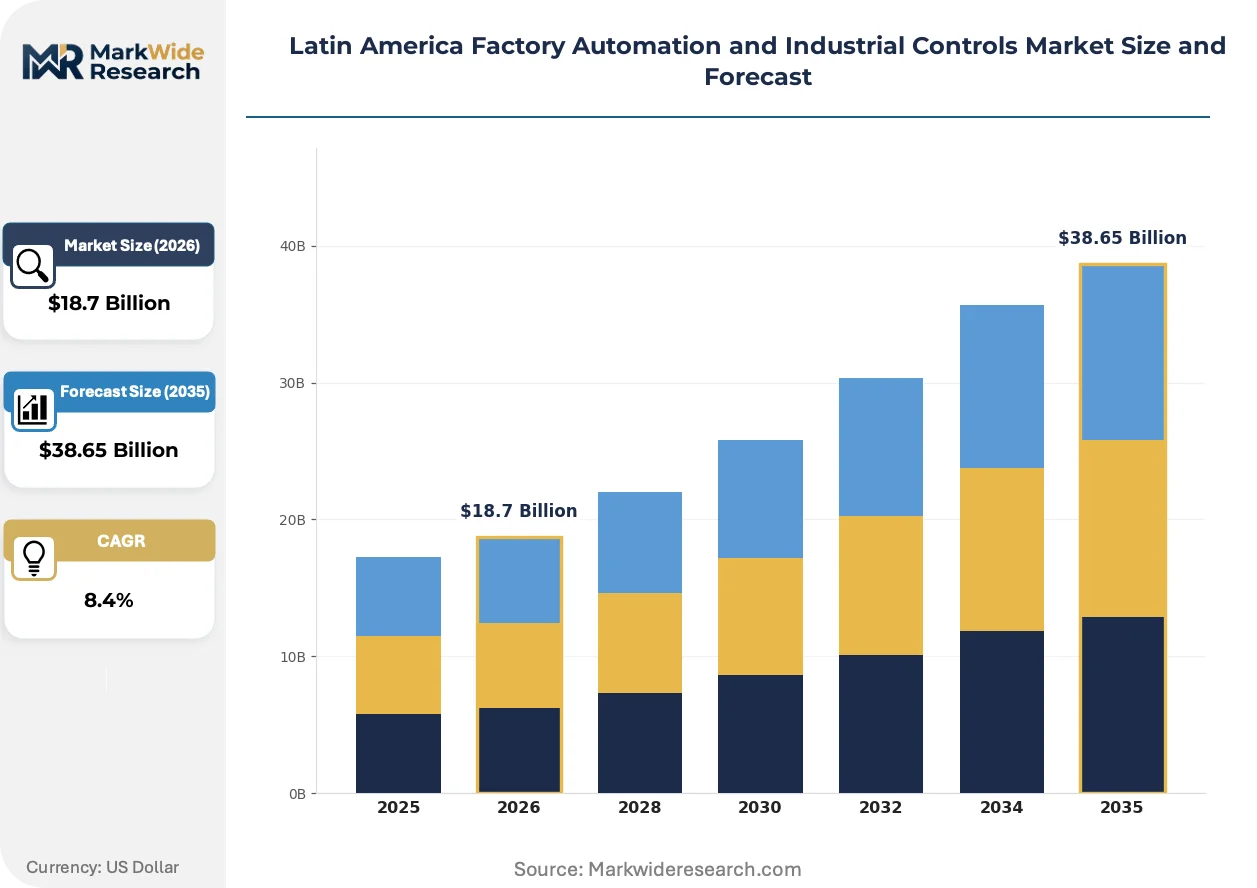
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, SCADA, DCS, HMI End User: Manufacturing, Oil & Gas, Automotive, Food & Beverage Technology: IoT, AI, Robotics, Cloud Computing Application: Process Control, Quality Control, Assembly Line, Safety Management |
| Companies Covered | Schneider Electric SE, Honeywell International Inc., Siemens AG, General Electric Co., Mitsubishi Electric Corporation, ABB Ltd, Emerson Electric Co., WEG Industrias S.A., Rockwell Automation Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Factory Automation and Industrial Controls Market Shifts & Advancements
Digital thread architectures are reconfiguring how Latin American manufacturers approach equipment lifecycle management, compressing the boundary between operational technology and enterprise resource planning systems.
Edge computing nodes with IEC 62443-3-3 security certification are fragmenting traditional hierarchical automation pyramids by enabling localized decision loops for predictive maintenance algorithms. Automotive stampers in São Paulo's ABC region deploy these devices to process vibration signatures without cloud dependency, reducing latency for press protection systems from fifty milliseconds to under five. This topology is compressing the addressable market for centralized historian software while expanding opportunities for ruggedized edge hardware with embedded cybersecurity.
Brazil's INMETRO Ordinance 623 now mandates efficiency testing for low-voltage three-phase motors above 0.75 kW, effectively banning importation of IE1 efficiency class equipment. Industrial buyers in Minas Gerais mining operations are responding by specifying IE4 permanent magnet synchronous motors paired with active front-end drives, despite thirty percent capital cost premiums. The regulation is accelerating obsolescence of established motor-distributor relationships and favoring vendors with integrated drive-motor portfolios.
After-sales service unbundling is disrupting traditional automation vendor lock-in across Mexican maquiladora operations. Discrete manufacturers in Tijuana are separating hardware procurement from commissioning and ongoing support, awarding multivendor maintenance contracts to specialized system integrators with cross-platform competency. This pattern is most pronounced in medical device manufacturing, where FDA validation requirements for 21 CFR Part 11 compliance create specialized service demand that original equipment manufacturers struggle to fulfill at competitive rates.
Latin America Factory Automation and Industrial Controls Market Segmentation
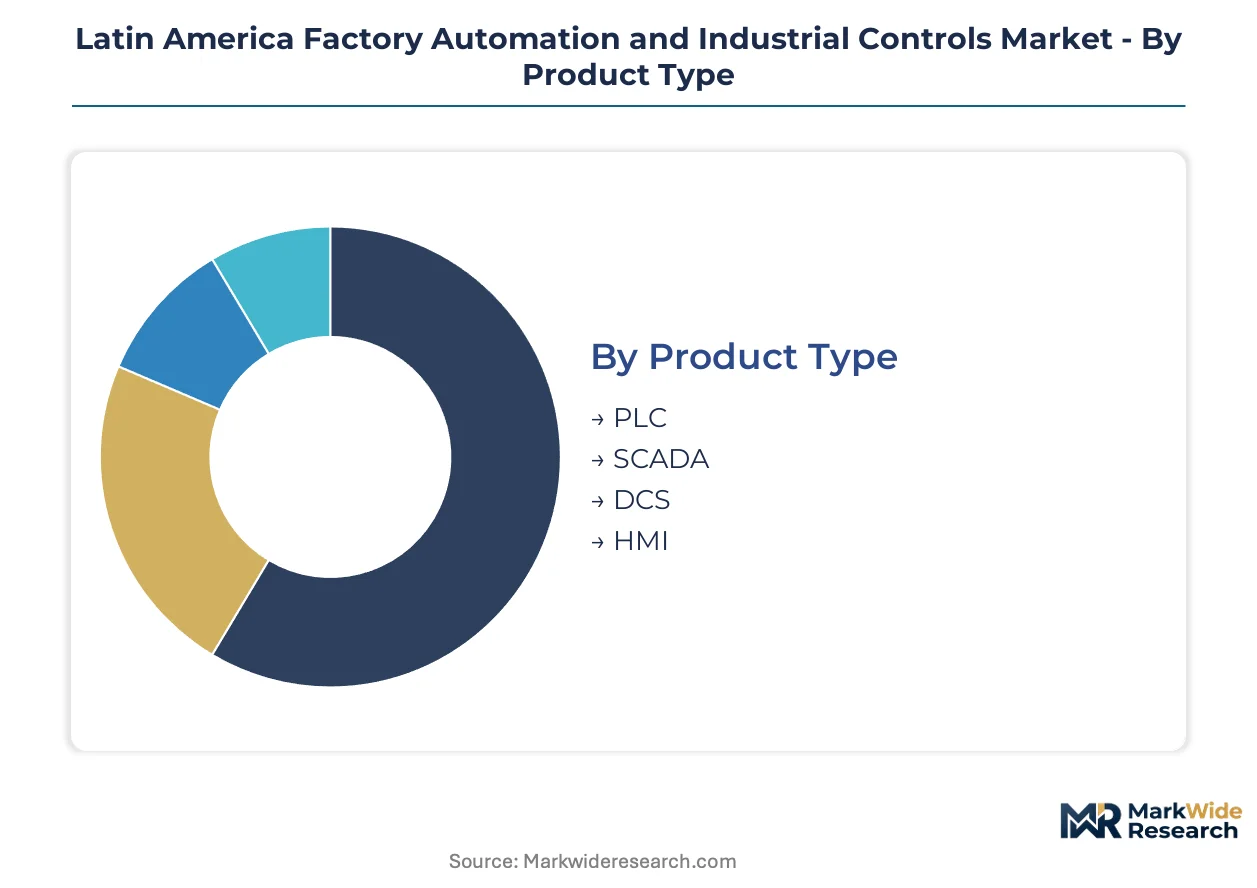
Segmentation in Latin American factory automation reveals divergent investment patterns between export-oriented manufacturing clusters and domestically focused processing industries. Understanding these splits enables vendors to align product portfolios with certification requirements and replacement cycles specific to each vertical.
Product Type:
Domestic process industries favor DCS architectures for continuous operations, while export manufacturing corridors drive discrete PLC and HMI demand.
- PLC:Ruggedized controllers with IEC 61131-3 programming environments dominate discrete manufacturing. Mexican automotive stampers in Querétaro deploy these for coordinated motion control in body-in-white cells serving North American export programs.
- SCADA:Distributed visualization platforms aggregate field data across geographically dispersed assets. Brazilian petrochemical complexes along the São Paulo coast utilize these systems to monitor pipeline integrity under ANP regulatory oversight.
- DCS:Process control architectures for continuous operations in pulp mills and sugar-ethanol plants.
- HMI:Industrial-grade touch interfaces with IP65 ratings for washdown environments in food processing.
PLC commands the established base. The steepest expansion runs through SCADA deployments integrating legacy fieldbus with modern analytics layers.
End User:
Cost tier stratification separates capital-intensive process industries from high-volume discrete manufacturers with shorter automation payback horizons.
- Manufacturing:Discrete production spanning electronics assembly, metal fabrication, and consumer goods. Colombian manufacturers in the Medellín valley are retrofitting relay-based lines with compact PLCs to meet export quality thresholds for North American retail chains.
- Oil & Gas:Upstream and downstream automation for flow control, safety shutdown, and custody transfer. Mexican offshore platforms in the Gulf of Mexico specify SIL-certified safety instrumented systems under ASEA regulatory mandates for hydrocarbon processing.
- Automotive:OEM and tier supplier automation for welding, painting, and final assembly operations.
- Food & Beverage:Hygienic automation for processing, packaging, and cold chain logistics.
Oil & Gas retains the deepest margin pool through long-term service contracts. Food & Beverage is gaining share fastest as cold chain modernization accelerates across Brazil and Mexico.
Technology:
Application maturity separates proven robotics deployments from emerging AI layers still navigating certification pathways.
- IoT:Sensor networks and edge gateways enabling predictive maintenance. Argentine food processors in Buenos Aires province deploy vibration monitoring on critical pumps to reduce unplanned downtime in export meatpacking operations.
- AI:Machine vision and process optimization algorithms. São Paulo automotive suppliers implement defect detection systems for real-time quality gates meeting stringent OEM traceability requirements.
- Robotics:Articulated arms and collaborative systems for material handling and precision assembly.
- Cloud Computing:Remote data aggregation and enterprise system integration for multi-site operations.
Robotics anchors current investment. AI applications are climbing the fastest as edge inference engines displace centralized processing architectures.
Application:
Customer type differentiation separates process control buyers with decade-long asset horizons from safety management purchasers facing compressed regulatory compliance windows.
- Process Control:Continuous regulation of temperature, pressure, and flow in chemical and petrochemical operations. Brazilian fertilizer producers in Bahia specify redundant controller architectures to maintain production continuity under strict environmental licensing conditions.
- Quality Control:Automated inspection and traceability systems. Mexican medical device manufacturers in Tijuana deploy vision systems for FDA-compliant validation documentation supporting US market access.
- Assembly Line:Coordinated motion and sequencing for discrete manufacturing operations.
- Safety Management:Emergency shutdown, interlocking, and personnel protection systems.
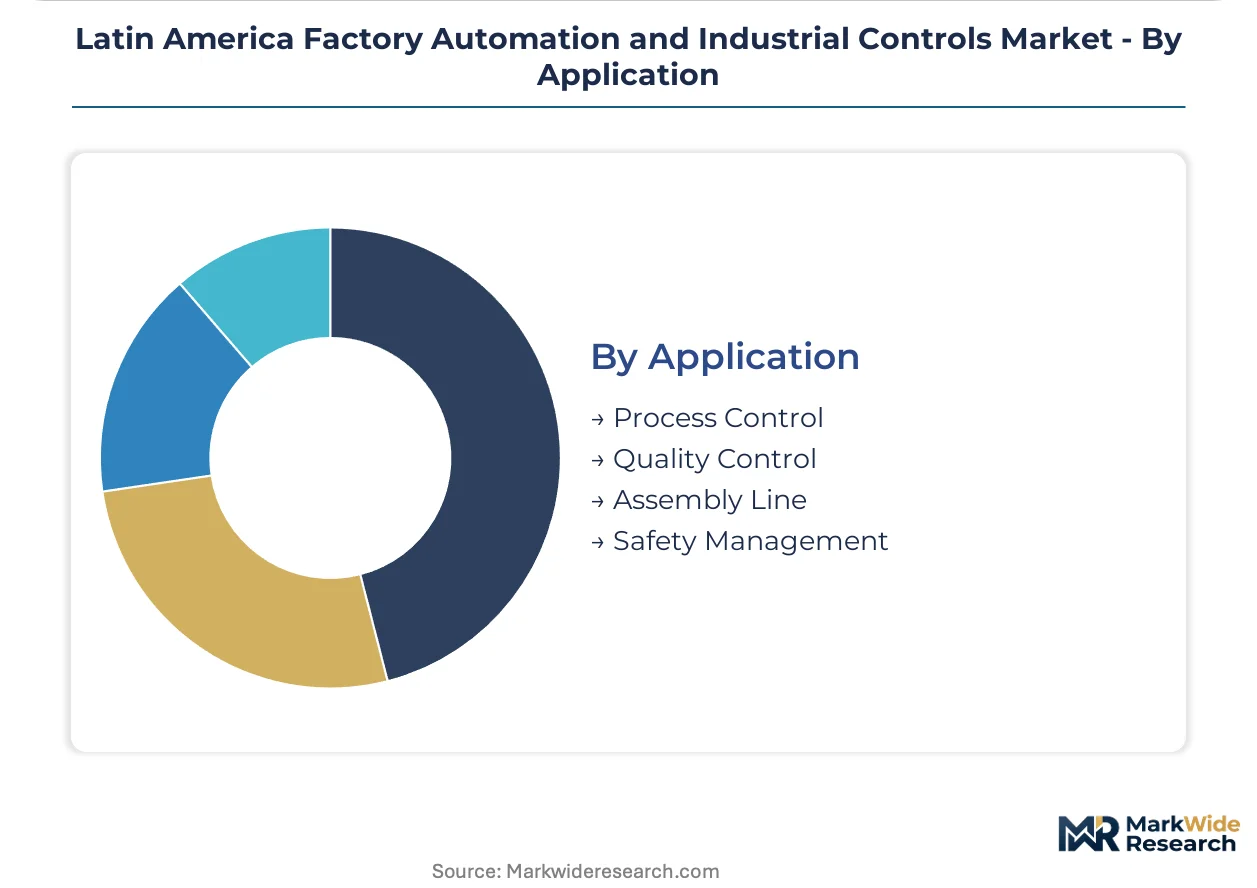
Process Control represents the largest installed base. Safety Management is expanding most quickly as INMETRO and NOM standards accelerate replacement of legacy electromechanical protection systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America's factory automation market tilts toward import substitution as regional manufacturers seek to reduce dependency on Asian component supplies. Export-oriented automotive clusters in Mexico and Brazil drive premium equipment demand, while domestic processing industries in Argentina and Colombia lag in modernization cycles. Regulatory divergence across national certification frameworks fragments procurement strategies for multinational operators.
Mexico
Automotive stampers in the Bajío corridor around León and Querétaro deploy coordinated motion control systems for North American export programs. CONUEE accelerates depreciation for NOM-certified variable frequency drives, tilting procurement toward premium efficiency tiers. Tijuana's medical device manufacturers separate hardware procurement from commissioning, awarding multivendor maintenance contracts to specialized integrators.
Brazil
INMETRO Ordinance 623 mandates efficiency testing for low-voltage motors above 0.75 kW, effectively banning IE1 equipment importation. Minas Gerais mining operations specify IE4 permanent magnet synchronous motors despite thirty percent capital cost premiums. São Paulo's ABC region automotive stampers deploy edge computing nodes to process vibration signatures without cloud dependency.
Argentina
IRAM electromagnetic compatibility testing requires six-to-nine month lead times, forcing project planners to front-load procurement decisions. Buenos Aires province food processors deploy vibration monitoring on critical pumps to reduce unplanned downtime in export meatpacking operations. The country's manufacturing base retains substantial relay-based control architecture awaiting replacement cycles.
Colombia
Eighty percent of manufacturing control architecture remains relay-based, creating first-mover advantage for PLC and HMI vendors establishing local application engineering. Medellín valley manufacturers retrofit legacy lines with compact PLCs to meet export quality thresholds for North American retail chains. The national energy efficiency agency structures incentive alignment for premium automation equipment procurement.
Chile
Mining automation demand concentrates in copper extraction operations facing pressure to maintain output amid price volatility. The country's national mining regulator enforces safety instrumented system standards for hydrocarbon processing adjacent to extraction sites. Antofagasta and Atacama desert operations specify ruggedized edge hardware with embedded cybersecurity for remote asset monitoring.
Latin America Factory Automation and Industrial Controls Market Competitive Landscape
Concentration sits with European and North American conglomerates possessing established local testing partnerships for INMETRO, NOM, and IRAM certification pathways. The vendor base stratifies across three tiers: integrated automation platforms with full voltage-class coverage, regional specialists in medium-voltage motor control, and emerging system integrators with cross-platform competency. Dominant competitive moves include portfolio diversification into edge-AI modules and strategic partnerships with local engineering firms to compress commissioning timelines.
Within the integrated platform tier, Schneider Electric SE anchors medium-voltage automation contracts through its regional distribution network, while Siemens AG occupies a position in process control integration for petrochemical complexes. Rockwell Automation Inc. exemplifies specialization strategy through Logix platform deployment in automotive body-in-white applications. These three European and North American entities represent the archetype of certification-compliant vendors filtering low-cost Asian suppliers from premium project bids.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc. |
| Siemens AG |
| General Electric Co. |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Emerson Electric Co. |
| WEG Industrias S.A. |
| Rockwell Automation Inc. |
| Others |
Supply & Pricing Matrix
IE4 permanent magnet synchronous motors displacing IE1 induction units across Brazilian mining operations simultaneously concentrates procurement toward German and Japanese drive-motor portfolios while compressing price elasticity for efficiency-tier premiums. This substitution dynamic redirects supply flows through INMETRO-certified channels and elevates total cost-of-ownership calculations over upfront capital expenditure in buyer negotiations.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Latin American automation markets. Three-tier pricing stratification separates SIL-certified safety systems from standard PLC architectures and economy relay replacements, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from copper conductor volatility in medium-voltage switchgear, compressing margins for Brazilian petrochemical contractors. System integrators exhibit highest price sensitivity due to currency hedge exposure, while mining operators in Minas Gerais demonstrate lowest sensitivity given efficiency-mandate compliance deadlines.
Supply Chain Analysis
Germany and Japan anchor precision motion control component fabrication for Latin American automation deployments. German suppliers feed servo motors and linear actuators while Japanese manufacturers source CNC controllers and robotic articulators, with both channels drawing from rare earth magnet processing concentrated in China. Single-source vulnerability runs through field-programmable gate arrays for safety-rated controllers. Distribution runs through authorized distributor networks with local application engineering support rather than direct vendor-to-plant sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national certification regimes creates niche entry points for specialists with IRAM, INMETRO, or NOM testing partnerships. After-sales unbundling in Mexican maquiladora operations fragments traditional vendor lock-in and elevates cross-platform integrator value.
For Market Incumbents: Fortify certification moats by deepening local testing partnerships with INMETRO, CONUEE, and IRAM bodies to extend procurement cycle advantages. Expand captive service organizations in São Paulo and Querétaro to capture unbundled maintenance contracts from medical device and automotive stampers facing FDA and OEM validation requirements. Vertical integration into edge-AI hardware with IEC 62443-3-3 security certification defends against emerging cybersecurity specialists.
For New Entrants and Emerging Players: Differentiate on CONUEE-aligned energy efficiency retrofit packages targeting Colombia's relay-dominated manufacturing base in the Medellín valley. Establish local application engineering presence before hardware volume to capture first-mover advantage in Bogotá and Cali industrial corridors. Partner with established system integrators possessing existing NOM certification pathways rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: INMETRO Ordinance 623 implementation reshapes the acquisition landscape toward integrated drive-motor portfolios with established Brazilian testing partnerships. Target mid-cap specialists with captive IE4 motor production and active front-end drive integration capabilities. Watch for inflection signals in Colombian energy efficiency incentive expansion and Argentine IRAM timeline compression as catalysts for regional consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Processing | Secures supply continuity for IE4 permanent magnet motors under INMETRO efficiency mandates. |
| Local Application Engineering Expansion | Captures unbundled commissioning contracts from Tijuana medical device manufacturers facing FDA validation. |
| Edge-AI Module Certification Investment | Enables real-time defect detection without separate industrial PC infrastructure in São Paulo automotive stampers. |
| Cross-Platform Integration Partnership | Addresses multiprotocol complexity mixing Siemens S7, Rockwell ControlLogix, and Schneider Modicon architectures. |
| IRAM Testing Partnership Establishment | Compresses six-to-nine month electromagnetic compatibility lead times for Argentine project planners. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists and refined through secondary validation. Trade data from Brazilian customs authorities, INMETRO certification registries, CONUEE efficiency equipment listings, and SEC filings from listed automation vendors anchored quantitative baselines. Bottom-up equipment deployment estimates triangulated against top-down manufacturing value-added projections across the analysis window.
Variance decomposition structured the analytical framework across product type, end-user vertical, technology maturity, and application criticality dimensions throughout the forecast period. CAGRs derived from installed base replacement cycles, regulatory mandate implementation timelines, and export manufacturing capacity expansion in the Bajío corridor and São Paulo ABC region. Copper price volatility indices and currency fluctuation bands informed margin sensitivity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained automotive export demand, stable certification timelines, and continued efficiency regulation enforcement would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and supply chain disruption frequency. Recalibration cycles align with material shifts in INMETRO ordinance revisions, CONUEE incentive program updates, and regional trade agreement modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Europe Industrial Embedded Systems Market