
 Europe Smart Manufacturing Market | 2026-2036
Europe Smart Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Manufacturing Market Foresight
Asset-light project financing and equipment-leasing structures are tilting competitive dynamics toward mid-tier manufacturers that previously lacked balance-sheet capacity for full automation overhauls. Siemens AG leverages its digital twin portfolio to anchor large-scale deployments across German automotive plants. ABB Ltd sustains technology leadership through its robotics-software integration stack, while Schneider Electric SE competes on energy-management convergence with production control systems.
Europe Smart Manufacturing denotes the integration of cyber-physical production systems, industrial IoT architectures, and AI-driven process optimization within factory environments, typically operating at latency thresholds below 10 milliseconds for real-time control loops and achieving Overall Equipment Effectiveness improvements of 15-25 percentage points over conventional lines. The primary purpose is to synchronize demand signals with flexible production capacity while minimizing energy intensity and material waste. Automation Software commands the deepest margin pools due to recurring licensing architectures and sticky enterprise integrations, whereas Edge Computing represents the fastest-expanding technology layer as plants push inference workloads closer to sensors to reduce cloud-dependency and latency exposure. Industrial Robots retain volume leadership but face margin compression from Chinese supplier encroachment into the sub-20kg payload segment.
The EU AI Act, REACH chemical compliance frameworks, and CE marking under the Machinery Directive collectively shape product standards, data governance obligations, and market access conditions for smart manufacturing equipment deployed across member states. ECHA substance restrictions and the F-Gas Regulation further constrain sensor coolant selections and pneumatic system designs, forcing vendors to requalify component supply chains. Stakeholders must monitor how the CSRD disclosure regime alters capital allocation priorities for brownfield retrofit versus greenfield automation investments.
Market Dynamics
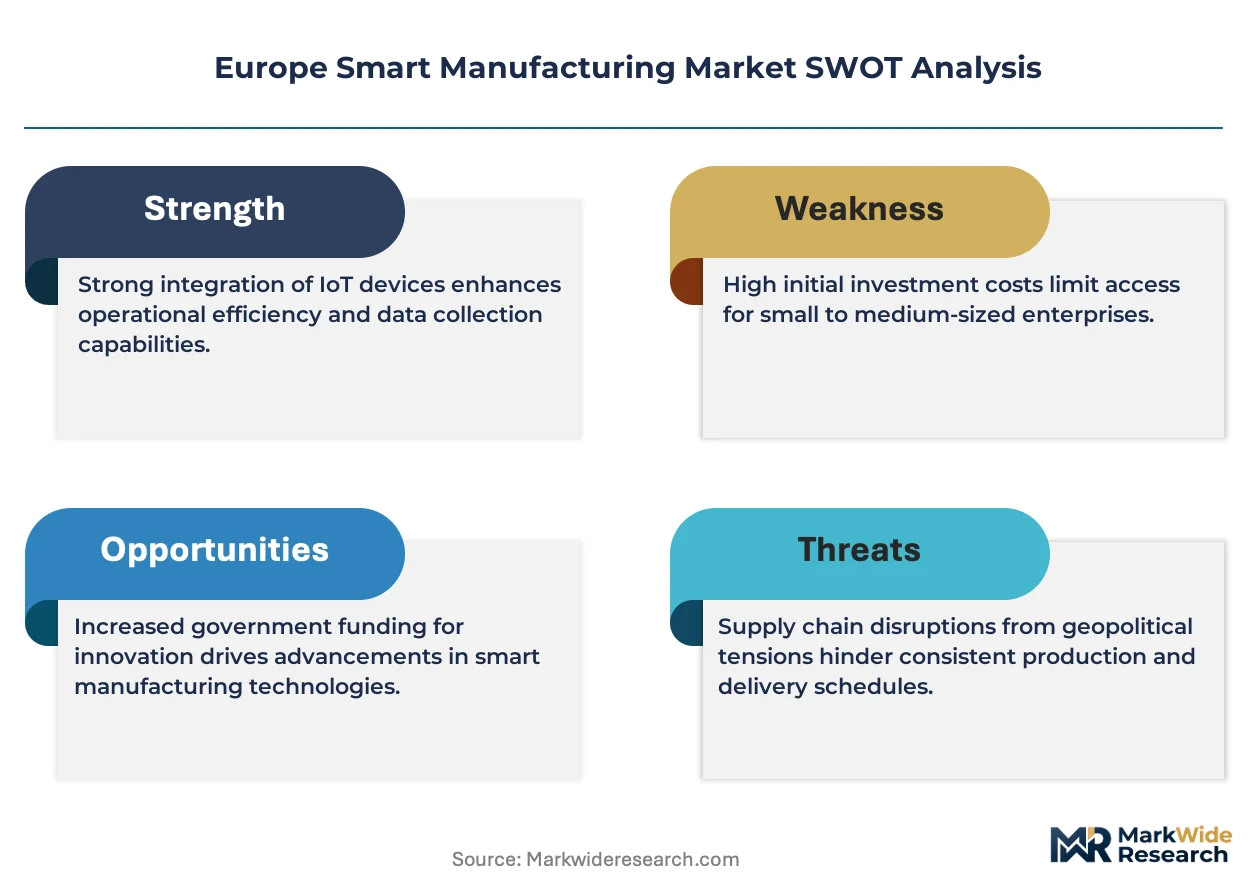
EU Green Deal carbon intensity targets are forcing automotive OEMs and steel producers to retrofit legacy production lines with energy-optimized control architectures, compressing payback period calculations and reshaping vendor selection criteria across the Ruhr and Upper Silesian industrial corridors.
Growth Catalysts
- Industry 5.0 Policy Framework:The EU Commission's human-centric manufacturing mandate accelerates cobot deployment in French and Italian precision machining facilities, prioritizing adaptive automation over full replacement.
- REACH Chemical Compliance:Restricted substance lists under ECHA jurisdiction drive sensor manufacturers toward solid-state alternatives, creating upgrade cycles in pneumatic-heavy automotive stamping plants.
- Ruhr Valley Cluster Density:Proximity of tooling suppliers, system integrators, and steel-to-semiconductor value chains reduces integration friction and shortens commissioning timelines for brownfield retrofits.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet dependency for servo motors and robotics actuators concentrates in non-European processing facilities, exposing automation projects to input cost volatility and quota risk.
- F-Gas Regulation Phase-Down:Refrigerant restrictions under EU climate law force requalification of thermal management systems in precision metrology equipment, extending product development cycles.
- Legacy Protocol Fragmentation:Proprietary fieldbus architectures in German automotive plants resist seamless integration with OPC-UA overlays, requiring costly gateway layers and custom middleware.
Strategic Opportunities
- Eastern European Manufacturing Catch-Up:Polish and Czech automotive component suppliers remain below 15 percent automation penetration, creating first-mover advantage for equipment-leasing structures and pay-per-output financing.
- CSRD-Driven Disclosure Demand:Mandatory sustainability reporting under EU corporate law positions energy-management software vendors to embed carbon accounting directly into MES platforms.
- Edge-AI Convergence:Fusion of time-series analytics with vision inspection at the network edge enables sub-10-millisecond defect rejection in semiconductor packaging lines without cloud dependency.
Industry Challenges
- OT Cybersecurity Skill Scarcity:Manufacturing engineers with combined PLC programming and zero-trust network architecture expertise command premium compensation, constraining rollout velocity for mid-tier system integrators.
- CE Marking Machinery Directive Timelines:Conformity assessment procedures for AI-enabled safety systems extend certification cycles by 8-14 months, delaying revenue recognition for robotics vendors.
- Intergenerational Workforce Transition:Retiring German toolmakers possess tacit knowledge of mechanical fault signatures that machine learning models struggle to replicate, creating diagnostic blind spots in predictive maintenance deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Manufacturing Market |
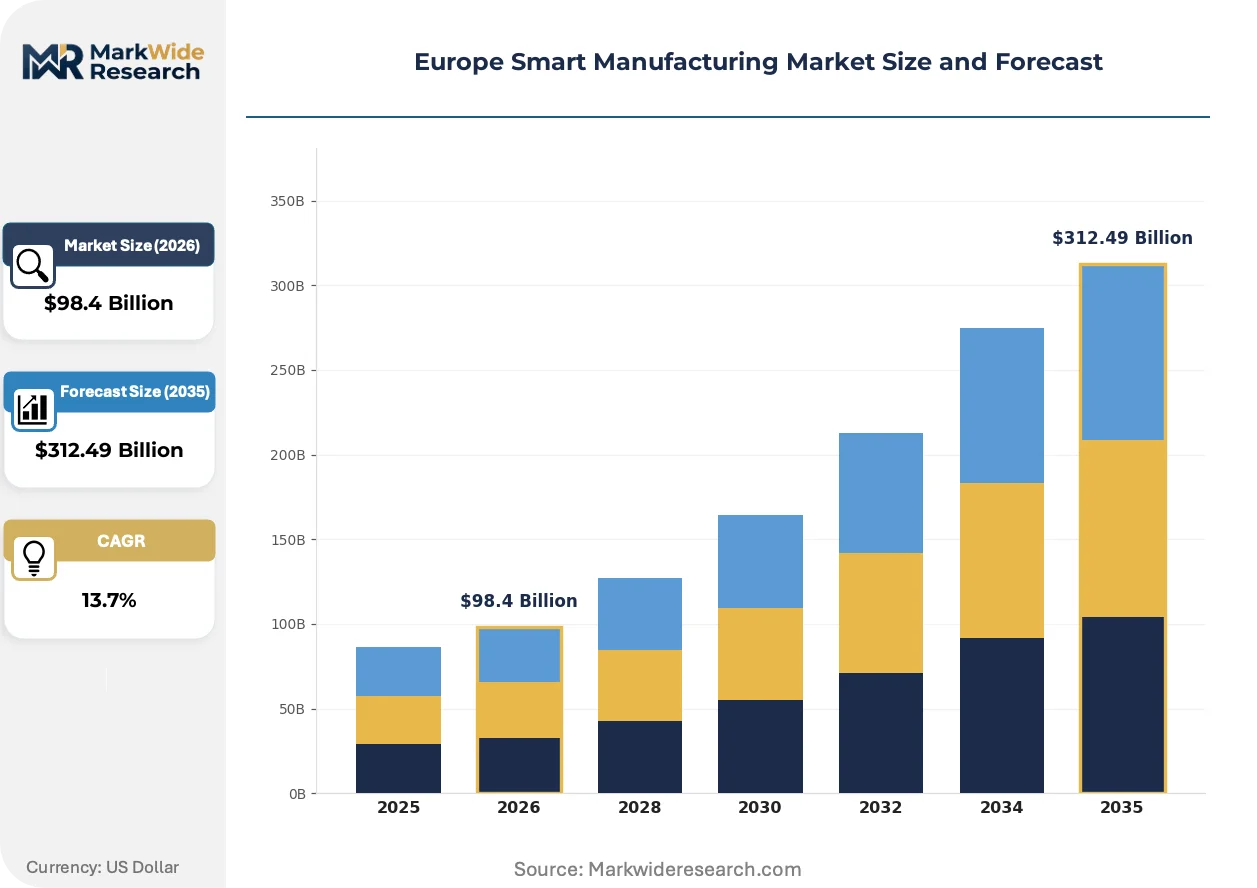
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $312.49 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, IoT Devices, Automation Software, Sensors Technology: Machine Learning, AI Solutions, Cloud Computing, Edge Computing End User: Aerospace, Electronics, Food Processing, Pharmaceuticals Application: Quality Control, Predictive Maintenance, Supply Chain Management, Inventory Optimization |
| Companies Covered | Siemens AG, ABB Ltd, Robert Bosch GmbH, Schneider Electric SE, Rockwell Automation Inc, Honeywell International Inc, Dassault Systemes SE, SAP SE, FANUC Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Manufacturing Market Shifts & Advancements
Digital thread architectures are collapsing the boundary between product design and shop-floor execution, enabling real-time reconfiguration of production sequences based on upstream demand signals rather than fixed batch scheduling.
Digital twin technology is hybridizing physics-based simulation with live operational data to create persistent virtual replicas of stamping presses and welding cells. German automotive Tier-1 suppliers deploy these twins for virtual commissioning, cutting physical prototype iterations by half. The technology is hybridizing traditional capex justification models toward subscription-based performance guarantees.
EU AI Act risk classification rules impose conformity obligations on manufacturing systems with embedded decision-making capabilities. High-risk applications in autonomous quality inspection now require documented training data governance and human oversight protocols. French pharmaceutical packaging lines face the steepest compliance burden, driving demand for explainable AI modules that trace classification logic.
Asset-light financing structures displace outright equipment ownership in capital-constrained Eastern European markets. Polish automotive suppliers increasingly contract for robotics capacity by the hour rather than purchasing hardware, shifting balance sheet risk to OEM-captive finance arms and specialized leasing consortia. This procurement evolution concentrates most visibly in battery module assembly operations where technology obsolescence cycles compress below five years.
Europe Smart Manufacturing Market Segmentation
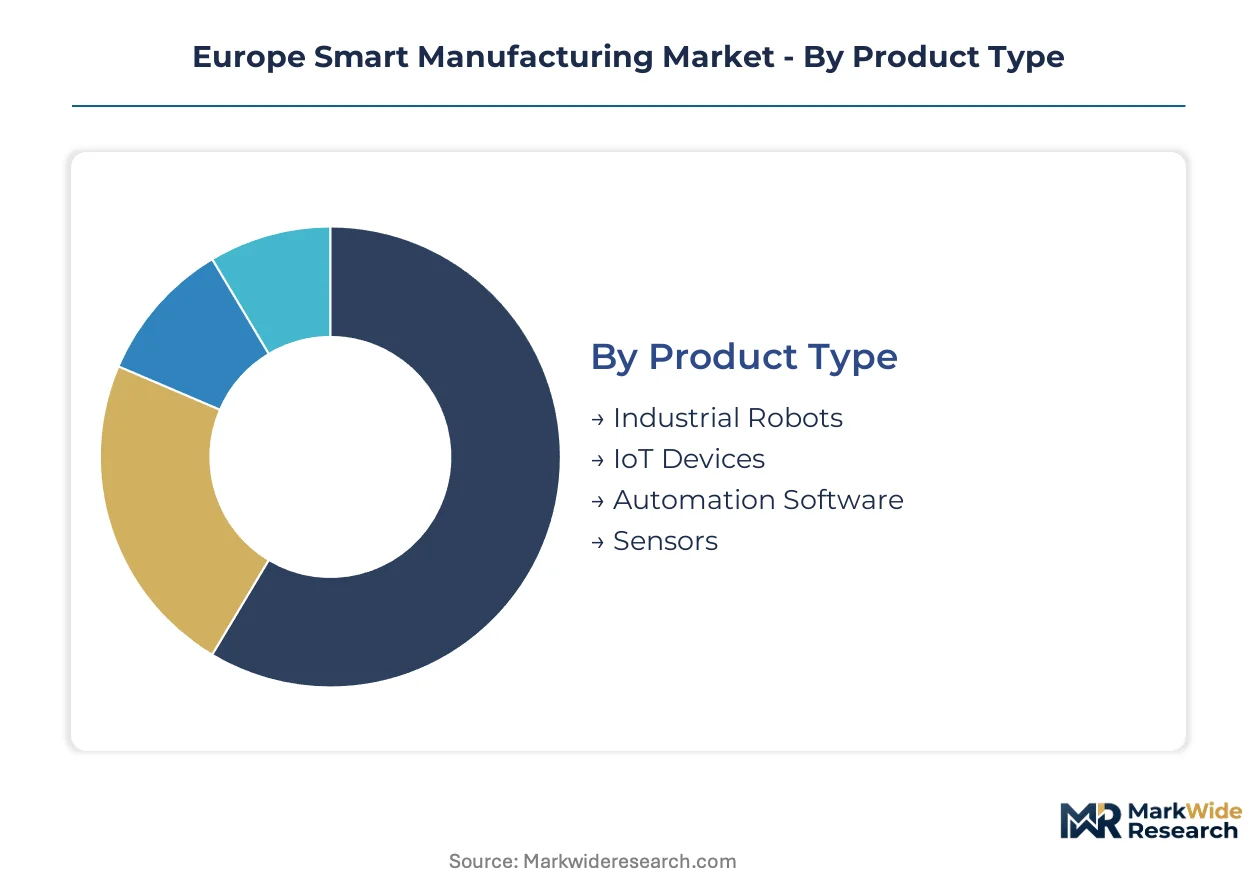
Segmentation in Europe Smart Manufacturing reveals how technology maturity, regulatory pressure, and capital intensity fragment procurement patterns across German automotive plants, French pharmaceutical lines, and Eastern European component suppliers. Understanding these divides exposes where margin pools concentrate and which integration paths face shortest sales cycles.
Product Type:
Mature hardware categories dominate installed base volumes while software layers capture expanding recurring revenue streams.
- Automation Software:Recurring licensing architectures and sticky enterprise integrations create the deepest margin pools in this segment. German automotive OEMs and French aerospace suppliers drive demand for MES platforms that embed carbon accounting under CSRD disclosure mandates.
- Industrial Robots:Articulated and collaborative systems handle physical manipulation tasks across welding, assembly, and material handling operations. Volume leadership persists but margin compression intensifies from Chinese supplier encroachment into sub-20kg payload segments serving Polish and Czech component manufacturers.
- IoT Devices:Connected sensors and gateways enable machine-to-machine communication across heterogeneous production environments.
- Sensors:Pressure, temperature, and vision systems feed real-time data into control loops for process optimization.
Automation Software handles the majority of recurring revenue capture; Edge-AI convergence is expanding most quickly on deployment timelines.
Technology:
Cost tier stratification separates capital-intensive infrastructure from pay-as-you-scale analytics layers.
- Edge Computing:Distributed processing nodes push inference workloads within 10 milliseconds of sensors, eliminating cloud dependency for real-time defect rejection. German semiconductor packaging lines and Italian precision machining facilities prioritize this architecture to meet EU AI Act latency requirements for high-risk autonomous quality systems.
- AI Solutions:Embedded decision-making modules for predictive maintenance and adaptive process control face steepest compliance burdens under EU AI Act risk classification rules. French pharmaceutical packaging lines mandate explainable AI modules that trace classification logic, extending vendor development cycles.
- Machine Learning:Time-series pattern recognition algorithms optimize equipment performance through historical operational data analysis.
- Cloud Computing:Centralized data lakes and computational resources support long-horizon analytics and cross-facility benchmarking.
Edge Computing handles the majority of new latency-sensitive deployments; AI Solutions is climbing the fastest on regulatory-driven upgrade cycles.
End User:
Application intensity varies by sector-specific traceability requirements and automation heritage.
- Automotive:Tier-1 suppliers across Germany's Ruhr corridor deploy digital twins for virtual commissioning of stamping presses and welding cells. ECHA substance restrictions under REACH compliance drive sensor upgrade cycles in pneumatic-heavy plants.
- Pharmaceuticals:French and Italian packaging lines face the steepest EU AI Act compliance burdens for autonomous quality inspection, requiring documented training data governance and human oversight protocols.
- Aerospace:Precision machining and assembly operations demand tight tolerance control and full component traceability.
- Electronics:Semiconductor and consumer device manufacturers prioritize throughput velocity and defect minimization.
- Food Processing:Hygienic design standards and batch consistency requirements shape equipment specifications.
Automotive handles the majority of installed automation base; Pharmaceuticals is gaining share fastest on regulatory compliance spending.
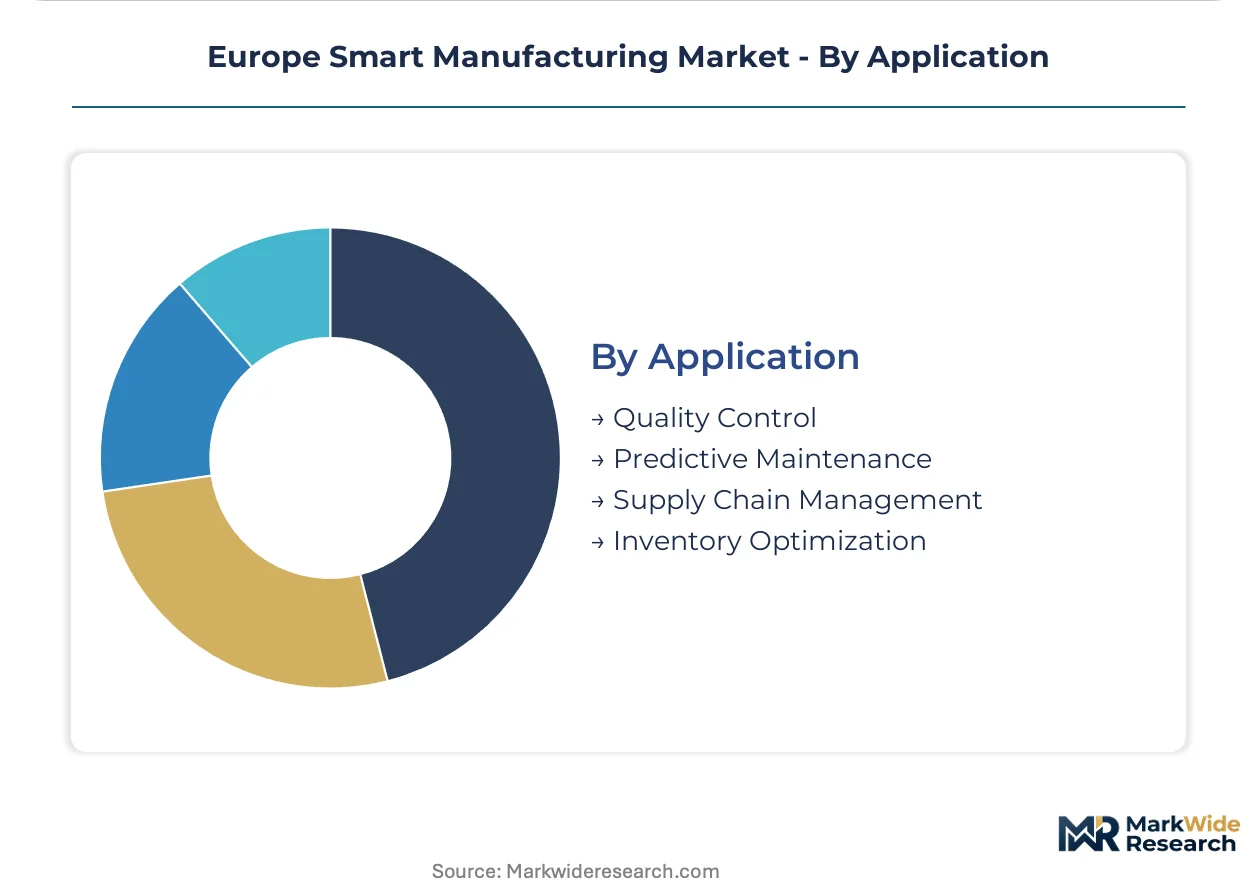
Application:
Customer type segmentation separates brownfield retrofit priorities from greenfield automation investments.
- Predictive Maintenance:Machine learning models analyze vibration, thermal, and current signatures to forecast equipment failures before production disruption. German toolmakers' retiring workforce creates diagnostic blind spots as tacit mechanical knowledge escapes institutional capture, forcing reliance on sensor-based anomaly detection.
- Quality Control:Vision systems and statistical process control enforce specification compliance across high-volume output. Edge-AI convergence enables sub-10-millisecond defect rejection without cloud dependency in semiconductor packaging lines.
- Supply Chain Management:Digital thread architectures synchronize upstream demand signals with flexible production capacity.
- Inventory Optimization:Real-time tracking and automated replenishment minimize working capital tied to raw materials and work-in-process.
Predictive Maintenance handles the majority of AI-enabled deployment value; Quality Control is expanding most quickly on vision-system cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's smart manufacturing sector generates substantial equipment exports to Asia-Pacific automotive markets while importing rare-earth magnet components and semiconductor-grade sensors from East Asian suppliers. This trade asymmetry shapes capital allocation priorities across German, French, and Eastern European production hubs.
Germany
Ruhr Valley automotive OEMs and Upper Silesian steel producers drive retrofit demand for energy-optimized control architectures under EU Green Deal carbon intensity targets. CE marking under the Machinery Directive governs AI-enabled safety system deployments. Stuttgart and Munich anchor precision tooling clusters where digital twin vendors cluster around Tier-1 supplier networks.
France
Pharmaceutical packaging lines in Île-de-France and precision machining facilities in Auvergne-Rhône-Alpes accelerate cobot deployment under the Industry 5.0 human-centric manufacturing mandate. ANSM and CNIL oversight intersects with EU AI Act risk classification rules for autonomous quality inspection. Lyon hosts specialist integrators serving aerospace component traceability requirements.
Italy
Emilia-Romagna and Lombardy machine builders pursue adaptive automation for legacy mechanical equipment, prioritizing collaborative robotics over full line replacement. REACH chemical compliance under ECHA jurisdiction drives sensor manufacturers toward solid-state alternatives. Bologna's packaging machinery district concentrates retrofit system integrators.
Poland
Automotive component suppliers across Silesia and Greater Poland remain below 15 percent automation penetration, creating demand for equipment-leasing structures and pay-per-output financing. EU structural funds channel capital toward brownfield modernization. Wrocław and Poznań attract German system integrators establishing nearshore service hubs.
United Kingdom
Midlands aerospace suppliers and Southeast pharmaceutical contract manufacturers deploy edge computing architectures to meet latency thresholds for real-time defect rejection. CSRD disclosure mandates alter capital allocation toward energy-management software integration. Cambridge and Bristol anchor AI-enabled vision system development clusters.
Europe Smart Manufacturing Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified industrial conglomerates with captive software stacks, specialized robotics-software integrators, and emerging pay-per-use equipment financiers. Siemens AG and ABB Ltd occupy the integrated platform tier. Schneider Electric SE and Rockwell Automation Inc anchor the automation-software convergence layer. Mid-tier Polish and Czech system integrators compete through asset-light project structures. Dominant competitive moves include portfolio diversification into energy-management convergence and strategic partnerships for edge-AI module development.
Within the integrated platform tier, Siemens AG and ABB Ltd exemplify the diversified industrial archetype combining hardware manufacturing with recurring software licensing. Schneider Electric SE occupies a position bridging energy management and production control convergence. These France-based and Germany-based entities anchor vendor selection criteria for large-scale automotive and steel retrofit programs across the Ruhr and Upper Silesian corridors.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Robert Bosch GmbH |
| Schneider Electric SE |
| Rockwell Automation Inc |
| Honeywell International Inc |
| Dassault Systemes SE |
| SAP SE |
| FANUC Corporation |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's congestion surcharges and modal switching costs concentrate pricing power among integrated logistics providers serving German automotive plants, while downstream price differentiation sharpens between CSRD-compliant energy-management bundles and commodity automation hardware.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure combining perpetual software licensing with subscription-based edge-computing capacity. Price differentiation stems from CE marking tier under the Machinery Directive and volume scale in multi-site deployments. Cost compression in collaborative robotics is intensifying because Chinese suppliers encroach on sub-20kg payload segments. Polish and Czech component manufacturers exhibit highest price sensitivity; German Tier-1 automotive suppliers demonstrate lowest sensitivity due to pay-per-output financing preferences.
Supply Chain Analysis
Permanent magnet feedstock draws from Chinese rare-earth processing facilities, Malaysian downstream separation plants, and Japanese magnet alloy production. Servo motor actuators, precision sensors, and semiconductor-grade vision processors constitute critical component dependencies. Single-source vulnerability concentrates in neodymium-dysprosium supply chains subject to export quota risk. Distribution runs through OEM-captive finance arms and specialized leasing consortia serving Eastern European brownfield retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where OPC-UA interoperability standards collapse proprietary fieldbus moats and concentrate value capture in software-layer vendors with sticky enterprise integrations.
For Market Incumbents: Entrench digital twin subscription architectures by embedding carbon accounting modules directly into MES platforms ahead of CSRD disclosure mandates. Deepen backward integration into edge-AI chip design to reduce dependency on Taiwanese semiconductor supply. Counter Chinese robotics encroachment through certified safety-system bundling that exploits CE marking timeline advantages.
For New Entrants and Emerging Players: Pursue asset-light equipment-leasing structures in Polish and Czech automotive component suppliers where automation penetration remains below fifteen percent. Target pharmaceutical packaging lines in France facing steepest EU AI Act compliance burdens for explainable AI modules. Lead with pay-per-output financing to bypass capital-constrained buyer balance sheets.
For Investors and Strategic Acquirers: Mid-tier system integrators with OT cybersecurity capabilities and zero-trust network architecture expertise command premium scarcity rents. Long-term viability hinges on software recurring revenue ratios exceeding hardware transactional exposure. Watch for F-Gas Regulation phase-down timelines as inflection triggers for thermal management system requalification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OPC-UA overlay deployment collapses proprietary fieldbus fragmentation in German automotive plants. |
| Backward Integration | In-house edge-AI chip design reduces latency exposure and Taiwanese semiconductor dependency. |
| Strategic Partnership | Collaboration with ECHA-compliant solid-state sensor vendors accelerates REACH-driven upgrade cycles. |
| Acquisition of Specialist Firm | OT cybersecurity boutiques with PLC programming expertise address skill scarcity constraining rollout velocity. |
| Geographic Expansion | Nearshore service hubs in Wrocław and Poznań capture Polish brownfield modernization demand. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interview insights combined with secondary validation against SEC filings, EU customs records, ECHA substance restriction databases, and industrial automation trade association reports. Bottom-up equipment shipment analysis triangulated with top-down capital expenditure tracking across automotive, pharmaceutical, and steel production facilities.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning technology layer, deployment latency threshold, end-use sector automation heritage, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle compression, and software attach ratio expansion. Industry-specific inputs included EU Green Deal carbon intensity target compliance timelines and Industry 5.0 policy implementation trajectories.
Sensitivities concentrate around rare-earth export quota disruptions, CE marking timeline extensions for AI-enabled safety systems, and intergenerational workforce transition impacts on predictive maintenance model training. Cross-checking against EPC contractor order books and German mechanical engineering association output indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
North America Automated Rotary Indexing Table Market