
 Industrial Computed Tomography Market | 2026-2036
Industrial Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Computed Tomography Market Intelligence
German precision metrology suppliers is realigning global distribution for high-resolution CT systems. Zeiss Industrial Quality Solutions leverages its Oberkochen manufacturing base to sustain calibration-certification workflows across European automotive OEMs. Nikon Metrology competes through electron-beam tomography specialization in semiconductor substrate inspection. Waygate Technologies anchors industrial service contracts through its embedded technician networks in North American aerospace clusters.
Industrial computed tomography employs X-ray or electron-beam sources to reconstruct three-dimensional volumetric datasets from two-dimensional projection images, achieving spatial resolutions below one micrometer for internal defect detection without destructive sectioning. The technique serves primary industrial purpose in dimensional metrology, porosity quantification, and assembly verification for safety-critical components. X-Ray Computed Tomography dominates installed base value due to decades of standardization in aerospace quality control, while Cone Beam Computed Tomography captures fastest expansion in electronics miniaturization where reduced source-to-detector geometry matches small-part throughput requirements. Hybrid Systems concentrate margin pools at the premium tier by combining 2D radiography with 3D reconstruction in single-platform configurations favored by automotive failure analysis laboratories.
FDA 21 CFR Part 11 electronic records requirements shape pharmaceutical and medical device manufacturer procurement criteria for traceable inspection data. ISO 10360 and VDI/VDE 2630 standards govern acceptance testing of CT-based coordinate measuring systems, creating compliance barriers for uncertified equipment entrants. EMA medical device regulation convergence with MDR technical documentation demands reinforces metrology investment in European manufacturing. Stakeholders must monitor divergence between national accreditation bodies over CT measurement uncertainty budgets as this determines cross-border equipment acceptance and service contract portability.
Market Dynamics
Calibration-certification workflows for CT-based coordinate measuring systems are tightening procurement criteria across automotive and aerospace supply chains, forcing OEMs to consolidate vendor relationships around metrology suppliers with embedded accreditation capabilities.
Growth Catalysts
- ISO 10360 acceptance testing mandates:European automotive OEMs now require certified CT systems for dimensional metrology, eliminating uncertified equipment from qualified supplier lists.
- Turbine blade inspection programs:German and US aerospace manufacturers are expanding non-destructive testing capacity for single-crystal superalloy components in next-generation propulsion systems.
- Electronics miniaturization:Cone Beam Computed Tomography matches reduced source-to-detector geometry to small-part throughput requirements in semiconductor substrate inspection.
Market Restraints
- X-ray source supply concentration:High-power microfocus tubes depend on a limited manufacturing base in Germany and Japan, creating lead time vulnerability for system integrators.
- EMA-MDR technical documentation convergence:European medical device manufacturers face duplicated validation requirements during the transition period, delaying CT metrology investments.
- Electron-beam tomography substitution:Semiconductor fabs below 7nm node geometries increasingly favor focused ion beam sectioning for sub-micron defect localization.
Strategic Opportunities
- Guangdong precision manufacturing corridor:Battery cell manufacturers in southern China lack qualified CT porosity analysis capacity for solid-state electrolyte validation.
- Hybrid system platform convergence:Automotive failure analysis laboratories seek single-platform configurations combining 2D radiography with 3D reconstruction to consolidate floor space.
- FDA 21 CFR Part 11 traceability mandates:Pharmaceutical packaging inspection creates demand for CT systems with embedded electronic records and audit trail functionality.
Industry Challenges
- VDI/VDE 2630 measurement uncertainty budgets:Divergence between national accreditation bodies over CT-specific error propagation methods complicates cross-border equipment acceptance.
- Multi-sensor integration complexity:Automotive metrology labs struggle to fuse CT volumetric data with tactile probe measurements in unified coordinate systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Computed Tomography Market |
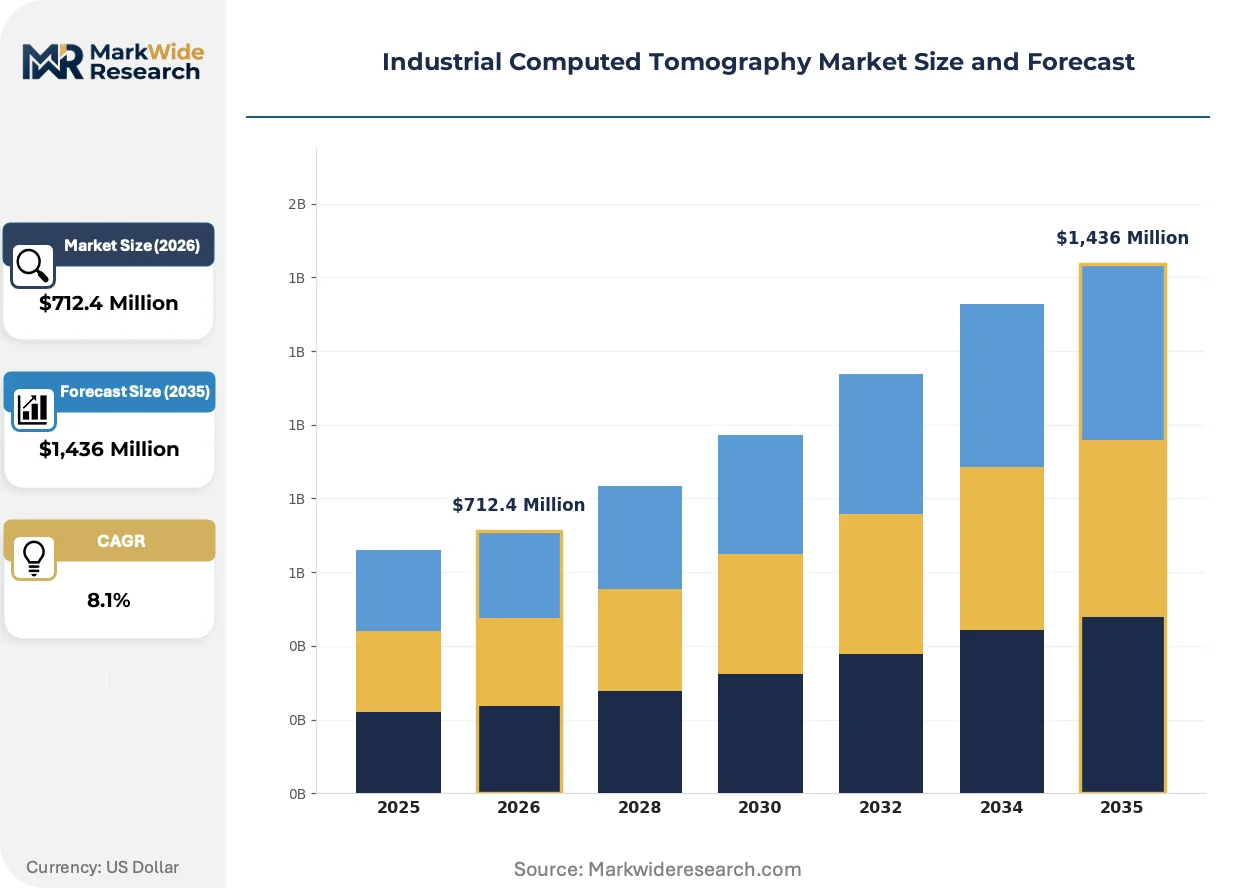
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,436 Million |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Imaging, 3D Imaging, Hybrid Systems, Portable Systems End User: Aerospace, Automotive OEMs, Electronics, Energy Sector Technology: X-Ray Computed Tomography, Electron Beam Tomography, Cone Beam Computed Tomography, Others Application: Quality Control, Failure Analysis, Material Inspection, Research & Development |
| Companies Covered | Yxlon International, Hexagon AB, Zeiss Industrial Quality Solutions, Thermo Fisher Scientific, Shimadzu Corporation, Nikon Metrology, North Star Imaging, Werth Messtechnik, Waygate Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Computed Tomography Market Strategic Shifts & Innovations
Resolution thresholds below one micrometer are compressing the boundary between industrial quality control and materials science research, repositioning CT systems as dual-use infrastructure spanning production floors and R&D laboratories.
Scattering-corrected reconstruction algorithms are overtaking conventional filtered back-projection in aerospace turbine blade inspection. Rolls-Royce and Pratt & Whitney suppliers adopt these methods to resolve casting porosity in nickel-based superalloys without beam-hardening artifacts. The technique is overtaking legacy software licenses in high-value metrology contracts where measurement uncertainty budgets determine component acceptance.
EMA medical device regulation convergence with MDR technical documentation demands reinforces metrology investment in European manufacturing. Manufacturers must demonstrate traceable inspection data for implantable devices, pushing CT system vendors to embed electronic signature workflows. German precision metrology suppliers capture this requirement through pre-validated software configurations that accelerate customer audit readiness.
After-sales service unbundling is fragmenting the vendor-customer relationship in North American aerospace clusters. Maintenance contracts, calibration services, and application training now procure separately through MRO intermediaries rather than bundled system sales. Michigan-based automotive suppliers lead this pattern, treating CT capability as utility infrastructure rather than capital asset ownership.
Industrial Computed Tomography Market Segmentation
Industrial CT procurement decisions hinge on resolution requirements, throughput constraints, and regulatory traceability mandates. Buyers segment investments across product architecture, target industry, radiation source technology, and intended application scope.
Product Type:
Capital allocation prioritizes dimensional accuracy certification and floor-space efficiency over raw acquisition speed.
- 3D Imaging:Volumetric reconstruction platforms dominate aerospace turbine blade inspection workflows. German and US propulsion system suppliers require sub-micron spatial resolution for single-crystal superalloy porosity mapping, locking in multi-year service contracts with embedded calibration technicians.
- Hybrid Systems:Single-platform configurations merge 2D radiography with 3D reconstruction. Automotive failure analysis laboratories in Michigan and Bavaria favor these units to consolidate equipment footprints while maintaining ISO 10360 compliance for dimensional metrology.
- 2D Imaging:Conventional projection radiography retains installed base in high-throughput electronics screening where volumetric data is unnecessary.
- Portable Systems:Field-deployable units serve energy sector pipeline inspection and in-situ aerospace MRO applications.
3D Imaging leads on scale; Hybrid Systems lead on momentum.
End User:
Industry-specific regulatory pressures determine procurement timing and vendor selection criteria.
- Aerospace:Non-destructive testing programs for next-generation propulsion systems drive demand in Germany and the United States. Pratt & Whitney and Rolls-Royce suppliers adopt scattering-corrected reconstruction algorithms to resolve casting defects without beam-hardening artifacts.
- Electronics:Semiconductor substrate inspection below 7nm node geometries increasingly substitutes electron-beam tomography for focused ion beam sectioning in Taiwan and South Korea.
- Automotive OEMs:European manufacturers require certified CT systems for dimensional metrology under ISO 10360, eliminating uncertified equipment from qualified supplier lists.
- Energy Sector:Battery cell manufacturers in Guangdong Province lack qualified porosity analysis capacity for solid-state electrolyte validation.
Aerospace leads on scale; Electronics leads on momentum.
Technology:
Radiation source selection trades spatial resolution against throughput and sample damage thresholds.
- X-Ray Computed Tomography:Decades of standardization in aerospace quality control anchor installed base value. High-power microfocus tube supply concentrates in Germany and Japan, creating lead time vulnerability for system integrators.
- Cone Beam Computed Tomography:Reduced source-to-detector geometry matches small-part throughput requirements in semiconductor substrate inspection. Electronics miniaturization corridors in Guangdong and Taiwan favor these configurations for miniaturized component validation.
- Electron Beam Tomography:Specialized for sub-micron defect localization in advanced packaging applications.
- Others:Emerging neutron and terahertz modalities serve hydrogen storage and composite delamination inspection niches.
X-Ray Computed Tomography leads on scale; Cone Beam Computed Tomography leads on momentum.
Application:
Workflow integration depth determines software licensing and service contract structures.
- Quality Control:Production-floor CT systems require embedded electronic records and audit trail functionality for FDA 21 CFR Part 11 compliance. Pharmaceutical packaging inspection creates demand for traceable inspection data in US and European manufacturing.
- Failure Analysis:Automotive laboratories seek unified coordinate systems fusing CT volumetric data with tactile probe measurements. VDI/VDE 2630 measurement uncertainty budgets complicate cross-border equipment acceptance.
- Material Inspection:Porosity quantification in additive manufacturing and casting applications.
- Research & Development:Dual-use infrastructure spanning production floors and materials science laboratories, with resolution thresholds below one micrometer compressing boundaries between industrial and academic use cases.
Quality Control leads on scale; Failure Analysis leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates metrology certification infrastructure while the United States dominates aerospace non-destructive testing deployment. Both markets face tightening ISO 10360 compliance timelines. China's Guangdong corridor represents the fastest-expanding demand node for battery inspection systems.
United States
Pratt & Whitney and GE Aerospace suppliers drive turbine blade inspection capacity expansion across Connecticut and Ohio manufacturing clusters. FDA 21 CFR Part 11 traceability mandates shape pharmaceutical packaging procurement in New Jersey and North Carolina. Michigan automotive laboratories treat CT capability as utility infrastructure through unbundled service contracts.
Germany
Zeiss and Werth Messtechnik anchor calibration-certification workflows for European automotive OEMs from Oberkochen and Giessen facilities. VDI/VDE 2630 measurement uncertainty standards govern acceptance testing protocols. Bavarian precision manufacturing corridors concentrate metrology R&D investment alongside aerospace supplier networks.
China
Battery cell manufacturers in Guangdong Province lack qualified porosity analysis capacity for solid-state electrolyte validation. GB standards and MIIT industrial quality directives accelerate domestic CT system adoption. Shenzhen and Dongguan electronics clusters deploy cone beam configurations for semiconductor substrate inspection.
Japan
Shimadzu Corporation anchors high-power microfocus tube manufacturing for global system integrators. METI industrial technology roadmaps prioritize non-destructive testing advancement. Nagoya aerospace suppliers and Kyushu semiconductor fabs concentrate precision inspection demand.
South Korea
Samsung and SK Hynix suppliers below 7nm node geometries favor electron-beam modalities for sub-micron defect localization. MFDS medical device traceability requirements align with MDR convergence timelines. Seoul Capital Area and Busan-Ulsan corridors concentrate advanced packaging inspection investment.
Industrial Computed Tomography Market Key Industry Players
German producers anchor the premium calibration-certification tier; Japanese specialists hold critical supply positions in high-power X-ray sources. The vendor structure concentrates around metrology suppliers with embedded accreditation capabilities and system integrators with regional service networks. Two strategic archetypes dominate: vertically integrated precision metrology houses and electron-beam technology specialists. Competitive moves center on unbundling after-sales service contracts and pre-validated software configurations for regulatory acceleration.
Within the integrated metrology tier, Zeiss Industrial Quality Solutions and Hexagon AB represent archetypes of calibration-certification workflow dominance. Nikon Metrology occupies a position among electron-beam specialization providers. Waygate Technologies exemplifies the service-network anchored model in North American aerospace clusters. These three named entities illustrate the geographic and technological segmentation governing vendor selection criteria.
| Leading Market Players |
|---|
| Yxlon International |
| Hexagon AB |
| Zeiss Industrial Quality Solutions |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Nikon Metrology |
| North Star Imaging |
| Werth Messtechnik |
| Waygate Technologies |
| Others |
Cost & Logistics Intelligence
Calibration-technician concentration in Bavaria and Baden-Württemberg compresses labor-cost differentials between premium-certified and standard-tier CT systems, widening pricing spreads as OEMs absorb embedded accreditation premiums for ISO 10360 compliance workflows.
Pricing Analysis
Capacity additions in Guangdong are reshaping price floors for cone-beam configurations serving electronics miniaturization corridors. Three-tier pricing structure across premium, standard, and economy levels separates embedded calibration-certification workflows from basic volumetric reconstruction packages. Price differentiation rests on ISO 10360 certification grade and after-sales service bundling intensity. Cost compression in economy-tier portable systems is intensifying because battery cell manufacturers prioritize throughput over metrology-grade uncertainty budgets. Automotive OEMs in Michigan exhibit highest price sensitivity; aerospace propulsion suppliers in Connecticut and Ohio demonstrate lowest sensitivity due to failure-analysis liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with high-power microfocus tube manufacturing concentrated in Germany and Japan. Raw material and component dependencies encompass tungsten-rhenium filament assemblies, ceramic-metal feedthroughs, and precision-machined vacuum housings. Supply chain risk centers on tariff exposure for Japanese-sourced electron-beam column subassemblies entering European assembly facilities. Distribution runs through embedded technician networks in North American aerospace clusters and direct OEM relationships for European automotive metrology labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial computed tomography functions as a stable compounder anchored by irreversible regulatory mandates for traceable inspection data across safety-critical manufacturing.
For Market Incumbents: Hedge against electron-beam substitution in sub-7nm semiconductor inspection by deepening calibration-certification moats in aerospace turbine blade workflows. Prioritize backward integration into high-power microfocus tube supply through captive sourcing agreements with Shimadzu manufacturing nodes. Lock in multi-year service contracts with embedded technician deployment to offset unbundling pressure from MRO intermediaries in Michigan automotive clusters. For New Entrants and Emerging Players: Scattering-corrected reconstruction algorithms offer a technology-first wedge into Rolls-Royce and Pratt & Whitney supplier networks seeking beam-hardening artifact elimination. Target Guangdong battery cell manufacturers lacking qualified porosity analysis capacity for solid-state electrolyte validation. Pursue regulatory-fast-track positioning through pre-validated FDA 21 CFR Part 11 software configurations that compress pharmaceutical customer audit timelines. For Investors and Strategic Acquirers: Precision metrology houses with embedded accreditation capabilities are the most active acquirer in this space, consolidating regional service networks to defend margin pools. Five-to-ten-year viability hinges on ISO 10360 certification workflow ownership rather than hardware manufacturing scale. Monitor divergence between national accreditation bodies over VDI/VDE 2630 measurement uncertainty budgets as inflection indicator for cross-border equipment acceptance portability.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-Certification Workflow Integration | Zeiss and Werth Messtechnik embed ISO 10360 compliance to accelerate European automotive OEM qualification timelines. |
| Scattering-Corrected Reconstruction Licensing | Rolls-Royce suppliers adopt algorithmic upgrades to resolve nickel-based superalloy porosity without beam-hardening artifacts. |
| After-Sales Service Unbundling | Michigan automotive laboratories procure CT capability as utility infrastructure through separate MRO maintenance contracts. |
| Electron-Beam Technology Specialization | Nikon Metrology targets semiconductor substrate inspection below 7nm node geometries with focused ion beam substitution resistance. |
| Guangdong Service Network Expansion | Waygate Technologies anchors battery cell porosity analysis capacity for solid-state electrolyte validation in southern China. |
Research Approach
Bottom-up aerospace and automotive OEM modeling reconciled against top-down X-ray source manufacturing tracking forms the analytical core. Primary interviews with metrology lab directors, OEM procurement teams, aftermarket service heads, and calibration technicians combined with secondary validation from FDA 510(k) filings, EMA medical device submissions, ISO 10360 accreditation registries, and customs trade data for high-power microfocus tube shipments. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map radiation source technology selection, resolution tier, and regulatory certification requirements against end-use industry adoption curves across the analysis window. Segmentation dimensions encompass product architecture, target industry, radiation source technology, and application scope. CAGRs derive from fitted adoption curves calibrated to ISO 10360 mandate implementation timelines and FDA 21 CFR Part 11 enforcement patterns. Forecast inputs include turbine blade inspection program expansion rates and semiconductor node geometry progression thresholds.
The model holds under stable regulatory convergence between EMA-MDR technical documentation demands; deviation in national accreditation body divergence over CT measurement uncertainty budgets would shift equipment acceptance portability assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision Camera Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Side View Camera System Market
Imaging
EUV Mask Inspection System Market
Imaging
Video Capture Card Market
Imaging
SWIR Camera Market
Imaging
Hyper Spectral Imaging System Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Photoacoustic Microscope Market
Imaging
Widefield Imaging Systems Market
Imaging
Europe IP Camera Market
Imaging
Low-Light Imaging Market
Imaging
Global Image Sensors Market
Imaging
Smart Camera Market
Imaging
Camera Stabilizer Market