
 Printed Electronics Devices Market | 2026-2036
Printed Electronics Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Electronics Devices Market Analytics
Multi-source procurement for conductive inks and flexible substrates is shifting toward captive supply arrangements as OEMs seek batch consistency for high-yield roll-to-roll lines. DuPont leverages its fluoropolymer and silver nanowire portfolio to anchor premium substrate supply contracts with display manufacturers in East Asia. BASF competes through its specialty chemicals division, which sustains R&D intensity in particle-free conductive formulations for inkjet deposition. Samsung Electronics dominates the integrated display segment, where its vertical control over OLED and printed-electronics pilot lines extends manufacturing scale advantages.
Printed electronics devices comprise functional electronic components manufactured through additive deposition of conductive, semiconductive, and dielectric materials onto flexible or rigid substrates, typically achieving layer thicknesses below five micrometers and operating voltages under twenty volts for low-power applications. Their primary purpose is to enable lightweight, conformable, or large-area electronic functionality at unit costs incompatible with silicon wafer processing. Displays and sensors lead current revenue contribution, with RFID and antenna segments expanding fastest as retail logistics and automotive telematics multiply tag and transceiver deployments. Inkjet printing captures margin concentration in prototype and short-run production, while roll-to-roll processing anchors volume economics for antenna and display backplane manufacturing.
FDA scrutiny of biocompatibility for wearable medical patches shapes material selection in the healthcare end-use segment, while REACH and RoHS compliance in Europe restricts certain solvent-based inks and heavy-metal conductors. The EU AI Act and emerging MDR requirements for connected diagnostic devices are tightening traceability standards across printed sensor supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode the cost advantage additive manufacturing promises over conventional electronics fabrication.
Market Dynamics
Automotive OEMs are consolidating printed sensor procurement around captive ink formulation and roll-to-roll coating capabilities to secure batch consistency for battery thermal management and in-cabin monitoring systems.
Growth Catalysts
- EU Green Deal substance restrictions:Hazardous material limits in electronics manufacturing accelerate substitution toward water-based conductive inks and biodegradable substrates across European supply chains.
- Automotive telematics expansion:Connected vehicle mandates and battery safety regulations multiply deployments of printed temperature and pressure sensor arrays in electric powertrains.
- Inkjet deposition advances:Particle-free conductive formulations enable finer feature resolution for medical wearable electrodes, opening FDA-regulated healthcare segments to additive manufacturing.
Market Restraints
- Silver nanowire supply concentration:Premium substrate feedstock depends on a limited supplier base in East Asia, exposing buyers to price volatility and allocation risk.
- REACH solvent restrictions:European chemical regulations eliminate certain high-performance solvent-based inks, forcing reformulation cycles that compress R&D bandwidth.
- Silicon wafer cost curve:Mature semiconductor fabrication maintains unit cost advantages for rigid, high-density applications, constraining printed electronics to conformable or large-area niches.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Production-linked incentives for domestic component fabrication attract printed antenna and RFID tag assembly capacity to serve retail logistics growth.
- EU AI Act traceability mandates:Connected diagnostic device regulations create demand for printed sensor supply chain documentation systems and embedded authentication features.
- Flexible-display backplane convergence:Integration of printed thin-film transistors with OLED stacks enables new form factors for foldable devices and automotive interior surfaces.
Industry Challenges
- Roll-to-roll yield engineering:High-volume antenna and display manufacturing requires specialized process control expertise that remains scarce in contract manufacturing channels.
- MDR biocompatibility certification timelines:Wearable medical patch developers face extended validation cycles for skin-contact materials under European medical device regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Electronics Devices Market |
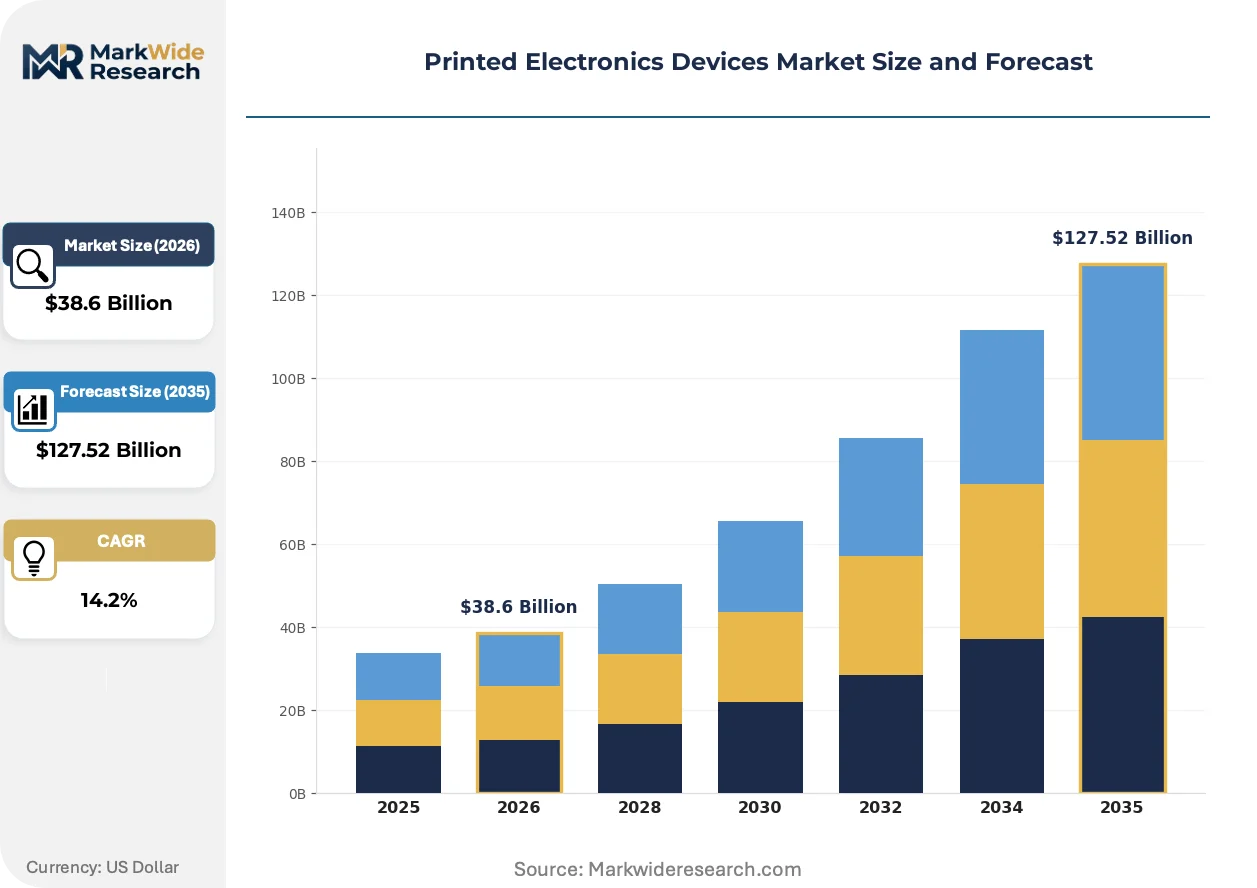
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Displays, Antennas, Radio Frequency Identification (RFID) Technology: Inkjet Printing, Screen Printing, Gravure Printing, Roll-to-Roll Processing End User: Consumer Electronics, Automotive, Healthcare, Aerospace Material: Conductive Ink, Dielectric Materials, Substrates, Adhesives |
| Companies Covered | DuPont, BASF, Agfa-Gevaert Group, Henkel AG & Co. KGaA, NovaCentrix, E Ink Holdings, Panasonic Corporation, Samsung Electronics, LG Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Electronics Devices Market Evolving Landscape
Material science breakthroughs and regulatory pressure on hazardous substances are compressing development cycles for water-based conductive formulations while expanding addressable applications in regulated end-uses.
Silver nanowire transparent conductors are absorbing market share from indium tin oxide in flexible touch sensors and display electrodes. Automotive tier-1 suppliers in Germany and display manufacturers in South Korea are qualifying these materials for production volumes. The technology is absorbing capital that previously supported vacuum-deposited alternatives, reshaping equipment investment patterns across substrate coating facilities.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of legacy solvent-based dielectric inks in European manufacturing. Industrial consequence includes accelerated partnerships between chemical suppliers and contract printers to validate water-based alternatives without sacrificing adhesion or cure speed. Medical wearable and food-contact sensor segments face the tightest compliance timelines, with some buyers dual-sourcing European and Asian supply to manage transition risk.
Captive ink formulation is displacing merchant supply relationships among large automotive and display OEMs. Batch consistency requirements for high-yield roll-to-roll lines drive backward integration into conductive paste production, particularly in Germany and Japan. This pattern concentrates most visibly in battery thermal management sensor arrays, where OEMs cite traceability and reformulation speed as procurement priorities over unit cost.
Printed Electronics Devices Market Segmentation
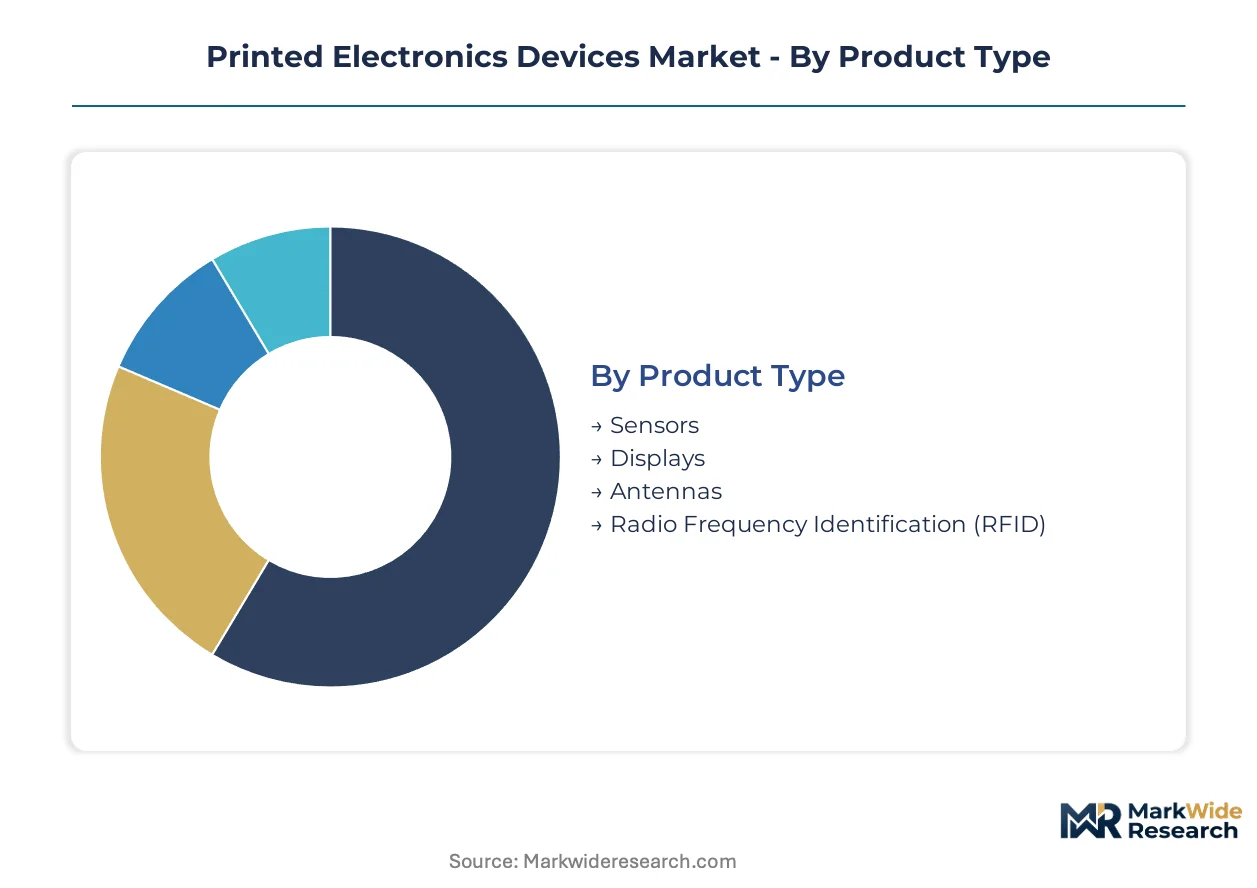
Printed electronics devices fragment across four structural dimensions that determine integration depth, manufacturing economics, and regulatory exposure. Each segmentation axis reveals distinct competitive dynamics between standalone component suppliers and embedded system integrators.
Product Type:
Integration depth varies sharply: sensors and RFID embed directly into host systems, while displays and antennas often function as standalone modules.
- Sensors:Arrays of printed temperature, pressure, and capacitive elements achieve layer thicknesses below five micrometers for conformable deployment. Automotive OEMs in Germany are consolidating procurement around captive ink formulation to secure batch consistency for battery thermal management and in-cabin monitoring systems.
- Displays:Flexible OLED backplanes and electrochromic indicators rely on printed thin-film transistor arrays for low-voltage operation. Samsung Electronics anchors premium supply contracts through vertical control over pilot lines in South Korea, extending manufacturing scale advantages for foldable device form factors.
- Antennas:Printed conductive traces on flexible substrates enable wideband RF performance for automotive telematics and retail logistics tags.
- Radio Frequency Identification (RFID):Passive and semi-active tags integrate printed antenna coils with silicon or printed logic for inventory tracking and authentication applications.
Sensors lead volumes today; RFID is gaining share fastest.
Technology:
Cost tier stratification separates prototype-scale deposition from high-volume continuous processing.
- Inkjet Printing:Piezoelectric and thermal drop-on-demand systems deposit particle-free conductive formulations with feature resolution below twenty micrometers. FDA-regulated healthcare segments in the US drive qualification for medical wearable electrodes where biocompatibility scrutiny shapes material selection.
- Roll-to-Roll Processing:Continuous coating and patterning of flexible webs achieves unit economics incompatible with sheet-fed alternatives. Display manufacturers in South Korea and automotive tier-1 suppliers in Germany anchor demand for high-yield antenna and backplane manufacturing lines.
- Screen Printing:Mesh-based stencil deposition suits thick-film conductive pastes and dielectric layers for robust outdoor applications.
- Gravure Printing:Engraved cylinder transfer delivers precise ink metering for long-run decorative and functional electronics.
Roll-to-Roll Processing dominates volume economics; Inkjet Printing captures margin concentration in short-run and regulated segments.
End User:
Application maturity determines whether printed electronics displace silicon or occupy uncontested conformable niches.
- Automotive:Printed sensor arrays monitor battery thermal states and passenger presence under EU battery safety regulations and connected vehicle mandates. OEMs cite traceability and reformulation speed as procurement priorities over unit cost for these safety-critical applications.
- Healthcare:Wearable patches and diagnostic electrodes face extended validation cycles under European MDR biocompatibility requirements and FDA scrutiny for skin-contact materials. REACH solvent restrictions force accelerated partnerships to validate water-based conductive alternatives.
- Consumer Electronics:Flexible displays and touch sensors absorb silver nanowire transparent conductors as indium tin oxide alternatives.
- Aerospace:Lightweight conformable antennas and structural health monitoring systems exploit printed electronics' mass advantage over conventional cabling.
Automotive leads current revenue contribution; Healthcare is expanding most quickly under regulatory tailwinds for connected diagnostic devices.
Material:
Supply concentration and regulatory compliance burden vary across the material stack.
- Conductive Ink:Silver flake, nanowire, and particle-free formulations enable conductivity ranging from ten to ten thousand siemens per centimeter. EU Green Deal substance restrictions accelerate substitution toward water-based systems, compressing development cycles for European chemical suppliers.
- Substrates:Polyethylene naphthalate, polyimide, and emerging biodegradable films determine mechanical flexibility and thermal stability. DuPont leverages fluoropolymer expertise to anchor premium supply contracts with display manufacturers in East Asia.
- Dielectric Materials:UV-curable and thermally cured insulators separate conductive layers in multilayer stacks.
- Adhesives:Pressure-sensitive and structural bonding layers attach printed components to host surfaces or encapsulate against environmental exposure.
Conductive Ink commands the steepest R&D investment intensity; Substrates face the tightest supply concentration risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting printed electronics investment toward jurisdictions with lower compliance costs for hazardous substance handling, while established clusters defend positions through captive ink formulation capabilities.
Germany
Automotive OEMs in Bavaria and Saxony are consolidating printed sensor procurement for battery thermal management systems under EU battery safety regulations. REACH solvent restrictions are accelerating partnerships between chemical suppliers and contract printers around Dresden. The Munich-Dresden corridor anchors applied research institutes and tier-1 supplier clusters qualifying water-based conductive formulations.
United States
FDA scrutiny of biocompatibility for wearable medical patches is concentrating demand in FDA-regulated healthcare segments. The EPA maintains oversight of volatile organic compound emissions from solvent-based ink production. Greater Boston and Silicon Valley host medical device startups and display technology ventures advancing particle-free conductive formulations for diagnostic electrodes.
South Korea
Display manufacturers are qualifying silver nanowire transparent conductors for flexible OLED backplanes under national dual carbon goals. The Seoul Capital Area anchors vertical integration from pilot lines through volume manufacturing. Samsung Electronics extends manufacturing scale advantages through control over printed-electronics pilot lines for foldable device form factors.
China
Domestic production of conductive inks and flexible substrates is expanding under MIIT industrial upgrading directives. The Yangtze River Delta and Pearl River Delta concentrate roll-to-roll coating capacity for antenna and RFID tag manufacturing. NMPA regulatory pathways for medical wearables are tightening traceability requirements for skin-contact printed sensors.
India
The PLI scheme for electronics manufacturing is attracting printed antenna and RFID tag assembly capacity to serve retail logistics growth. BIS standards for electronic components are shaping local content requirements for government procurement. Karnataka and Tamil Nadu are emerging as contract manufacturing hubs for conformable sensor arrays.
Printed Electronics Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulations and regional supply contracts. The market structures around three tiers: integrated chemical-materials conglomerates with captive R&D, display-centric electronics manufacturers with vertical pilot line control, and niche formulation specialists serving regulated healthcare segments. Consolidation pressure concentrates in conductive ink supply, while substrate and equipment channels retain fragmentation. Dominant competitive moves include backward integration into ink formulation and strategic partnerships for roll-to-roll yield engineering.
Among diversified chemical conglomerates, DuPont and BASF exemplify the materials-science archetype, anchoring premium substrate and specialty formulation supply relationships. Samsung Electronics occupies a distinct position as an integrated display manufacturer with vertical control over OLED and printed-electronics pilot lines. These three entities represent contrasting competitive vectors: chemical-materials depth, electronics manufacturing scale, and end-use application integration.
| Leading Market Players |
|---|
| DuPont |
| BASF |
| Agfa-Gevaert Group |
| Henkel AG & Co. KGaA |
| NovaCentrix |
| E Ink Holdings |
| Panasonic Corporation |
| Samsung Electronics |
| LG Display |
| Others |
Value Network & Pricing Analysis
EU Green Deal substance restrictions gate qualified supply for automotive and medical segments, concentrating premium-tier pricing access among chemical suppliers with validated water-based conductive formulations and biodegradable substrate portfolios. Buyers lacking REACH-compliant ink qualification face reformulation costs that erode the cost advantage additive manufacturing promises over conventional silicon fabrication.
Pricing Analysis
Silver nanowire and fluoropolymer substrate costs pass through directly to display manufacturers and automotive tier-1 suppliers, with pricing stratifying across premium, standard, and economy tiers based on ink biocompatibility certification grade and roll-to-roll yield performance. FDA and MDR compliance tiers command substantial premiums over industrial-grade alternatives. Price differentiation reflects batch consistency guarantees and captive formulation capabilities. Automotive OEMs show lowest price sensitivity for battery thermal management sensors where traceability outweighs unit cost; retail logistics RFID tag buyers exhibit highest sensitivity, driving commodity spot dynamics for high-volume antenna contracts.
Supply Chain Analysis
Dual-sourcing requirements from automotive and medical device OEMs mandate multi-supplier qualification for conductive inks across Germany, South Korea, and Japan to mitigate silver nanowire feedstock concentration in East Asia. Raw material dependencies center on silver flake, polyethylene naphthalate substrates, and UV-curable dielectric resins. Single-source vulnerability in premium fluoropolymer supply exposes buyers to allocation risk during capacity constraints. Distribution runs through direct long-term offtake agreements with chemical conglomerates rather than merchant distributors, concentrating procurement leverage among large-volume buyers with captive ink formulation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where production-linked incentive schemes in India attract antenna and RFID assembly capacity at compliance costs substantially below REACH-regulated European manufacturing.
For Market Incumbents: Deploy captive ink formulation capabilities to defend margin position against emerging particle-free conductive specialists. BASF and DuPont should accelerate water-based formulation partnerships with Dresden-area contract printers to preempt reformulation cycles forced by EU solvent restrictions. Backward integration into silver nanowire purification reduces exposure to East Asian supply concentration. For New Entrants and Emerging Players: Inkjet deposition advances for medical wearable electrodes offer the most penetrable entry vector, with FDA-regulated healthcare segments demanding finer feature resolution that particle-free formulations uniquely address. Target Greater Boston and Silicon Valley medical device startups seeking biocompatible skin-contact materials. Pursue platform licensing arrangements with diagnostic electrode developers rather than direct manufacturing scale-up. For Investors and Strategic Acquirers: Roll-up economics work for niche formulation specialists because REACH compliance timelines compress independent R&D bandwidth below viable scale. Long-term viability favors targets with validated water-based conductive portfolios and existing automotive tier-1 supplier relationships. Watch silver nanowire spot price volatility as the inflection indicator for vertical integration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ink Formulation Investment | Automotive OEMs in Bavaria secure batch consistency for battery thermal management sensor arrays under EU battery safety regulations. |
| Water-Based Conductive Formulation Partnership | Chemical suppliers near Dresden validate REACH-compliant alternatives without sacrificing adhesion or cure speed for medical wearables. |
| Silver Nanowire Supply Integration | Display manufacturers in South Korea reduce allocation risk from East Asian feedstock concentration for flexible OLED backplanes. |
| Roll-to-Roll Yield Engineering Acquisition | Contract manufacturers absorb scarce process control expertise for high-volume antenna and display backplane production lines. |
| India PLI Scheme Manufacturing Footprint | Printed antenna and RFID tag assemblers capture retail logistics demand at compliance costs below European REACH restrictions. |
Research Methodology
Direct dialogue with automotive tier-1 procurement directors, medical device regulatory affairs leads, chemical supplier R&D heads, and contract printer operations managers grounded qualitative assessments in operational reality. Secondary validation drew from ECHA REACH authorization databases, FDA 510(k) filings for wearable electrodes, MIIT industrial upgrading directives, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation outputs across product type, deposition technology, end-use vertical, and material chemistry fed into analytical frameworks modeling adoption curves and price elasticity. CAGRs derived from regression against historical capacity buildouts and regulatory mandate implementation schedules. Industry-specific forecast inputs included automotive electric powertrain penetration assumptions and MDR biocompatibility certification timeline distributions for skin-contact sensors.
The model holds under stable regulatory enforcement intensity and silver price corridors; deviation in EU Green Deal substance restriction timelines or East Asian export control activation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
High Current Springs Market