
 Photoacoustic Microscope Market | 2026-2036
Photoacoustic Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Photoacoustic Microscope Market Analytics
The capital-intensity divergence between integrated laser manufacturers and assembly-focused OEMs is rotating competitive advantage toward firms with captive photonics supply chains. FUJIFILM VisualSonics leverages its vertically integrated ultrasound platform to dominate preclinical imaging workflows. iThera Medical anchors its position through specialized clinical applications in dermatology and rheumatology. TomoWave Laboratories competes on modular system architectures that reduce customer switching costs.
A photoacoustic microscope generates acoustic waves through pulsed laser absorption in biological or material samples, detecting the resulting pressure transients with ultrasonic transducers to reconstruct high-resolution optical-absorption maps at depths exceeding pure optical microscopy. Benchtop systems currently lead installed base across research laboratories, while portable systems represent the fastest-growing product category as point-of-care oncology screening expands. Multi-modal technology configurations command premium positioning by combining photoacoustic detection with conventional ultrasound or optical coherence tomography, concentrating margin pools in integrated platforms rather than standalone hardware.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and commercialization pathways for photoacoustic diagnostic devices. ISO 13485 quality management standards govern manufacturing processes for systems deployed in clinical settings, while REACH compliance constrains laser dye and contrast agent formulations in European markets. Stakeholders must monitor evolving reimbursement codes for photoacoustic procedures in key healthcare systems and align R&D portfolios with regulatory precedents that determine time-to-market for new clinical indications.
Market Dynamics
The photoacoustic microscope market pivots on FDA 510(k) clearance velocity, which compresses time-to-market for clinical-grade systems while elevating compliance costs for preclinical-only vendors seeking hospital procurement channels.
Growth Catalysts
- METI infrastructure grants:Japan's Ministry of Economy, Trade and Industry funds university hospital installations, accelerating domestic adoption curves for dermatology workflows.
- Multi-modal platform integration:Hybrid photoacoustic-ultrasound configurations expand reimbursable procedure codes in oncology screening protocols.
- Early-stage melanoma detection protocols:German university hospitals expand procurement specifications to include photoacoustic systems in dermatology department capital budgets.
Market Restraints
- Tunable laser cost volatility:Nd:YAG and optical parametric oscillator assemblies constitute 35-45% of system BOM, exposing margins to rare-earth supply fluctuations.
- EU MDR conformity assessment timelines:Extended notified body review periods delay commercialization for devices seeking European clinical deployment.
- Pure optical microscopy substitution:Confocal and two-photon systems retain cost advantages for superficial imaging applications under 500 microns depth.
Strategic Opportunities
- Point-of-care oncology screening:Portable system architectures unlock ambulatory clinic deployment models outside traditional hospital radiology departments.
- Photoacoustic-OCT convergence:Combined optical coherence tomography detection channels create premium positioning for ophthalmology and vascular imaging applications.
- India PLI scheme alignment:Domestic manufacturing incentives for medical devices reduce import duty exposure for assembly-focused OEMs establishing local production.
Industry Challenges
- Ultrasonic transducer calibration expertise:Shortage of trained service engineers extends installation timelines and elevates customer support costs for distributed installations.
- ISO 13485 certification complexity:Quality management system implementation demands 18-24 month runway for research-system vendors pivoting to clinical markets.
- Legacy PACS integration friction:DICOM compliance gaps between photoacoustic data formats and hospital archiving systems require custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoacoustic Microscope Market |
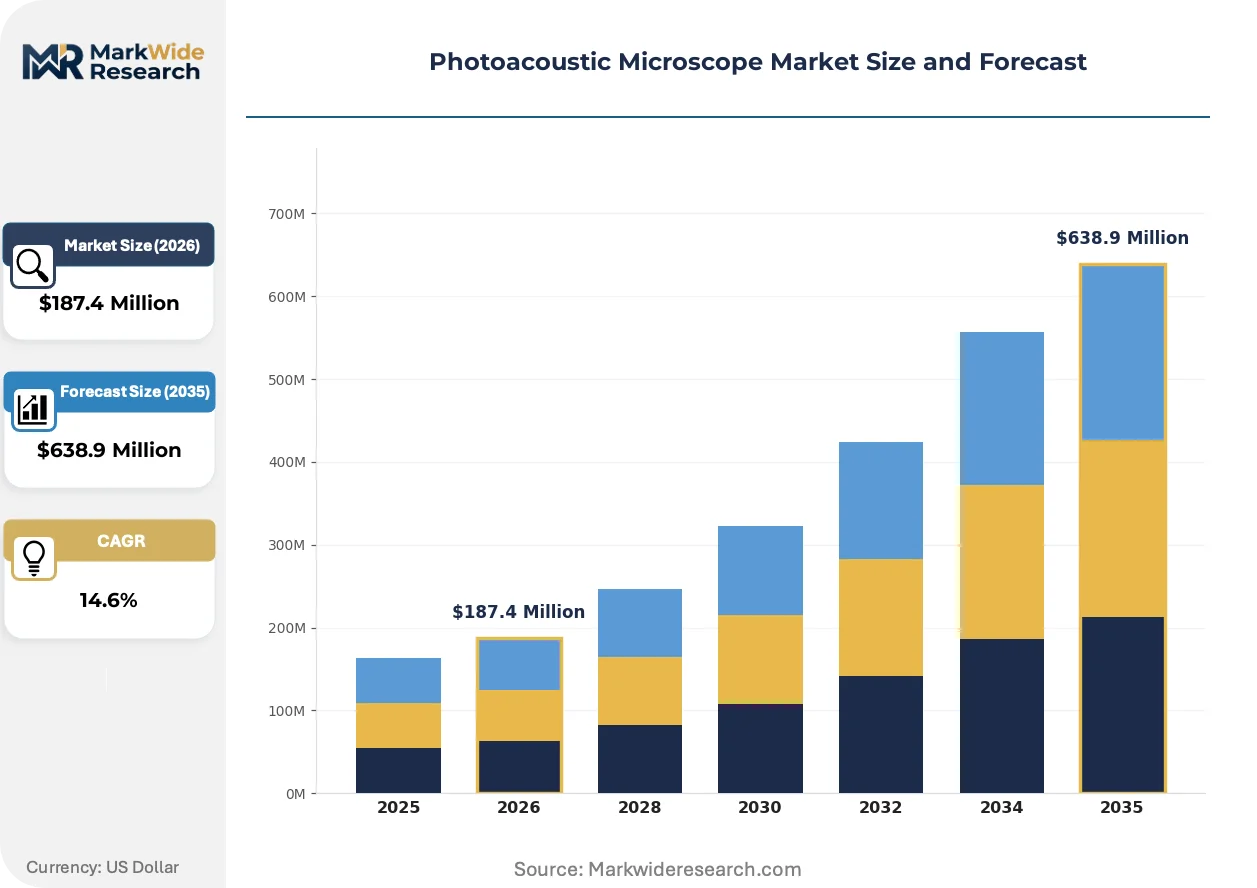
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Systems, Portable Systems, Handheld Devices, OEM Solutions Technology: Laser-Induced, Ultrasound-Based, Multi-Modal, Non-Linear End User: Research Laboratories, Biomedical Facilities, Educational Institutions, Industrial Applications Application: Biomedical Imaging, Material Science, Cancer Detection, Biological Research |
| Companies Covered | FUJIFILM VisualSonics Inc., iThera Medical GmbH, Seno Medical Instruments Inc., TomoWave Laboratories Inc., Advantest Corporation, Kibero GmbH, OPOTEK LLC, illumiSonics Inc., ENDRA Life Sciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoacoustic Microscope Market Evolving Landscape
Hardware miniaturization and algorithmic reconstruction advances are compressing the performance gap between benchtop and portable photoacoustic platforms, enabling new deployment contexts outside centralized imaging centers.
LED-based excitation sources are decomposing the cost structure of traditional laser-dependent photoacoustic systems. Research laboratories in Japan and Germany adopt solid-state illumination for preclinical vascular mapping applications. This shift is decomposing the historical premium attached to tunable laser subsystems and opening mid-market price bands for multi-wavelength functional imaging.
EU MDR Article 10 post-market surveillance requirements now mandate systematic clinical follow-up data for Class IIa diagnostic devices. Manufacturers must establish quality management systems capturing real-world performance metrics across installed base. Dermatology applications in France and Germany face elevated documentation burdens, prompting vendors to pre-validate clinical evidence packages during design phases.
Hospital procurement committees now unbundle service contracts from capital equipment purchases, compressing vendor margin pools into discrete performance-based maintenance agreements. Academic medical centers in the United States negotiate outcome-tied service tiers indexed to system uptime and image quality metrics. This restructuring concentrates pricing power with buyers possessing internal biomedical engineering capabilities.
Photoacoustic Microscope Market Segmentation
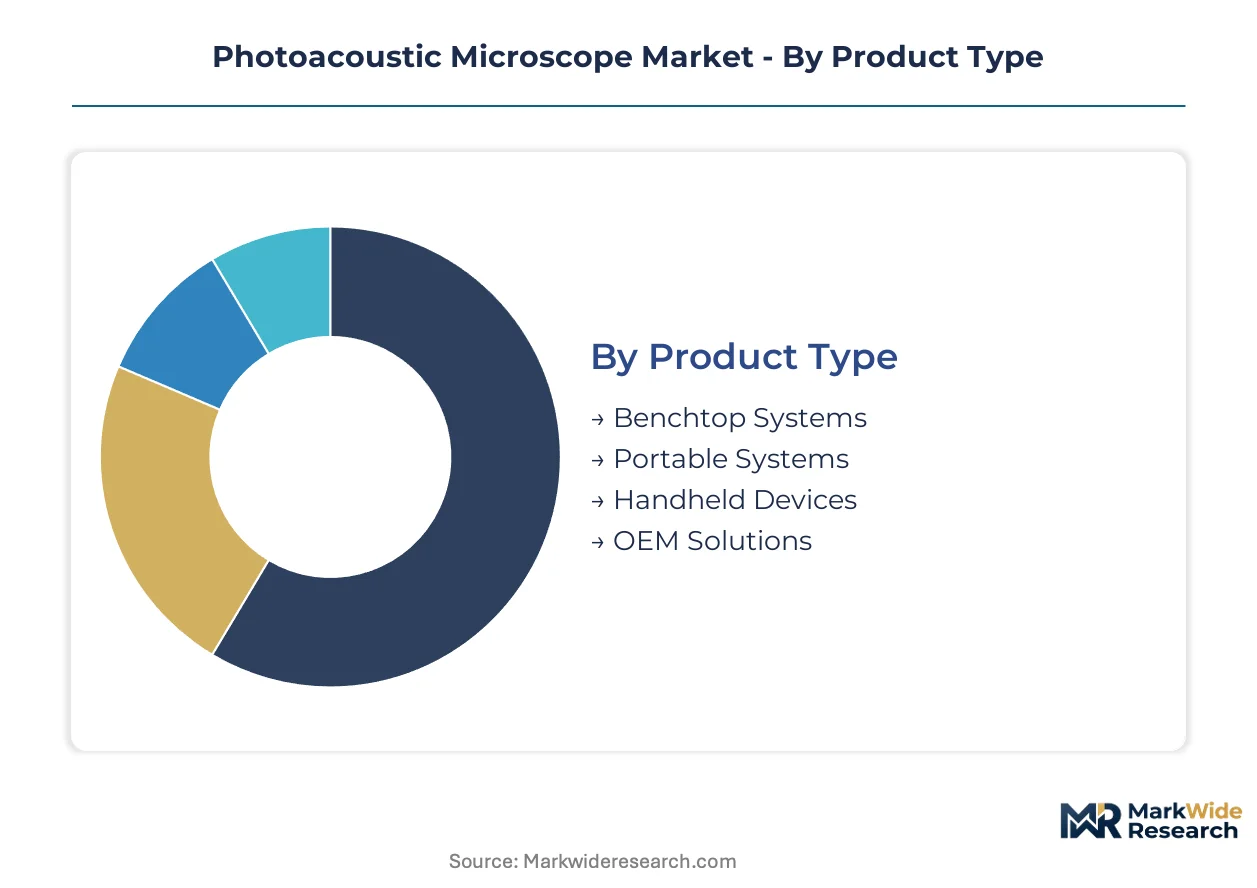
Photoacoustic microscope segmentation reveals divergent commercial pathways across product architectures and deployment contexts. Research laboratories in Germany and Japan concentrate procurement in integrated benchtop configurations, while point-of-care expansion in ambulatory settings is fragmenting demand across portable and handheld form factors.
Product Type:
Benchtop systems dominate domestic installations across university hospital networks in Germany and Japan, where capital budgets accommodate premium laser subsystems. Portable architectures concentrate export-led demand from Southeast Asian diagnostic chains seeking deployable oncology screening.
- Benchtop Systems:Full-scale laboratory platforms integrate tunable Nd:YAG lasers and optical parametric oscillators for multi-wavelength functional imaging. German university hospitals anchor procurement volumes through dermatology department expansions, constrained by extended EU MDR conformity assessment timelines.
- Portable Systems:Compact architectures with solid-state LED excitation enable ambulatory clinic deployment outside centralized radiology departments. Japanese METI infrastructure grants accelerate domestic adoption for point-of-care melanoma protocols.
- Handheld Devices:Miniaturized probe designs target superficial vascular mapping in rheumatology outpatient workflows.
- OEM Solutions:Modular subsystems supplied to third-party imaging integrators reduce customer switching costs.
Benchtop systems hold the largest share; momentum sits with portable systems.
Technology:
Laser-dependent architectures command premium positioning through wavelength tunability, while LED-based alternatives decompose cost structures for mid-market access. Multi-modal configurations justify higher price tiers through combined ultrasound and optical coherence tomography channels.
- Laser-Induced:Pulsed Nd:YAG and optical parametric oscillator assemblies generate acoustic waves through selective optical absorption. Research laboratories in Germany specify these systems for preclinical vascular depth penetration exceeding 500 microns.
- Multi-Modal:Hybrid photoacoustic-ultrasound platforms integrate conventional imaging channels for reimbursable oncology screening protocols. Japanese university hospitals concentrate procurement through METI-funded infrastructure programs.
- Ultrasound-Based:Standalone acoustic detection without optical excitation serves industrial non-destructive testing applications.
- Non-Linear:Harmonic generation techniques enable specialized material science characterization.
Multi-modal configurations capture premium positioning; LED-based alternatives are expanding most quickly.
End User:
Research laboratories anchor installed base volumes through preclinical imaging workflows, while biomedical facilities concentrate clinical-grade procurement under FDA 510(k) and EU MDR pathways. Educational institutions represent price-sensitive demand for training-tier configurations.
- Research Laboratories:Preclinical imaging workflows in Germany and Japan drive specifications for multi-wavelength functional mapping and vascular network reconstruction. METI funding accelerates domestic Japanese university installations.
- Biomedical Facilities:Clinical deployment demands ISO 13485-certified manufacturing and DICOM-compliant data formats for PACS integration. German dermatology departments expand procurement specifications for early-stage melanoma detection.
- Educational Institutions:Training-focused demand concentrates in simplified system architectures with reduced service contract requirements.
- Industrial Applications:Non-destructive material characterization drives specialized configurations outside biomedical use cases.
Research laboratories retain volume leadership; biomedical facilities gain share fastest.
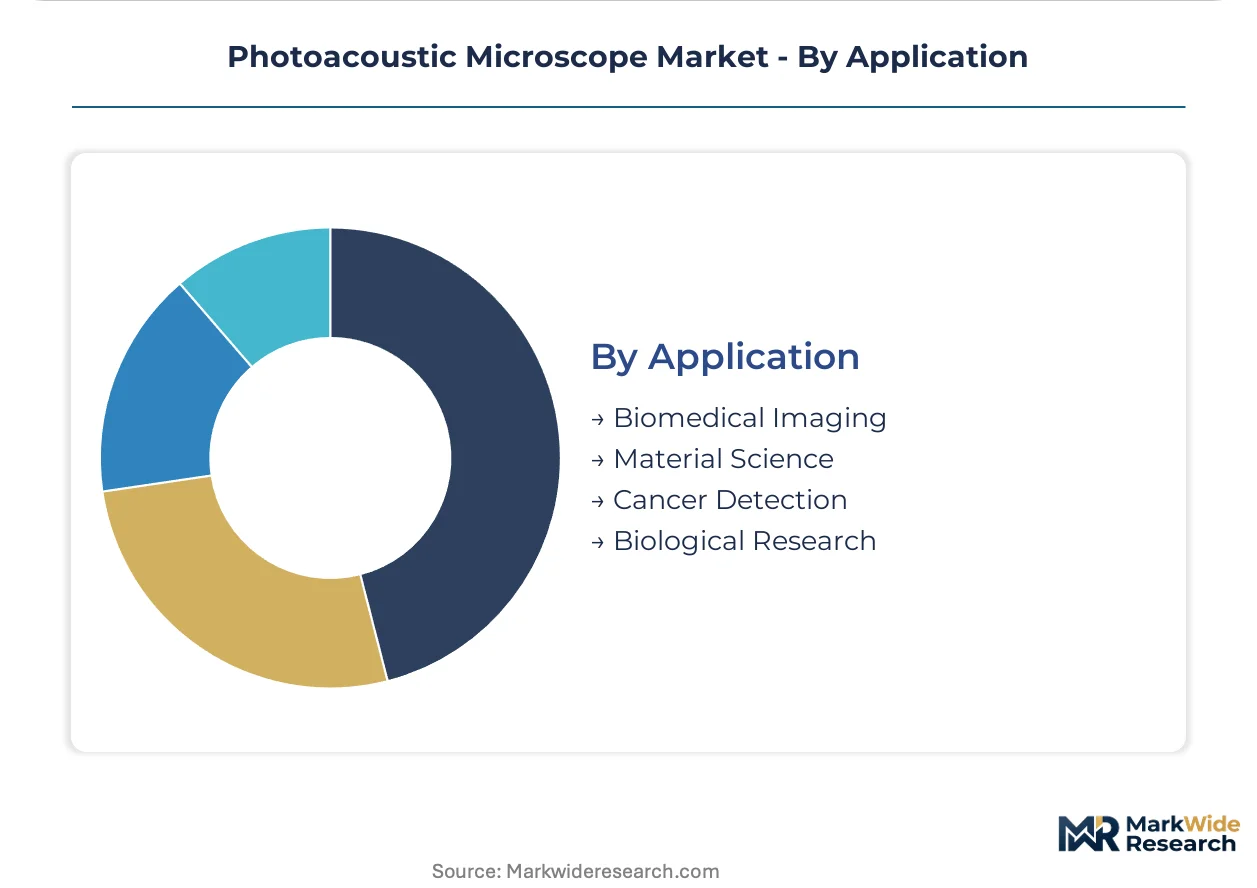
Application:
Cancer detection protocols concentrate reimbursement-focused investment, while material science applications remain confined to industrial research segments. Biological research spans both preclinical and translational workflows with divergent regulatory requirements.
- Cancer Detection:Early-stage melanoma screening protocols in German university hospitals specify photoacoustic systems for dermatology department capital budgets. FDA 510(k) clearance velocity compresses time-to-market for clinical-grade configurations.
- Biomedical Imaging:Vascular network mapping and oxygen saturation monitoring concentrate demand in rheumatology and ophthalmology workflows. Japanese domestic adoption curves accelerate through METI infrastructure grants.
- Material Science:Non-destructive testing of composite structures serves aerospace and electronics manufacturing quality control.
- Biological Research:Preclinical vascular dynamics studies span plant physiology and small-animal model applications.
Cancer detection commands premium pricing; biomedical imaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers absorb premium pricing through METI-funded hospital infrastructure, while Indian diagnostic chains drive portable system demand at aggressive price points. German procurement committees balance clinical-grade specifications against extended EU MDR timelines. The United States concentrates FDA-cleared clinical deployment, and South Korean manufacturing clusters supply laser subsystems across the value chain.
United States
FDA 510(k) clearance velocity compresses commercialization timelines for clinical-grade photoacoustic systems. Hospital procurement committees at academic medical centers in Boston and the San Francisco Bay Area unbundle service contracts from capital purchases. The National Institutes of Health funds preclinical imaging infrastructure at research universities, anchoring benchtop system demand.
Germany
University hospital dermatology departments in Munich and Heidelberg expand capital budgets for early-stage melanoma detection protocols. EU MDR conformity assessment timelines extend by 12-18 months for Class IIa diagnostic devices seeking notified body review. The Baden-Württemberg medical technology cluster concentrates preclinical imaging R&D alongside precision photonics manufacturing.
Japan
METI infrastructure grants accelerate domestic adoption curves through university hospital installations in Tokyo and Osaka. PMDA regulatory pathways align with international standards for multi-modal imaging platforms. The Kanto region anchors demand for portable configurations serving point-of-care oncology screening in ambulatory settings.
India
Diagnostic chains in Maharashtra and Karnataka procure portable LED-based systems for deployable cancer screening programs. PLI scheme incentives for domestic medical device manufacturing reduce import duty exposure for assembly-focused OEMs. Hyderabad and Bengaluru clusters concentrate biomedical engineering talent for ultrasonic transducer calibration services.
South Korea
MFDS regulatory harmonization with FDA precedents streamlines market entry for clinical-grade systems. Seoul-based photonics manufacturers supply Nd:YAG laser subsystems to integrated OEMs across the Asia-Pacific. The Pangyo Techno Valley cluster concentrates optical parametric oscillator production for multi-wavelength functional imaging platforms.
Photoacoustic Microscope Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in firms controlling captive photonics supply chains. The market structure stratifies between full-platform vendors and modular subsystem suppliers, with switching costs determining customer retention. Two strategic archetypes dominate: vertically integrated imaging conglomerates and focused clinical-application specialists. Competitive moves center on multi-modal platform integration and regional regulatory pre-certification to compress time-to-market.
Within the integrated imaging tier, FUJIFILM VisualSonics Inc. exemplifies platform leverage through ultrasound technology convergence, while iThera Medical GmbH anchors the specialized clinical-application segment with Germany-based manufacturing. TomoWave Laboratories Inc. occupies a position in modular system architectures that reduce customer migration costs. These three firms represent divergent strategic postures: full-platform dominance, indication-specific depth, and configurability-focused market access.
| Leading Market Players |
|---|
| FUJIFILM VisualSonics Inc. |
| iThera Medical GmbH |
| Seno Medical Instruments Inc. |
| TomoWave Laboratories Inc. |
| Advantest Corporation |
| Kibero GmbH |
| OPOTEK LLC |
| illumiSonics Inc. |
| ENDRA Life Sciences Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Nd:YAG laser foundries in South Korea and Germany sets price floors across system tiers, concentrating margin pressure on assembly-focused OEMs lacking captive photonics supply. This scale dynamic bifurcates the market between integrated manufacturers commanding premium positioning and modular suppliers competing on configurability.
Pricing Analysis
Service contract unbundling now drives lifetime value, with academic medical centers in the United States negotiating outcome-tied maintenance tiers indexed to system uptime. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical platforms from preclinical research systems and training-tier configurations. Cost compression in portable LED-based architectures is intensifying because solid-state illumination decomposes traditional laser-dependent BOM structures. Diagnostic chains in India exhibit highest price sensitivity, while Japanese university hospitals absorbing METI-funded installations show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for optical parametric oscillator assemblies sourced from Seoul-based photonics manufacturers. Supply concentrates in South Korea for laser subsystems, Germany for precision optics, and Japan for ultrasonic transducer arrays. System BOM draws from rare-earth elements for Nd:YAG crystals, specialty glass for fiber couplers, and piezoelectric ceramics for acoustic detection. Single-source vulnerability sits with tunable laser suppliers facing rare-earth supply fluctuations. Distribution runs through direct hospital procurement committees at academic medical centers and specialized imaging distributors serving research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement committee consolidation among German university hospital networks is shifting pricing power toward buyers with internal biomedical engineering capabilities, fragmenting vendor margin pools into discrete performance-based agreements.
For Market Incumbents: Consolidate captive control over photonics supply chains to defend against LED-based substitution eroding premium positioning in portable segments. Deepen ISO 13485-certified manufacturing capacity in Germany to compress EU MDR conformity assessment timelines. Lock hospital system partnerships through outcome-tied service contracts that raise customer switching costs. For New Entrants and Emerging Players: Lead with modular OEM subsystems that reduce migration costs for research-system vendors pivoting to clinical markets. Target India's PLI-aligned domestic manufacturing incentives to bypass import duty exposure at aggressive price points. Pursue rheumatology outpatient workflows as the most penetrable application segment, leveraging handheld form factors for superficial vascular mapping protocols. For Investors and Strategic Acquirers: Focused clinical-application specialists with dermatology-specific regulatory dossiers represent priority acquisition targets in a market favoring indication depth over platform breadth. Long-term viability hinges on multi-modal convergence with ultrasound and optical coherence tomography channels expanding reimbursable procedure codes. Monitor FDA 510(k) clearance velocity for photoacoustic-ultrasound hybrid platforms as the inflection signal distinguishing scalable clinical deployment from confined research applications.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Integration | Hybrid photoacoustic-ultrasound configurations unlock reimbursable oncology screening codes in German hospital networks. |
| LED Excitation Transition | Solid-state illumination decomposes laser-dependent cost structures for mid-market portable system access. |
| EU MDR Pre-Certification | Early notified body engagement compresses commercialization timelines for Class IIa diagnostic devices. |
| Point-of-Care Deployment Architecture | Compact form factors enable ambulatory clinic screening outside centralized radiology departments in Japan. |
| Outcome-Tied Service Contracts | Performance-based maintenance agreements align vendor economics with hospital system uptime metrics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, PMDA regulatory databases, METI infrastructure grant disclosures, and EU MDR notified body assessment records. Clinicians at German university hospital dermatology departments, biomedical engineers at Japanese academic medical centers, GPO contracts managers at US hospital systems, and procurement leads at Indian diagnostic chains provided structured input. Bottom-up triangulation across installed base estimates and top-down validation against capital equipment expenditure flows ensure analytical coherence.
Segmentation dimensions modeled span product architecture, excitation technology, end-user category, and clinical application across the projection horizon. CAGRs derive from regression analysis of historical procurement cycles and regulatory approval timelines. Forecast inputs incorporate METI funding trajectories, EU MDR assessment period extensions, and LED-based system adoption curves in point-of-care settings.
The analysis sits within stated boundaries; outcomes outside sustained regulatory funding commitments, stable rare-earth supply chains, and continued 510(k) pathway efficiency would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code expansion and hospital capital budget prioritization. Technology substitution risks from confocal microscopy and evolving PACS integration standards could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Handheld Imaging Systems Market
Imaging
Contact Image Sensor Market
Imaging
Digital X-Ray Technology Market
Imaging
CMOS Camera Market
Imaging
EUV Mask Inspection System Market
Imaging
Digital Imaging Market
Imaging
Raman-Imaging System Market
Imaging
Handheld Retinal Scanners Market
Imaging
Ingaas Image Sensor Market
Imaging
Multimodal Imaging Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
Computer Aided Detection Market
Imaging
TDI Camera Market
Imaging
Wearable IP Camera Market
Imaging
Stacked CMOS Image Sensor Market