
 EUV Mask Inspection System Market | 2026-2036
EUV Mask Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
EUV Mask Inspection System Market Insights
East Asian foundry expansion is tilting capital equipment allocation toward mask inspection infrastructure. Lasertec Corporation leverages its dominant position in actinic pattern mask inspection for sub-7nm nodes. KLA Corporation sustains broad metrology portfolios spanning optical and e-beam modalities. Carl Zeiss SMT GmbH anchors optical column technology critical to high-NA EUV imaging resolution.
An EUV mask inspection system verifies defect-free photomask integrity using actinic wavelengths at 13.5nm, employing multi-layer Mo/Si mirror optics and aerial image simulation to catch phase defects, particles, and pattern errors before wafer exposure. Optical inspection systems dominate current installed bases due to throughput advantages at production scale, while e-beam inspection systems capture expanding share for sensitivity-critical logic layers where single-digit nanometer defect detection proves essential. Machine learning integration across pattern recognition pipelines is compressing classification cycle times and reducing false-positive rates in high-volume manufacturing environments.
The EU AI Act, US BIS export controls, and Japan METI foreign exchange regulations are fragmenting equipment procurement pathways and forcing regional qualification of inspection tool suppliers. REACH and RoHS compliance requirements constrain materials selection for optical coatings and electronic subassemblies, adding certification overhead to new product introductions. Stakeholders must monitor evolving multilateral semiconductor controls and pre-qualify alternative supply chain configurations before capacity commitments lock in.
Market Dynamics
Actinic inspection at 13.5nm wavelength is displacing optical methods for sub-7nm node qualification, forcing foundries to retool mask qualification workflows before high-NA EUV deployment locks in infrastructure choices.
Growth Catalysts
- High-NA EUV lithography ramp:TSMC and Samsung Foundry are qualifying actinic pattern mask inspection tools for 2nm-class production, creating immediate tool procurement pull.
- REACH and RoHS compliance mandates:European environmental regulations are accelerating replacement of legacy inspection systems using restricted coating materials.
- Memory layer complexity:3D NAND string stacking beyond 200 layers demands defect detection at single-digit nanometer sensitivity for critical mask layers.
Market Restraints
- Mo/Si multilayer supply concentration:Mirror substrate fabrication depends on a limited supplier base in Germany and Japan, creating input vulnerability.
- Actinic source scarcity:EUV plasma source generation for inspection tools remains technically constrained, limiting system throughput relative to optical alternatives.
- US BIS export control friction:Licensing requirements for sub-7nm inspection technology are fragmenting equipment deployment timelines across foundry networks.
Strategic Opportunities
- India semiconductor manufacturing:Micron Technology's Gujarat assembly and test facility is creating demand for mask qualification infrastructure as domestic fab projects advance.
- Machine learning defect classification:Neural network integration with aerial image simulation is compressing classification cycle times and reducing false-positive rates.
- Japan METI equipment localization incentives:Subsidies for domestic production of critical lithography subsystems are opening qualification pathways for regional inspection tool vendors.
Industry Challenges
- Actinic inspection physicist shortage:The intersection of EUV optics, plasma physics, and computational imaging commands limited talent pools concentrated at national laboratories and leading equipment makers.
- Legacy optical system integration:Foundries must maintain parallel qualification workflows during multi-year transition periods, straining cleanroom footprint and technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EUV Mask Inspection System Market |
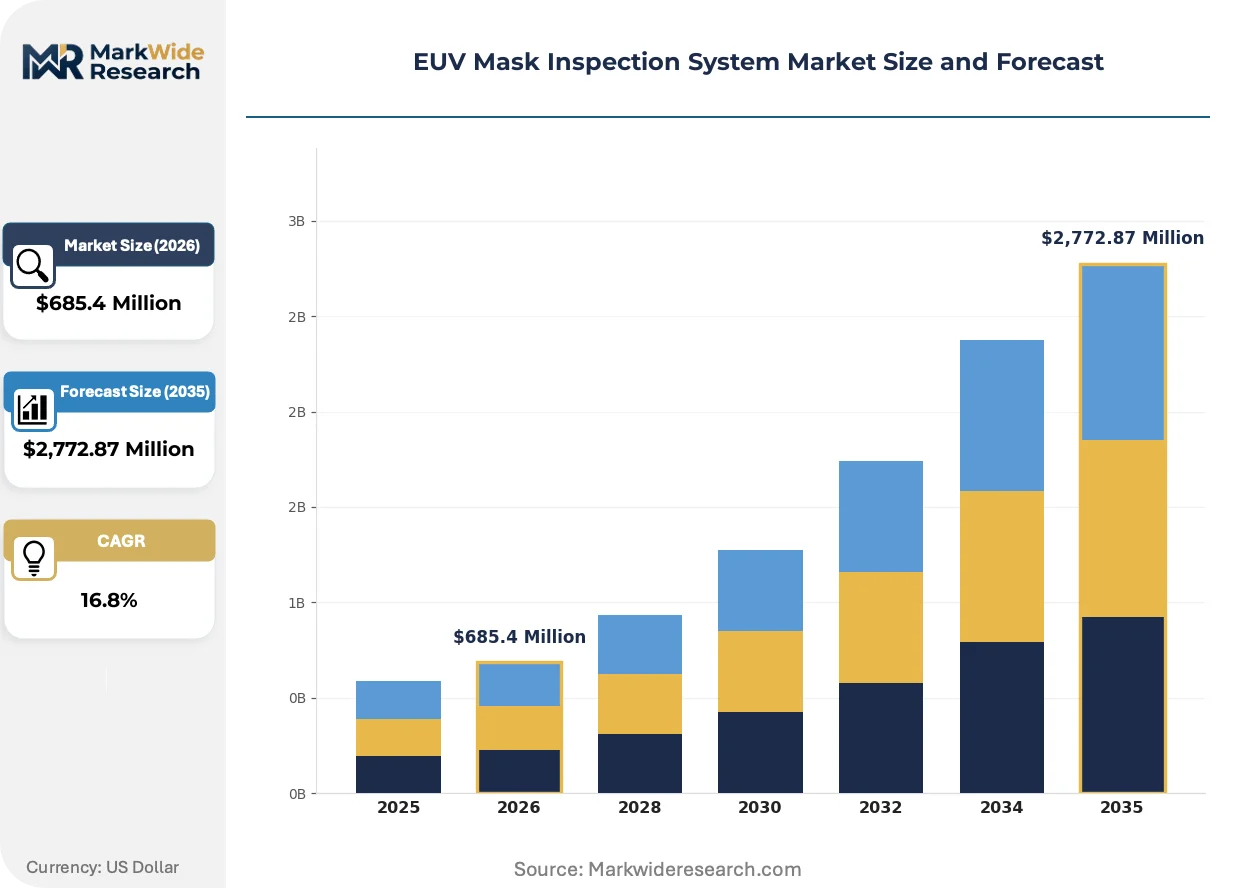
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,772.87 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Inspection Systems, E-beam Inspection Systems, 3D Inspection Systems, Automated Inspection Systems Technology: Image Processing, Pattern Recognition, Machine Learning, Data Analytics Application: Semiconductor Manufacturing, Photomask Production, Quality Control, Research & Development End User: Foundries, Integrated Device Manufacturers, R&D Institutions, Fabless Companies |
| Companies Covered | Lasertec Corporation, KLA Corporation, Carl Zeiss SMT GmbH, NuFlare Technology, ASML Holding, Advantest Corporation, Hitachi High-Tech Corporation, Applied Materials, ZEISS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EUV Mask Inspection System Market Trends and Innovations
Computational imaging and machine learning are compressing defect detection workflows while regulatory fragmentation forces regional equipment qualification strategies. Three developments are reshaping competitive positioning.
Deep ultraviolet optical inspection is rendering obsolete traditional broadband visible-light systems for sub-10nm node mask qualification. Leading foundries in Taiwan and South Korea are phasing out 193nm optical tools for critical layers, completing transition to actinic wavelength inspection by 2027. The shift is compressing equipment replacement cycles from seven years to four years for logic mask sets.
EU AI Act algorithmic transparency requirements are mandating explainable defect classification in automated inspection pipelines. Equipment suppliers must document machine learning model decision pathways for high-risk semiconductor manufacturing applications. Memory producers in Germany and France are pre-qualifying inspection tools against forthcoming conformity assessment procedures.
Consolidated procurement through foundry-alliance joint qualification is displacing individual equipment selection by single fabs. The Common Platform alliance and IMEC's mask program are centralizing technical evaluation, compressing vendor negotiation leverage. This concentration is most visible in Taiwan where TSMC's supplier co-development programs lock in multi-year capacity commitments.
EUV Mask Inspection System Market Segmentation
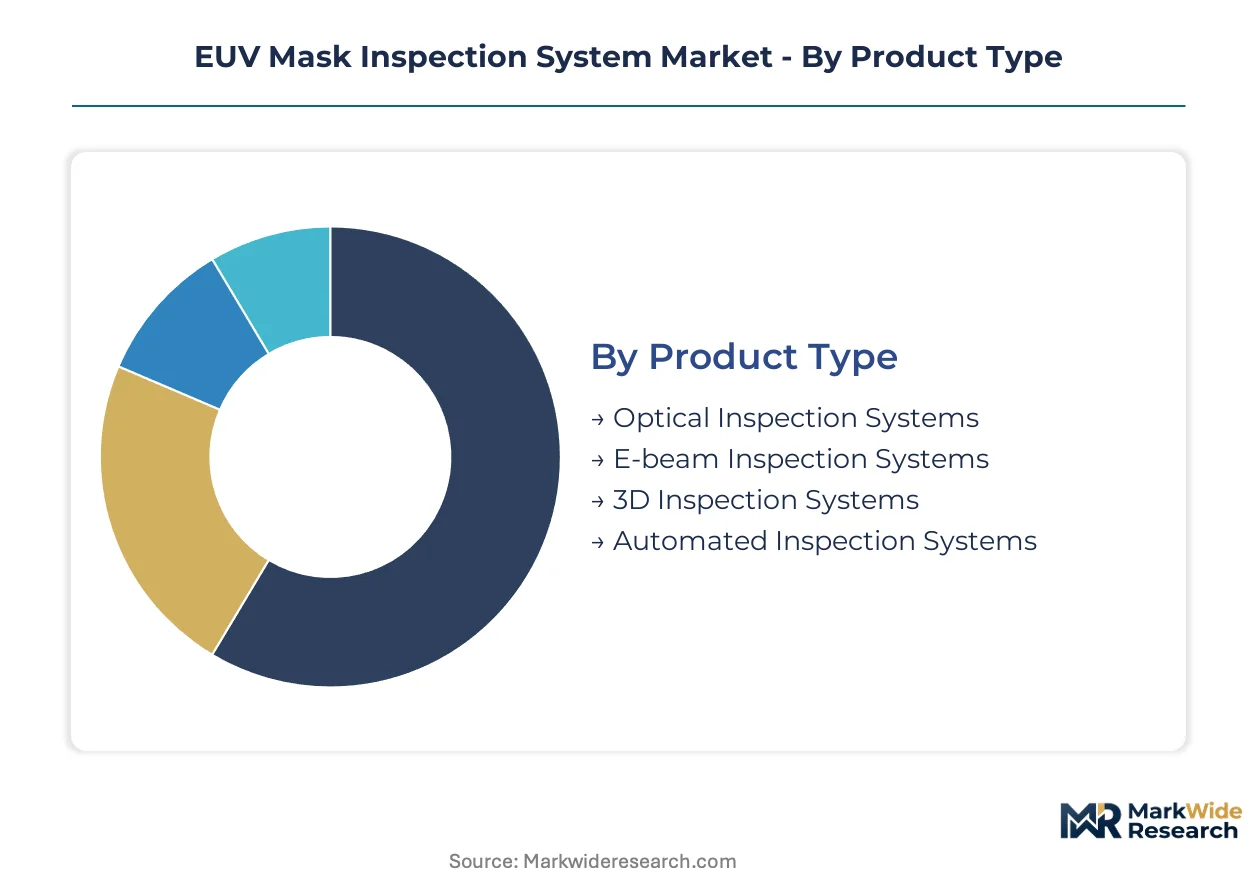
EUV mask inspection system procurement varies sharply across product architectures and user workflows. Segmentation reveals where capital concentrates and which technology transitions are forcing infrastructure replacement cycles.
Product Type:
After-sales service intensity runs highest for actinic platforms requiring specialized plasma source maintenance and Mo/Si mirror refurbishment contracts.
- Optical Inspection Systems:These systems employ deep ultraviolet wavelengths for high-throughput pattern verification at mature nodes. Demand clusters at legacy logic fabs in Taiwan and South Korea maintaining multi-node production portfolios.
- E-beam Inspection Systems:Electron beam architectures deliver sub-nanometer sensitivity for critical mask layers through direct surface imaging. Memory producers in South Korea are expanding installed base for 3D NAND string stacking applications where particle detection thresholds approach atomic dimensions.
- 3D Inspection Systems:Multi-angle acquisition platforms reconstruct mask topography for phase defect quantification.
- Automated Inspection Systems:Robotic handling integration enables lights-out operation in high-volume manufacturing environments.
Optical inspection systems hold the largest share; momentum sits with E-beam platforms.
Technology:
Cost tier separation is pronounced between legacy algorithmic methods and AI-augmented pipelines requiring specialized compute hardware.
- Image Processing:Traditional filtering and enhancement algorithms provide baseline defect detection for non-critical mask layers. Foundries in Taiwan retain these systems for routine pattern verification where throughput outweighs sensitivity requirements.
- Pattern Recognition:Template matching against design databases enables systematic error classification. Memory manufacturers in Japan deploy these methods for repetitive array structures in 3D NAND production.
- Machine Learning:Neural network architectures reduce false-positive rates through training on historical defect libraries.
- Data Analytics:Statistical process control integration links mask quality to downstream lithography performance.
Image processing commands the largest installed base; machine learning is climbing the fastest.
Application:
Volume concentration tracks directly with leading-edge fab capacity expansion timelines.
- Semiconductor Manufacturing:In-line mask qualification for wafer production represents the primary demand center. Foundries in Taiwan and South Korea are procuring actinic tools ahead of high-NA EUV ramp schedules.
- Photomask Production:Merchant mask shops require multi-modal inspection for diverse customer node requirements. Japanese suppliers are upgrading capabilities to serve both domestic and export markets.
- Quality Control:Final verification workflows before mask shipment to fab customers.
- Research & Development:Process development for future nodes employs flexible inspection configurations.
Semiconductor manufacturing dominates value capture; photomask production shows steepest expansion trajectory.
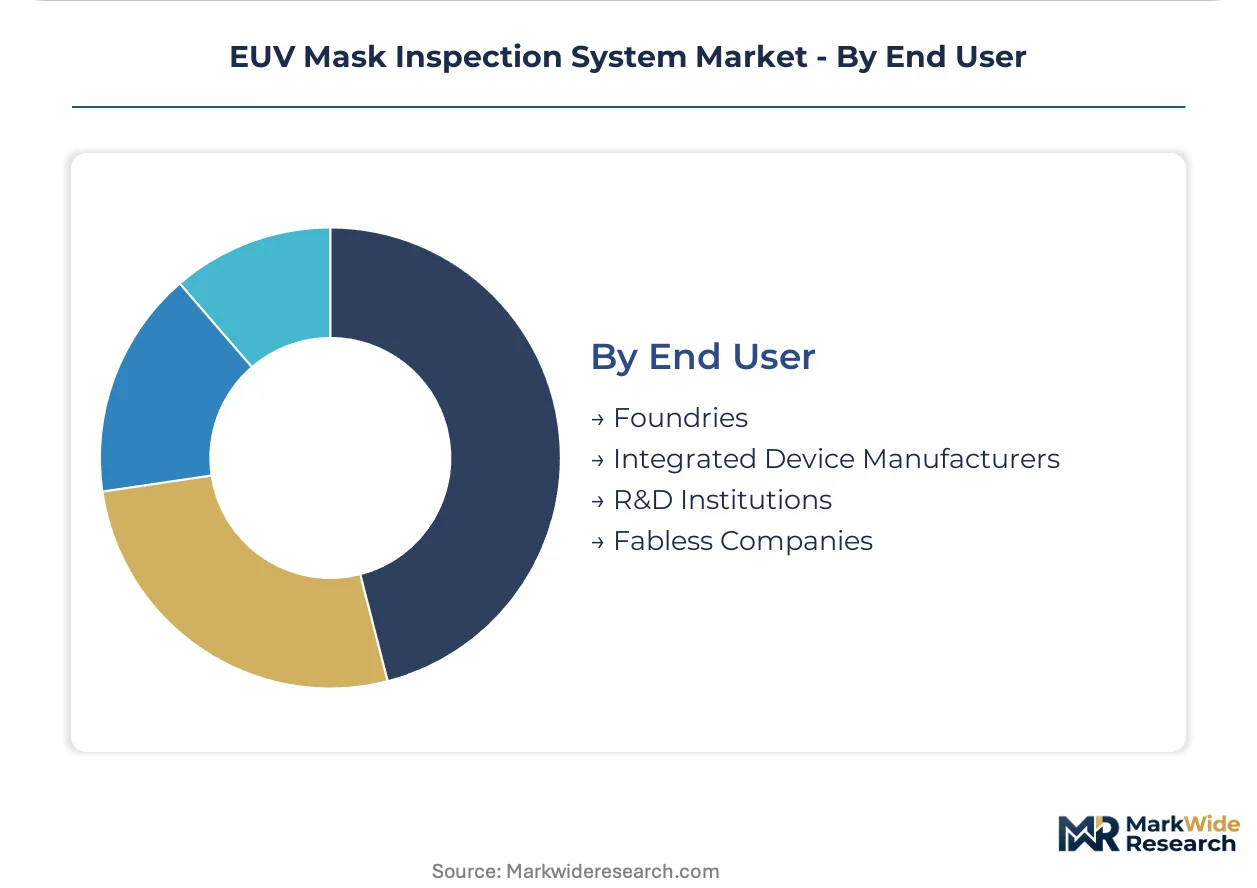
End User:
Customer type determines procurement scale and technical specification rigor.
- Foundries:Pure-play contract manufacturers purchase highest system counts for multi-customer mask portfolios. TSMC and Samsung Foundry drive specification roadmaps through direct supplier co-development programs.
- Integrated Device Manufacturers:Captive logic and memory producers balance internal demand against merchant supply opportunities. Intel and Micron Technology maintain dedicated inspection infrastructure for proprietary process flows.
- R&D Institutions:IMEC and national laboratories qualify next-generation inspection methods before production transfer.
- Fabless Companies:Design houses rely on foundry and merchant mask shop inspection services without direct capital investment.
Foundries represent the largest procurement segment; integrated device manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mo/Si multilayer mirror fabrication concentrates in German and Japanese supplier networks, creating input dependencies that shape regional procurement strategies for EUV mask inspection infrastructure.
Taiwan
TSMC's foundry expansion in Hsinchu Science Park drives actinic inspection tool procurement ahead of high-NA EUV ramp schedules. The island's National Development Council coordinates semiconductor infrastructure subsidies under the Chip Implementation Act. Tainan and Taichung science parks host mask qualification facilities serving 2nm-class production lines.
South Korea
Samsung Foundry and SK Hynix are qualifying e-beam inspection systems for 3D NAND string stacking beyond 200 layers. K-Semiconductor Belt initiative channels public investment into domestic lithography subsystem capabilities. Pyeongtaek and Yongin clusters concentrate memory-focused mask inspection demand.
United States
Intel's domestic fab buildout in Arizona and Ohio creates procurement pull for multi-modal inspection platforms. US BIS export controls fragment equipment deployment timelines for sub-7nm technology. Greater Phoenix and Columbus metro areas anchor captive IDM mask qualification infrastructure.
Japan
Merchant mask shops in Tokyo and Osaka prefectures upgrade capabilities for export market service. METI equipment localization incentives subsidize domestic production of critical lithography subsystems. Tsukuba and Yokohama industrial corridors host R&D institutions qualifying next-generation inspection methods.
Germany
Carl Zeiss SMT anchors optical column technology for high-NA EUV imaging resolution from Oberkochen and Jena facilities. ECHA REACH compliance mandates accelerate replacement of legacy systems using restricted coating materials. Dresden's Silicon Saxony cluster integrates mask inspection into leading-edge logic production workflows.
EUV Mask Inspection System Market Competitive Landscape
Actinic specialists and diversified metrology conglomerates split the market between wavelength-specific depth and portfolio breadth. The vendor base concentrates around three strategic archetypes: pure-play EUV inspection developers, multi-platform metrology conglomerates, and optical subsystem technology anchors. Consolidation pressure intensifies through foundry-alliance joint qualification programs and supplier co-development lock-ins.
Within the pure-play actinic tier, Lasertec Corporation exemplifies specialized wavelength expertise. Among diversified metrology conglomerates, KLA Corporation occupies a position spanning optical and e-beam modalities. Carl Zeiss SMT GmbH anchors optical column technology critical to imaging resolution. These three represent distinct competitive positioning vectors without overlapping capability claims.
| Leading Market Players |
|---|
| Lasertec Corporation |
| KLA Corporation |
| Carl Zeiss SMT GmbH |
| NuFlare Technology |
| ASML Holding |
| Advantest Corporation |
| Hitachi High-Tech Corporation |
| Applied Materials |
| ZEISS Group |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese Mo/Si multilayer mirror suppliers determines both pricing tier spreads and supply chain shape, compressing procurement leverage for foundries while amplifying cost pass-through from substrate vendors to system integrators.
Pricing Analysis
REACH and RoHS compliance mandates dictate the pricing tier structure across EUV mask inspection platforms. Three-tier pricing structure across premium, standard, and economy levels separates actinic systems with full environmental certification from legacy optical tools facing accelerated replacement cycles. Price differentiation rests on certification grade and after-sales service bundling, with plasma source maintenance contracts commanding substantial premiums. Cost compression in economy-tier optical systems is intensifying because foundries in Taiwan and South Korea are phasing out 193nm tools faster than planned. Merchant mask shops in Japan exhibit highest price sensitivity due to fragmented demand across diverse node requirements, while TSMC and Samsung Foundry absorb premium pricing through multi-year co-development lock-ins.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant contract-manufacturing capacity for leading-edge logic, anchoring downstream demand concentration. Geographic supply concentration centers on Germany for optical column technology, Japan for plasma source components and merchant mask fabrication, and Taiwan for foundry-integrated qualification workflows. Raw material dependencies draw from high-purity silicon substrates, molybdenum deposition targets, and specialized vacuum chamber alloys. Single-source vulnerability runs through Zeiss-controlled optical column supply for high-NA EUV imaging resolution. Distribution runs through direct supplier co-development programs rather than arms-length procurement, with IMEC and Common Platform alliance centralizing technical evaluation and compressing vendor negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through foundry-alliance joint qualification programs, with TSMC's supplier co-development lock-ins and IMEC's mask program centralizing technical evaluation and fragmenting vendor negotiation leverage.
For Market Incumbents: Build switching-cost moats through multi-year service contracts for plasma source maintenance and Mo/Si mirror refurbishment. Deepen backward integration into optical column technology to reduce Zeiss dependency exposure. Expand captive supply of actinic source components in Japan and Germany to mitigate METI and export control fragmentation. Lock in capacity commitments before high-NA EUV deployment locks in infrastructure choices. For New Entrants and Emerging Players: Build out India semiconductor manufacturing infrastructure as Micron Technology's Gujarat facility creates demand for mask qualification tools. Target merchant mask production segment where Japanese suppliers upgrade capabilities for export markets without foundry-alliance procurement concentration. Pursue METI equipment localization subsidies for domestic production of critical lithography subsystems. Position around machine learning defect classification as neural network integration compresses classification cycle times and reduces false-positive rates. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors actinic specialists with wavelength-specific depth over diversified metrology conglomerates. Long-term viability hinges on qualification for 2nm-class production and high-NA EUV ramp schedules. Acquisition target archetype: pure-play EUV inspection developers with plasma physics and computational imaging talent pools. Watch for US BIS export control licensing decisions as inflection indicator for equipment deployment timeline fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Actinic Platform Qualification | TSMC and Samsung Foundry procurement for 2nm-class production creates immediate tool pull. |
| Machine Learning Integration | Neural network deployment with aerial image simulation compresses defect classification cycle times. |
| Regional Supply Chain Localization | METI subsidies in Japan and Chip Implementation Act subsidies in Taiwan reshape equipment sourcing. |
| After-Sales Service Expansion | Plasma source maintenance and Mo/Si mirror refurbishment contracts capture recurring revenue streams. |
| Merchant Mask Shop Capability Upgrade | Japanese suppliers in Tokyo and Osaka prefectures expand for export market service. |
Research Methodology
Cross-validation between equipment supplier technical disclosures and foundry capital expenditure filings anchors the qualitative findings in this study. Primary interviews with mask qualification engineers, lithography subsystem procurement leads, plasma physics researchers, cleanroom operations directors, and regulatory compliance officers combined with secondary validation from SEMI equipment forecasts, national semiconductor subsidy filings, export control licensing databases, and patent assignment records. Bottom-up and top-down triangulation reconciles system shipment tallies with fab capacity expansion timelines.
Calibration against historical replacement cycles for optical inspection systems and announced high-NA EUV ramp schedules validates projection assumptions across the analysis window. Segmentation dimensions modeled include inspection modality, technology tier, application workflow, and customer archetype, with additional granularity on node-specific sensitivity requirements. CAGRs derive from equipment procurement phasing tied to foundry buildout schedules and memory layer complexity trajectories. Forecast inputs incorporate plasma source throughput constraints and Mo/Si multilayer fabrication capacity.
Sensitivities concentrate around US BIS export control licensing decisions, METI subsidy allocation timing, and high-NA EUV deployment schedule acceleration. Forecasts reflect assumptions on regional qualification pathway fragmentation and supplier co-development lock-in persistence. Quarterly review of foundry capital expenditure announcements, export control licensing queues, and plasma source technology disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Handheld Imaging Devices Market
Imaging
Latin America IP Camera Market
Imaging
Near Infra-Red Imaging Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Facial Recognition Machine Market
Imaging
Electron Microscopy Market
Imaging
PET Imaging Systems Market
Imaging
Image Intensifier Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Global Label-Free Array Systems Market
Imaging
Machine Vision System Market
Imaging
Chemical Imaging Systems Market
Imaging
Machine Vision Camera Market
Imaging
Global 3D Camera Market
Imaging
Small CCTV Camera Market