
 Side View Camera System Market | 2026-2036
Side View Camera System Market Size, Share, and Industry Trends Forecast 2026-2036
Side View Camera System Market Analysis
Silicon carbide power substrates are repositioning thermal management economics in side view camera modules, enabling smaller housings and reduced wiring complexity. Continental AG leverages in-house semiconductor sourcing to control module costs across European OEM programs. Robert Bosch anchors its competitive stance through proprietary image-processing algorithms that reduce latency in digital side view systems. Valeo dominates the factory-installed segment by integrating camera housings with aerodynamic mirror-replacement enclosures.
A side view camera system replaces traditional exterior mirrors with compact camera modules and interior display units, typically operating at IP6K9K ingress protection ratings with 60-120 degree fields of view and high-dynamic-range sensors for glare suppression. The primary purpose is eliminating blind spots while reducing aerodynamic drag and pedestrian strike risk in commercial and passenger vehicles. Conventional cameras still occupy the largest installed base, though 360-degree cameras represent the fastest-expanding product category as surround-view architectures consolidate multiple sight lines into unified processing chains. Digital technology leads the technology split, while fiber optic transmission gathers momentum in heavy-duty fleet applications where electromagnetic interference resistance matters.
NHTSA in the United States and UN ECE R46 in Europe govern mirror-replacement approval, with both frameworks now permitting camera systems as legal alternatives to reflective glass. Japan's Ministry of Land, Infrastructure, Transport and Tourism aligned its type-approval process with UN standards, opening Japanese OEM integration pathways. Fleet operators and autonomous vehicle developers must monitor how regional homologation timelines diverge, as delayed regulatory parity between jurisdictions will fragment procurement strategies and complicate platform standardization across multinational vehicle programs.
Market Dynamics
Silicon carbide power substrates are compressing thermal management footprints in side view camera modules, forcing suppliers to redesign housings and simplify wiring architectures across OEM programs.
Growth Catalysts
- UN ECE R46 mirror-replacement standards:European and Japanese regulators now permit camera systems as legal alternatives to reflective glass, unlocking factory-installed integration at major automotive platforms.
- Commercial fleet electrification:Electric truck and bus operators in Germany, Japan, and the United States prioritize aerodynamic drag reduction through mirror-replacement camera systems to extend range.
- High-dynamic-range sensor diffusion:HDR image sensors suppress glare in adverse lighting conditions, enabling consistent performance across dawn-dusk commercial driving schedules.
Market Restraints
- Semiconductor substrate cost volatility:Silicon carbide wafer prices fluctuate with power electronics demand from adjacent sectors, compressing module margins.
- Homologation timeline fragmentation:Divergent approval schedules between NHTSA, UN ECE R46, and Japan's MLIT complicate platform standardization for multinational vehicle programs.
- Glass mirror residual preference:Cost-sensitive fleet segments in emerging markets continue specifying conventional reflective mirrors for repair simplicity and vandalism tolerance.
Strategic Opportunities
- Heavy-duty fiber optic transmission:Electromagnetic interference resistance in mining and construction fleets opens premium pricing for fiber-linked camera architectures.
- 360-degree surround-view consolidation:Camera modules that feed unified processing chains reduce per-vehicle sensor count and wiring weight.
- Autonomous vehicle developer procurement:Self-driving truck and robotaxi programs require redundant side visibility without mirror-induced sensor occlusion.
Industry Challenges
- IP6K9K sealing expertise scarcity:Ingress protection at high-pressure wash ratings demands specialized automotive sealing engineering that outpaces available talent pools.
- Legacy CAN bus integration friction:Digital camera outputs must interface with existing vehicle networks without full electrical architecture redesigns.
- Multi-regional certification parallelism:Engineering teams must maintain simultaneous homologation tracks for NHTSA, UN ECE, and Japan MLIT type approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side View Camera System Market |
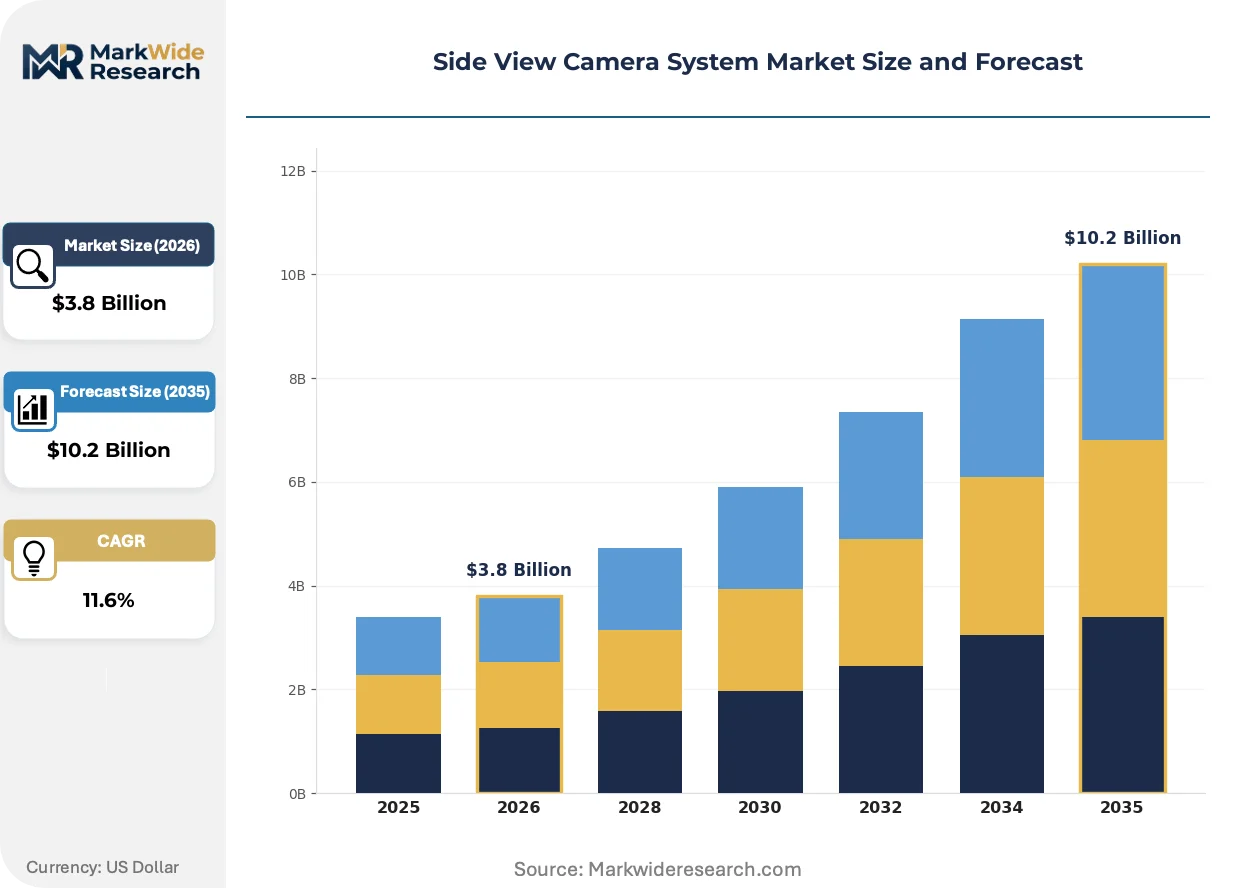
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Cameras, 360-Degree Cameras, Night Vision Cameras, Remote Cameras Technology: Analog, Digital, Wireless, Fiber Optic End User: OEMs, Aftermarket Suppliers, Fleet Operators, Autonomous Vehicles Installation: Integrated, Standalone, Retrofit, Factory-Installed |
| Companies Covered | Hyundai Mobis, Continental AG, Valeo, Robert Bosch, Denso Corporation, Magna International, Samvardhana Motherson, Stoneridge, Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side View Camera System Market Emerging Trajectories
Processing architectures are migrating from distributed modules toward centralized domain controllers, compressing hardware diversity and reshaping supplier value capture in side view visibility systems.
High-dynamic-range CMOS sensors with local tone mapping are consolidating image-processing steps previously handled by separate ISP chips. Tier 1 suppliers integrate these sensors into single-module designs for European premium OEMs. This consolidation eliminates discrete processing boards, reducing housing volume and wiring complexity while improving thermal reliability.
NHTSA's updated Federal Motor Vehicle Safety Standards now explicitly accommodate camera-based visibility systems as mirror replacements, removing interpretive ambiguity that delayed OEM submissions. The regulatory revision forces suppliers to maintain dual-validation protocols for US and UN ECE testing regimes. Heavy-duty truck manufacturers face the steepest compliance adaptation as they serve both regulatory jurisdictions with common platforms.
Fleet procurement departments now specify total cost of ownership metrics rather than upfront hardware pricing, weighting fuel savings from aerodynamic drag reduction against camera system premiums. This behavioral pivot favors integrated mirror-replacement enclosures over add-on visibility accessories. German long-haul logistics operators demonstrate the most advanced TCO modeling, incorporating driver fatigue and accident liability into camera system valuation frameworks.
Side View Camera System Market Segmentation
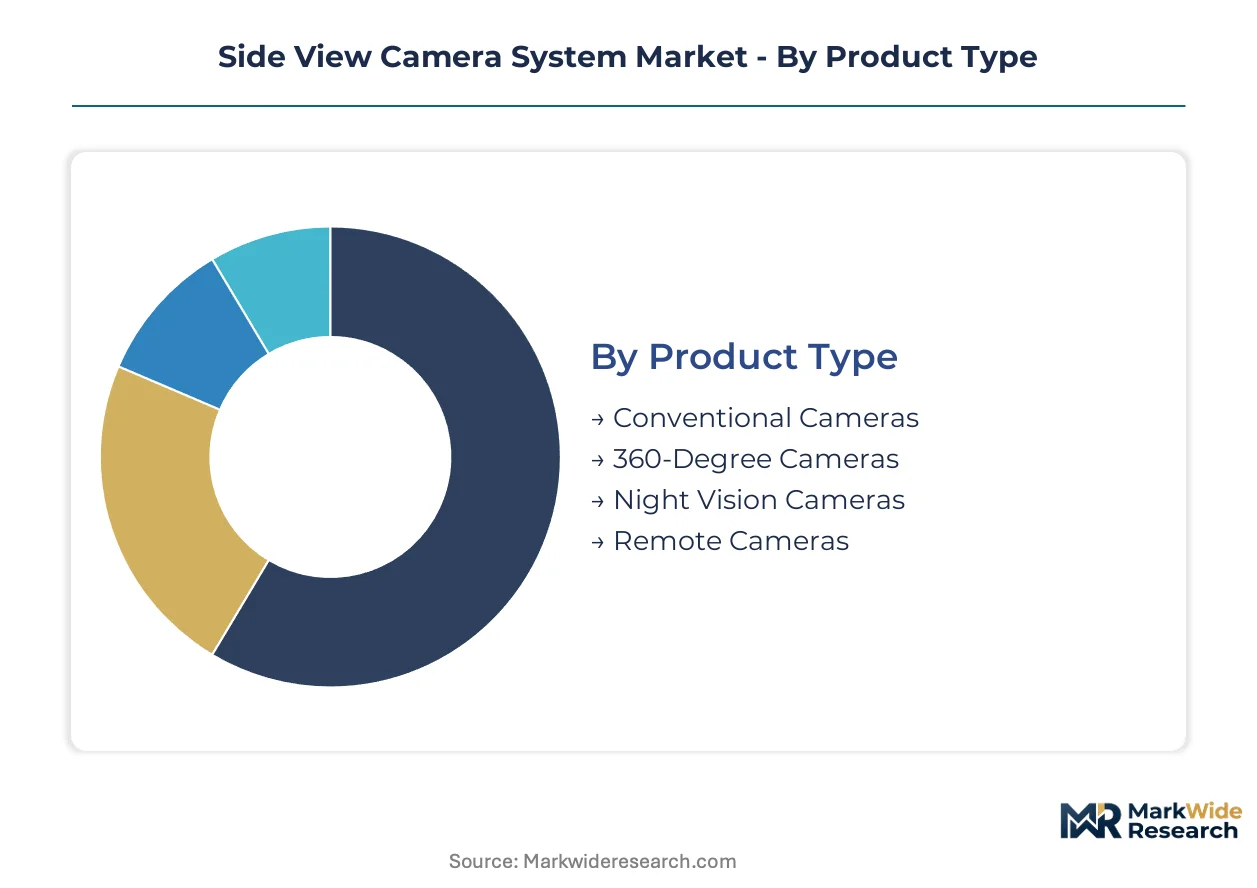
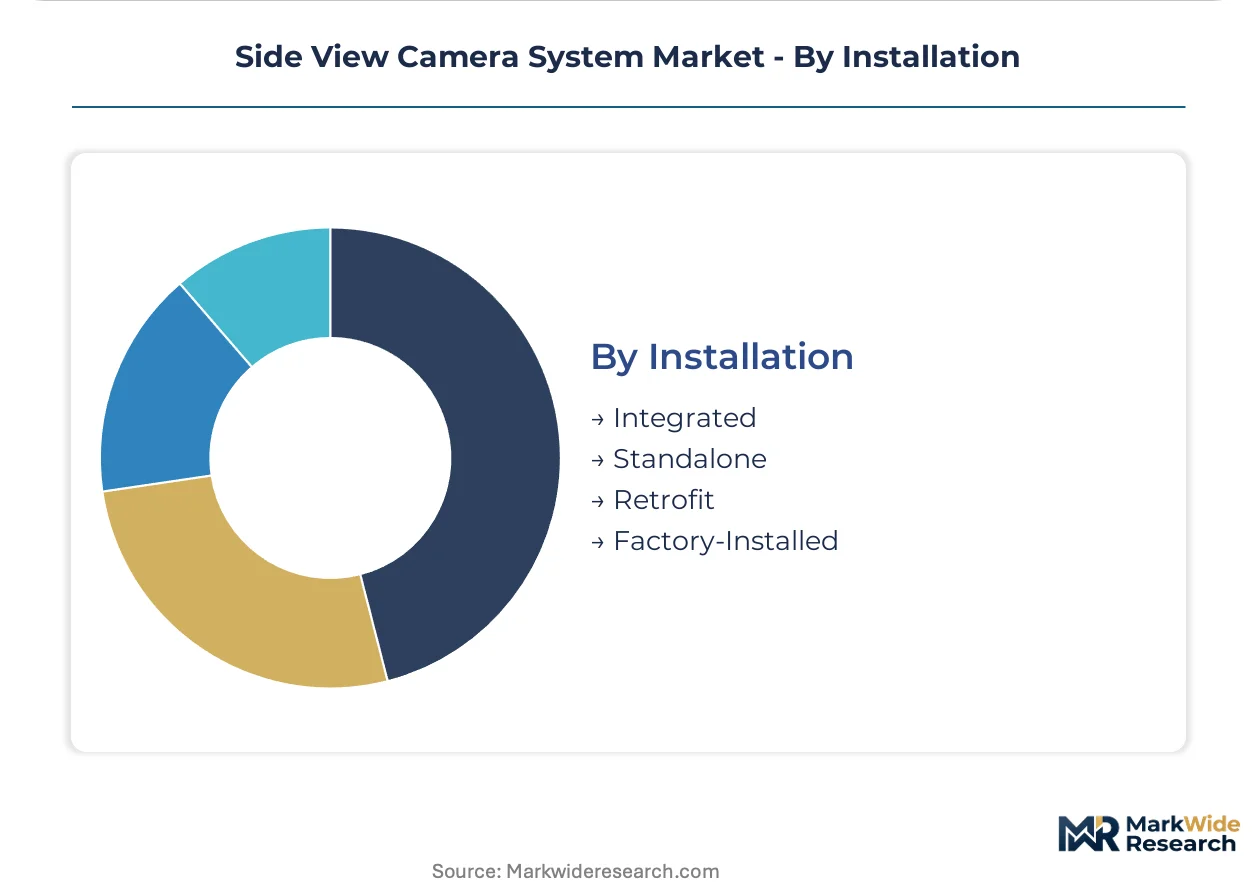
Side view camera system procurement splits sharply between factory-integrated platforms and retrofit installations, with technology choices determining thermal budgets, wiring complexity, and regulatory compliance pathways across vehicle programs.
Product Type:
Volume concentrates in single-view modules while premium growth clusters in multi-camera architectures.
- 360-Degree Cameras:Multi-sensor arrays feed unified processing chains, consolidating four to six sight lines into single-domain controllers. German long-haul fleets and Japanese premium OEMs specify these for surround-view liability reduction in tight maneuvering scenarios. Expanding most quickly as autonomous vehicle developers mandate redundant coverage without mirror occlusion.
- Conventional Cameras:Single-view modules with 60-120 degree fields of view dominate current installed base, operating at IP6K9K ratings with HDR sensors for glare suppression. North American commercial truck operators specify these for NHTSA compliance at lowest unit cost, though aerodynamic gains remain partial versus full mirror-replacement enclosures.
- Night Vision Cameras:Infrared-augmented modules for low-illumination commercial routes.
- Remote Cameras:Detached sensor heads with centralized processing for articulated vehicle configurations.
Today's leader: Conventional Cameras. Tomorrow's challenger: 360-Degree Cameras.
Technology:
Signal transmission architecture determines electromagnetic resilience and cable weight penalties.
- Digital:LVDS and Ethernet-based protocols dominate European OEM programs, enabling 2+ megapixel streams with local tone mapping on HDR CMOS sensors. Tier 1 suppliers compress module housings by eliminating discrete ISP boards, though legacy CAN bus integration demands protocol bridges that add latency.
- Fiber Optic:Heavy-duty mining and construction fleets in Germany and the United States specify glass-fiber links for immunity to electromagnetic interference from high-voltage drivetrains. Premium pricing holds where operational uptime justifies cable cost premiums.
- Analog:Cost-sensitive retrofit channels in emerging markets.
- Wireless:Provisional deployments in specialty vehicle applications.
Digital architectures capture current volume leadership. Fiber Optic transmission commands the steepest expansion trajectory in heavy-duty electrification.
End User:
Procurement authority separates specification control from installation execution.
- OEMs:Factory integration programs in Germany, Japan, and the United States define performance benchmarks and homologation requirements. Valeo and Continental AG anchor supply relationships through aerodynamic housing co-design and in-house semiconductor sourcing respectively.
- Autonomous Vehicles:Self-driving truck developers and robotaxi operators require redundant side visibility without mirror-induced sensor occlusion, driving demand for camera modules with deterministic latency and functional safety certification.
- Fleet Operators:Long-haul logistics departments in Germany apply total cost of ownership modeling that weights fuel savings against camera premiums.
- Aftermarket Suppliers:Retrofit channel serving cost-sensitive segments.
OEMs set current technology roadmaps. Autonomous Vehicles are forcing latency and redundancy specifications that reshape module design.
Installation:
Mounting approach determines aerodynamic benefit capture and regulatory compliance burden.
- Factory-Installed:Mirror-replacement enclosures integrated at vehicle assembly capture full drag reduction for electric range extension. UN ECE R46 and NHTSA type-approval requirements force dual-validation protocols that favor Tier 1 suppliers with homologation expertise.
- Integrated:Camera modules built into body panels during vehicle design phase.
- Standalone:Add-on visibility accessories without aerodynamic housing integration.
- Retrofit:Post-assembly installation for existing fleet assets.
Factory-Installed integration delivers maximum aerodynamic value. Retrofit channels serve fleet refresh cycles without platform redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor around Stuttgart anchors side view camera system development, with OEM integration programs and Tier 1 supplier clusters driving regulatory alignment and aerodynamic enclosure innovation across European platforms.
United States
Commercial truck manufacturers in Michigan and Ohio accelerate factory-installed camera adoption for NHTSA compliance and electric range extension. NHTSA updated Federal Motor Vehicle Safety Standards explicitly accommodate camera-based mirror replacements, removing interpretive barriers that delayed OEM submissions. Detroit-area engineering centers coordinate validation protocols for heavy-duty platforms serving dual US-European markets.
Germany
Long-haul logistics operators in Bavaria and Baden-Württemberg apply total cost of ownership modeling that weights fuel savings from aerodynamic drag reduction against camera system premiums. UN ECE R46 permits camera systems as legal mirror alternatives, unlocking factory integration at premium automotive platforms. Stuttgart-based Tier 1 suppliers co-design aerodynamic housings with OEM aerodynamics teams.
Japan
Premium OEMs in Aichi Prefecture integrate side view cameras into electric vehicle architectures for domestic and export programs. The Ministry of Land, Infrastructure, Transport and Tourism aligned type-approval with UN ECE R46 standards, opening integration pathways previously blocked by regulatory divergence. Nagoya-area manufacturing clusters specialize in HDR sensor module assembly for glare suppression.
China
Electric vehicle manufacturers in Shanghai and Shenzhen specify camera-based visibility systems for aerodynamic optimization and autonomous driving sensor redundancy. MIIT certification requirements for intelligent connected vehicles incorporate camera-based mirror replacement provisions. Yangtze River Delta component suppliers scale digital transmission module production for domestic OEM programs.
South Korea
Hyundai Motor Group affiliates in Gyeonggi Province develop integrated camera-display architectures for next-generation electric platforms. KSA homologation standards for mirror-replacement systems advance in parallel with UN ECE frameworks. Seoul-area electronics clusters supply high-dynamic-range CMOS sensors and domain controller semiconductors.
Side View Camera System Market Vendor Landscape
Technology licensing dominates the current landscape as Tier 1 suppliers consolidate image-processing IP and transmission protocols. The vendor base organizes around three strategic archetypes: diversified automotive electronics conglomerates with in-house semiconductor sourcing, specialized visibility system houses with aerodynamic enclosure expertise, and autonomous vehicle technology providers requiring deterministic latency certification. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers securing long-term OEM program commitments and co-development agreements.
Among diversified automotive electronics conglomerates, Continental AG and Robert Bosch exemplify the integrated technology platform archetype, combining proprietary image-processing capabilities with broad OEM relationship networks. Valeo occupies a distinct position within the specialized visibility system tier, anchoring supply relationships through aerodynamic housing co-design expertise. Denso Corporation represents the Asia-Pacific engineering center model, linking Japanese OEM integration programs with sensor module manufacturing scale. Hyundai Mobis sits within the captive supply structure, supporting affiliated OEM platform development with dedicated camera system roadmaps.
| Leading Market Players |
|---|
| Hyundai Mobis |
| Continental AG |
| Valeo |
| Robert Bosch |
| Denso Corporation |
| Magna International |
| Samvardhana Motherson |
| Stoneridge |
| Aptiv PLC |
| Others |
Supply Flow & Price Mechanics
Silicon carbide wafer price volatility cascades through module assembly tiers, compressing margins at integrated Tier 1 suppliers while amplifying cost spreads between premium mirror-replacement enclosures and economy-grade retrofit modules. NHTSA and UN ECE R46 certification requirements stratify procurement pools, with OEM factory-installed programs absorbing substrate premiums through aerodynamic value capture while aftermarket channels face acute price elasticity.
Pricing Analysis
Input-cost pass-through from semiconductor substrates and HDR sensor modules drives contract renegotiation cycles across European OEM programs. Pricing stratifies across premium mirror-replacement enclosures, standard digital camera modules, and economy analog retrofit tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-tier modules is intensifying because silicon carbide sourcing competition from adjacent power electronics sectors squeezes supplier margins. Fleet operators in Germany demonstrate lowest price sensitivity due to total cost of ownership modeling, while emerging market retrofit channels exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese OEMs mandate multi-supplier qualification for HDR CMOS sensors and domain controller semiconductors, fragmenting procurement authority across Tier 1 engineering centers. Manufacturing concentrates in Germany, Japan, and South Korea for precision optical assemblies, with China scaling digital transmission module production. Supply chains draw from silicon carbide substrates, high-dynamic-range image sensors, and aerodynamic housing composites as critical inputs. Single-source vulnerability in specialized IP6K9K sealing engineering creates qualification bottlenecks. Distribution runs through captive OEM supply agreements and authorized Tier 1 distribution networks serving fleet retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in side view camera systems rests on silicon carbide cost-down curves and the shift toward premium mirror-replacement enclosures that capture aerodynamic value. HDR sensor integration and centralized domain controller architectures compress hardware diversity while elevating software content premiums.
For Market Incumbents: Deepen in-house semiconductor sourcing capabilities to insulate module margins from silicon carbide price volatility, mirroring Continental AG's captive substrate strategy. Secure long-term aerodynamic housing co-development agreements with German and Japanese OEMs to lock out specialized visibility system competitors. Prioritize IP6K9K sealing engineering talent acquisition as qualification bottlenecks intensify.
For New Entrants and Emerging Players: Begin with heavy-duty fiber optic transmission architectures for mining and construction fleets in Germany and the United States, where electromagnetic interference resistance commands premium pricing and incumbent coverage remains thin. Target autonomous vehicle developer procurement channels with deterministic latency certification as the most penetrable entry point. Pursue direct engineering partnerships with self-driving truck programs rather than OEM supply chain insertion.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized visibility system houses possessing aerodynamic enclosure co-design expertise and UN ECE R46 homologation track records. Long-term viability favors suppliers with simultaneous NHTSA, UN ECE, and Japan MLIT certification capabilities across the 5-10 year regulatory convergence window. Watch for divergence in regional homologation timelines as the primary inflection signal for platform standardization risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | In-house sourcing of power electronics substrates insulates Continental AG from adjacent sector demand spikes. |
| Aerodynamic Housing Co-Design | Valeo's mirror-replacement enclosures capture full drag reduction value for electric vehicle range extension. |
| 360-Degree Camera Consolidation | Multi-sensor architectures reduce per-vehicle wiring weight for German long-haul logistics operators. |
| Fiber Optic Transmission Deployment | Heavy-duty fleets specify glass-fiber links for immunity to high-voltage drivetrain interference. |
| Deterministic Latency Certification | Autonomous vehicle developers mandate redundant side visibility without mirror-induced sensor occlusion. |
Methodological Framework
Multiple input streams — OEM platform engineering interviews, Tier 1 supplier procurement discussions, fleet operator TCO modeling sessions, and regulatory affairs consultations — were reconciled against secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, UN ECE R46 type-approval databases, Japan MLIT certification records, and vehicle production registration data. Bottom-up module shipment estimates and top-down OEM program value analysis were triangulated to constrain forecast variance.
Historical adoption curves for mirror-replacement systems were cross-referenced against panel input from autonomous vehicle developers and commercial fleet electrification roadmaps. Segmentation modeling spanned product type, transmission technology, end-user procurement authority, and installation approach across the projection horizon. CAGRs were derived from installed base replacement cycles, regulatory approval timelines, and aerodynamic value capture elasticities specific to electric commercial vehicle platforms.
Several conditions sit outside the modeled scope, including potential NHTSA-UN ECE regulatory divergence, silicon carbide supply disruptions from adjacent power electronics sectors, and autonomous vehicle deployment delays. Forecasts reflect assumptions about homologation timeline convergence and HDR sensor cost-down trajectories. Deviation in regional certification parallelism would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Acoustic Cameras Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Gel Imaging Documentation Market
Imaging
Digital Image Processing Market
Imaging
Cinematographic Camera Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Photoacoustic Microscope Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Camera with Flip Screen Market
Imaging
Europe Image Sensors Market
Imaging
Ent Cameras Market
Imaging
Hyperspectral Imaging Market
Imaging
Global Microbolometer Market
Imaging
Global Automotive Imaging Market
Imaging
Semiconductor Microscopes Market