
 Industrial Metrology Market | 2026-2036
Industrial Metrology Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Metrology Market Analysis
Automotive OEMs is bifurcating industrial metrology demand away from traditional machinery builders as electric vehicle battery pack dimensional tolerances tighten. KLA Corporation dominates semiconductor wafer inspection metrology with proprietary optical architectures. Hexagon AB anchors its position through backward integration into metrology software ecosystems. Nikon Corporation differentiates via ultrahigh-precision optical systems serving lithography-adjacent measurement tasks.
Industrial metrology encompasses the science of measurement applied to manufacturing processes, employing coordinate measuring machines with sub-micron positional accuracy, laser interferometry, and structured-light triangulation to verify geometric dimensioning and tolerancing against design specifications. Its primary purpose is to reduce process variation, prevent defect propagation, and certify compliance with customer engineering standards across production environments. Coordinate measuring machines retain the largest installed base but face margin compression as optical measurement systems capture share in electronics and medical device inspection. Non-contact measurement technology leads growth velocity, driven by throughput advantages in fragile-component and soft-material applications where tactile probing risks damage.
FDA enforces process analytical technology guidelines that mandate in-line metrology for pharmaceutical manufacturing, while ISO 17025 accreditation requirements shape third-party calibration laboratory competitiveness across supplier networks. The EU AI Act introduces conformity assessment obligations for autonomous measurement systems, compelling vendors to document algorithmic traceability. Stakeholders must weigh capital deployment between incremental CMM upgrades and leapfrog investments in multisensor optical platforms before regulatory timelines harden compliance costs.
Market Dynamics
Optical metrology systems are fragmenting the installed base of coordinate measuring machines as semiconductor and medical device manufacturers prioritize throughput over tactile precision. The EU AI Act's conformity assessment obligations for autonomous measurement systems are forcing vendors to rearchitect software validation protocols before enforcement timelines harden.
Growth Catalysts
- ISO 17025 Traceability Mandates:Third-party calibration laboratories in Germany's precision engineering corridor are upgrading protocol infrastructure to retain supplier network accreditation. Equipment procurement from machine tool builders is accelerating as a result.
- EV Battery Dimensional Verification:Automotive OEMs are deploying in-line metrology stations for pouch cell and cylindrical cell stack alignment. Tighter tolerances on thermal interface materials are driving non-contact measurement adoption.
- FDA Process Analytical Technology:Pharmaceutical manufacturers are embedding laser interferometry and structured-light triangulation into continuous manufacturing lines. In-line geometric verification is replacing offline batch sampling for compliance documentation.
Market Restraints
- High-Precision Granite Substrate Costs:Coordinate measuring machine frame production depends on vibration-dampening mineral casting supply concentrated in Bavaria and Baden-Württemberg. Input cost volatility is compressing margins for mid-tier equipment vendors.
- Optical Component Supply Concentration:Ultrahigh-precision lens assemblies for lithography-adjacent measurement tasks rely on Japanese and German specialty glass suppliers. Geopolitical friction is extending lead times for multisensor platform manufacturers.
- EU AI Act Algorithmic Documentation:Autonomous measurement systems face conformity assessment friction as vendors struggle to document decision traceability for machine learning-based defect classification. Compliance timeline uncertainty is freezing capital deployment.
Strategic Opportunities
- India Pharmaceutical Manufacturing Expansion:CDSCO's alignment with FDA process analytical technology guidelines is creating demand for in-line metrology in active pharmaceutical ingredient production. Domestic calibration laboratory accreditation remains underpenetrated.
- Multisensor Optical Platform Convergence:Structured-light triangulation combined with laser interferometry is enabling single-station verification of soft-material medical devices. Fragile-component inspection throughput is improving by an order of magnitude.
- China NMPA Medical Device Traceability:The regulator's unique device identification implementation is mandating dimensional verification documentation for implantable devices. Domestic metrology service providers are capturing outsourced quality control spend.
Industry Challenges
- Sub-Micron Calibration Technician Scarcity:Geometric dimensioning and tolerancing expertise combined with optical system alignment skill is concentrating among aging workforces in Stuttgart and Aachen. Training pipeline gaps are extending commissioning timelines.
- Legacy CMM Software Integration:Brownfield manufacturing environments running proprietary coordinate measuring machine control architectures face protocol incompatibility with modern optical data acquisition systems. Retrofit engineering costs are eroding upgrade project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Metrology Market |
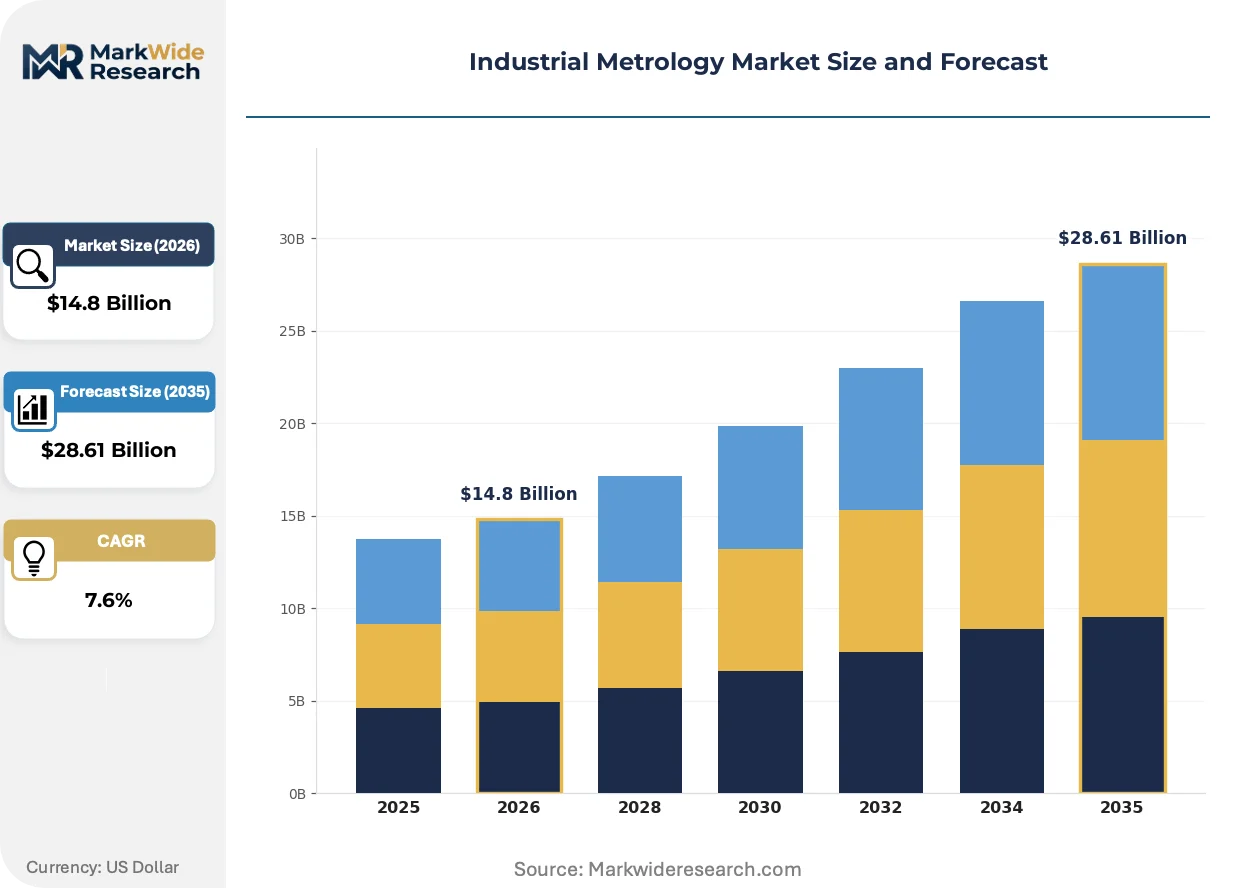
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coordinate Measuring Machines, Optical Measurement Systems, 3D Scanners, Laser Scanners Technology: Contact Measurement, Non-Contact Measurement, Digital Measurement, Optical Measurement End User: Aerospace, Automotive, Electronics, Machinery Application: Quality Control, Precision Measurement, Research & Development, Production |
| Companies Covered | KLA Corporation, Nikon Corporation, Hexagon AB, Renishaw plc, FARO Technologies, Carl Zeiss AG, Mitutoyo Corporation, Jenoptik AG, KEYENCE CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Metrology Market Emerging Trajectories
Measurement modality convergence is compressing the traditional separation between tactile probing and optical acquisition, while regulatory algorithmic transparency mandates are redefining software architecture requirements across vendor portfolios.
Structured-light triangulation is fragmenting the coordinate measuring machine market's historical dominance in electronics inspection. Semiconductor packaging manufacturers are adopting blue-light optical scanners for wafer-level chip scale package verification at cycle times incompatible with tactile probing. The technology is fragmenting equipment vendor revenue pools as pure-play optical specialists capture share from incumbent CMM providers.
The EU AI Act's conformity assessment framework for autonomous measurement systems is mandating algorithmic traceability documentation for machine learning-based defect classification. Vendors must now maintain version-controlled training data records and decision audit trails for regulatory submission. German precision engineering clusters are responding by embedding compliance engineering teams within product development organizations ahead of enforcement deadlines.
After-sales service unbundling is disrupting traditional equipment vendor revenue models. Automotive OEMs in Michigan and South Carolina are procuring metrology hardware separately from calibration and software maintenance contracts, compressing vendor lifetime value per unit. Third-party metrology service providers are capturing recurring revenue streams that previously accrued to original equipment manufacturers.
Industrial Metrology Market Segmentation
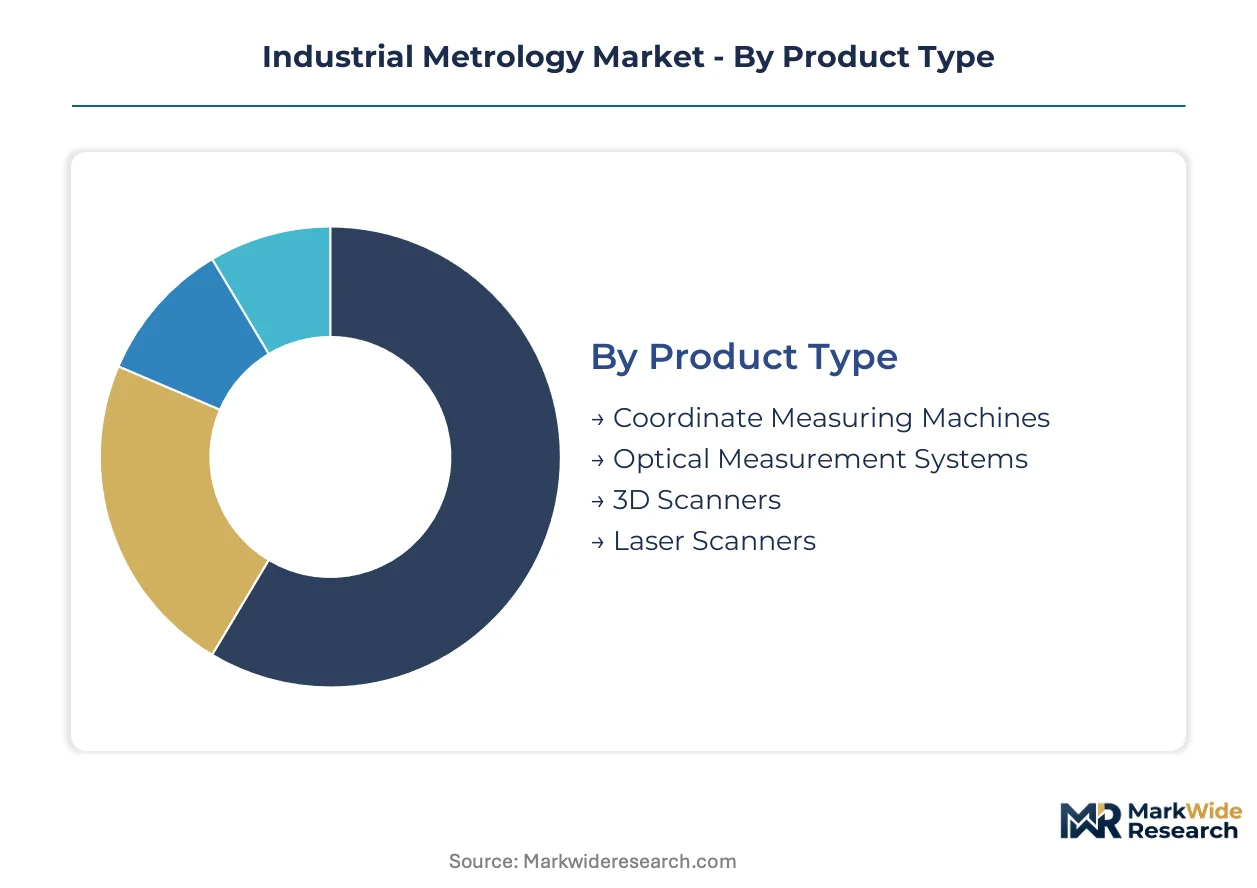
Segmentation in industrial metrology reveals how substitution dynamics between tactile and optical modalities are redistributing capital deployment across equipment categories. Procurement patterns diverge sharply between legacy manufacturing environments and greenfield electronics assembly where throughput requirements dominate specification decisions.
Product Type:
Substitution pressure from non-contact alternatives is fragmenting the historical dominance of tactile measurement platforms across precision manufacturing sectors.
- Coordinate Measuring Machines:Granite-framed tactile probing systems deliver sub-micron positional accuracy for geometric dimensioning verification. Demand concentrates in Germany's precision engineering corridor where machine tool builders anchor equipment procurement for legacy automotive powertrain manufacturing.
- Optical Measurement Systems:Structured-light triangulation and laser interferometry architectures enable fragile-component inspection without surface contact. Semiconductor packaging manufacturers in South Korea and Taiwan are displacing CMM stations with blue-light optical scanners for wafer-level chip scale package verification.
- 3D Scanners:Portable articulated-arm systems with integrated laser triangulation heads support reverse engineering workflows in aerospace MRO facilities.
- Laser Scanners:Long-range time-of-flight units capture large-scale dimensional data for construction machinery frame alignment and shipbuilding applications.
Coordinate Measuring Machines retain volume leadership; Optical Measurement Systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium optical architectures from commodity contact probes, with digital integration commanding intermediate pricing positions.
- Contact Measurement:Tactile probing with ruby or silicon nitride styli remains the reference standard for hard-surface dimensional verification. Automotive OEMs in Michigan and South Carolina maintain installed bases for cylinder block and transmission housing inspection despite slower cycle times.
- Non-Contact Measurement:Optical triangulation and confocal chromatic sensing eliminate surface damage risk for soft materials and fragile electronics. Medical device manufacturers in Massachusetts and Minnesota are prioritizing these systems for catheter and implantable component verification.
- Digital Measurement:Software-defined metrology platforms with open architecture interfaces enable retrofit integration with legacy CMM hardware.
- Optical Measurement:Lithography-adjacent interferometric systems serve semiconductor wafer inspection with nanometer-scale resolution requirements.
Contact Measurement retains volume leadership; Non-Contact Measurement commands the steepest expansion curve.
End User:
Application maturity varies dramatically, with electronics manufacturing driving the most aggressive technology refresh cycles while aerospace maintains the longest equipment depreciation schedules.
- Aerospace:Large-volume gantry CMMs and laser trackers verify airframe assembly tolerances across multi-meter measurement envelopes. Boeing and Airbus tier-one suppliers in Wichita and Toulouse anchor demand for high-precision granite-substrate systems with extended calibration intervals.
- Automotive:EV battery pack dimensional verification is bifurcating demand between traditional powertrain metrology and new pouch cell stack alignment stations. OEMs are deploying in-line optical measurement for thermal interface material placement verification.
- Electronics:Semiconductor packaging and PCB assembly drive the fastest adoption of multisensor optical platforms with sub-micron throughput requirements.
- Machinery:General industrial equipment manufacturers prioritize cost-efficient manual CMMs for batch inspection of machined components.
Automotive retains volume leadership; Electronics holds the steepest expansion curve.
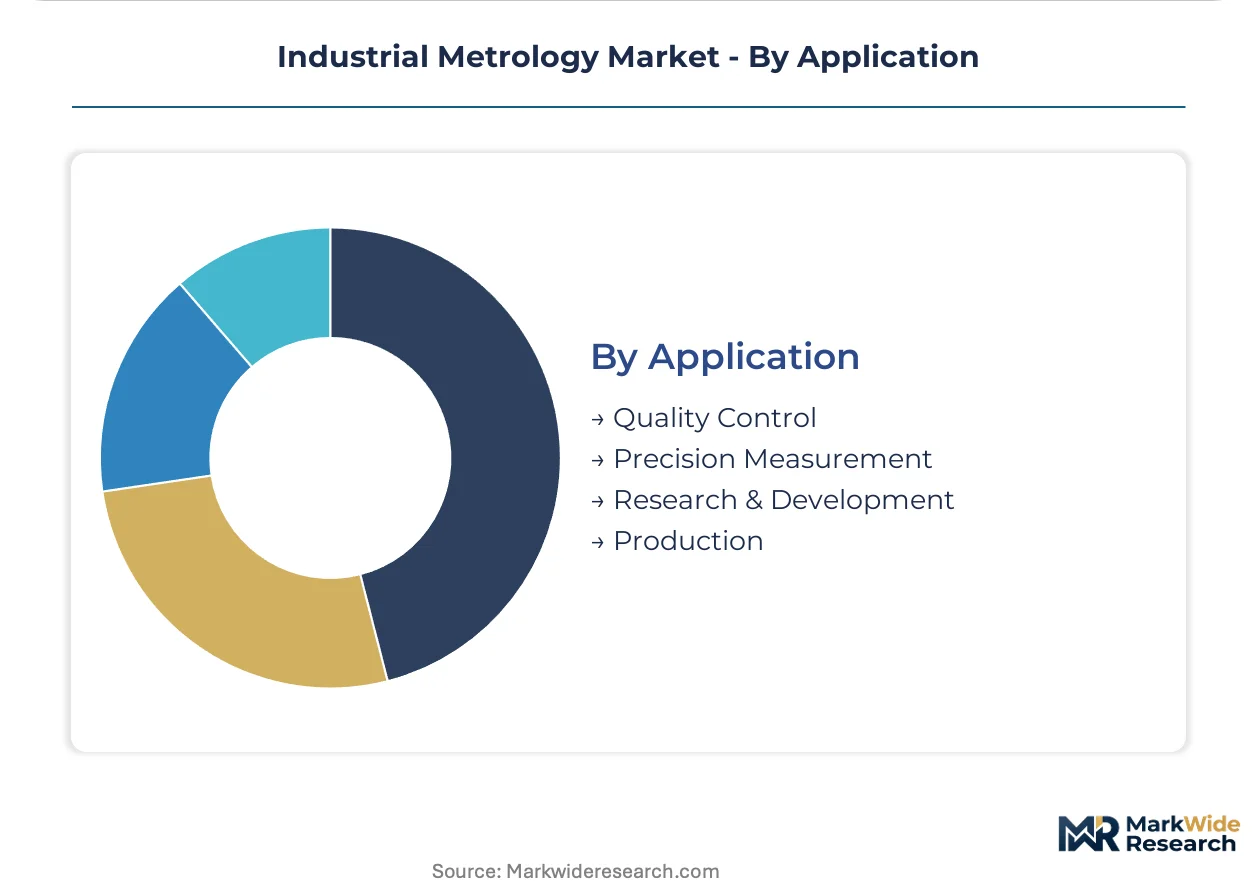
Application:
Customer type separation distinguishes capital-intensive in-line production integration from lower-commitment laboratory and R&D procurement patterns.
- Quality Control:Statistical process control integration mandates real-time dimensional feedback for manufacturing line adjustment. Pharmaceutical manufacturers under FDA process analytical technology guidelines are embedding laser interferometry into continuous manufacturing lines for compliance documentation.
- Precision Measurement:Reference-level calibration and gauge R&R studies require NIST-traceable artifacts and controlled-environment laboratory conditions. Germany's DAkkS-accredited laboratories anchor demand for premium coordinate measuring machines with expanded uncertainty budgets.
- Research & Development:Flexible measurement configurations support prototype iteration and design validation before production tooling commitment.
- Production:Shop-floor hardened systems with automated part handling maximize throughput in high-volume manufacturing environments.
Quality Control retains volume leadership; Precision Measurement holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision metrology equipment to automotive manufacturing clusters across the United States, China, and South Korea. Equipment flows concentrate through Stuttgart and Aachen engineering corridors. Calibration protocol upgrades follow ISO 17025 traceability mandates in buyer markets.
United States
Automotive OEMs in Michigan and South Carolina deploy in-line metrology for EV battery dimensional verification. FDA process analytical technology guidelines mandate laser interferometry integration in pharmaceutical continuous manufacturing. Boston and Minneapolis medical device clusters anchor non-contact measurement system procurement for catheter inspection.
Germany
Machine tool builders in Bavaria and Baden-Württemberg anchor metrology equipment procurement for precision engineering supply chains. EU AI Act conformity assessment obligations compel vendors to document algorithmic traceability for autonomous measurement systems. Stuttgart's DAkkS-accredited calibration laboratories upgrade protocol infrastructure to retain supplier network accreditation.
China
NMPA medical device traceability mandates drive dimensional verification documentation for implantable devices in Yangtze River Delta manufacturing zones. Domestic metrology service providers capture outsourced quality control spend from multinational device manufacturers. Shanghai and Suzhou electronics assembly clusters adopt blue-light optical scanners for semiconductor packaging verification.
Japan
Ultrahigh-precision lens assemblies for lithography-adjacent measurement tasks supply semiconductor wafer inspection equipment globally. METI industrial standards shape domestic metrology software validation protocols. Nagoya automotive suppliers maintain coordinate measuring machine installed bases for powertrain component verification despite optical system substitution pressure.
South Korea
Semiconductor packaging manufacturers in Suwon and Hwaseong displace CMM stations with optical measurement platforms for wafer-level chip scale package verification. MFDS alignment with international pharmaceutical manufacturing standards creates demand for in-line geometric verification systems. Domestic equipment vendors face lead time extensions for specialty glass component procurement.
Industrial Metrology Market Vendor Landscape
Player mix skews toward diversified precision equipment conglomerates with captive metrology divisions. Market structure exhibits moderate concentration around optical system specialists and tactile measurement incumbents. Three archetypes dominate: semiconductor-focused optical architects, backward-integrated software-platform vendors, and precision optics heritage manufacturers. Competitive moves center on multisensor platform convergence and calibration service unbundling.
Within the optical architecture tier, KLA Corporation and Nikon Corporation exemplify divergent specialization models. KLA anchors semiconductor wafer inspection positioning through proprietary optical system design. Nikon occupies a heritage-manufacturer position rooted in ultrahigh-precision optical engineering for lithography-adjacent applications. Hexagon AB represents the backward-integration archetype, embedding metrology hardware within software ecosystem control.
| Leading Market Players |
|---|
| KLA Corporation |
| Nikon Corporation |
| Hexagon AB |
| Renishaw plc |
| FARO Technologies |
| Carl Zeiss AG |
| Mitutoyo Corporation |
| Jenoptik AG |
| KEYENCE CORPORATION |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Japanese and German specialty glass foundries shapes both input cost floors and vendor pricing power across optical metrology architectures. Scale economies in ultrahigh-precision lens grinding concentrate margin capture among heritage manufacturers, while mid-tier equipment vendors face compression from granite substrate volatility and optical component lead time extension.
Pricing Analysis
Current-generation multisensor optical platforms command substantial premiums over prior-generation coordinate measuring machines, while next-generation AI-integrated autonomous systems are pricing at contract-only tiers pending EU AI Act conformity clarity. Three-tier pricing structure across premium interferometric systems, standard structured-light platforms, and economy manual CMMs stratifies by certification grade and after-sales bundling. Cost compression in mid-tier optical equipment is intensifying as automotive OEMs unbundle calibration contracts from hardware procurement. Contract manufacturers and machinery builders exhibit highest price sensitivity; semiconductor fabs and DAkkS-accredited calibration laboratories demonstrate lowest.
Supply Chain Analysis
Inventory buffers for ultrahigh-precision lens assemblies have thinned to critical levels, with Japanese and German specialty glass suppliers extending quoted lead times for lithography-grade optical components. Metrology equipment production draws from Bavarian granite casting foundries, Baden-Württemberg precision mechanics clusters, and Nagoya optical glass suppliers. Single-source vulnerability concentrates in vibration-dampening mineral casting supply concentrated in southern Germany. Distribution runs through Stuttgart and Aachen engineering corridors to automotive OEMs in Michigan, pharmaceutical manufacturers in Massachusetts, and semiconductor packaging facilities in Suwon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial metrology demand tracks automotive capital expenditure cycles, with EV battery dimensional verification investment now driving recovery momentum after powertrain metrology contraction. Equipment refresh decisions concentrate around ISO 17025 accreditation deadlines and EU AI Act enforcement timelines.
For Market Incumbents: Compound software ecosystem control through backward integration into metrology data platforms, capturing recurring revenue streams as automotive OEMs unbundle hardware from calibration contracts. Deepen captive supply of ultrahigh-precision optical components to offset Japanese and German specialty glass lead time volatility. Prioritize compliance engineering team embedding ahead of EU AI Act algorithmic documentation mandates. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing expansion, where CDSCO alignment with FDA process analytical technology guidelines outpaces domestic calibration laboratory accreditation capacity. Target multisensor optical platform convergence for soft-material medical device inspection, a white-space application where fragile-component throughput requirements outstrip incumbent capability. Pursue direct hospital system partnerships in Boston and Minneapolis clusters to bypass established distribution channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical architecture specialists with semiconductor wafer inspection exposure over legacy CMM incumbents facing substitution pressure. Five-to-ten year viability hinges on multisensor platform convergence capability and regulatory compliance infrastructure deployment. Monitor EU AI Act conformity assessment timeline clarity as inflection signal for autonomous measurement system capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captures margin from Japanese and German specialty glass supply concentration. |
| Software Ecosystem Control | Locks in recurring revenue as automotive OEMs unbundle calibration contracts. |
| Compliance Engineering Team Embedding | Accelerates EU AI Act algorithmic traceability documentation ahead of enforcement. |
| Multisensor Platform Convergence | Enables single-station verification of soft-material medical devices at order-of-magnitude throughput improvement. |
| Calibration Service Unbundling Defense | Preserves lifetime value per unit as third-party metrology service providers capture recurring streams. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, equipment vendor SEC disclosures, and customs trade data covering precision optical component flows. Primary interviews engaged metrology equipment product managers, automotive OEM quality engineering directors, pharmaceutical manufacturing compliance leads, and DAkkS-accredited calibration laboratory technical directors. Secondary validation drew from FDA process analytical technology guidance documents, EU AI Act conformity assessment frameworks, ISO 17025 accreditation databases, and semiconductor packaging equipment procurement records. Bottom-up equipment shipment analysis triangulates against top-down manufacturing capital expenditure tracking across automotive, electronics, and pharmaceutical end-use sectors.
Segmentation dimensions modeled span product type, measurement technology, end-use industry, and application across the analysis window. Analytical framework incorporates coordinate measuring machine versus optical system substitution dynamics, regulatory compliance timeline impacts on procurement acceleration, and geographic concentration of precision engineering supply chains. CAGRs derive from equipment shipment trajectory analysis combined with capital expenditure elasticity modeling against automotive and semiconductor manufacturing cycle indicators. Forecast inputs include EV battery pack dimensional tolerance evolution and pharmaceutical continuous manufacturing adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained ISO 17025 traceability mandate enforcement and EU AI Act timeline adherence; material deviation in regulatory implementation would warrant model refresh. Specific risk factors include geopolitical friction extending Japanese and German optical component lead times, and sub-micron calibration technician scarcity compressing commissioning capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Density Tester Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Color Meter Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Insulation Testing Instrument Market