
 Air Measuring Equipment Market | 2026-2036
Air Measuring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Measuring Equipment Market Outlook
Pharmaceutical cleanroom operators is rotating procurement priority toward continuous environmental monitoring systems over periodic manual sampling. TSI Incorporated leverages its laser-based particle counting heritage to dominate high-precision pharmaceutical applications. Honeywell International sustains broad channel control across industrial safety portfolios, competing on bundled building automation solutions. Aeroqual specializes in compact ambient monitoring stations, positioning its optical sensor platforms for decentralized air quality networks.
Air measuring equipment encompasses instruments that quantify physical and chemical properties of gaseous media, including particle concentration, flow velocity, humidity, and gas composition, typically achieving detection thresholds from parts-per-billion to milligram-per-cubic-meter scales depending on sensing modality. These systems serve critical functions in regulatory compliance, process control, and occupational health protection across manufacturing and environmental management. Gas analyzers and particulate monitors capture the dominant share of current revenue, with electrochemical and infrared technologies anchoring mature industrial segments while laser-based optical methods are displacing legacy approaches in emission testing and workplace safety applications where real-time data transmission is becoming standard.
The U.S. FDA and OSHA shape domestic product standards through aseptic processing guidelines and permissible exposure limit enforcement, while the EPA's ambient monitoring requirements drive Environmental Agencies procurement of certified reference-grade instrumentation. In Europe, the EU Green Deal and REACH compliance obligations are tightening emission measurement protocols, forcing industrial end users to upgrade analyzer accuracy specifications. Stakeholders must decide whether to anchor R&D spending on multi-parameter sensor fusion or defend position through modular platform architectures that simplify retrofit into existing building management systems.
Market Dynamics
The transition from periodic manual sampling to continuous environmental monitoring is compressing replacement cycles and forcing vendors to rearchitect sensor platforms for real-time data transmission rather than batch reporting.
Growth Catalysts
- EU Green Deal emission protocols:Industrial facilities across Germany and the Netherlands face mandatory upgrades to analyzer accuracy specifications, triggering equipment replacement demand.
- Pharmaceutical cleanroom expansion:Aseptic processing facilities in Singapore and Switzerland are deploying particle counters with integrated airflow mapping for continuous compliance documentation.
- Laser-based optical sensing:This detection modality is penetrating emission testing applications previously served by infrared absorption methods, enabling sub-part-per-billion resolution.
Market Restraints
- Reference-grade sensor supply concentration:High-precision photodetectors and laser diodes depend on specialized Japanese and German component suppliers, creating single-source vulnerability.
- Calibration gas cost volatility:Certified reference mixtures for trace-level analyzers fluctuate with rare gas extraction economics, compressing service margin predictability.
- REACH substance restrictions:Certain electrochemical sensor electrolytes face phase-out timelines, forcing redesigns of established industrial gas detector architectures.
Strategic Opportunities
- Decentralized ambient networks:Compact optical stations are penetrating municipal air quality grids in Australian and Canadian cities where reference-grade stations remain sparse.
- Sensor fusion architectures:Multi-parameter modules combining particulate, gas, and meteorological sensing are opening building automation retrofit opportunities without parallel infrastructure deployment.
- OSHA permissible exposure limit enforcement:Tighter workplace monitoring mandates are expanding rental and subscription service models for industrial hygiene departments.
Industry Challenges
- Metrology talent scarcity:Qualified technicians for gravimetric calibration and interferometer alignment are concentrating in aging workforce pockets across Midwestern US industrial corridors.
- Legacy system integration friction:BACnet and Modbus protocol mismatches between new optical sensors and 1990s-era building management systems extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Measuring Equipment Market |
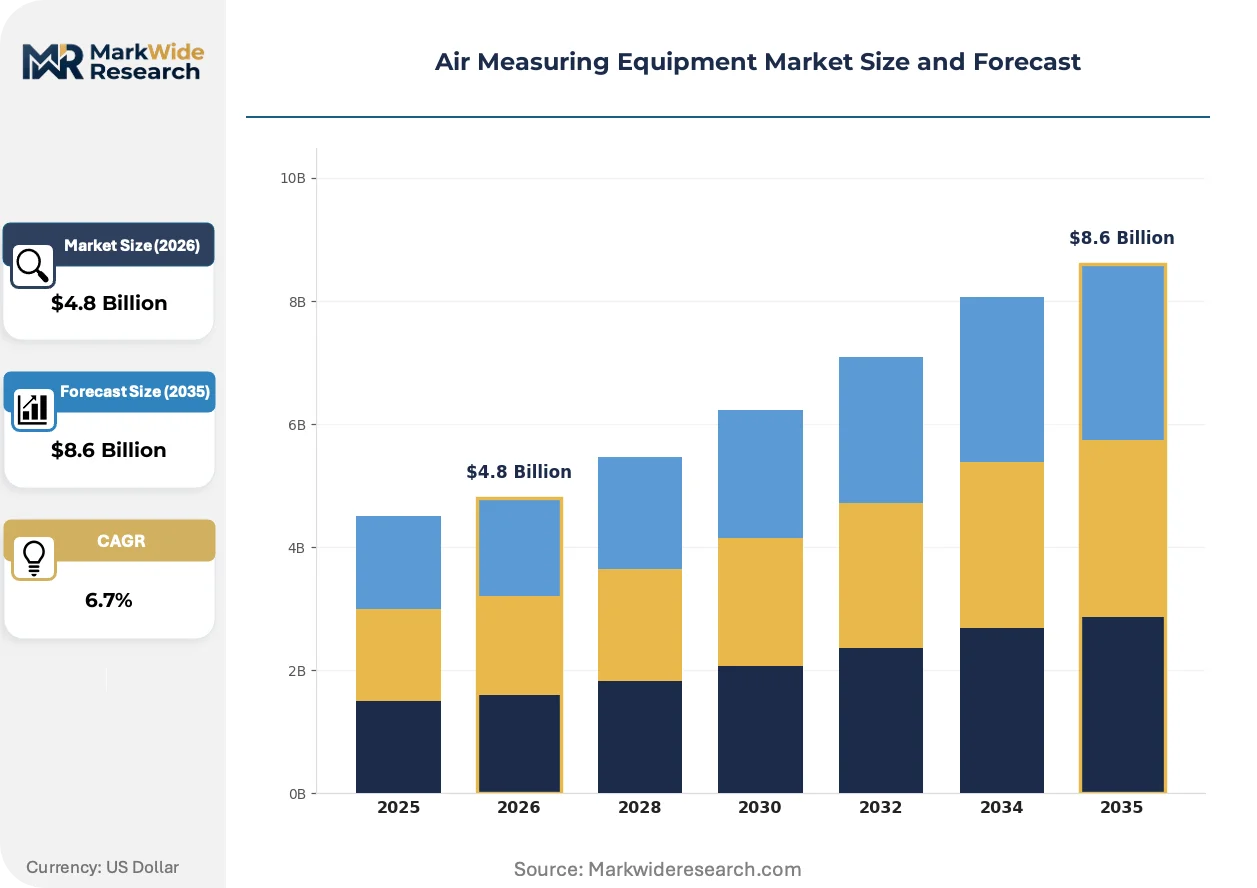
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Particulate Monitors, Flow Meters, Humidity Sensors Technology: Electrochemical, Infrared, Laser, Optical End User: Industrial, Environmental Agencies, Research Institutions, Hospitals Application: Air Quality Monitoring, Emission Testing, Workplace Safety, Indoor Air Quality Assessment |
| Companies Covered | Siemens, Honeywell International, TSI Incorporated, Thermo Fisher Scientific, Testo, Aeroqual, 3M, HORIBA, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Measuring Equipment Market Strategic Shifts
Real-time data architectures are displacing batch-oriented monitoring paradigms across pharmaceutical, environmental, and industrial safety applications. Three converging developments are reshaping competitive positioning.
Tunable diode laser absorption spectroscopy is supplanting conventional infrared bench analyzers in continuous emission monitoring systems. Power generation and chemical processing operators in Texas and Louisiana are deploying these platforms for ammonia and hydrogen chloride detection. The technology is compressing maintenance intervals from quarterly to annual while eliminating consumable reagent costs.
REACH compliance obligations are tightening measurement uncertainty requirements for volatile organic compound reporting. Industrial end-users in Belgium and northern Italy must now demonstrate analyzer performance against certified reference methods rather than manufacturer specifications alone. This is accelerating third-party validation service demand and equipment upgrade timelines.
Pharmaceutical quality departments are unbundling after-sales service from capital equipment procurement. Large molecule manufacturing sites in Massachusetts and North Carolina now contract calibration and certification separately through specialized metrology service providers. This channel fragmentation is compressing OEM service margins while expanding independent laboratory market entry.
Air Measuring Equipment Market Segmentation
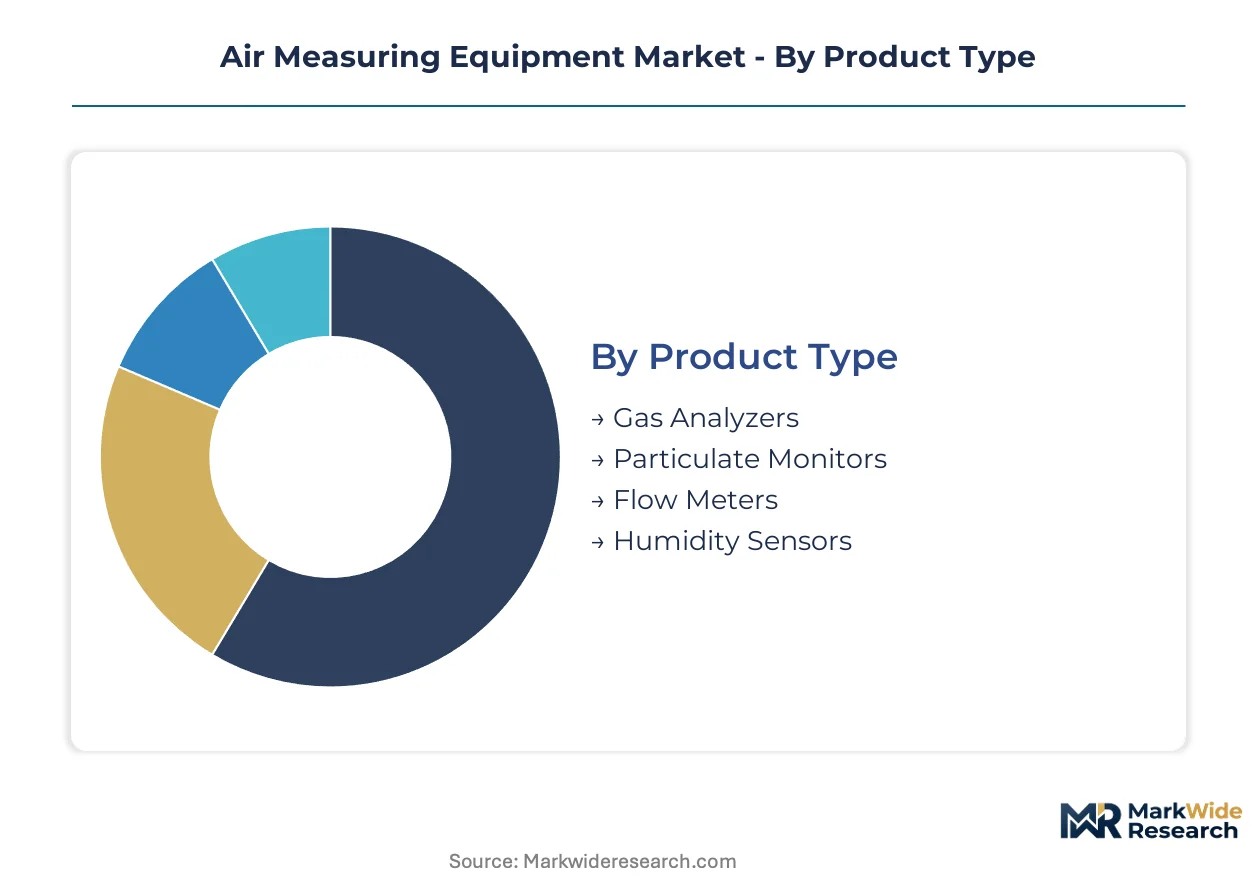
Equipment segmentation in air measuring markets reveals distinct margin architectures. Product type determines baseline pricing power, while technology modality and end-user vertical shape recurring revenue attachment rates.
Product Type:
Margin pools concentrate in instruments requiring certified calibration chains and regulatory documentation.
- Gas Analyzers:These systems quantify chemical composition through electrochemical cells or spectroscopic methods. Demand concentrates in Texas and Louisiana petrochemical corridors where EPA continuous emission monitoring mandates require sub-part-per-billion detection thresholds for ammonia and hydrogen chloride.
- Particulate Monitors:Laser-based optical counters dominate pharmaceutical cleanrooms in Singapore and Switzerland. FDA aseptic processing guidance is tightening validation requirements, forcing replacement of legacy manual sampling equipment with continuous monitoring platforms.
- Flow Meters:Thermal anemometry and ultrasonic variants serve HVAC commissioning and industrial process control.
- Humidity Sensors:Capacitive and resistive polymer technologies anchor building automation retrofits.
The dominant share belongs to Gas Analyzers, while Particulate Monitors is closing the gap fastest.
Technology:
Technology choice determines maintenance cadence and consumable economics, with laser platforms commanding premium positioning.
- Electrochemical:Mature, cost-effective sensing for standard industrial gases. REACH substance restrictions on certain electrolytes are forcing architectural redesigns in established detector lines.
- Infrared:Nondispersive absorption benches serve bulk gas analysis in chemical processing. German and Dutch industrial clusters under EU Green Deal protocols are upgrading accuracy specifications, triggering replacement demand.
- Laser:Tunable diode absorption spectroscopy is displacing infrared methods in emission testing. Power generation operators in Texas are deploying these platforms for annual rather than quarterly maintenance intervals.
- Optical:Compact sensor platforms enable decentralized ambient monitoring networks in Australian and Canadian municipalities.
Laser platforms capture the steepest expansion trajectory as real-time data architectures displace batch-oriented paradigms.
End User:
Customer type dictates procurement modality, with industrial buyers favoring capital purchase and environmental agencies migrating to service contracts.
- Industrial:Petrochemical, pharmaceutical, and manufacturing operators drive volume through compliance-driven replacement cycles. OSHA permissible exposure limit enforcement is expanding rental and subscription service models for industrial hygiene departments.
- Environmental Agencies:EPA ambient monitoring requirements in the US and EU Green Deal obligations in Europe demand certified reference-grade instrumentation. Procurement concentrates in Germany, the Netherlands, and Belgium.
- Research Institutions:Academic and government laboratories require metrological traceability for publication-grade data.
- Hospitals:Infection control departments deploy particle counters for operating theater validation.
Industrial buyers command the dominant share, while Environmental Agencies are gaining share fastest through network expansion mandates.
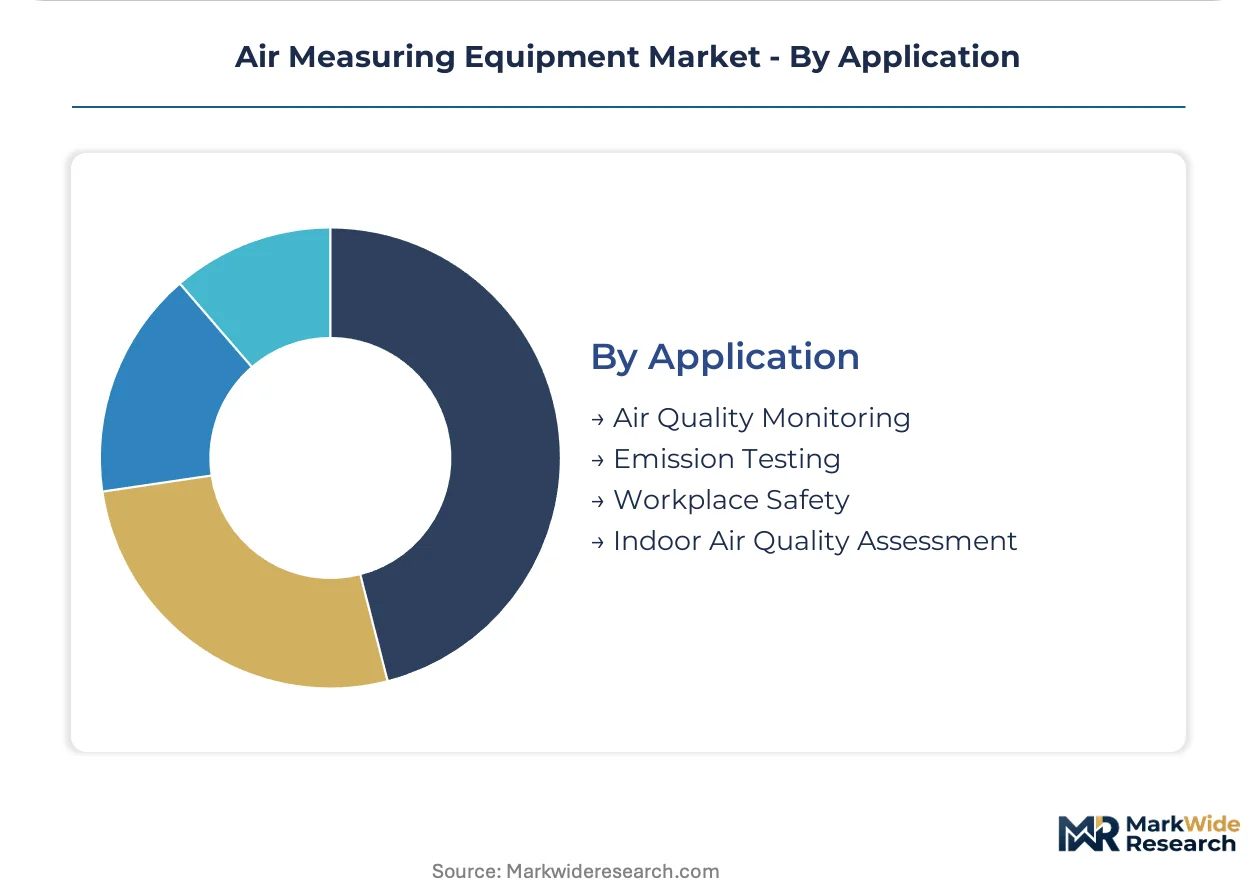
Application:
Application focus determines sensor fusion requirements, with multi-parameter modules opening retrofit opportunities without parallel infrastructure deployment.
- Air Quality Monitoring:Ambient networks in Australian and Canadian cities are adopting compact optical stations where reference-grade stations remain sparse.
- Emission Testing:Continuous monitoring systems in Texas and Louisiana chemical processing are adopting laser-based platforms for ammonia detection. The technology eliminates consumable reagent costs while compressing maintenance intervals.
- Workplace Safety:Industrial hygiene departments face tighter OSHA enforcement, expanding demand for personal and area monitors.
- Indoor Air Quality Assessment:Building automation integration favors modular platforms compatible with BACnet and Modbus protocols.
Air Quality Monitoring holds the dominant share, while Emission Testing is climbing the fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision gas analyzers to Dutch and Belgian industrial facilities facing EU Green Deal compliance deadlines. This trade corridor channels equipment upgrades through the Rhine-Ruhr and Antwerp-Rotterdam port clusters.
United States
Texas and Louisiana petrochemical operators deploy continuous emission monitoring systems for ammonia detection. EPA mandates under the Clean Air Act tighten analyzer accuracy requirements for chemical processing facilities. Houston's Energy Corridor anchors replacement demand as operators retire infrared benches for laser-based platforms.
Germany
Frankfurt and Munich industrial clusters drive replacement cycles for legacy airflow monitors in pharmaceutical cleanrooms. REACH compliance obligations force electrolyte redesigns in established electrochemical detector lines. The Rhine-Main region concentrates metrology service providers supporting calibration chains for export-bound equipment.
Singapore
Aseptic processing facilities deploy particle counters with integrated airflow mapping for continuous compliance documentation. The national pharmaceutical regulator enforces validation standards aligned with FDA aseptic processing guidance. Tuas Biomedical Park anchors procurement concentration for multi-parameter environmental monitoring systems.
Switzerland
Large molecule manufacturing sites in Basel and Zurich unbundle after-sales service from capital equipment procurement. Swissmedic guidance tightens documentation requirements for cleanroom validation. The Basel Area anchors demand for certified reference-grade instrumentation serving contract manufacturing organizations.
Australia
Municipal air quality grids in Sydney and Melbourne adopt compact optical stations where reference-grade stations remain sparse. State environmental protection agencies mandate network expansion under national air quality standards. The Sydney Basin concentrates deployment of decentralized monitoring architectures for urban pollution mapping.
Air Measuring Equipment Market Competitive Environment
Listed leaders compete with private specialists across technology modality and service bundling. The vendor base spans three tiers: diversified conglomerates with building automation portfolios, precision instrument specialists with laser-based platforms, and regional sensor fabricators with cost-optimized offerings. Strategic moves concentrate on sensor fusion architectures and calibration service unbundling rather than horizontal consolidation.
Within the precision instrument tier, TSI Incorporated and Aeroqual exemplify divergent specialization vectors. Honeywell International occupies a position bridging industrial safety and building automation integration. These three anchors represent distinct competitive archetypes: laser-heritage precision, compact optical decentralization, and bundled automation control.
| Leading Market Players |
|---|
| Siemens |
| Honeywell International |
| TSI Incorporated |
| Thermo Fisher Scientific |
| Testo |
| Aeroqual |
| 3M |
| HORIBA |
| Emerson Electric |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in both component access and price visibility for pharmaceutical cleanroom operators facing FDA validation deadlines. These arrangements tether equipment vendors to recurring revenue streams while insulating buyers from spot-market volatility in rare gas reference mixtures.
Pricing Analysis
Current-generation laser-based optical platforms command 40-60% premiums over prior-generation infrared benches, while next-generation tunable diode absorption spectroscopy systems price at additional premiums for maintenance interval compression. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical-grade systems from industrial safety monitors and compact ambient stations. Cost compression in standard-tier electrochemical detectors is intensifying because REACH electrolyte redesigns are forcing R&D recapture. Environmental agencies exhibit lowest price sensitivity due to grant-funded procurement, while municipal air quality departments show highest sensitivity to per-unit capital costs.
Supply Chain Analysis
Extended lead times for high-precision photodetectors and laser diodes now stretch 16-24 weeks, forcing equipment manufacturers to pre-position inventory ahead of regulatory compliance deadlines. Component manufacturing concentrates in Japan and Germany for specialized optical elements, with final assembly distributed across the United States and Switzerland. Rare earth element dependencies for laser gain media and certified reference gas mixtures for calibration chains create single-source vulnerability. Distribution runs through authorized metrology service providers who maintain calibration certification chains for pharmaceutical and environmental end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are accelerating as regulatory compliance deadlines compress procurement windows, positioning the market for cyclical recovery through 2035.
For Market Incumbents: Shield installed base relationships by embedding sensor fusion modules into existing building management system architectures, countering modular retrofit threats from emerging optical specialists. Deepen backward integration into laser diode component supply through exclusive offtake agreements with Japanese photonics manufacturers. Prioritize certification investment for REACH-compliant electrolyte formulations ahead of phase-out timelines. For New Entrants and Emerging Players: EPA reference-grade certification fast-tracks open municipal air quality network opportunities in Australian and Canadian cities where incumbent coverage remains sparse. Target decentralized ambient monitoring deployments where compact optical stations displace sparse reference-grade infrastructure. Pursue sensor-as-a-service go-to-market models that unbundle capital procurement from recurring calibration revenue. For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument specialists with laser-heritage platforms and established pharmaceutical cleanroom relationships. Long-term viability centers on multi-parameter sensor fusion capabilities that retrofit into building automation without parallel infrastructure. Watch OSHA permissible exposure limit enforcement intensity as the inflection signal for industrial hygiene rental model expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Enables retrofit into BACnet and Modbus building management systems without infrastructure replacement. |
| Calibration Service Unbundling | Separates recurring revenue streams from capital equipment sales, expanding independent laboratory market entry. |
| REACH-Compliant Electrolyte Redesign | Preserves electrochemical detector lines ahead of substance restriction phase-out deadlines in Germany. |
| Decentralized Ambient Network Deployment | Positions compact optical stations for Australian and Canadian municipal air quality grid expansion. |
| Laser Platform Maintenance Interval Compression | Displaces infrared benches in Texas and Louisiana petrochemical corridors through annual versus quarterly service cycles. |
Study Parameters
The analysis maps gas analyzers, particulate monitors, flow meters, and humidity sensors, each validated through primary interviews with cleanroom validation engineers, industrial hygiene directors, environmental agency procurement officers, and metrology service technicians. Secondary sources include EPA continuous emission monitoring guidance documents, FDA aseptic processing guidelines, EU Green Deal implementation protocols, and REACH substance restriction timelines. Bottom-up equipment shipment data triangulates against top-down regulatory compliance deadline modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions encompass product type, technology modality, end-user vertical, and application focus, with additional modeling of regulatory compliance cluster effects. CAGRs derive from replacement cycle compression analysis and real-time data architecture penetration curves. Industry-specific inputs include pharmaceutical cleanroom expansion pipelines and petrochemical emission monitoring upgrade schedules.
Underlying assumptions cover regulatory deadline adherence, component supply continuity, and metrology workforce availability, with deviation risk concentrated in rare gas reference mixture cost volatility and REACH substance restriction timeline acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Automated Ultrasonic Testing Market