
 SWIR Camera Market | 2026-2036
SWIR Camera Market Size, Share, and Industry Trends Forecast 2026-2036
SWIR Camera Market Intelligence
The market for short-wave infrared (SWIR) imaging is pivoting on a performance-cost axis, separating high-sensitivity cooled cameras from more accessible uncooled industrial models. Teledyne Technologies specializes in advanced, high-specification sensors for aerospace and defense applications. In contrast, FLIR Systems leverages its scale to offer solutions for broader industrial inspection and security markets. Xenics differentiates through its focus on InGaAs detector technology across a range of price points.
A SWIR camera operates in the 900 to 1700 nanometer wavelength range, which is beyond the visibility of standard silicon-based sensors. This capability allows it to see through materials like silicon wafers or detect moisture content, making it essential for industrial process control and material sorting. While InGaAs-based products dominate the market due to their mature technology, Type-II Superlattice sensors are an emerging high-performance alternative. Among applications, semiconductor inspection represents a high-value segment, whereas agricultural analysis is a volume-driven opportunity.
Export controls, such as the International Traffic in Arms Regulations (ITAR) in the United States, govern the sale of high-performance SWIR cameras for military applications. In Europe, CE marking and RoHS directives influence material composition and product safety standards for industrial and commercial units. Component sourcing and compliance with dual-use technology regulations remain critical decision points for manufacturers targeting international markets.
Market Dynamics
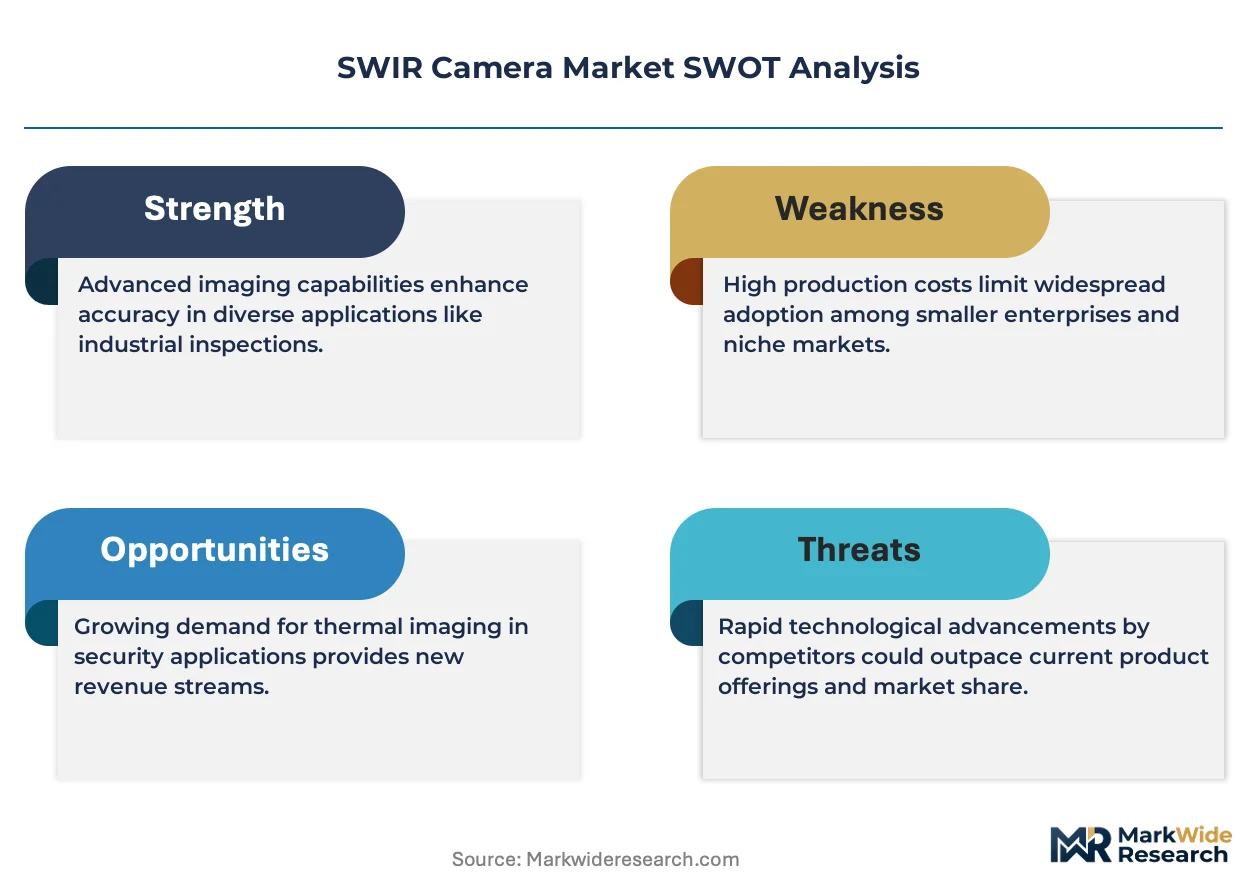
The SWIR camera market's trajectory is defined by the tension between expanding industrial applications demanding lower costs and specialized segments requiring ever-higher sensor performance. This dynamic forces a clear segmentation between volume-driven and specification-driven product development strategies for manufacturers.
Growth Catalysts
- InGaAs Fabrication Advances:Improvements in manufacturing processes for Indium Gallium Arsenide sensors are lowering unit costs and increasing pixel density, making SWIR technology accessible for a wider range of industrial automation and machine vision tasks.
- Precision Agriculture Adoption:Agricultural operations are increasingly using SWIR imaging for moisture detection, crop health monitoring, and sorting, creating a high-volume demand channel distinct from traditional industrial inspection and scientific research.
- South Korean Semiconductor Investment:National industrial strategies in South Korea supporting its semiconductor manufacturing ecosystem directly stimulate demand for high-resolution SWIR cameras used for silicon wafer inspection and process control.
Market Restraints
- Export Controls:Regulations like the U.S. International Traffic in Arms Regulations (ITAR) restrict the sale of high-performance, cooled SWIR cameras, limiting access to certain international defense and aerospace markets without specific licenses.
- Indium Price Volatility:The market's reliance on InGaAs sensors exposes manufacturers to price fluctuations and supply chain risks associated with indium, a critical but relatively scarce raw material in the III-V semiconductor family.
- Performance of Uncooled Sensors:While more affordable, uncooled SWIR cameras have inherent limitations in sensitivity and noise levels, making them unsuitable for demanding scientific research or low-light imaging applications that require cooled detectors.
Strategic Opportunities
- Plastics and Waste Sorting:New environmental mandates, such as those related to the EU Green Deal, create an opportunity for SWIR cameras in automated sorting facilities to identify and separate different types of polymers for recycling.
- Type-II Superlattice Commercialization:Developing and scaling production of Type-II Superlattice (T2SL) sensors offers a path to compete with InGaAs on performance, particularly in extended SWIR ranges, opening new spectroscopy and threat detection applications.
- Medical Imaging Expansion:An emerging opportunity exists in non-invasive medical diagnostics, such as vein visualization for phlebotomy or tissue analysis during surgery, where SWIR provides contrast invisible to the human eye.
Industry Challenges
- System Integration Complexity:Integrating SWIR cameras with existing machine vision software and industrial automation platforms requires specialized expertise in both hardware and software, slowing deployment cycles in factory settings.
- Specialized Talent Scarcity:A limited pool of engineers and physicists with deep knowledge of InGaAs sensor design and fabrication creates a bottleneck for research and development efforts across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SWIR Camera Market |
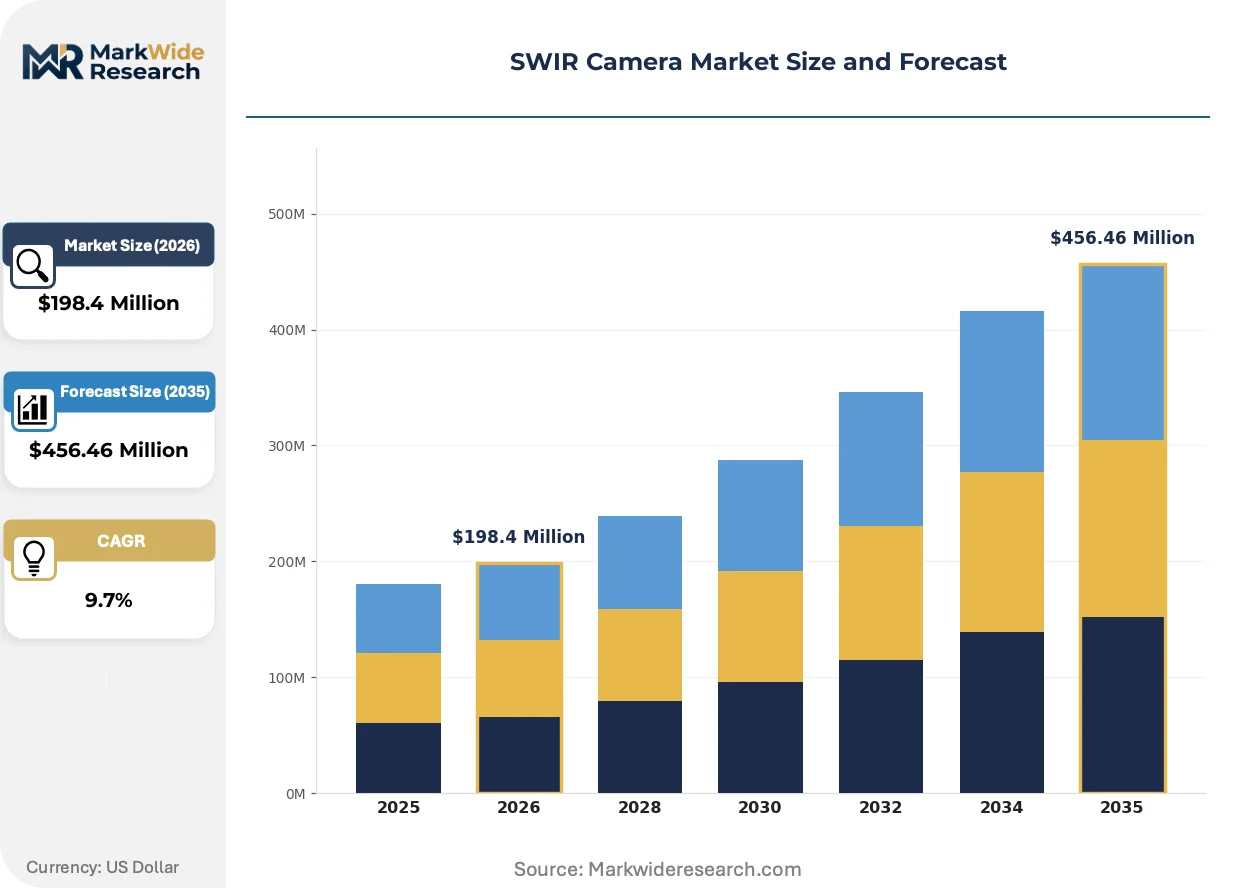
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $456.46 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: InGaAs, Extended InGaAs, MCT, Type-II Superlattice Technology: Photon Counting, Time-of-Flight, Cooling, Non-Cooling Application: Surveillance, Industrial Inspection, Environmental Monitoring, Semiconductor Inspection, Agricultural Analysis End User: Defense Contractors, Manufacturing Facilities, Research Institutes, Remote Sensing Organizations |
| Companies Covered | Xenics, New Imaging Technologies, Teledyne Technologies, L3Harris Technologies, Sensors Unlimited, FLIR Systems, Hamamatsu Photonics, SVS-Vistek GmbH, Allied Vision Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SWIR Camera Market Strategic Shifts & Innovations
Technological maturation and cost-down engineering are transforming SWIR cameras from specialized laboratory instruments into integrated components for industrial process control. This evolution is driven by new sensor architectures and demand for data beyond the visible spectrum.
Uncooled InGaAs sensor arrays provide cost-effective SWIR imaging without the need for cryogenic cooling systems. Industrial automation and machine vision integrators are rapidly adopting these more accessible cameras for quality control tasks. This trend is consolidating the market into a high-performance, cooled segment for science and defense, and a larger, volume-driven industrial segment.
The European Union’s Restriction of Hazardous Substances (RoHS) directive governs the material composition of electronic equipment sold within the bloc. This regulation forces SWIR camera manufacturers to verify their supply chains and eliminate restricted materials from solders and electronic components. Industrial camera makers targeting European markets must invest in compliant design and documentation to maintain market access.
End-users are increasingly prioritizing integrated imaging solutions over standalone camera hardware, seeking systems with pre-configured software and analytics. This shift challenges the traditional component sales model, favoring suppliers who can provide complete, application-specific inspection packages. The trend is most visible in semiconductor inspection and automated agricultural sorting, where turnkey systems reduce integration time and complexity for operators.
SWIR Camera Market Segmentation

The SWIR camera market's segmentation reflects the diverse technological approaches and application demands driving its expansion. Understanding these distinct segments is crucial for manufacturers to align product development with specific end-user requirements and market opportunities.
Product Type:
SWIR camera product differentiation primarily hinges on sensor material and spectral range capabilities.
- InGaAs:Indium Gallium Arsenide (InGaAs) sensors dominate the SWIR market due to their mature fabrication processes and broad spectral response. Demand concentrates in industrial inspection and semiconductor manufacturing for defect detection and quality control.
- Type-II Superlattice:Type-II Superlattice (T2SL) sensors offer high-performance alternatives, especially for extended SWIR ranges and improved detectivity. This technology is gaining traction in defense applications and advanced scientific research requiring superior sensitivity.
- Extended InGaAs:These sensors push the spectral response beyond the standard InGaAs range, enabling specialized gas detection and material analysis.
- MCT:Mercury Cadmium Telluride (MCT) detectors provide high sensitivity across a wide infrared spectrum but often require cryogenic cooling.
InGaAs leads on scale; Type-II Superlattice leads on momentum.
Technology:
Different SWIR camera technologies offer varying performance-to-cost ratios, influencing their market adoption.
- Cooling:Cooled SWIR cameras employ thermoelectric or cryogenic coolers to reduce sensor noise and enhance sensitivity for demanding applications. These units serve high-end scientific research and military surveillance where performance is paramount.
- Non-Cooling:Uncooled SWIR sensors provide a cost-effective solution for industrial automation and machine vision tasks, simplifying system integration and reducing operational costs. This technology is expanding rapidly into volume-driven industrial markets.
- Photon Counting:This technology detects individual photons, offering extreme sensitivity for ultra-low light imaging and quantum optics research.
- Time-of-Flight:Time-of-Flight (ToF) SWIR cameras measure depth information by calculating light travel time, useful for 3D sensing and autonomous navigation systems.
Cooling technology delivers superior performance for scientific applications, while non-cooling solutions are gaining share fastest in industrial volume markets.
Application:
The diverse application landscape for SWIR cameras drives market volume across multiple end-use sectors.
- Semiconductor Inspection:SWIR cameras are essential for inspecting silicon wafers and electronic components, detecting subsurface defects invisible to visible light. This high-value segment is critical for quality control in South Korean semiconductor fabrication plants.
- Agricultural Analysis:Precision agriculture utilizes SWIR imaging for real-time moisture content assessment, crop health monitoring, and automated sorting of produce. This application represents a significant volume-driven opportunity for uncooled SWIR systems.
- Industrial Inspection:SWIR cameras perform quality control in manufacturing processes, including plastic sorting, food inspection, and non-destructive testing of materials.
- Surveillance:SWIR technology enhances visibility in low-light conditions and through atmospheric obscurants, making it valuable for security and defense surveillance systems.
- Environmental Monitoring:These cameras detect specific gases and pollutants, supporting environmental research and industrial emissions monitoring.
Semiconductor inspection commands the highest unit value, whereas agricultural analysis represents a significant volume opportunity.
End User:
SWIR camera adoption is segmented by the specific operational needs and purchasing power of distinct customer types.
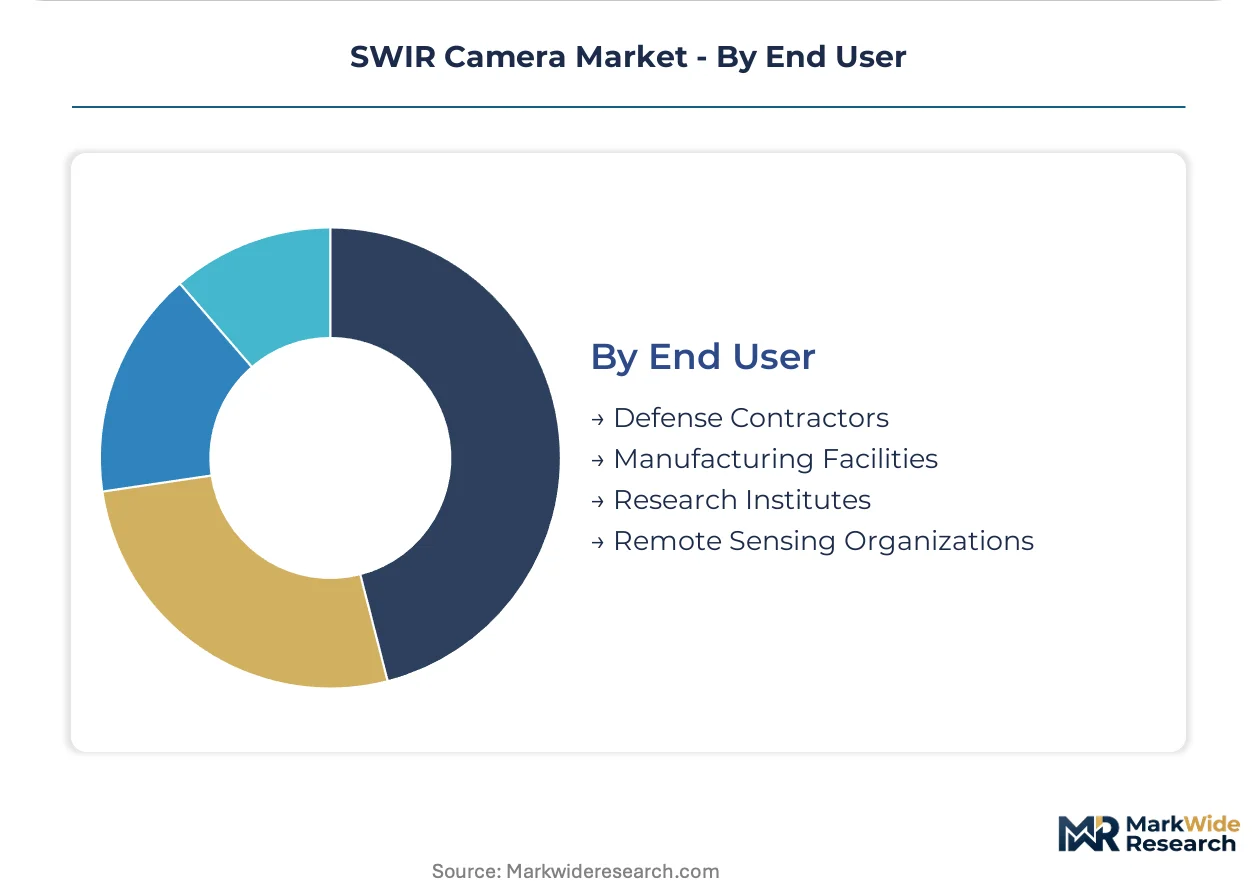
- Defense Contractors:These users procure high-performance, often cooled, SWIR cameras for military reconnaissance, target acquisition, and night vision systems. Export controls like ITAR significantly impact sales to this segment.
- Manufacturing Facilities:Industrial manufacturers integrate SWIR cameras into automated production lines for quality control, process monitoring, and material sorting. This segment drives demand for cost-effective, uncooled solutions.
- Research Institutes:Academic and commercial research organizations use SWIR cameras for scientific experimentation, material characterization, and spectroscopy.
- Remote Sensing Organizations:These entities deploy SWIR cameras on drones, aircraft, and satellites for earth observation, environmental mapping, and infrastructure inspection.
Manufacturing facilities consume the largest volume of industrial SWIR cameras, while defense contractors drive demand for high-specification cooled units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A specialized engineering talent pool in advanced optics and materials science anchors demand across key regions for SWIR cameras. This expertise drives innovation and application development in high-value industrial sectors. Countries with strong manufacturing bases and research ecosystems are at the forefront of adoption.
South Korea
South Korea's robust semiconductor manufacturing ecosystem drives significant demand for high-resolution SWIR cameras. National industrial strategies actively support the growth of advanced fabrication technologies. Major semiconductor hubs in Gyeonggi Province utilize SWIR imaging for critical wafer inspection and defect detection processes.
United States
Defense and aerospace sectors generate substantial demand for high-performance, cooled SWIR cameras in the United States. International Traffic in Arms Regulations (ITAR) govern the export of these sensitive technologies. Research institutions and defense contractors in California develop advanced SWIR systems for surveillance and scientific applications.
Germany
Germany's strong industrial automation and machine vision industries require SWIR cameras for quality control and process monitoring. CE marking and RoHS directives ensure compliance for electronic components across the European Union. Manufacturing centers in Bavaria integrate uncooled SWIR systems into automated production lines for diverse applications.
Japan
Japan's precision manufacturing and advanced materials research sectors create consistent demand for SWIR imaging solutions. Compliance with JIS standards guides the development and integration of industrial cameras. Technology clusters around Tokyo drive innovation in InGaAs sensor applications for factory automation and scientific analysis.
China
China's expanding manufacturing base and growing focus on industrial upgrading stimulate demand for cost-effective SWIR cameras. GB standards ensure product quality and safety for domestic and international markets. Industrial zones in the Yangtze River Delta increasingly adopt SWIR technology for automated sorting and quality inspection.
SWIR Camera Market Key Industry Players
Top-tier vendors anchor the high-performance segment, while a broader base of specialized firms addresses volume-driven industrial markets. The market structure exhibits a clear bifurcation between companies serving defense and scientific research and those targeting industrial automation. Strategic archetypes include integrated defense contractors, specialized InGaAs sensor developers, and industrial machine vision providers. Competitive moves frequently involve strategic partnerships for system integration, technology licensing to broaden application reach, and targeted M&A for niche capabilities.
Among established technology specialists, Teledyne Technologies exemplifies a focus on advanced, high-specification sensors for demanding aerospace applications. FLIR Systems occupies a position as a scale-driven provider, leveraging its broad portfolio for industrial inspection and security solutions. Meanwhile, Xenics, a European-based firm, represents the specialized InGaAs detector technology segment, offering a range of price points for diverse industrial and scientific uses. These firms define the performance and cost benchmarks for the industry, influencing product development across various application domains.
| Leading Market Players |
|---|
| Xenics |
| New Imaging Technologies |
| Teledyne Technologies |
| L3Harris Technologies |
| Sensors Unlimited |
| FLIR Systems |
| Hamamatsu Photonics |
| SVS-Vistek GmbH |
| Allied Vision Technologies |
| Others |
Cost & Logistics Intelligence
Industrial automation integrators' preference for cost-effective, easily deployable SWIR solutions is forcing manufacturers to optimize production processes, influencing component sourcing and overall camera pricing strategies.
Pricing Analysis
Pricing differentiates between standalone SWIR cameras and integrated imaging solutions, which often include software and analytics packages. Per-unit transactional pricing dominates for uncooled industrial cameras, while project-based contracts serve high-performance cooled systems for defense and research. Performance tiers, based on sensitivity and resolution, drive price differentiation, with brand premium influencing high-end units. Cost compression in the uncooled segment intensifies due to InGaAs fabrication advances, making manufacturing facilities highly price-sensitive, unlike defense contractors who prioritize performance.
Supply Chain Analysis
Mandated multi-supplier qualification for critical components shapes the SWIR camera supply chain, particularly for high-volume industrial applications. Component manufacturing concentrates in South Korea for semiconductor-grade sensors and Japan for precision optics, with specialized cooling systems from the United States and Germany. The market draws from Indium, Gallium, and Arsenic as key raw materials, exposing manufacturers to commodity price volatility. Export controls like ITAR represent a structural risk, and distribution runs through direct sales for defense and specialized integrators for industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SWIR camera market is transitioning into a late-cycle quality story, driven by demand for higher resolution and lower noise across critical industrial inspection applications.
For Market Incumbents: Extend product lines into emerging high-growth segments like Type-II Superlattice sensors for enhanced performance. Acquire niche technology firms specializing in advanced InGaAs fabrication to counter the threat of lower-cost competitors. Deepen customer relationships with long-term service contracts and invest in R&D for next-generation sensor materials.
For New Entrants and Emerging Players: Capture white-space opportunities in uncooled industrial automation and agricultural analysis. The most penetrable segment remains volume-driven industrial applications requiring cost-effective, easy-to-integrate SWIR solutions. Partnerships with machine vision integrators, offering turnkey SWIR imaging systems, provide a strong go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized InGaAs detector developers and Type-II Superlattice technology firms over the next decade. Acquisition targets should include companies offering advanced sensor materials or software platforms for SWIR data analytics. The commercialization success of T2SL sensors in industrial applications represents a critical signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification into T2SL | Expands market reach into high-performance and extended SWIR applications for defense and scientific research. |
| Strategic Alliances with Integrators | Facilitates broader adoption of uncooled SWIR cameras in industrial automation and machine vision systems. |
| R&D Investment in InGaAs Fabrication | Drives down unit costs and increases pixel density for industrial and volume-driven SWIR camera segments. |
| Geographic Expansion in Asia-Pacific | Captures growing demand from semiconductor manufacturing and industrial upgrading initiatives in countries like China. |
| Development of Turnkey Software Solutions | Reduces system integration complexity for end-users, accelerating deployment in factory settings and agricultural operations. |
Research Approach
Direct dialogue with SWIR sensor engineers, machine vision integrators, defense procurement specialists, and semiconductor fab managers grounds the qualitative insights. This primary research combines with extensive secondary validation from industry association reports, academic journals, and company financial filings. The analysis employs both bottom-up and top-down triangulation to ensure robust data integrity.
Volume and value projections were developed across the analysis window, integrating various market dynamics. The model segments by product type, technology, application, end-user, and spectral range capabilities. Compound annual growth rates derived from historical data and projected market shifts incorporate semiconductor capital expenditure and agricultural technology investment.
Indium price volatility, geopolitical export control changes, and rapid technological obsolescence are the dominant revision risks for forecasts reflecting underlying assumptions. Deviation in geopolitical export control changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Instant Digital Cameras Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Global Acoustic Cameras Market
Imaging
Visualiser Market
Imaging
Cinematographic Camera Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
Multimodal Imaging Market
Imaging
China Electron Microscopy Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Video Microscopes Market
Imaging
Global Camera Module Market
Imaging
X-Ray Market
Imaging
Asia Pacific IP Camera Market
Imaging
North America IP Camera Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Thermal Camera Market