
 Hyper Spectral Imaging System Market | 2026-2036
Hyper Spectral Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Hyper Spectral Imaging System Market Foresight
Precision agriculture buyers is bifurcating from defense-heavy procurement toward commercial environmental monitoring contracts. Specim, Spectral Imaging Ltd. dominates airborne pushbroom configurations for Nordic forestry ministries. Headwall Photonics anchors its position through backward integration into custom diffraction gratings for OEM spectral engines. Resonon Inc. competes on laboratory-grade benchtop systems serving university research consortia.
Hyperspectral imaging systems capture contiguous narrow spectral bands across ultraviolet through shortwave infrared wavelengths, typically spanning 400-2500 nanometers with spectral resolution below 10 nanometers, enabling pixel-level material identification through spectral signature matching. Pushbroom technology leads installed base in satellite and aerial platforms due to proven signal-to-noise ratios at altitude. Snapshot architectures represent the fastest-expanding technology segment as semiconductor fabrication advances permit focal plane array integration. Camera hardware commands the dominant margin pool while software analytics layers attract venture funding for cloud-based spectral classification services.
FDA clearance pathways govern medical imaging subsystems destined for surgical guidance applications in the United States. REACH compliance requirements from ECHA constrain germanium and indium gallium arsenide supply chains for European sensor fabricators. ISO 9001 and IEC 61340 certifications function as baseline qualifications for defense procurement tenders across NATO member states. Stakeholders must monitor spectral data sovereignty regulations as agricultural analytics platforms migrate to cloud architectures.
Market Dynamics
The EU Green Deal's sustainability mandates are compressing procurement timelines for environmental monitoring equipment across European agricultural ministries, while semiconductor fabrication advances simultaneously enable focal plane array integration at scale.
Growth Catalysts
- REACH compliance acceleration:ECHA constraints on germanium and indium gallium arsenide supply chains are forcing European fabricators toward alternative sensor architectures, opening design contracts for spectral engine OEMs.
- Precision agriculture scaling:Crop health monitoring deployments are expanding hyperspectral camera procurement beyond defense ministries into commercial farming cooperatives across Germany's industrial optics corridor.
- Snapshot architecture maturation:Focal plane array integration is displacing legacy whiskbroom systems in airborne platforms, reducing mechanical complexity and maintenance intervals for forestry ministries.
Market Restraints
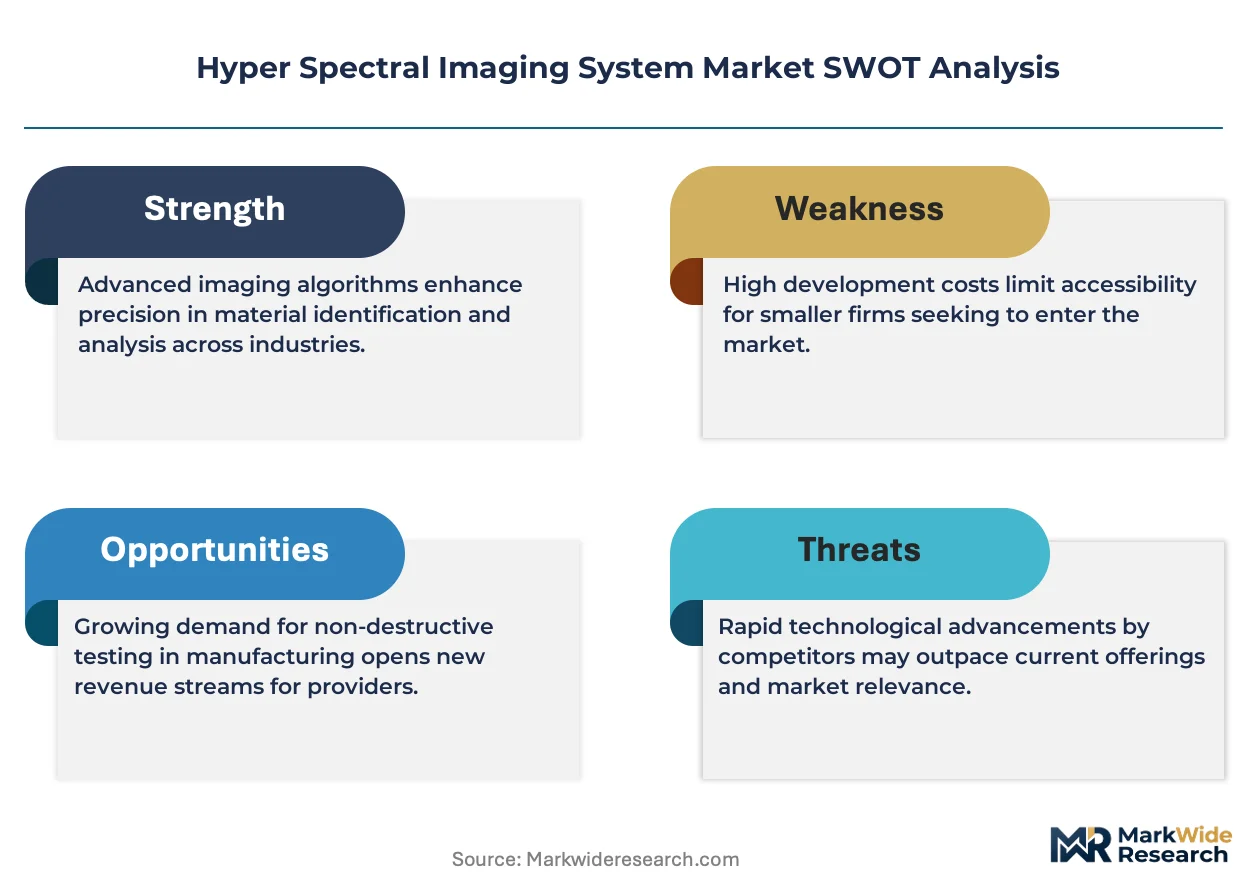
- Germanium supply concentration:Sensor fabricators face input cost volatility from concentrated rare earth processing in limited geographic corridors, constraining production planning for shortwave infrared detectors.
- Technical noise-floor limitations:Signal-to-noise ratio degradation at altitude remains a structural barrier for satellite-based mineralogical surveys, limiting commercial viability compared to aerial alternatives.
- FDA pathway friction:Medical imaging subsystems for surgical guidance face extended clearance timelines in the United States, compressing venture timelines for clinical-stage spectral device developers.
Strategic Opportunities
- Cloud-based analytics migration:Agricultural analytics platforms moving to cloud architectures create white space for spectral data sovereignty compliance services across Nordic forestry ministries.
- Benchtop system university penetration:Laboratory-grade configurations remain underpenetrated in Asian research consortia outside established North American and European markets.
- EU AI Act convergence:Automated spectral classification algorithms embedded in imaging software fall within emerging regulatory frameworks, creating certification-driven preference shifts for compliant vendors.
Industry Challenges
- Diffraction grating fabrication expertise:The specialized optical engineering talent pool for custom grating production concentrates in legacy industrial clusters, creating recruitment friction for new market entrants.
- IEC 61340 certification timelines:Defense procurement tenders across NATO member states require electrostatic discharge compliance that extends product qualification cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyper Spectral Imaging System Market |
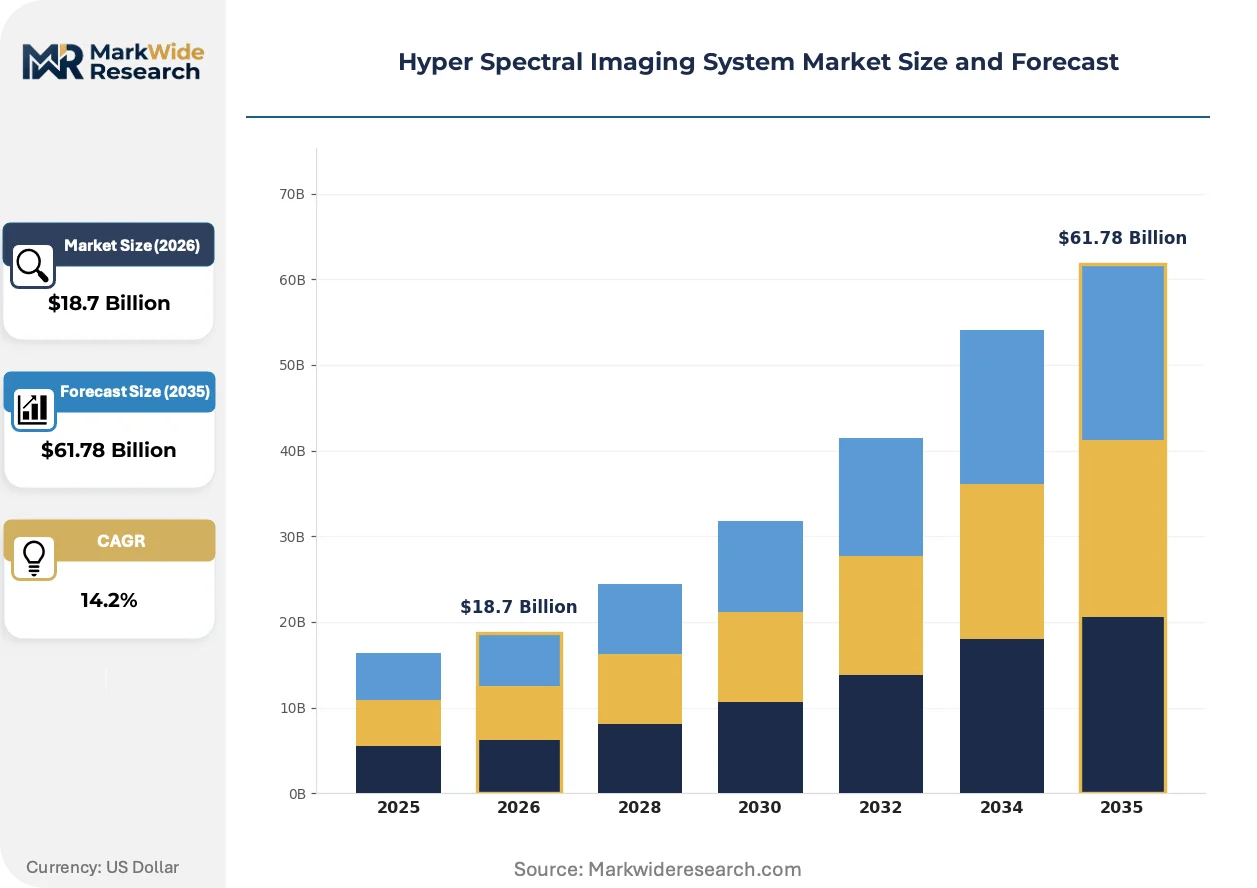
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera, Sensor, Software, Accessories End User: Aerospace, Healthcare, Agriculture, Environmental Monitoring Technology: Pushbroom, Whiskbroom, Snapshot, Tunable Filter Application: Food Quality Testing, Mineralogy, Medical Imaging, Biometric Analysis |
| Companies Covered | Specim, Spectral Imaging Ltd., Resonon Inc., Headwall Photonics, Corning Incorporated, BaySpec Inc., Norsk Elektro Optikk, Telops Inc., Imec, Surface Optics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyper Spectral Imaging System Market Shifts & Advancements
Spectral imaging hardware is compressing toward chip-scale integration while regulatory frameworks simultaneously mandate data transparency, reshaping competitive differentiation from optical performance toward software analytics layers.
Snapshot focal plane array architectures are miniaturizing hyperspectral sensors from rack-mounted laboratory instruments to handheld field devices. Agricultural drone operators in Germany's Bavarian farming cooperatives are adopting these compact configurations for real-time nitrogen stress mapping. The form factor reduction is miniaturizing addressable market entry barriers, enabling university research consortia to bypass traditional capital-intensive benchtop procurement.
REACH substance restrictions from ECHA are constraining germanium and indium gallium arsenide supply chains for European sensor fabricators. Manufacturers are responding with silicon-based alternative detector materials that trade some quantum efficiency for supply security. Shortwave infrared camera modules destined for environmental monitoring applications face the most acute reformulation pressure, with German optics houses accelerating alternative material qualification programs.
Equipment-as-a-service models are displacing outright purchase contracts in precision agriculture verticals. German farming cooperatives now lease hyperspectral drone payloads with bundled analytics subscriptions rather than capitalizing hardware. This preference shift concentrates vendor risk on performance uptime guarantees and compresses customer switching costs, with Munich-area agricultural technology clusters showing the highest contract penetration rates.
Hyper Spectral Imaging System Market Segmentation
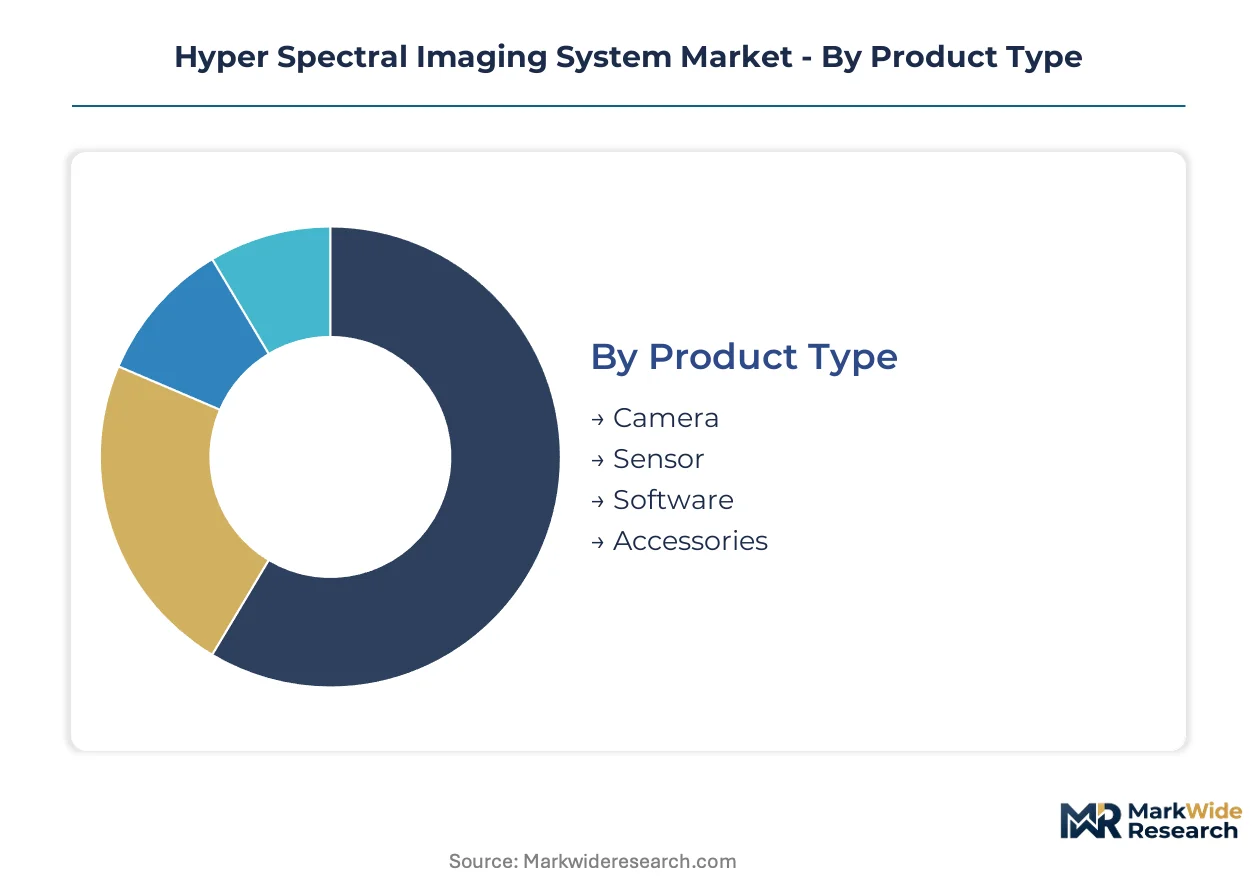
Hyperspectral imaging system procurement channels diverge sharply by segment maturity. Camera hardware flows through defense integrators and OEM spectral engine contracts, while software analytics layers attract cloud-service subscriptions from agricultural cooperatives.
Product Type:
Camera units dominate direct sales channels to aerospace integrators, whereas software licenses increasingly route through equipment-as-a-service bundles for precision agriculture leasing programs.
- Camera:Pushbroom and snapshot architectures constitute the primary hardware revenue pool, with airborne configurations commanding premium pricing from forestry ministries in Germany's Bavarian farming cooperatives. REACH compliance constraints on germanium detector materials are forcing silicon-based alternative qualification programs across Munich-area optics houses.
- Sensor:Focal plane array integration is miniaturizing detector assemblies from rack-mounted laboratory instruments to handheld field devices for drone-mounted nitrogen stress mapping. Indium gallium arsenide shortwave infrared sensors face acute supply reformulation pressure from ECHA substance restrictions.
- Software:Cloud-based spectral classification services attract venture funding for agricultural analytics platforms migrating to cloud architectures.
- Accessories:Calibration targets and thermal management modules complete system configurations for laboratory-grade benchtop deployments.
By volume, Camera leads. By growth pace, Software is ahead.
End User:
Cost tier stratification separates defense-funded aerospace programs from commercial environmental monitoring contracts with compressed procurement timelines.
- Aerospace:Satellite and aerial platforms require proven signal-to-noise ratios at altitude, with pushbroom technology anchoring the installed base. Signal-to-noise ratio degradation at altitude remains a structural barrier for satellite-based mineralogical surveys, limiting commercial viability compared to aerial alternatives.
- Agriculture:German farming cooperatives now lease hyperspectral drone payloads with bundled analytics subscriptions rather than capitalizing hardware, concentrating vendor risk on performance uptime guarantees.
- Healthcare:FDA clearance pathways govern medical imaging subsystems destined for surgical guidance applications in the United States.
- Environmental Monitoring:The EU Green Deal's sustainability mandates are compressing procurement timelines for European agricultural ministries.
Environmental Monitoring shows the steepest expansion trajectory as sustainability mandates accelerate.
Technology:
Application requirements dictate technology selection, with airborne mineralogical surveys demanding proven altitude performance while handheld field devices prioritize mechanical simplicity.
- Pushbroom:Linear array scanning captures contiguous spectral bands across flight paths, dominating satellite and aerial platforms due to established signal-to-noise performance. Nordic forestry ministries specify airborne pushbroom configurations for large-area coverage contracts.
- Snapshot:Focal plane array architectures capture full spectral cubes in single exposures, miniaturizing sensors for real-time agricultural drone operations. Semiconductor fabrication advances permit integration at scale, reducing mechanical complexity and maintenance intervals.
- Whiskbroom:Point-scanning mechanisms persist in legacy satellite systems with extensive qualification heritage.
- Tunable Filter:Acousto-optical and liquid crystal configurations enable wavelength-selective imaging for laboratory research consortia.
Pushbroom retains the largest installed base. Snapshot architectures are gaining share fastest through miniaturization.
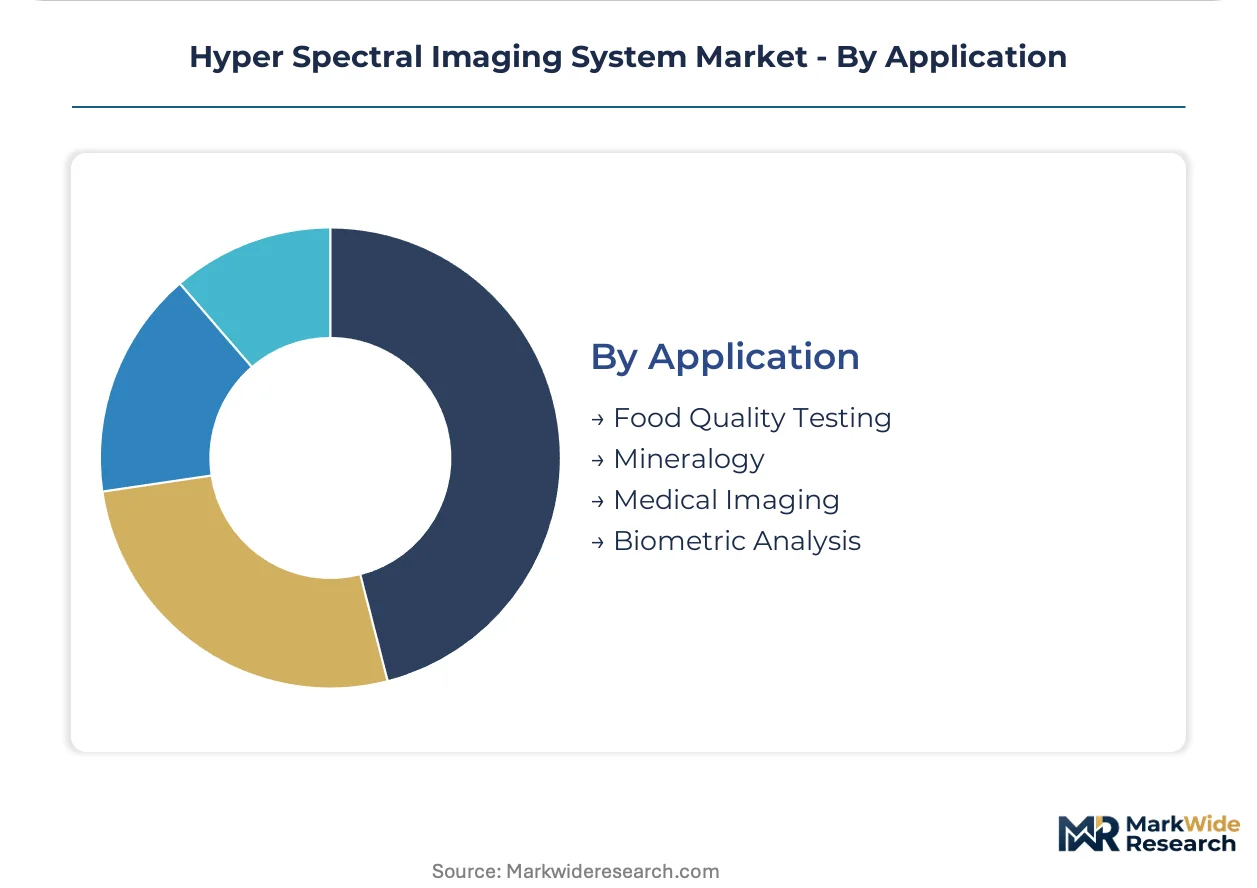
Application:
Margin concentration varies by regulatory burden, with medical imaging facing extended FDA clearance timelines while food quality testing routes through faster CE marking pathways.
- Medical Imaging:Surgical guidance subsystems require FDA clearance pathways in the United States, compressing venture timelines for clinical-stage spectral device developers. Extended qualification cycles extend product development timelines by twelve to eighteen months for electrostatic discharge compliance.
- Food Quality Testing:Non-destructive spectral inspection identifies contamination and ripeness markers for processing facilities under EFSA hygiene mandates.
- Mineralogy:Satellite-based surveys face signal-to-noise limitations that constrain commercial viability compared to aerial alternatives.
- Biometric Analysis:Spectral signature matching enables pixel-level identification for security and forensic applications.
Medical Imaging commands the highest unit values. Food Quality Testing is expanding most quickly through faster regulatory pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Munich-Jena industrial optics corridor anchors European hyperspectral manufacturing capacity, while semiconductor fabrication infrastructure in East Asia enables focal plane array integration at scale.
United States
Defense procurement from NASA and NOAA sustains demand for satellite-grade pushbroom systems. FDA clearance pathways govern medical imaging subsystems for surgical guidance applications. Greater Boston hosts clinical-stage spectral device developers facing extended venture timelines.
Germany
Bavarian farming cooperatives lease hyperspectral drone payloads with bundled analytics subscriptions under EU Green Deal sustainability mandates. REACH compliance requirements from ECHA constrain germanium and indium gallium arsenide supply chains. Munich-area optics houses accelerate silicon-based alternative detector qualification programs.
China
MIIT industrial policy supports domestic focal plane array fabrication for environmental monitoring equipment. Dual carbon goals accelerate procurement timelines for agricultural ministries. Yangtze River Delta semiconductor foundries enable snapshot architecture miniaturization at scale.
Japan
METI funding programs advance shortwave infrared detector research for forestry ministry contracts. JIS certification requirements structure defense procurement tenders. Nagoya-area precision optics clusters supply diffraction grating components to regional system integrators.
Finland
Nordic forestry ministries specify airborne pushbroom configurations for large-area coverage contracts. EU AI Act convergence shapes automated spectral classification algorithm development. Helsinki-Tampere photonics corridors concentrate pushbroom integration expertise.
Hyper Spectral Imaging System Market Competitive Landscape
Concentration sits with specialized optical engineering houses controlling custom diffraction grating fabrication. The vendor base spans three tiers: defense-aerospace integrators with NATO qualification heritage, commercial environmental monitoring specialists with EU Green Deal contract access, and university-facing benchtop system providers. Tier boundaries blur as equipment-as-a-service models compress capital barriers. Dominant competitive moves include backward integration into captive sensor architectures and cloud-based analytics layer development.
Among Nordic specialists, Specim, Spectral Imaging Ltd. and Norsk Elektro Optikk represent the environmental monitoring archetype with forestry ministry contract penetration. Headwall Photonics exemplifies the backward-integrated tier through in-house diffraction grating production. Resonon Inc. occupies the research consortium segment with laboratory-grade system positioning. These three anchors illustrate how geographic clustering around Munich, Helsinki, and North American university towns shapes competitive differentiation.
| Leading Market Players |
|---|
| Specim, Spectral Imaging Ltd. |
| Resonon Inc. |
| Headwall Photonics |
| Corning Incorporated |
| BaySpec Inc. |
| Norsk Elektro Optikk |
| Telops Inc. |
| Imec |
| Surface Optics Corporation |
| Others |
Supply & Pricing Matrix
IEC 61340 electrostatic discharge certification gates both NATO defense procurement eligibility and premium pricing tiers for hyperspectral camera hardware, compressing supplier qualification timelines while stratifying vendors into performance-based price bands.
Pricing Analysis
Volume-discount tiering structures dominate hyperspectral system procurement, with aerospace integrators capturing standard-tier pricing through multi-unit satellite payload contracts while university research consortia face premium per-unit rates for single benchtop configurations. Price differentiation rests on ISO 9001 certification grade and bundled analytics subscription depth. Pricing pressure stems from silicon-based detector alternatives displacing germanium-dependent shortwave infrared modules. Agricultural drone operators in German farming cooperatives exhibit highest price sensitivity; defense ministries show lowest.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Asia-Europe container availability constraints are compressing delivery timelines for focal plane array components sourced from Taiwanese and South Korean foundries. Germanium concentrate flows from Chinese rare earth processors; diffraction grating fabrication concentrates in Munich-Jena and Nagoya precision optics clusters. Supply chain risk centers on single-source vulnerability for indium gallium arsenide substrates. Distribution runs through defense integrators for aerospace tiers and equipment-as-a-service platforms for precision agriculture leasing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH compliance and NATO qualification heritage creates defensive moats for established hyperspectral vendors, with certification switching costs locking defense ministries into incumbent supplier relationships.
For Market Incumbents: Compound backward integration into captive diffraction grating production to defend margin position against emerging silicon-detector specialists. Accelerate cloud-based analytics layer development to capture recurring revenue streams as equipment-as-a-service models displace hardware purchases in German agricultural cooperatives.
For New Entrants and Emerging Players: CE marking fast-tracks for food quality testing applications open white-space penetration routes outside defense procurement barriers. Target Asian university research consortia with compact snapshot architectures for underpenetrated laboratory-grade benchtop segments. Pursue bundled calibration-subscription go-to-market angles.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward automated spectral classification algorithm developers with compliance-ready software stacks. Five-to-ten-year viability favors vendors controlling both sensor hardware and analytics layers. Target acquisition archetype: mid-cap specialists with forestry ministry contract penetration and in-house grating fabrication. Signal to watch: silicon-based shortwave infrared qualification milestones at Munich-area optics houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diffraction Grating Production | Captive optical component supply secures margin control against germanium supply volatility from ECHA constraints. |
| Cloud-Based Analytics Platform Development | Spectral data sovereignty services capture recurring revenue from Nordic forestry ministries migrating to cloud architectures. |
| Silicon-Based Detector Qualification Programs | Alternative sensor materials reduce REACH compliance exposure while opening design contracts for European spectral engine OEMs. |
| Equipment-as-a-Service Model Deployment | Leasing structures with bundled analytics subscriptions compress customer switching costs in Bavarian farming cooperatives. |
| EU AI Act Compliance Certification | Automated spectral classification algorithm validation creates preference shifts for compliant vendors in public procurement tenders. |
Research Methodology
Operator-level perspectives from spectral imaging hardware engineers, precision agriculture procurement officers at German farming cooperatives, NATO defense procurement contract managers, and ECHA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA 510(k) filings for surgical guidance subsystems, REACH substance restriction updates from ECHA, ISO certification registries, and customs data for germanium and indium gallium arsenide trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around semiconductor fabrication yield assumptions and rare earth supply disruption scenarios shaped the forecast framework. Segmentation dimensions modeled include product architecture, end-use vertical, technology type, and application requirement across the projection horizon. CAGRs derived from fitted growth curves applied to unit shipment and average selling price trajectories. Industry-specific inputs encompassed forestry ministry budget allocation patterns and dual carbon goal procurement acceleration timelines from MIIT policy directives.
Underlying assumptions cover sustained EU Green Deal funding continuity and stable semiconductor foundry capacity expansion, with deviation risk concentrated in germanium supply chain disruptions and extended FDA clearance timelines for clinical-stage spectral device developers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Thermal Imaging Systems Market
Imaging
Global Digital Photo Frame Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Global Digital Binoculars Market
Imaging
Widefield Imaging Systems Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Camera with Flip Screen Market
Imaging
Global Panoramic Camera Market
Imaging
Global CMOS Image Sensors Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Fiducial Markers Market
Imaging
Underwater Camera Market
Imaging
Europe Image Sensors Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Industrial Camera Market
Imaging
Europe IP Camera Market