
 Global Image Sensors Market | 2026-2036
Global Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Sensors Market Outlook
Semiconductor fabrication talent is rotating toward image sensor specialization as foundries expand dedicated CIS capacity. Sony Corporation leverages in-house wafer processing to sustain technology leadership in stacked CMOS architectures. Samsung Electronics Co., Ltd. anchors high-volume supply for captive smartphone demand while extending foundry services to external clients. OmniVision Technologies, Inc. specializes in compact form factors for automotive and medical end uses, navigating tight automotive qualification cycles.
Image sensors are solid-state devices that convert photons into electrical signals through pixel arrays fabricated on silicon wafers, typically achieving quantum efficiency above 70 percent in backside-illuminated architectures for low-light performance. These components serve as the primary visual acquisition layer in cameras, machine vision systems, and biometric scanners across industrial and consumer applications. CMOS technology dominates unit shipments due to lower power draw and on-chip integration, while thermal and multispectral technologies capture premium margin pools in defense and precision agriculture. Automotive applications represent the fastest-expanding demand segment as surround-view and cabin-monitoring mandates proliferate across vehicle platforms.
The EU's REACH framework restricts hazardous substances in sensor packaging materials, while the F-Gas Regulation limits fluorinated greenhouse gases used in certain etching processes during wafer fabrication. China's MIIT enforces GB standards for electromagnetic compatibility in automotive-integrated cameras, shaping product certification requirements for suppliers targeting domestic NEV manufacturers. Stakeholders must monitor evolving camera-perception mandates from NHTSA in the United States and KBA in Germany, as regulatory divergence between safety standards and data privacy frameworks will determine regional product configuration strategies.
Market Dynamics
Automotive ADAS mandates are compressing qualification cycles and forcing foundries to reallocate wafer capacity toward automotive-grade CMOS fabrication, reshaping supply allocation across consumer and industrial segments.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated etching gases are accelerating transition to dry etching processes, reducing environmental compliance costs for European wafer fabricators.
- China NEV procurement:Domestic new energy vehicle manufacturers are volume-contracting locally fabricated BSI sensors, concentrating demand within vertically integrated supply chains.
- Surround-view mandates:Camera-perception requirements from NHTSA and KBA are mandating multi-sensor arrays per vehicle platform, expanding unit pull-through.
Market Restraints
- Specialized silicon wafer supply:300mm CIS-grade wafer output concentrates among three Japanese suppliers, creating input bottleneck risk.
- Automotive qualification timelines:AEC-Q100 certification cycles extend 18-24 months, freezing design wins and delaying revenue recognition.
- EU REACH material restrictions:Hazardous substance limits in sensor packaging materials are forcing reformulation of epoxy molding compounds and die-attach adhesives.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting sensor packaging and testing investments to Gujarat and Tamil Nadu clusters.
- Medical endoscopy miniaturization:Sub-2mm CMOS modules for disposable scopes represent uncaptured margin pools outside automotive and smartphone saturation.
- Multispectral fusion:Convergence of visible and SWIR sensing architectures is opening precision agriculture and defense applications previously served by discrete technologies.
Industry Challenges
- Deep-submicron pixel design talent:Foundries face acute scarcity of engineers experienced in 0.7µm and smaller pixel optimization.
- Legacy automotive integration:OEMs struggle to reconcile 12V electrical architectures with low-voltage CMOS sensor power requirements without full platform redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Sensors Market |
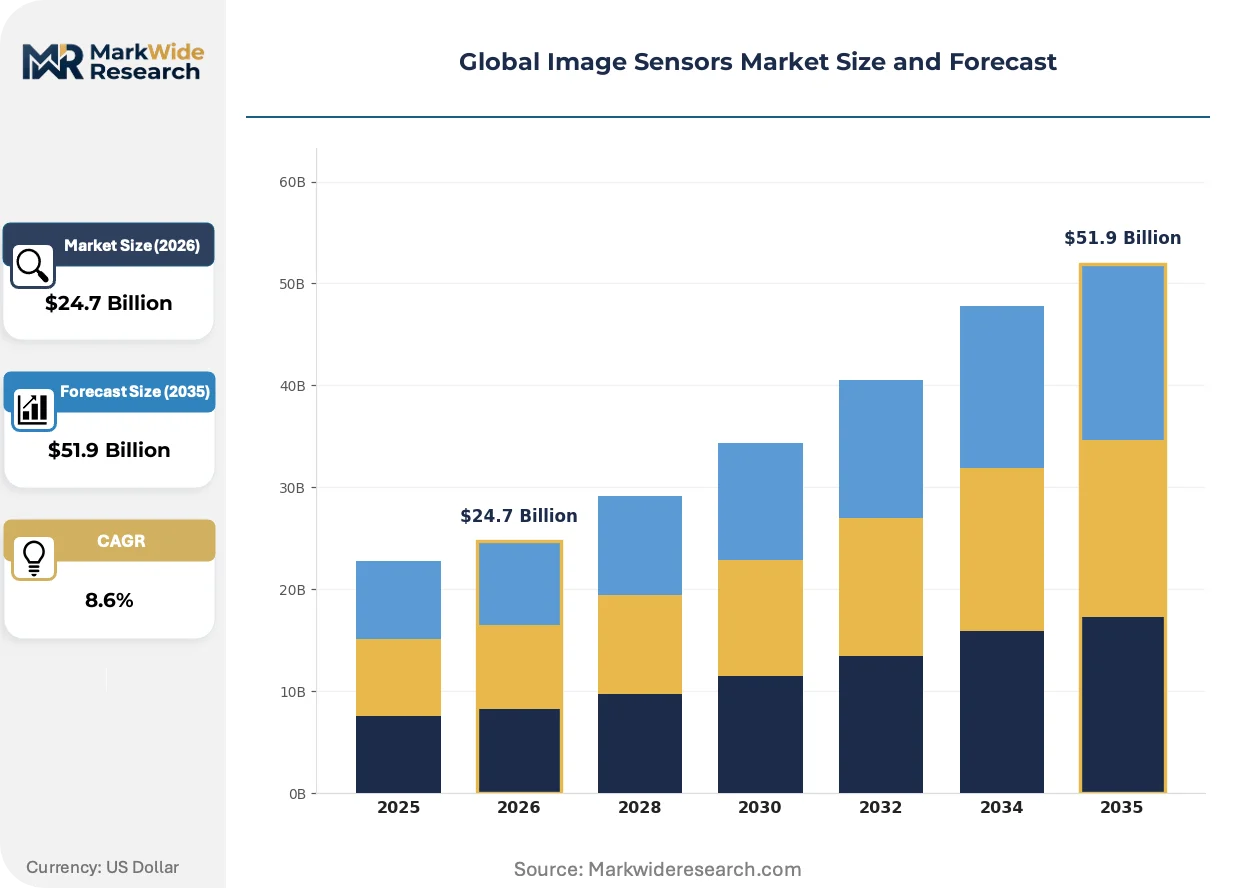
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS, CCD, BSI, FSI Application: Automotive, Consumer Electronics, Industrial, Healthcare Technology: Optical, X-ray, Thermal, Multispectral End User: OEMs, Retailers, Distributors, Aftermarket Providers |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., OmniVision Technologies, Inc., STMicroelectronics N.V., onsemi, Canon Inc., Panasonic Holdings Corporation, SK Hynix Inc., Himax Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Sensors Market Strategic Shifts
Stacked CMOS architectures are compressing die footprints while elevating readout speeds, forcing competitive repositioning among foundries and IDMs. Three developments are restructuring technical and commercial trajectories.
Backside-illuminated stacked sensors are displacing frontside-illuminated alternatives in premium smartphone and automotive applications. Samsung and Sony have transitioned flagship production lines to hybrid bonding interconnects, achieving pixel pitches below 0.6µm. This displacement is compressing margin structures for non-stacked legacy architectures.
China's MIIT GB standards for electromagnetic compatibility in automotive-integrated cameras are tightening shielding and grounding specifications. Domestic NEV manufacturers must certify to these protocols before volume deployment, forcing foreign suppliers to establish local testing partnerships. The certification burden falls heaviest on Tier 2 module integrators lacking in-country validation facilities.
Direct foundry contracting is displacing traditional distributor channels for high-volume smartphone and automotive OEMs. Procurement teams at Xiaomi, BYD, and Tesla negotiate wafer starts directly with Samsung and TSMC, bypassing legacy semiconductor distribution. This channel compression is most advanced in China and South Korea, where captive foundry relationships dominate strategic sourcing.
Global Image Sensors Market Segmentation
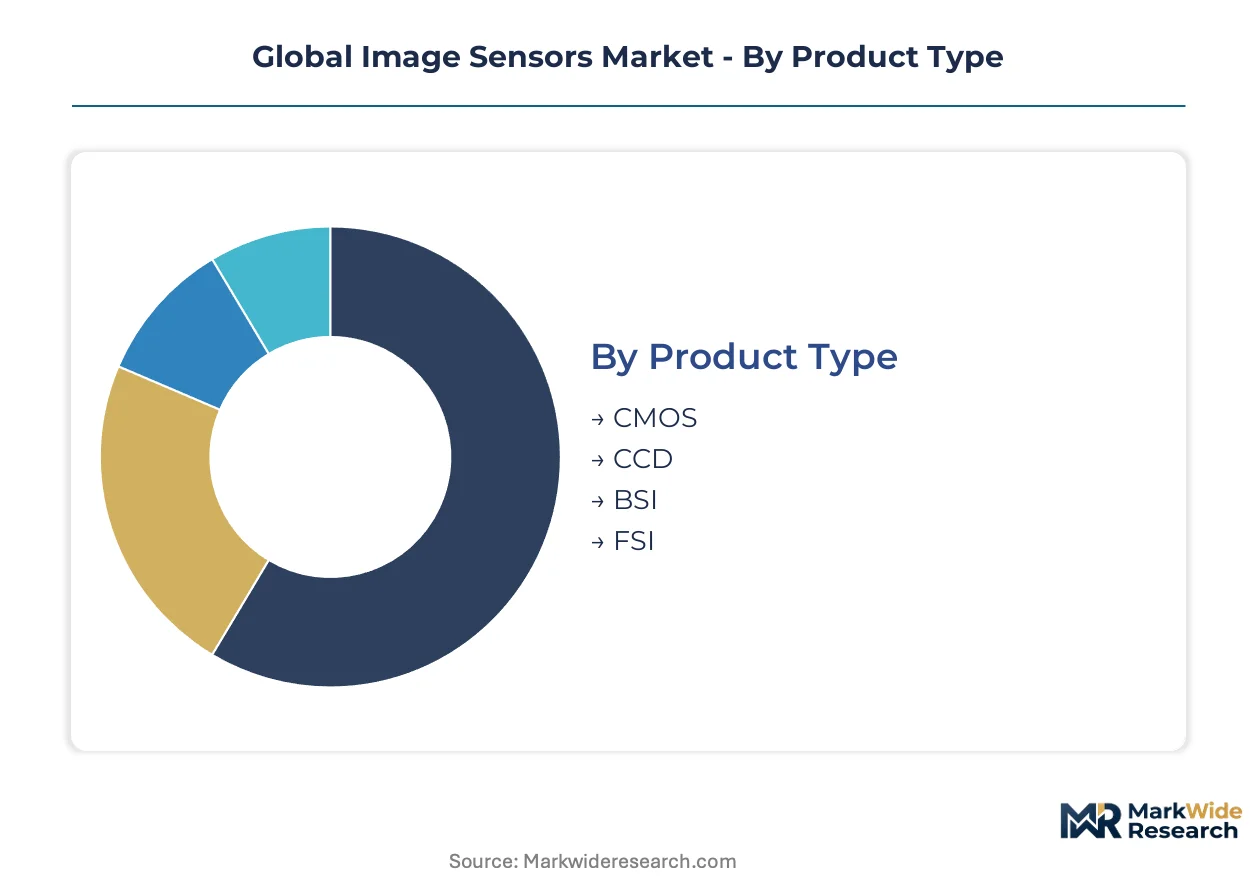
Image sensor segmentation reveals divergent sourcing patterns across technology tiers and end-use verticals. Product type splits expose domestic fabrication advantages in China against export-dependent specialty supply elsewhere.
Product Type:
CMOS and BSI architectures dominate volume procurement within Chinese smartphone and NEV supply chains, while CCD and FSI segments serve export-led industrial and scientific instrument markets.
- CMOS:Complementary metal-oxide-semiconductor pixels integrate readout circuitry on-chip, enabling low-power operation at high frame rates. Chinese OEMs source CMOS predominantly from domestic foundries to satisfy MIIT GB electromagnetic compatibility mandates for automotive camera integration.
- BSI:Backside-illuminated architectures flip the silicon wafer to expose photodiodes directly to incident light, achieving quantum efficiency above 70 percent in low-lux conditions. BYD and Xiaomi contract wafer starts directly with Samsung and TSMC for BSI supply, bypassing traditional distribution channels in vertically integrated procurement patterns.
- CCD:Charge-coupled devices maintain scientific and machine vision applications requiring uniform pixel response across large formats.
- FSI:Frontside-illuminated sensors persist in cost-sensitive industrial monitoring where pixel pitch requirements exceed 1.0µm.
CMOS commands the established base. The steepest expansion runs through BSI.
Application:
Cost tier stratification separates premium automotive qualification cycles from high-volume consumer electronics procurement, with industrial and healthcare occupying mid-tier pricing bands.
- Automotive:Surround-view and cabin-monitoring mandates from NHTSA and KBA require AEC-Q100 qualified sensors with extended temperature ranges. German OEMs source through KBA-certified Tier 1 integrators, while Chinese NEV manufacturers accelerate local BSI procurement under MIIT GB standards.
- Consumer Electronics:Smartphone camera arrays demand sub-0.7µm pixel pitches with stacked die architectures. Samsung and Sony foundries allocate dedicated capacity for flagship device programs, compressing margin structures for non-stacked alternatives.
- Industrial:Machine vision systems prioritize global shutter performance and consistent color fidelity for automated inspection workflows.
- Healthcare:Medical endoscopy applications drive miniaturization toward sub-2mm CMOS modules for disposable scope platforms.
Consumer electronics commands the established base. The steepest expansion runs through automotive.
Technology:
Volume concentration favors optical sensing for visible spectrum applications, while thermal and multispectral technologies capture defense and precision agriculture premiums through specialized foundry processes.
- Optical:Visible spectrum sensors utilizing silicon photodiode arrays span 400-700nm wavelengths. Optical sensors concentrate in Chinese and South Korean smartphone supply chains, with domestic foundries expanding dedicated CIS capacity to serve captive OEM demand.
- Thermal:Uncooled microbolometer arrays detect infrared radiation for night vision and industrial thermography. Thermal sensing depends on export-controlled germanium optics and specialized III-V foundry processes concentrated in US and European defense supply chains.
- X-ray:Direct-conversion photon-counting sensors serve medical imaging and security screening with high dynamic range requirements.
- Multispectral:Converged visible-SWIR architectures enable precision agriculture crop health monitoring and military target identification.
Optical commands the established base. Multispectral is climbing the fastest.
End User:
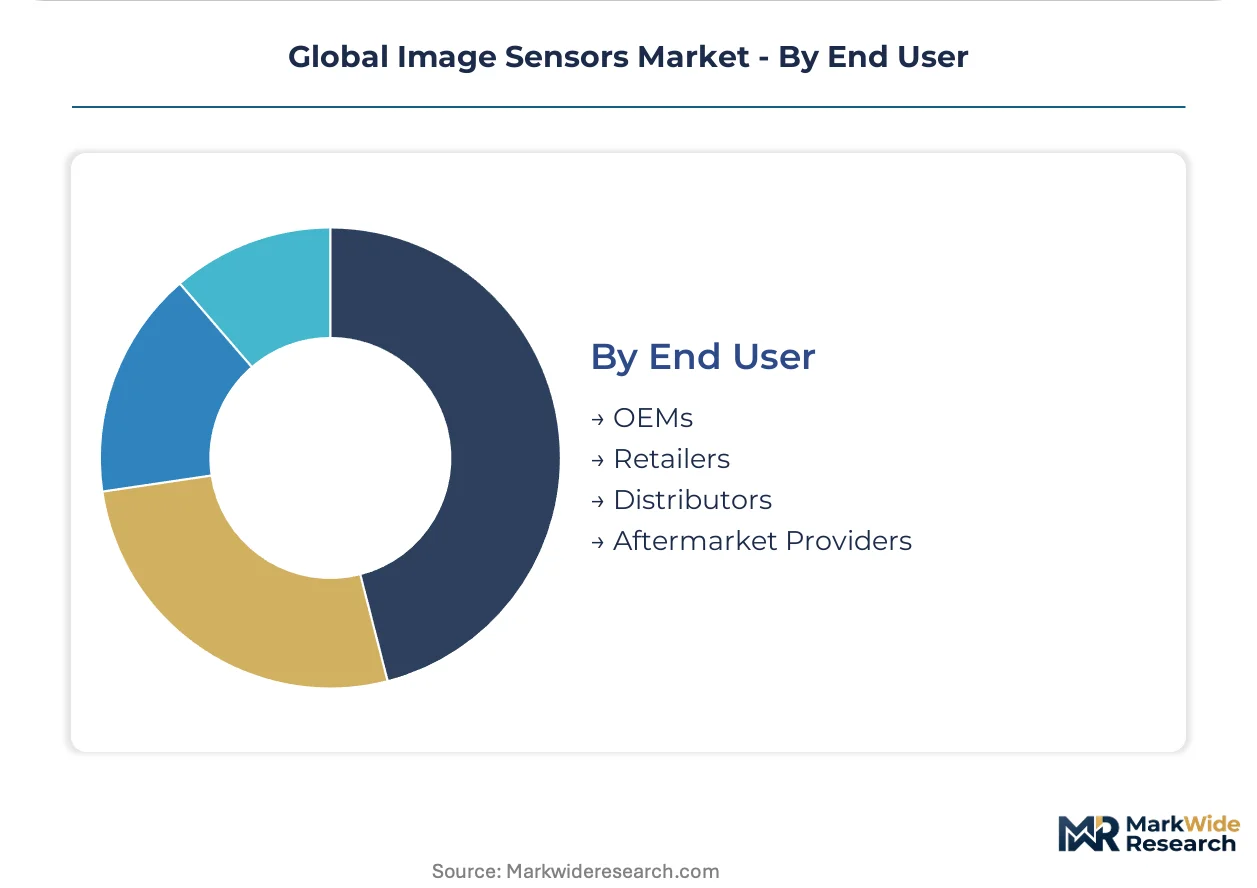
Procurement pattern divergence separates direct foundry contracting by high-volume OEMs from distributor-dependent aftermarket and retail channels.
- OEMs:Original equipment manufacturers negotiate wafer starts directly with Samsung, TSMC, and domestic Chinese foundries. Tesla and BYD procurement teams bypass legacy semiconductor distribution entirely, compressing channel margins and reshaping supplier relationship management.
- Distributors:Arrow Electronics and Avnet maintain inventory positions for mid-volume industrial and medical customers lacking direct foundry access. Distributor relationships concentrate in European and North American markets where customer fragmentation prevents direct contracting scale.
- Retailers:Consumer electronics retailers source finished camera modules through established supply chain intermediaries.
- Aftermarket Providers:Automotive retrofit and replacement camera suppliers depend on distributor inventory for legacy vehicle platform compatibility.
OEMs command the established base. The steepest expansion runs through direct foundry contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for automotive camera electromagnetic compatibility anchor Chinese procurement patterns, while NHTSA and KBA mandates reshape sourcing across North America and Europe. Foundry capacity allocation tracks regulatory divergence between safety certification and environmental compliance frameworks.
China
BYD and Xiaomi negotiate direct wafer starts with Samsung and TSMC for BSI sensor supply, bypassing legacy distribution channels entirely. MIIT enforces GB standards for electromagnetic compatibility in NEV-integrated cameras, forcing foreign suppliers into local testing partnerships. Yangtze River Delta foundries expand dedicated CIS capacity to serve captive domestic OEM demand.
United States
Tesla procurement teams contract directly with TSMC for automotive-grade CMOS fabrication, compressing channel margins for traditional semiconductor distributors. NHTSA camera-perception mandates for surround-view systems expand unit pull-through across vehicle platforms. Arizona and Texas wafer fabrication clusters attract capacity investments targeting AEC-Q100 qualified sensor production.
Germany
BMW and Volkswagen source image sensors through KBA-certified Tier 1 integrators, extending qualification cycles to 18-24 months for automotive-grade supply. The EU's F-Gas Regulation restricts fluorinated etching gases, accelerating dry etching transitions at Dresden and Bavarian fabrication facilities. REACH compliance reshapes epoxy molding compound formulations for sensor packaging materials.
Japan
Sony Corporation leverages in-house wafer processing at Kyushu facilities to sustain technology leadership in stacked CMOS architectures. METI industrial policy supports domestic 300mm CIS-grade wafer output concentrated among three specialized suppliers. Tokyo and Osaka metropolitan areas anchor precision optics and sensor module integration clusters.
South Korea
Samsung Electronics anchors high-volume BSI supply for captive smartphone demand while extending foundry services to external automotive clients. Seoul Capital Area procurement teams at Hyundai and Kia negotiate multi-year wafer allocation agreements. Busan-Ulsan packaging clusters specialize in hybrid bonding interconnects for sub-0.6µm pixel pitch production.
Global Image Sensors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive foundry relationships determining access to premium automotive and smartphone supply channels. The upper tier commands direct OEM contracting relationships, while specialists navigate extended qualification cycles for industrial and medical end uses. Two strategic archetypes dominate: vertically integrated IDMs with in-house wafer processing, and fabless designers dependent on external foundry allocation. Competitive moves concentrate on capacity reservation agreements and cross-licensing of stacked die architectures.
Within the integrated IDM tier, Sony Corporation and Samsung Electronics Co., Ltd. occupy positions defined by captive fabrication assets and direct OEM channel access. OmniVision Technologies, Inc. exemplifies the specialist archetype, navigating tight automotive qualification cycles through compact form factor expertise. These three entities represent the competitive spectrum from full vertical integration to targeted fabless specialization.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies, Inc. |
| STMicroelectronics N.V. |
| onsemi |
| Canon Inc. |
| Panasonic Holdings Corporation |
| SK Hynix Inc. |
| Himax Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
AEC-Q100 automotive qualification gates both supply access and price differentiation, compressing margins for non-certified suppliers while allowing qualified foundries to command sustained premiums across 18-24 month certification cycles.
Pricing Analysis
Chinese domestic foundries undercut Japanese and South Korean suppliers by 15-25 percent on CMOS wafer starts, though AEC-Q100 certification premiums reverse this spread for automotive-grade supply. Pricing stratifies across stacked BSI architectures, legacy FSI sensors, and commodity CCD formats, with pixel pitch below 0.7µm commanding the widest premiums. Cost compression in consumer smartphone tiers is intensifying because Chinese OEMs negotiate direct wafer allocation agreements, bypassing distributor markups. Industrial machine vision buyers exhibit highest price sensitivity, while medical endoscopy specialists accept 40-60 percent premiums for sub-2mm form factors.
Supply Chain Analysis
300mm CIS-grade silicon wafer output concentrates among three Japanese suppliers, creating single-source vulnerability for foundries expanding automotive capacity. Raw material dependencies draw from specialized silicon ingot suppliers, fluorinated etching gases restricted under EU F-Gas Regulation, and hybrid bonding equipment for sub-0.6µm pixel production. Tariff exposure runs through US-China semiconductor equipment restrictions affecting wafer fabrication tool imports. Distribution runs through direct foundry contracting for high-volume OEMs, with Arrow Electronics and Avnet serving fragmented industrial and medical accounts lacking scale for wafer-start negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive ADAS deployment cycles signal recovery momentum, with NHTSA and KBA surround-view mandates creating predictable demand visibility across vehicle platform refreshes.
For Market Incumbents: Secure multi-year wafer allocation agreements with 300mm CIS-grade silicon suppliers before capacity constraints harden. Expand in-house hybrid bonding capacity at Kyushu or Busan-Ulsan clusters to defend against Chinese foundry cost advantages. Prioritize AEC-Q100 certification pipeline investments as non-qualified suppliers face 24-month exclusion from German OEM sourcing.
For New Entrants and Emerging Players: Anchor in medical endoscopy miniaturization, where sub-2mm CMOS module demand outpaces established supplier capacity and qualification cycles remain shorter than automotive tiers. Target Indian PLI scheme packaging clusters in Gujarat and Tamil Nadu for cost-competitive test and assembly capacity. Pursue direct hospital procurement relationships for disposable scope platforms, bypassing consolidated distributor channels that favor incumbent module integrators.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by stranding etching-dependent fabrication assets and rewarding dry-etching technology portfolios. Frame long-term viability around 5-10 year automotive content-per-vehicle expansion rather than smartphone saturation exposure. Prioritize fabless designers with MIIT GB certification partnerships for Chinese NEV access. Monitor NHTSA rulemaking velocity as the signal indicating ADAS mandate acceleration or delay.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables sub-0.6µm pixel production for Samsung and Sony flagship programs. |
| AEC-Q100 Certification Investment | Unlocks German OEM sourcing through KBA-certified Tier 1 integrator relationships. |
| Direct Foundry Contracting | Bypasses distributor margins for Tesla and BYD procurement teams negotiating wafer starts. |
| India PLI Scheme Participation | Captures packaging and test cost advantages in Gujarat and Tamil Nadu clusters. |
| Multispectral Architecture Development | Opens precision agriculture and defense applications beyond visible spectrum saturation. |
Study Parameters
A standing panel of wafer foundry operations directors, Tier 1 automotive module procurement managers, medical device OEM engineering leads, and smartphone platform camera integration specialists provided ongoing calibration throughout the study. Primary interview findings combined with secondary validation from SEMI wafer shipment data, MIIT GB standard certification registries, SEC 10-K filings from listed sensor suppliers, and IHS Markit vehicle production databases. Bottom-up unit demand modeling triangulated against top-down foundry capacity allocation estimates across the analysis window.
Consistency checks validated volume and value outputs against SEMI silicon wafer area forecasts and automotive camera content-per-vehicle trajectories. Segmentation modeling spanned technology architecture, application vertical, pixel pitch tier, and regional regulatory cluster throughout the projection horizon. CAGRs derived from regression analysis of historical foundry utilization rates and forward capacity expansion announcements, with automotive ADAS mandate schedules and smartphone refresh cycles as industry-specific demand inputs.
Underlying assumptions cover sustained automotive electrification, continued China NEV volume growth, and stable fluorinated gas substitution timelines, with deviation risk concentrated in US-China semiconductor equipment trade restrictions and EU REACH material reformulation delays. Practitioners should keep alternative scenarios live as NHTSA rulemaking velocity and MIIT GB standard enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Near Infra-Red Imaging Market
Imaging
Camera with Flip Screen Market
Imaging
China Electron Microscopy Market
Imaging
Global 3D Camera Market
Imaging
Contact Image Sensor Market
Imaging
Digital Microscope Market
Imaging
Small CCTV Camera Market
Imaging
Silent Scan Technology Market
Imaging
Mobile Imaging Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Europe IP Camera Market
Imaging
SWIR Camera Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
India CCTV Camera Market
Imaging
Machine Vision Market