
 Ceramic IC Packages Market | 2026-2036
Ceramic IC Packages Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic IC Packages Market Outlook
Aftermarket thermal simulation and reliability testing revenue is tilting toward original package manufacturers as end-users seek integrated lifetime performance guarantees. KYOCERA Corporation leverages its captive alumina supply chain to dominate high-reliability aerospace sockets. CeramTec GmbH anchors European production through precision co-firing capabilities certified for space-grade applications. CoorsTek competes on scale, operating one of the largest non-oxide ceramic substrate facilities serving North American RF foundries.
Ceramic IC packages are hermetic enclosures fabricated from alumina, aluminum nitride, or beryllium oxide, formed through multilayer co-firing at temperatures exceeding 1500°C to create thermally stable, electrically insulated housings for semiconductor dies. Their primary purpose is to protect sensitive integrated circuits from moisture, thermal cycling, and corrosive environments while enabling high-frequency signal integrity. Multi-chip module formats command premium positioning as system-in-package architectures displace discrete board assemblies in radar and satellite payloads. Low-temperature co-fired ceramic technology leads volume production for consumer telecommunications, though high-temperature variants sustain margin pools in defense and medical implant applications where hermeticity failure carries catastrophic cost.
FDA device-grade hermeticity standards, EU REACH substance restrictions on beryllium compounds, and Japan METI's green procurement guidelines collectively shape material selection and testing protocols across the supply base. China's GB standards for electronic ceramics, administered by SAMR, create additional certification layers for packages entering domestic 5G base station deployments. Stakeholders must monitor divergence between regional substance restrictions and thermal performance requirements when configuring multi-source substrate strategies.
Market Dynamics
System-in-package miniaturization is compressing board real estate requirements, forcing ceramic substrate manufacturers to achieve finer line resolution and higher layer counts without sacrificing hermeticity performance in defense and aerospace applications.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is accelerating demand for hermetic ceramic enclosures as semiconductor manufacturers abandon polymer-based sealing alternatives in European-sourced equipment.
- Aluminum nitride thermal conductivity:Power electronics in electric vehicle inverters and 5G base stations require substrates with thermal conductivity exceeding 170 W/mK, pulling capacity expansion toward nitride ceramic formulations.
- Japan METI green procurement:Government procurement guidelines for environmentally conscious electronics are mandating lead-free and low-carbon ceramic package specifications across domestic telecommunications infrastructure.
Market Restraints
- Beryllium oxide toxicity liability:EU REACH substance restrictions on beryllium compounds are forcing thermal management designers toward aluminum nitride substitutes with inferior thermal performance at equivalent cost structures.
- High-temperature co-fired ceramic furnace concentration:Specialized sintering equipment for 1500°C+ processing concentrates among Japanese and German equipment suppliers, creating single-source vulnerability for capacity expansion.
- Alumina raw material price volatility:Refinery-grade alumina supply disruptions from Australian and Brazilian bauxite processing constraints are transmitting cost pressure through substrate fabrication.
Strategic Opportunities
- India PLI scheme for semiconductor packaging:Production-linked incentive structures for domestic electronics manufacturing are creating first-mover advantages for ceramic package suppliers establishing local co-firing operations.
- Photonic integrated circuit hermeticity:Silicon photonics modules for data center interconnects require optical-grade ceramic feedthroughs, opening adjacent demand beyond traditional electronic IC enclosures.
- Quantum computing cryogenic packaging:Superconducting qubit systems operating at millikelvin temperatures demand specialized low-outgassing ceramic materials with matched thermal expansion coefficients.
Industry Challenges
- Multi-physics simulation expertise:Concurrent thermal-electrical-mechanical modeling of multilayer ceramic structures requires rare cross-functional engineering talent combining materials science with RF design.
- Space-grade qualification timelines:NASA EEE-INST-002 and ESA ECSS-Q-ST-60-13C certification cycles extend 18-24 months, compressing revenue recognition for new product introductions.
- Legacy Kovar alloy integration:Mismatched coefficient of thermal expansion between traditional metal seals and advanced ceramic formulations is forcing costly redesign of established package families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic IC Packages Market |
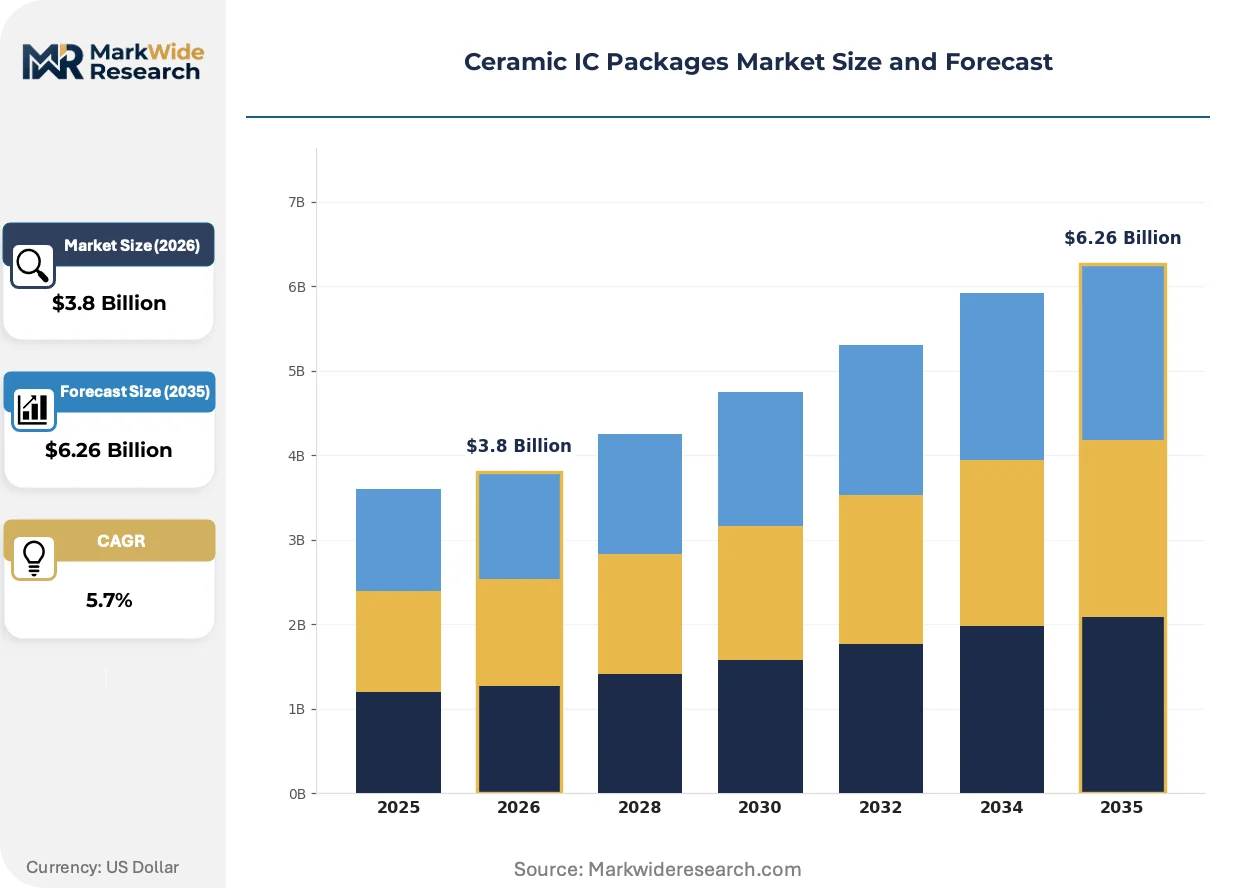
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual In-Line Package, Chip-on-Board, Lead Frame, Multi-Chip Module Technology: High-Temperature Co-fired Ceramic, Low-Temperature Co-fired Ceramic, Thick Film, Thin Film End User: Aerospace, Consumer Electronics, Telecommunications, Automotive Application: Signal Processing, Power Management, RF Communication, Data Conversion |
| Companies Covered | KYOCERA Corporation, AGC Inc., CeramTec GmbH, CoorsTek, Materion Corporation, NGK Insulators, Amkor Technology, AdTech Ceramics, Remtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic IC Packages Market Strategic Shifts
Material science breakthroughs and regulatory stringency are converging to redefine ceramic package architectures, with thermal performance and environmental compliance now co-equal design constraints rather than trade-offs.
High-purity aluminum nitride is migrating from niche military applications into commercial 5G infrastructure and automotive power modules as thermal management requirements exceed alumina capabilities. RF foundries in North America and telecommunications equipment manufacturers in South Korea are adopting nitride substrates at accelerating rates. This migration is compressing the historical price premium between nitride and oxide ceramics, eroding margin buffers that previously protected alumina-dominant suppliers.
China's GB standards for electronic ceramics, administered by SAMR, are tightening traceability and testing documentation requirements for packages entering domestic 5G base station deployments. Domestic certification layers now mandate third-party hermeticity testing at approved laboratories, extending qualification timelines. Foreign suppliers are responding by establishing joint testing protocols with Chinese certification bodies to maintain market access without duplicating entire manufacturing footprints.
Integrated lifetime performance guarantees are displacing transactional component sales as aftermarket thermal simulation and reliability testing revenue tilts toward original package manufacturers. Defense prime contractors and medical device OEMs now require predictive failure models and continuous monitoring telemetry embedded in ceramic package specifications. This behavioral shift is most visible in aerospace and implantable medical verticals, where hermeticity failure carries catastrophic liability exposure and drives preference for vertically integrated substrate-to-test suppliers.
Ceramic IC Packages Market Segmentation
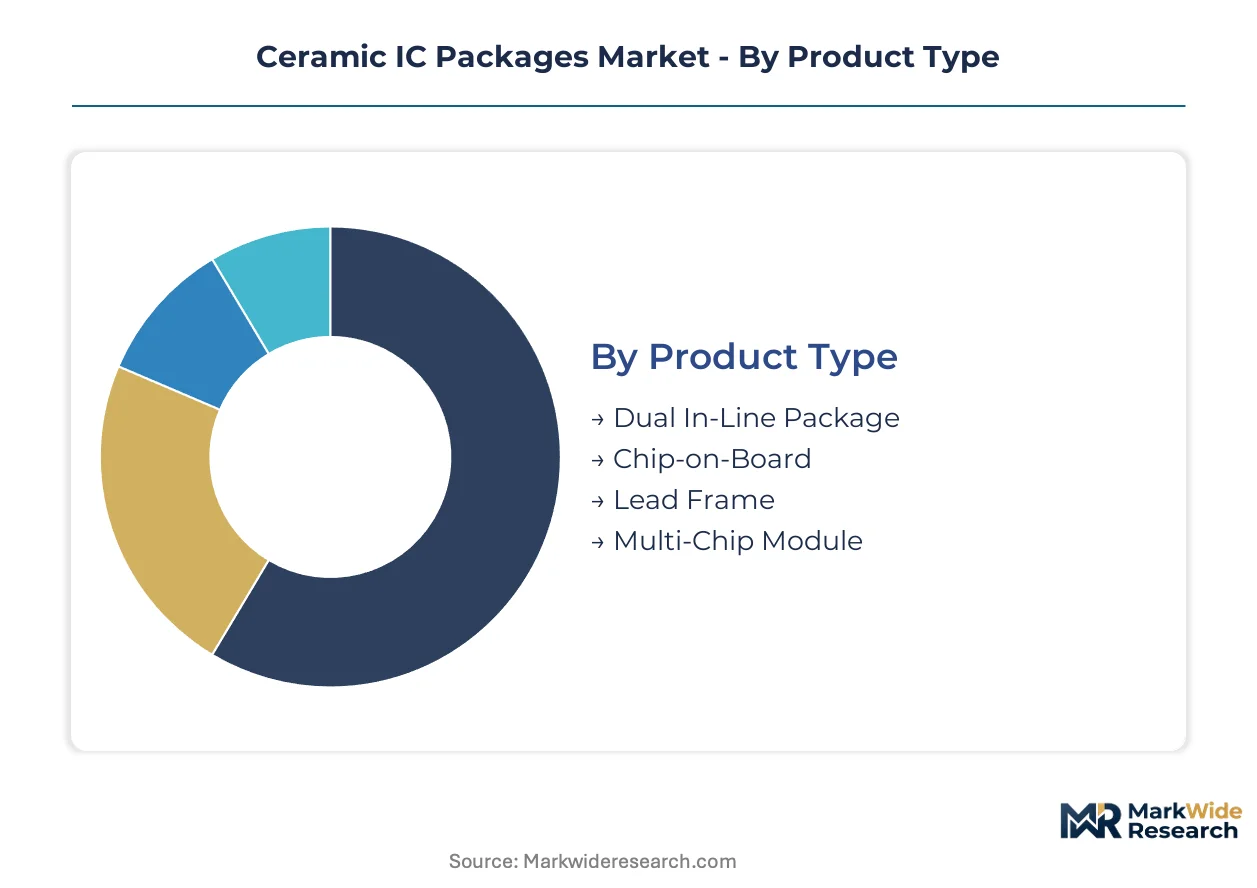
Ceramic IC package architectures diverge sharply across thermal budgets, hermeticity grades, and integration density. Segmentation reveals how material selection and co-firing technology partition margin pools between commodity telecommunications volume and premium aerospace reliability.
Product Type:
Mature through-hole formats coexist with emerging system-in-package architectures as aerospace miniaturization accelerates substrate consolidation.
- Dual In-Line Package:Legacy ceramic enclosures with parallel lead configurations remain entrenched in military-grade memory and logic devices where hermeticity certification cycles favor proven geometries. Demand concentrates in US and European defense electronics as primes resist redesigning qualified board assemblies.
- Multi-Chip Module:Three-dimensional ceramic stacking integrates multiple dies with passive components in unified hermetic housings, displacing discrete packaging in radar and satellite payloads. Japanese and South Korean RF foundries drive capacity expansion for 5G base station transceivers.
- Chip-on-Board:Direct die attach to ceramic substrates without traditional lead frames suits implantable medical devices where package height minimization is critical.
- Lead Frame:Metal-ceramic composite packages dominate automotive power module interfaces requiring matched thermal expansion with copper interconnects.
Multi-Chip Module retains volume leadership; Chip-on-Board holds the steepest expansion curve.
Technology:
Cost tiers separate furnace-intensive high-temperature processes from screen-printed alternatives serving consumer volume.
- High-Temperature Co-fired Ceramic:Sintering above 1500°C produces fully dense alumina and aluminum nitride substrates with near-zero porosity for space-grade hermeticity. Japanese furnace manufacturers control critical equipment supply, concentrating capacity buildouts in Japan, Germany, and China.
- Low-Temperature Co-fired Ceramic:Gold and silver conductor co-firing below 1000°C enables finer line resolution for consumer telecommunications, though thermal conductivity sacrifices limit deployment in power electronics. South Korean and Chinese producers dominate volume output for smartphone RF modules.
- Thick Film:Screen-printed conductor patterns on prefired ceramic substrates offer rapid prototyping for industrial sensor packaging with moderate thermal demands.
- Thin Film:Sputtered metallization achieves sub-micron precision for microwave and millimeter-wave applications in satellite communications.
Low-Temperature Co-fired Ceramic retains volume leadership; High-Temperature Co-fired Ceramic commands the steepest margin expansion.
End User:
Application risk profiles segment procurement behavior from catastrophic-failure aerospace liability to cost-optimized consumer electronics.
- Aerospace:Satellite and avionics systems demand ESA ECSS-Q-ST-60-13C and NASA EEE-INST-002 certified packages where hermeticity failure triggers mission loss. European prime contractors and US defense integrators specify captive supply chains with full traceability.
- Automotive:Electric vehicle inverters and onboard chargers pull aluminum nitride substrates for thermal management as power densities exceed alumina capabilities. German and Japanese automotive tier-1s qualify packages against AEC-Q100 stress test protocols.
- Telecommunications:5G infrastructure deployments in China operate under SAMR-administered GB standards requiring third-party hermeticity documentation at approved laboratories.
- Consumer Electronics:Cost pressure dominates material selection, with alumina substrates standard in non-hermetic applications where polymer alternatives compete.
Telecommunications retains volume leadership; Automotive is expanding most quickly as electrification accelerates thermal substrate migration.
Application:
Signal integrity requirements at frequency extremes partition ceramic formulations between microwave-grade purity and power-handling bulk.
- RF Communication:Millimeter-wave and microwave modules require low-loss tangent ceramics with precisely controlled dielectric constants for phased array antennas. North American radar foundries and South Korean base station manufacturers specify high-purity aluminum nitride for thermal-electrical performance balance.
- Power Management:Wide-bandgap semiconductor packaging for silicon carbide and gallium nitride devices demands thermal conductivity exceeding 170 W/mK, pulling formulation shifts from alumina to nitride ceramics in traction inverters.
- Signal Processing:Mixed-signal ASICs in aerospace payloads favor multi-layer co-fired ceramic for integrated passive component embedding.
- Data Conversion:High-resolution ADC and DAC packages prioritize low thermal EMF junctions between ceramic and conductor metallizations.
RF Communication retains volume leadership; Power Management is gaining share fastest as wide-bandgap device penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-temperature co-fired ceramic furnace supply concentrates among Japanese and German equipment makers, channeling capacity expansion toward East Asian electronics clusters and European aerospace corridors. China, Japan, and South Korea collectively host the fastest buildouts for multilayer ceramic substrate fabrication.
China
Domestic 5G base station deployments and electric vehicle power module demand are pulling aluminum nitride capacity expansion. SAMR-administered GB standards mandate third-party hermeticity testing at approved laboratories, extending qualification timelines for foreign suppliers. Yangtze River Delta electronics clusters around Shanghai and Suzhou concentrate LTCC volume production for consumer telecommunications.
Japan
RF foundries and satellite payload manufacturers drive premium HTCC substrate demand for millimeter-wave applications. METI green procurement guidelines mandate lead-free and low-carbon ceramic package specifications across domestic telecommunications infrastructure. Nagoya and Kyoto industrial corridors anchor precision co-firing capabilities certified for space-grade hermeticity.
United States
Defense prime contractors specify captive supply chains with full NASA EEE-INST-002 traceability for satellite and avionics systems. FDA device-grade hermeticity standards shape material selection for implantable medical electronics. Greater Boston and Pacific Northwest aerospace clusters sustain demand for legacy through-hole ceramic packages in military-grade memory devices.
Germany
Automotive tier-1 suppliers qualify aluminum nitride substrates against AEC-Q100 stress test protocols for electric vehicle inverters. EU F-Gas Regulation and REACH compliance tighten material specifications for European-sourced packages, accelerating abandonment of polymer sealing alternatives. Bavaria and Baden-Württemberg precision ceramics corridors anchor ESA ECSS-Q-ST-60-13C certified production for space applications.
South Korea
Telecommunications equipment manufacturers specify high-purity aluminum nitride for 5G base station transceivers requiring thermal-electrical performance balance. MFDS medical device regulations align with international hermeticity standards for implantable electronics. Seoul Capital Area and Busan-Ulsan industrial zones drive multi-chip module capacity expansion for RF communication modules.
Ceramic IC Packages Market Competitive Environment
Captive raw material suppliers and precision co-firing specialists split the market between cost-controlled volume production and premium reliability tiers. Japanese and German equipment makers constrain HTCC furnace availability, concentrating high-reliability capacity among established players with deep equipment relationships. Three archetypes dominate: integrated ceramics conglomerates with captive alumina supply, precision co-firing specialists certified for aerospace applications, and scale-driven substrate fabricators serving RF foundries. Competitive dynamics center on backward integration into alumina refining and joint testing protocol establishment with Chinese certification bodies.
Among integrated ceramics conglomerates, KYOCERA Corporation and NGK Insulators exemplify the captive supply chain archetype, leveraging in-house raw material control to dominate high-reliability aerospace sockets. CeramTec GmbH occupies a position within the precision co-firing specialist tier, anchoring European production through space-grade certified capabilities. CoorsTek represents the scale-driven fabricator archetype, competing on volume from one of the largest non-oxide ceramic substrate facilities serving North American RF foundries.
| Leading Market Players |
|---|
| KYOCERA Corporation |
| AGC Inc. |
| CeramTec GmbH |
| CoorsTek |
| Materion Corporation |
| NGK Insulators |
| Amkor Technology |
| AdTech Ceramics |
| Remtec |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta electronics cluster around Shanghai and Suzhou anchors global LTCC volume production, concentrating capacity among Chinese and South Korean manufacturers whose scale advantages translate into downstream pricing power over European and North American buyers facing extended qualification timelines.
Pricing Analysis
Aftermarket thermal simulation and extended reliability testing contracts now drive lifetime value capture as defense prime contractors and medical device OEMs abandon transactional component purchases. Three-tier pricing structure across aerospace-certified premium, automotive-qualified standard, and consumer-economy levels separates margin pools by certification grade and hermeticity failure liability exposure. Cost compression in LTCC consumer telecommunications is intensifying because South Korean and Chinese producers are expanding nitride ceramic capacity faster than demand absorption. Automotive power module buyers exhibit the lowest price sensitivity due to AEC-Q100 qualification barriers, while consumer electronics procurement teams drive aggressive spot-market negotiation.
Supply Chain Analysis
Amkor Technology and select Japanese precision co-firing specialists concentrate contract-manufacturing capacity for multi-chip module assembly, feeding from captive alumina refining operations in Japan and Germany alongside aluminum nitride powder synthesis in China. Raw material dependencies center on Australian and Brazilian bauxite for refinery-grade alumina, Japanese furnace equipment for HTCC sintering above 1500°C, and high-purity nitride ceramics from Chinese and South Korean chemical processors. Single-source vulnerability in Japanese and German HTCC furnace equipment creates structural supply risk for capacity expansion. Distribution runs through direct OEM qualification channels for aerospace and medical verticals, with RF foundries and automotive tier-1s procuring via authorized distributor networks with certified testing documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum nitride thermal conductivity thresholds exceeding 170 W/mK are disrupting material selection across electric vehicle inverters and 5G base stations, compressing historical formulation premiums and forcing supply base reconfiguration.
For Market Incumbents: Entrench position through backward integration into alumina refining and captive aluminum nitride powder production, securing raw material cost control against Australian bauxite supply volatility. Prioritize ESA ECSS-Q-ST-60-13C and NASA EEE-INST-002 certification maintenance to defend aerospace margin pools from emerging Chinese competitors establishing joint testing protocols with SAMR-approved laboratories.
For New Entrants and Emerging Players: Photonic integrated circuit hermeticity for silicon photonics data center interconnects represents the most penetrable entry point, as optical-grade ceramic feedthroughs sit outside established electronic IC enclosure supply relationships. Target quantum computing cryogenic packaging as a second white-space vector, where superconducting qubit systems demand specialized low-outgassing materials with matched thermal expansion coefficients absent from incumbent catalogs. Lead with collaborative testing partnerships rather than manufacturing scale.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because captive supply chain control and precision co-firing certification scarcity create durable moats against commodity substitution. Acquisition targets should prioritize precision co-firing specialists with space-grade hermeticity credentials rather than volume-scale LTCC producers facing margin compression. Monitor aluminum nitride price convergence with alumina as the inflection signal for formulation migration velocity across automotive and telecommunications verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | KYOCERA and NGK Insulators leverage captive raw material control to dominate aerospace socket pricing. |
| Joint Testing Protocol Establishment | Foreign suppliers partner with SAMR-approved laboratories to maintain China 5G base station market access. |
| Aluminum Nitride Capacity Expansion | Japanese and South Korean producers accelerate nitride ceramic buildouts for EV inverter thermal management. |
| Space-Grade Certification Investment | ESA ECSS-Q-ST-60-13C and NASA EEE-INST-002 credentials defend premium positioning against emerging competitors. |
| Photonic Feedthrough Development | Silicon photonics module suppliers create adjacent demand beyond traditional electronic IC enclosures. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ceramic package procurement managers at defense prime contractors, RF foundry process engineers, automotive tier-1 thermal management specialists, and medical device reliability engineers. Secondary validation drew from SAMR GB standards documentation, ESA ECSS-Q-ST-60-13C certification records, NASA EEE-INST-002 qualification databases, and customs trade data for alumina and aluminum nitride powder flows. Bottom-up substrate fabrication capacity estimates were triangulated against top-down end-use demand modeling across aerospace, automotive, and telecommunications verticals.
Calibration against historical capacity buildouts and qualification timeline data informed projection methodology across the analysis window. Segmentation dimensions modeled include co-firing technology tier, hermeticity grade, end-use risk profile, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating aluminum nitride thermal conductivity migration patterns and EU F-Gas Regulation phase-down impacts on polymer sealing substitution. Industry-specific forecast inputs encompassed HTCC furnace equipment delivery backlogs and AEC-Q100 stress test protocol adoption rates.
Practitioners should monitor bauxite refinery output disruptions, Japanese furnace equipment order backlogs, and SAMR certification timeline extensions for early signals of supply constraint or demand inflection. Forecasts reflect modeling assumptions around aluminum nitride price convergence velocity and space-grade qualification cycle stability. Quarterly review of ESA and NASA certification queue depths, automotive power module thermal substrate specifications, and Chinese domestic 5G deployment procurement schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market