
 Radiography Test Equipment Market | 2026-2036
Radiography Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiography Test Equipment Market Outlook
European detector foundries is rebalancing capacity toward flat-panel digital radiography sensors amid sustained order backlogs from industrial inspection clients. General Electric Company leverages its aviation heritage to anchor turbine blade inspection protocols across North American maintenance networks. YXLON International specializes in computed tomography integration for automotive powertrain validation, while Rigaku Corporation dominates semiconductor wafer defect detection through advanced X-ray diffraction systems.
Radiography test equipment encompasses ionizing and non-ionizing imaging systems that generate two-dimensional or three-dimensional representations of internal object structures, typically operating at tube voltages from 10 kV to 450 kV depending on material density and penetration requirements. These systems serve critical quality assurance functions in manufacturing, medical diagnosis, and security screening by revealing subsurface defects without destructive disassembly. Digital radiography systems lead product type deployment due to immediate image acquisition and elimination of chemical processing infrastructure, whereas computed radiography retains installed base relevance in cost-sensitive emerging markets. X-ray technology anchors the technology dimension through decades of standardization, though advanced imaging modalities including computed tomography and phased-array ultrasonics capture expanding application share in composite materials testing.
The FDA enforces 21 CFR 1020 performance standards for diagnostic X-ray systems, directly shaping product certification requirements and design specifications for equipment entering US clinical environments. EASA mandates periodic non-destructive testing under Part-M continuing airworthiness regulations, sustaining demand for portable radiography units across European maintenance, repair, and overhaul facilities. ISO 17636-1 weld inspection standards and ASME Boiler and Pressure Vessel Code Section V govern industrial radiography practices across multiple jurisdictions, creating compliance-driven replacement cycles. Stakeholders must monitor detector material transitions from amorphous silicon to CMOS-based architectures, as this technical inflection will redistribute competitive advantage among established suppliers and emerging sensor developers.
Market Dynamics
Detector material transitions from amorphous silicon to CMOS-based architectures are redistributing competitive advantage among established suppliers and emerging sensor developers, forcing capital reallocation across manufacturing footprints.
Growth Catalysts
- EASA Part-M continuing airworthiness regulations:European maintenance, repair, and overhaul facilities sustain demand for portable radiography units through mandated periodic non-destructive testing cycles.
- Pipeline inspection in the Permian Basin:Digital detector arrays are displacing film-based systems as operators seek immediate image acquisition without chemical processing infrastructure.
- METI industrial radiography promotion:Japan's Ministry of Economy, Trade and Industry advances precision manufacturing quality assurance through subsidized equipment deployment.
Market Restraints
- Amorphous silicon detector supply concentration:Foundry capacity constraints in East Asia create order backlogs that delay equipment delivery to industrial inspection clients.
- 21 CFR 1020 certification timelines:FDA performance standards for diagnostic X-ray systems impose extended product validation periods before US clinical market entry.
- Phased-array ultrasonics substitution:Composite materials testing in aerospace applications increasingly favors non-ionizing alternatives that eliminate radiation safety protocols.
Strategic Opportunities
- German aerospace manufacturing clusters:EASA airworthiness directives drive expansion of non-destructive testing programs among turbine blade and airframe producers.
- Semiconductor wafer defect detection:Advanced X-ray diffraction systems capture expanding share of front-end manufacturing quality control as node sizes shrink.
- Automotive powertrain validation:Computed tomography integration enables three-dimensional porosity analysis in electric motor housings and battery enclosures.
Industry Challenges
- ASME Boiler and Pressure Vessel Code Section V certification:Weld inspection personnel shortages delay compliance-driven replacement cycles across pressure equipment fabricators.
- Legacy computed radiography infrastructure:Cost-sensitive emerging markets retain installed film-era systems that resist digital workflow integration without substantial retraining investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiography Test Equipment Market |
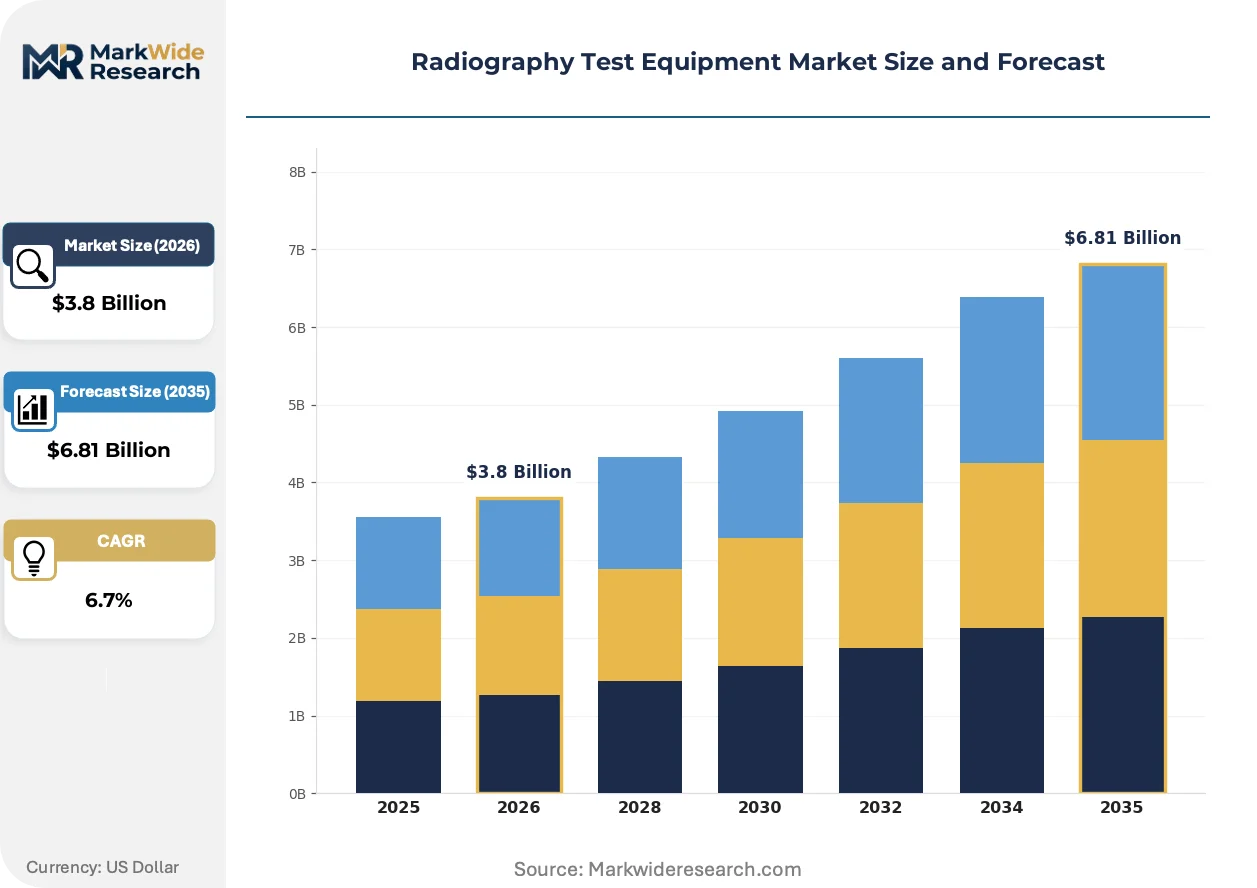
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Radiography, Computed Radiography, X-Ray Tubes, Accessories End User: Hospitals, Diagnostic Centers, Research Institutions, Dental Clinics Technology: X-Ray, Fluoroscopy, Ultrasound, Advanced Imaging Application: Orthopedics, Cardiovascular, Oncology, Pediatrics |
| Companies Covered | General Electric Company, Nikon Metrology Inc., YXLON International, Olympus Corporation, Canon Inc., Hitachi Ltd, Hamamatsu Photonics KK, Rigaku Corporation, North Star Imaging Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiography Test Equipment Market Strategic Shifts
Equipment architectures are fragmenting into configurable subsystems that permit field upgrades without full replacement, compressing capital deployment cycles and altering vendor-customer relationships across inspection services.
CMOS-based flat-panel detectors is modularizing system design by separating sensor layers from readout electronics, enabling end-users in pipeline inspection and aerospace maintenance to swap detector formats without replacing tube heads or positioning systems. This architecture reduces downtime during technology refresh cycles and permits incremental capability expansion. The shift is compressing traditional seven-to-ten-year replacement timelines into three-year upgrade intervals.
ISO 17636-1 weld inspection standards are harmonizing with ASME Section V requirements, creating unified certification pathways that reduce regulatory friction for equipment manufacturers serving multiple jurisdictions. Industrial radiography practices across fabrication shops now converge on common exposure parameters and acceptance criteria. European and North American inspection contractors benefit from interchangeable personnel qualifications and equipment validation protocols.
Service unbundling is separating hardware ownership from image analysis subscriptions, with inspection contractors in Japan and Germany purchasing detector access while outsourcing defect interpretation to specialized radiologists or AI-enabled platforms. This model shifts capital burden to utilization-based fees and accelerates technology refresh rates. Equipment vendors respond with tiered platform access rather than perpetual licensing structures.
Radiography Test Equipment Market Segmentation
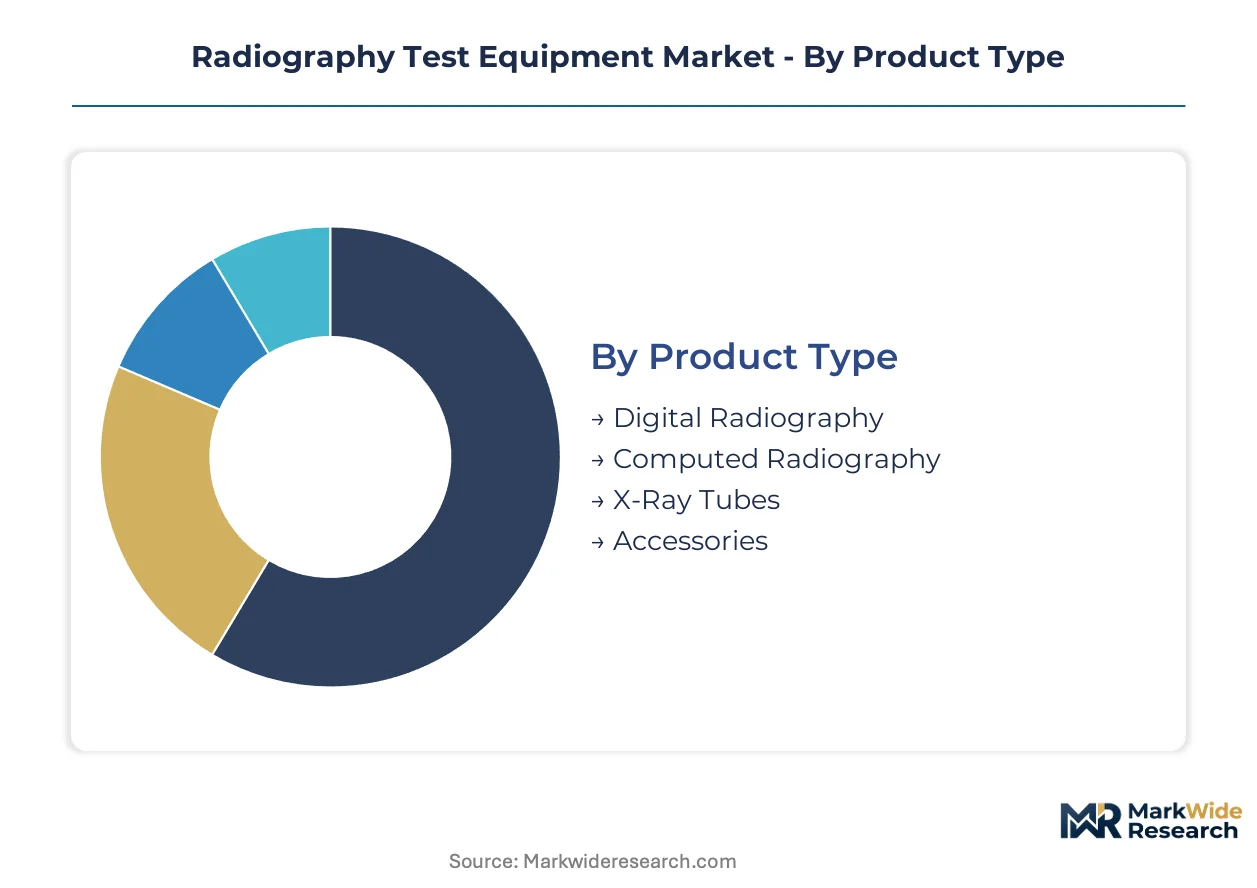
Radiography equipment purchasing follows distinct technical and economic logics across healthcare and industrial verticals. Buyer priorities diverge sharply between immediate image acquisition needs and legacy infrastructure preservation.
Product Type:
Capital allocation decisions hinge on workflow speed versus total cost of ownership across detector technologies.
- Digital Radiography:Flat-panel CMOS and amorphous silicon detectors deliver instantaneous image capture without chemical processing. Pipeline operators in the Permian Basin favor these systems for corrosion monitoring where downtime costs exceed equipment premiums.
- Computed Radiography:Photostimulable phosphor plates bridge analog-to-digital workflows using existing cassette infrastructure. Cost-sensitive emerging markets retain these systems where full detector replacement strains capital budgets.
- X-Ray Tubes:Tungsten-rhenium filament assemblies generating 10-450 kV outputs remain the core energy source across all system architectures.
- Accessories:Positioning systems, collimators, and shielding enclosures complete integrated inspection platforms.
Volume sits with Digital Radiography; growth tilts toward Computed Radiography in budget-constrained installations.
End User:
Procurement scale and regulatory exposure shape vendor relationships across clinical and research environments.
- Hospitals:Integrated health systems deploy enterprise-wide digital radiography networks to satisfy Joint Commission accreditation and maximize throughput in emergency departments.
- Diagnostic Centers:Specialized imaging facilities concentrate volume in outpatient musculoskeletal and chest examinations where rapid turnaround drives referral patterns.
- Research Institutions:Universities and national laboratories operate custom-configured systems for materials science and biological specimen analysis.
- Dental Clinics:Intraoral and panoramic systems dominate this segment with compact footprints and reduced shielding requirements.
Revenue concentrates in Hospitals; expansion tilts toward Diagnostic Centers capturing ambulatory migration.
Technology:
Physics fundamentals and safety protocols determine adoption ceilings across ionizing and non-ionizing modalities.
- X-Ray:Attenuation-based projection imaging remains the reference standard for bone and metallic defect detection across aerospace and medical applications.
- Fluoroscopy:Continuous X-ray emission enables real-time guidance during interventional cardiology and orthopedic procedures.
- Ultrasound:Phased-array systems penetrate composite materials without radiation safety protocols, gaining share in aircraft maintenance.
- Advanced Imaging:Computed tomography and tomosynthesis reconstruct three-dimensional volumes for porosity analysis in battery enclosures and turbine castings.
Installed base favors X-Ray; capability expansion tilts toward Advanced Imaging for dimensional inspection.
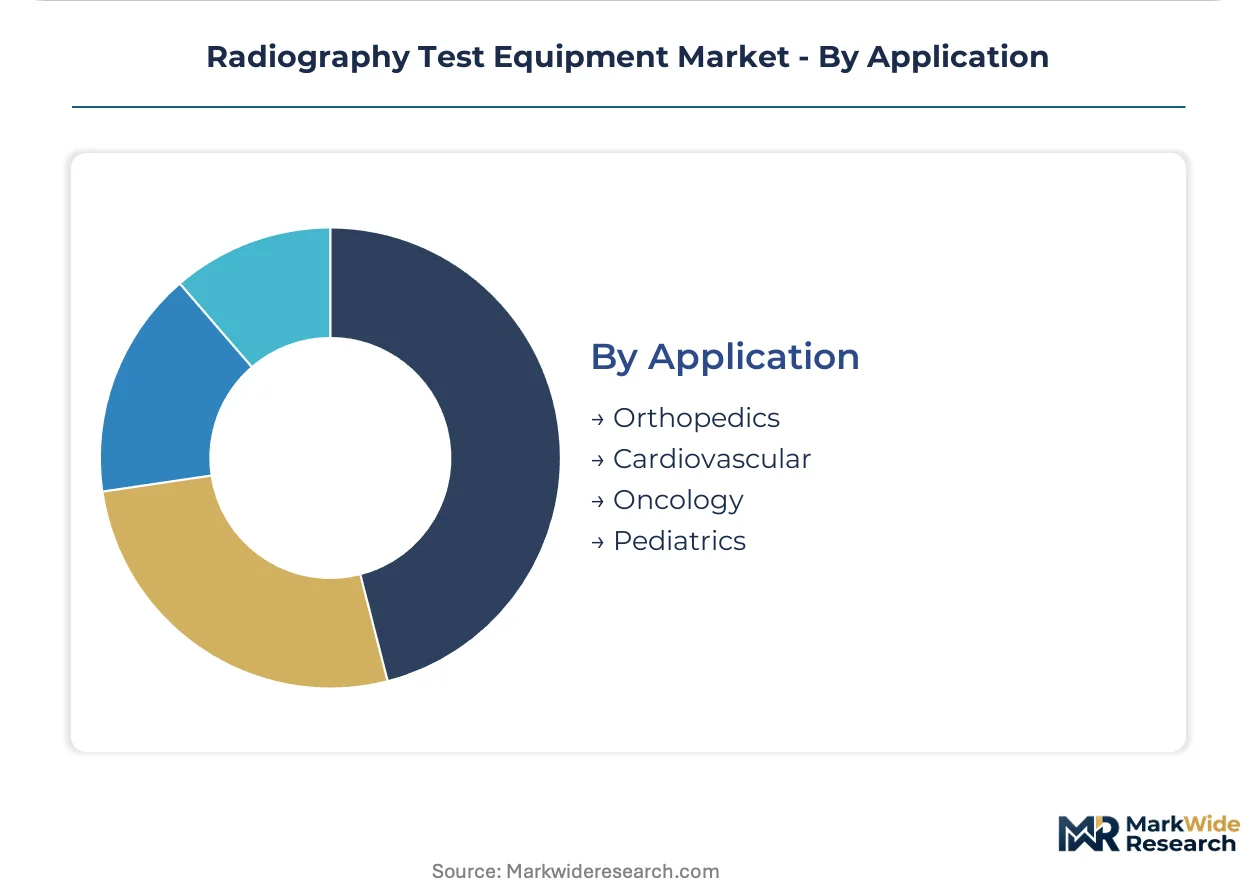
Application:
Clinical indication prevalence and reimbursement levels direct R&D investment across therapeutic areas.
- Orthopedics:Trauma, joint replacement, and spinal procedures generate sustained volume for weight-bearing extremity and full-spine systems.
- Cardiovascular:Coronary angiography and structural heart interventions demand high-frame-rate fluoroscopy with advanced dose management.
- Oncology:Staging and treatment response monitoring utilize chest and skeletal surveys with low-dose protocols.
- Pediatrics:Size-specific exposure parameters and child-appropriate positioning equipment address radiation sensitivity in developing patients.
Procedure volume concentrates in Orthopedics; technology refresh tilts toward Cardiovascular for structural heart expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten-rhenium filament supply chains concentrate in Chinese and Russian mining districts, anchoring detector manufacturing cost structures across East Asian foundries serving industrial inspection networks worldwide.
United States
Pipeline operators in the Permian Basin deploy digital detector arrays for corrosion monitoring, displacing film-based workflows. FDA enforces 21 CFR 1020 performance standards that shape product certification timelines for diagnostic X-ray systems entering clinical environments. Houston and Midland anchor energy-sector inspection demand where downtime costs exceed equipment premiums.
Germany
Aerospace manufacturers expand non-destructive testing programs to satisfy EASA Part-M continuing airworthiness directives for turbine blade validation. EASA mandates periodic NDT cycles across European maintenance, repair, and overhaul facilities. Munich and Hamburg clusters concentrate computed tomography integration for automotive powertrain quality assurance.
Japan
Precision manufacturing quality assurance drives METI-subsidized industrial radiography deployment across semiconductor and automotive supply chains. METI promotes advanced imaging for defect detection as node sizes shrink. Yokohama and Nagoya house front-end manufacturing quality control operations utilizing X-ray diffraction systems.
China
Domestic detector foundries rebalance capacity toward flat-panel digital radiography sensors amid sustained order backlogs from industrial inspection clients. MIIT oversees standards alignment for equipment entering domestic and export markets. Shenzhen and Suzhou clusters manufacture CMOS-based architectures that redistribute competitive advantage among sensor developers.
South Korea
Semiconductor wafer fabrication facilities demand advanced defect detection systems as process nodes advance below nanometer thresholds. MFDS regulates diagnostic equipment performance for clinical applications. Seoul and Pyeongtaek concentrate memory and logic chip manufacturing where dimensional inspection requirements intensify.
Radiography Test Equipment Market Competitive Environment
Global majors compete with regional champions across detector technology and application specialization, producing a tiered structure where scale-driven conglomerates anchor aviation and energy segments while mid-size specialists capture automotive and semiconductor niches. The competitive field separates into three archetypes: diversified industrial conglomerates with aviation heritage, dedicated metrology specialists with computed tomography focus, and precision optics houses with sensor manufacturing integration. Dominant moves include strategic partnerships for detector material transitions and geographic expansion into German aerospace clusters.
Among diversified industrial conglomerates, General Electric Company exemplifies scale-driven positioning anchored in aviation maintenance networks, while YXLON International occupies a specialist tier focused on computed tomography integration. Rigaku Corporation represents precision optics integration within semiconductor quality control segments. These three entities illustrate how competitive advantage redistributes across detector architecture transitions and end-market concentration patterns.
| Leading Market Players |
|---|
| General Electric Company |
| Nikon Metrology Inc. |
| YXLON International |
| Olympus Corporation |
| Canon Inc. |
| Hitachi Ltd |
| Hamamatsu Photonics KK |
| Rigaku Corporation |
| North Star Imaging Inc. |
| Others |
Value Chain & Pricing Dynamics
EASA Part-M continuing airworthiness mandates gate qualified supply access for European aerospace maintenance facilities, with certified detector suppliers commanding premium-tier pricing against uncertified alternatives. Compliance-driven procurement concentrates purchasing power among validated vendors, compressing margins for second-tier suppliers unable to absorb certification overhead.
Pricing Analysis
Warranty and field-service bundling separates premium CMOS detector suppliers from unbundled hardware-only vendors in the radiography equipment market. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution grades and ISO 17636-1 certification status. Pricing pressure stems from semiconductor foundry capacity constraints in East Asia, which elongate delivery timelines and force buyers toward spot-market premiums. Pipeline operators in the Permian Basin exhibit lowest price sensitivity due to downtime cost structures, while emerging market fabricators retain legacy computed radiography systems to avoid capital replacement.
Supply Chain Analysis
Refurbishment and remanufacturing flows for amorphous silicon detector panels create secondary supply channels that compete with new CMOS architectures. Tungsten-rhenium filament production concentrates in Chinese and Russian mining districts, while CMOS sensor fabrication anchors in Taiwan, South Korea, and Japan. Raw material dependencies span rare earth elements for scintillator crystals, high-purity silicon wafers, and precision tungsten alloys. Single-source vulnerability in East Asian foundry capacity represents the dominant structural risk. Distribution runs through authorized service networks for clinical systems and direct OEM relationships for industrial inspection clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiography test equipment market sits in a detector technology-transition phase, with CMOS-based flat-panel architectures displacing amorphous silicon legacy systems across aerospace and pipeline inspection verticals.
For Market Incumbents: To counter phased-array ultrasonics substitution in composite materials testing, anchor defensive positioning through backward integration into CMOS sensor fabrication and captive supply of tungsten-rhenium filament assemblies. Accelerate certification investment for EASA Part-M and FDA 21 CFR 1020 compliance to maintain preferred vendor status in regulated aerospace and clinical environments. For New Entrants and Emerging Players: Enter via modular detector subsystem supply, targeting cost-sensitive emerging markets where legacy computed radiography infrastructure resists full replacement. White-space concentration sits in automotive powertrain validation for electric vehicle battery enclosure inspection, with go-to-market leverage through tiered platform access models that separate hardware from AI-enabled defect interpretation subscriptions. For Investors and Strategic Acquirers: Foundry order backlog duration is the leading indicator that CMOS detector supply constraints will persist, favoring asset-light inspection service platforms over capital-intensive hardware manufacturing. Target acquisition archetypes include specialized computed tomography integrators with automotive powertrain validation relationships and precision optics houses with sensor manufacturing integration. Long-term viability hinges on detector material transition completion and service unbundling penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Detector Architecture Transition | Redistributes competitive advantage among established suppliers and emerging sensor developers across East Asian foundries. |
| Service Unbundling and Subscription Models | Shifts capital burden from hardware ownership to utilization-based fees for inspection contractors in Japan and Germany. |
| EASA Part-M Certification Investment | Sustains demand for portable radiography units across European maintenance, repair, and overhaul facility networks. |
| Automotive Powertrain CT Integration | Enables three-dimensional porosity analysis in electric motor housings and battery enclosures for EV manufacturers. |
| Pipeline Inspection Digital Migration | Displaces film-based systems in the Permian Basin through immediate image acquisition without chemical processing infrastructure. |
Study Parameters
Multi-period observation of detector order backlogs, certification timeline extensions, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with maintenance directors at aerospace MRO facilities, biomedical engineers at hospital purchasing committees, plant engineers at pressure equipment fabricators, and aftermarket service heads at industrial inspection contractors. Secondary validation drew from FDA 510(k) filings, EASA airworthiness directives, ASME Boiler and Pressure Vessel Code Section V updates, and customs trade data for tungsten-rhenium filament imports. Bottom-up equipment shipment tracking and top-down end-market demand sizing provided triangulation.
Segment-weighting approaches distributed value across product type, end user, technology, and application dimensions, with additional granularity for regional regulatory cluster variations. CAGRs were derived from equipment replacement cycle compression, technology transition velocity, and compliance-driven procurement timing. Industry-specific forecast inputs included semiconductor node shrinkage rates affecting wafer defect detection demand and EASA airworthiness directive revision frequency.
Revisions become necessary when detector material transition timelines accelerate, phased-array ultrasonics substitution rates exceed projected thresholds, or foundry capacity expansion in East Asia resolves current order backlogs. Material deviation in these triggers warrants pause and re-evaluation of competitive positioning assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Pump Testers Market
Test and Measurement
Tube Tester Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
LCR Meter Market
Test and Measurement
Curve Tracer Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Sound Meter Market