
 Machine Vision Camera Market | 2026-2036
Machine Vision Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Vision Camera Market Outlook
EU AI Act compliance is restructuring capital deployment across machine vision suppliers, forcing firmware traceability and risk-class documentation for every camera deployed in automated inspection. Cognex Corporation leverages its in-house algorithm development to absorb these compliance costs without external certification dependencies. Basler AG anchors its competitive position through captive sensor partnerships and streamlined CE marking workflows. Teledyne Technologies Inc. competes by extending its radiation-hardened camera expertise into semiconductor wafer inspection where regulatory thresholds are most stringent.
A machine vision camera captures and digitizes optical images for automated analysis, typically employing CMOS or CCD sensors with resolutions spanning VGA to 100+ megapixels and frame rates from 30 fps to over 100,000 fps for high-speed line scan variants. These devices convert photonic data into structured digital signals for industrial process control, metrology, and robotic guidance. Smart cameras integrate embedded processing directly on the imager, capturing margin pools in distributed quality control architectures where PC-tethered setups prove too costly or fragile. 3D cameras using structured light or time-of-flight methods represent the fastest-expanding technology segment as bin-picking and dimensional verification applications multiply across logistics and automotive assembly.
FDA 21 CFR Part 820 quality system regulations govern machine vision systems deployed in US medical device manufacturing, while the EU MDR extends conformity obligations to cameras used in surgical navigation and diagnostic imaging workflows. China's NMPA and GB standards impose electromagnetic compatibility and optical safety testing on imported vision equipment, creating divergent certification burdens for multinational suppliers. Stakeholders must monitor how divergent AI governance frameworks between Brussels and Beijing reshape product architecture decisions and regional go-to-market sequencing.
Market Dynamics
EU AI Act conformity requirements are forcing machine vision suppliers to re-architect firmware development workflows, embedding traceability documentation and risk-classification protocols directly into sensor production pipelines.
Growth Catalysts
- Automotive defect detection mandates:Assembly line automation in Germany's Stuttgart-Munich corridor drives high-speed camera deployment for paint, weld, and dimensional verification.
- EU AI Act safety-critical classification:Vision systems deployed in automated inspection must now carry documented conformity assessments, expanding addressable market for certified hardware suppliers.
- 3D structured light adoption:Bin-picking applications in logistics hubs accelerate demand for depth-sensing cameras with sub-millimeter accuracy.
Market Restraints
- CMOS sensor supply concentration:Foundry capacity constraints in East Asia create allocation bottlenecks for high-resolution imagers above 25 megapixels.
- FDA 21 CFR Part 820 compliance costs:Medical device manufacturers face extended validation timelines for vision systems used in surgical navigation, stretching sales cycles.
- PC-tethered system substitution:Smart cameras with embedded processing displace traditional camera-link architectures, compressing margins for peripheral component suppliers.
Strategic Opportunities
- India industrial automation corridor:PLI scheme incentives for electronics manufacturing attract vision system deployment for quality control in smartphone and component assembly.
- Semiconductor wafer inspection expansion:Radiation-hardened camera expertise transfers to EUV lithography metrology, opening premium pricing tiers.
- China NMPA electromagnetic compatibility harmonization:Streamlined GB standards testing for imported equipment reduces dual-certification burdens for multinational suppliers.
Industry Challenges
- Embedded vision engineering talent scarcity:Shortage of firmware developers capable of optimizing ISP pipelines for real-time edge inference limits smart camera rollout velocity.
- Multi-regulatory certification parallelism:Simultaneous FDA, EU MDR, and NMPA submission requirements fragment R&D resources and delay product launches.
- Legacy M12 lens mount incompatibility:Existing installed bases resist migration to C-mount and F-mount systems, slowing 3D camera adoption in retrofit-heavy automotive plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Vision Camera Market |
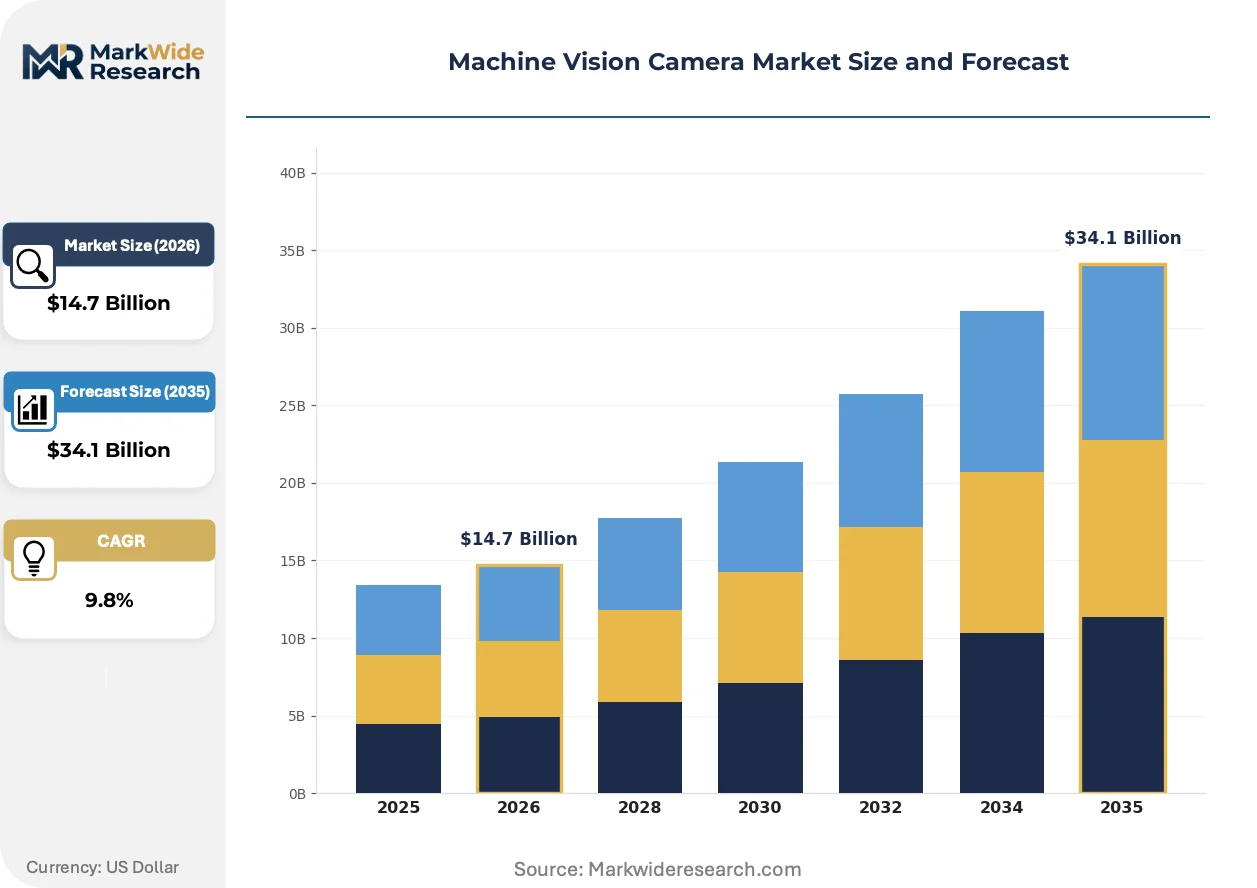
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $34.1 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, Smart Cameras, Line Scan Cameras, 3D Cameras Technology: CMOS, CCD, Infrared, Laser Application: Quality Control, Robotics, Autonomous Vehicles, Medical Imaging End User: Manufacturing, Healthcare, Transportation, Food & Beverage |
| Companies Covered | Cognex Corporation, KEYENCE Corporation, Basler AG, Teledyne Technologies Inc., OMRON Corporation, Allied Vision Technologies GmbH, Adimec Advanced Image Systems, SICK AG, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Vision Camera Market Strategic Shifts
Computational photography techniques and edge-native processing architectures are collapsing the traditional boundary between image capture and real-time analysis, compressing system footprints while expanding deployment contexts.
Time-of-flight sensors are integrating directly into compact smart camera enclosures, enabling millimeter-accurate depth mapping without external laser projectors. Automotive tier-one suppliers in Germany and Japan are adopting these modules for in-line dimensional verification at conveyor speeds exceeding 2 meters per second. The technology is integrating quality control steps previously requiring separate metrology stations, reducing floor space requirements by consolidating inspection functions.
EU MDR Article 10 technical documentation requirements now extend to cameras used in diagnostic imaging workflows, mandating clinical performance evidence and post-market surveillance protocols. Manufacturers must maintain quality management systems audited against harmonized standards, with notified body involvement for Class IIa and above devices. Surgical navigation camera suppliers are responding by pre-validating software algorithms against reference datasets before CE marking submission.
Buyer preference for outcome-guaranteed performance contracts is displacing traditional hardware-plus-software procurement in pharmaceutical packaging inspection. End-users in the United States and Switzerland now specify defect detection rates and false-positive thresholds as contractual KPIs, transferring operational risk to system integrators. This shift concentrates purchasing authority among quality engineering departments rather than procurement functions, lengthening evaluation cycles but increasing vendor stickiness post-installation.
Machine Vision Camera Market Segmentation
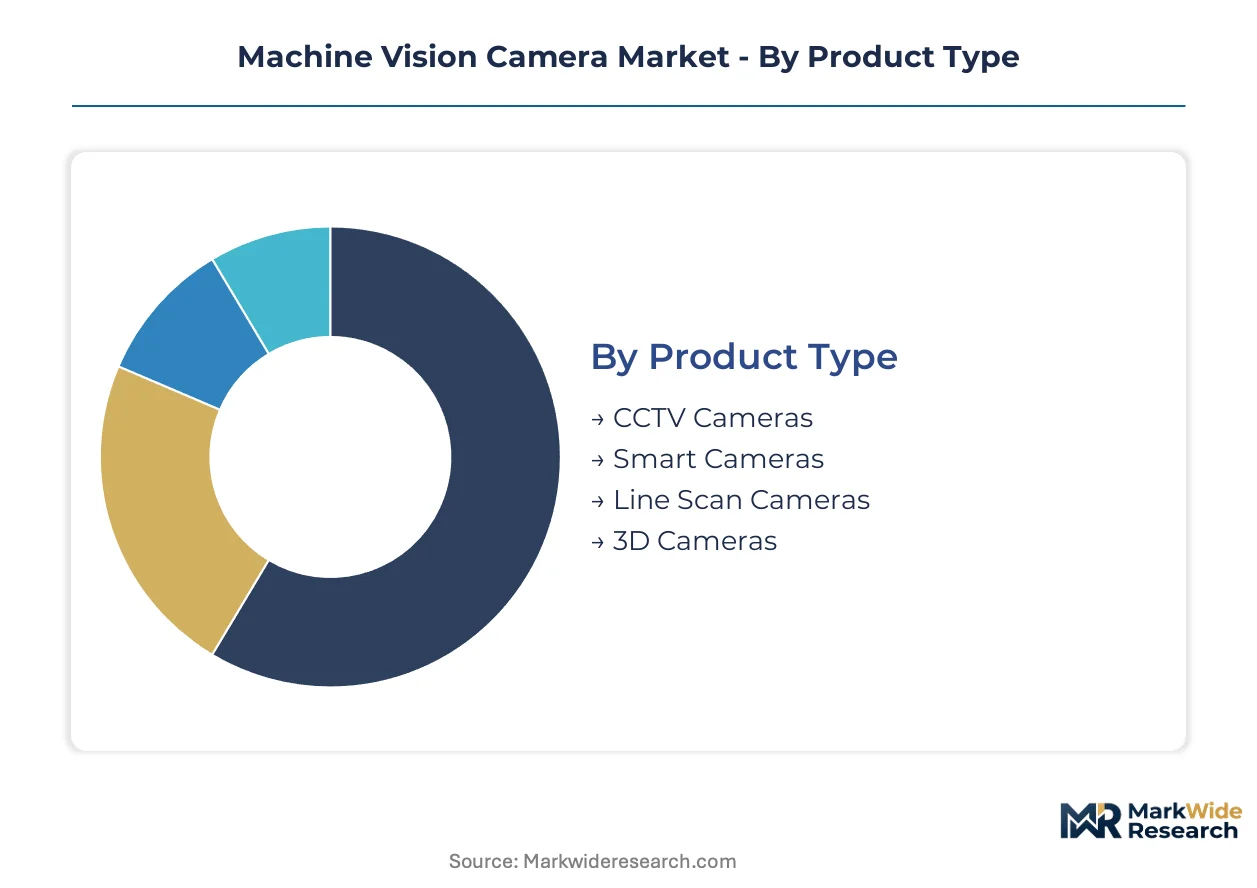
Segmentation in the machine vision camera market reveals how buyer priorities diverge across automation maturity levels and regulatory exposure. Procurement patterns cluster around processing architecture preferences, sensor technology trade-offs, and end-use certification requirements.
Product Type:
Buyers select product architecture based on processing location, cabling constraints, and inspection throughput requirements.
- Smart Cameras:Embedded processors execute inspection algorithms directly on the imager, eliminating PC dependencies in harsh factory environments. Automotive manufacturers in Germany's Stuttgart-Munich corridor deploy these for weld seam verification where vibration and electromagnetic interference degrade tethered systems. EU AI Act firmware traceability mandates favor suppliers with in-house algorithm development.
- 3D Cameras:Structured light and time-of-flight sensors capture depth data for dimensional verification and bin-picking operations. Logistics hubs across Germany and Japan integrate these modules for sub-millimeter accuracy at conveyor speeds exceeding 2 meters per second. The technology consolidates previously separate metrology stations.
- Line Scan Cameras:High-speed variants achieve frame rates above 100,000 fps for continuous web inspection in printing and film manufacturing.
- CCTV Cameras:Surveillance-optimized designs with lower frame rates serve perimeter monitoring and process documentation roles.
Smart cameras lead on scale; 3D cameras lead on momentum.
Technology:
Sensor selection hinges on resolution requirements, low-light performance, and foundry allocation timelines.
- CMOS:Dominant sensor architecture enabling high frame rates and on-chip integration at lower power consumption. Foundry capacity constraints in East Asia create allocation bottlenecks for imagers above 25 megapixels, stretching lead times for semiconductor wafer inspection equipment.
- CCD:Legacy technology retained for applications demanding superior dynamic range and uniform noise characteristics. Scientific imaging and certain metrology workflows specify CCD for measurement repeatability despite higher cost and power draw.
- Infrared:Non-visible spectrum sensors penetrate obscurants for thermal process monitoring and night-vision automation.
- Laser:Coherent light sources enable structured light projection and time-of-flight depth calculation in compact enclosures.
CMOS dominates volume; 3D-enabled laser projection climbs the fastest.
Application:
Application segmentation tracks how inspection tasks map to hardware specifications and regulatory classification.
- Quality Control:Defect detection on assembly lines drives the largest deployment base, with paint verification and dimensional checks commanding premium sensor specifications. FDA 21 CFR Part 820 and EU MDR extend validation timelines for pharmaceutical and medical device manufacturing.
- Robotics:Guidance cameras for pick-and-place and assembly operations require low-latency data streams and robust calibration protocols.
- Autonomous Vehicles:Cameras for navigation and obstacle detection face ISO 26262 functional safety requirements and NHTSA documentation standards.
- Medical Imaging:Surgical navigation and diagnostic workflows trigger EU MDR Article 10 technical documentation and clinical performance evidence mandates.
Quality control anchors revenue; medical imaging faces the steepest regulatory barriers.
End User:
End-user segmentation reflects divergent certification burdens and automation investment cycles.
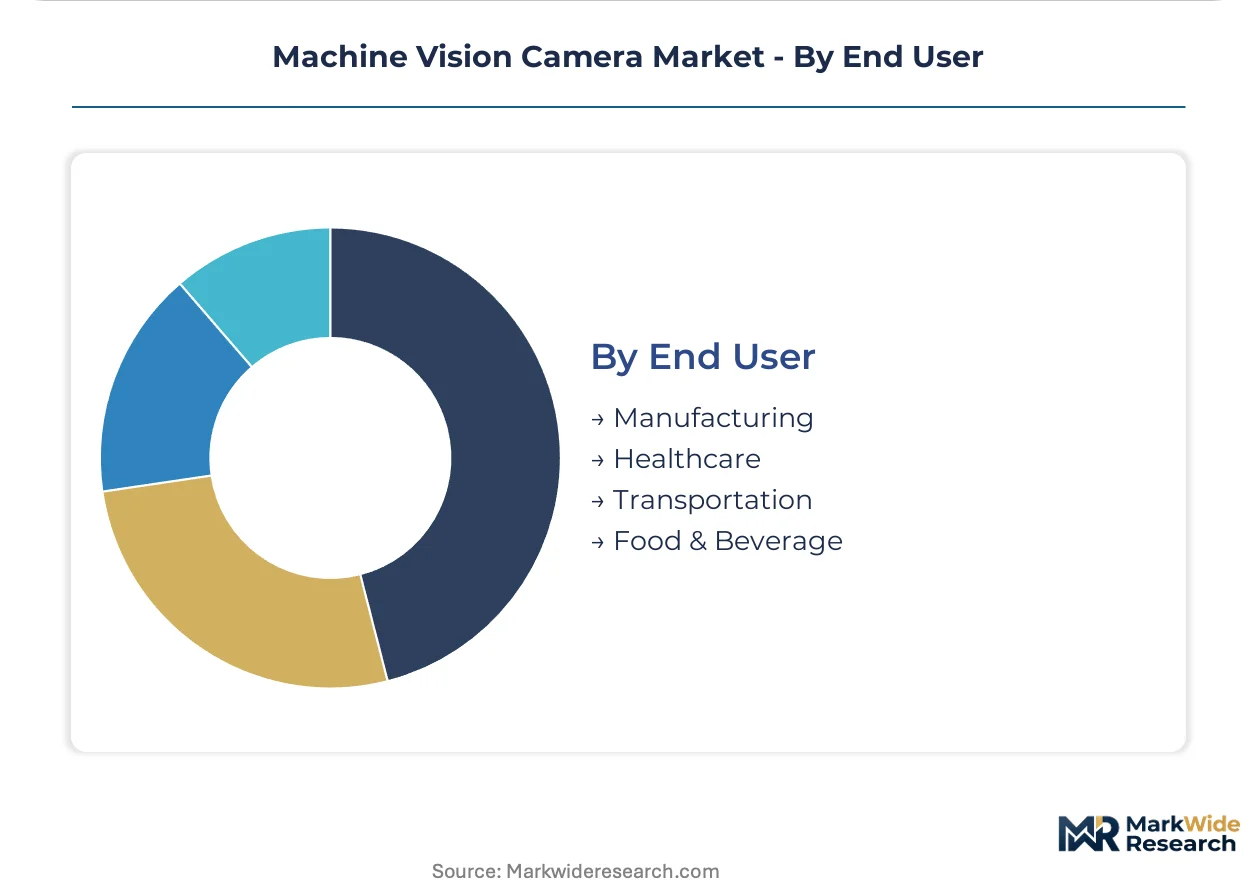
- Manufacturing:Automotive and electronics assembly lines generate concentrated demand for high-speed inspection, with Germany's industrial automation corridor representing a significant cluster. Outcome-guaranteed performance contracts now specify defect detection rates and false-positive thresholds.
- Healthcare:Medical device manufacturers and hospital systems require FDA, EU MDR, and NMPA compliance, fragmenting R&D resources across submission pathways.
- Transportation:Logistics hubs and automotive tier-one suppliers adopt 3D cameras for bin-picking and dimensional verification.
- Food & Beverage:Packaging inspection prioritizes throughput and hygiene-rated enclosures over sub-pixel measurement precision.
Manufacturing commands the largest installed base; healthcare imposes the most complex certification parallelism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine vision camera manufacturing originated in Germany and Japan during the 1980s factory automation wave, with both countries retaining dominant positions in precision optics and industrial sensor engineering. Demand diffusion now spans automotive assembly corridors, semiconductor foundry zones, and pharmaceutical packaging hubs across multiple continents.
Germany
Automotive defect detection mandates from BMW, Mercedes-Benz, and Volkswagen drive dense camera deployment across paint shops and weld lines. EU AI Act conformity assessments now accompany every safety-critical vision system installation, extending sales cycles but expanding certified supplier margins. Stuttgart and Munich anchor the country's industrial automation corridor, hosting concentrated integration facilities for bin-picking and dimensional verification systems.
United States
Semiconductor wafer inspection and pharmaceutical packaging lines generate premium demand for FDA-validated vision hardware. FDA 21 CFR Part 820 quality system regulations govern medical device manufacturing deployments, requiring extensive algorithm validation documentation. Greater Boston and Silicon Valley clusters concentrate metrology equipment development, with Arizona fabs driving recent high-resolution camera procurement.
China
Electronics contract manufacturers deploy vision systems for smartphone assembly quality control at massive scale. NMPA electromagnetic compatibility testing and GB standards optical safety requirements impose dual-certification burdens on imported equipment. Yangtze River Delta manufacturing zones around Shanghai and Suzhou represent the densest installation base for PC-tethered and smart camera architectures.
Japan
Automotive tier-one suppliers and robotics integrators sustain demand for compact, high-reliability camera modules. METI industrial automation incentives and JIS standards harmonization streamline domestic procurement while complicating foreign equipment entry. Nagoya's Chubu region and Osaka's Kansai manufacturing belt concentrate precision machinery production requiring sub-pixel inspection accuracy.
South Korea
Memory chip and display panel manufacturers drive specialized demand for line scan cameras achieving frame rates above 50,000 fps. MFDS medical device regulations and KOSHA industrial safety standards apply to vision systems in pharmaceutical packaging and heavy machinery guarding. Seoul Capital Area fabs and Busan-Ulsan logistics hubs represent dual demand poles for 3D depth-sensing and high-speed inspection cameras.
Machine Vision Camera Market Competitive Environment
The competitive structure tilts toward technology-integrated specialists rather than pure component suppliers. Tier-one positions concentrate among firms controlling sensor supply relationships and embedded algorithm development. Three archetypes dominate: captive sensor partnerships exemplified by German optics houses, in-house algorithm development represented by US automation platforms, and radiation-hardened specialization anchored in aerospace-derived suppliers. Competitive moves center on firmware traceability investments for EU AI Act compliance and backward integration into custom ISP pipeline design.
Within the algorithm-integrated tier, Cognex Corporation and Teledyne Technologies Inc. exemplify contrasting strategic positions. Cognex anchors the Massachusetts-based automation software tradition with embedded processing capabilities. Teledyne occupies the California-industrial conglomerate archetype, leveraging aerospace heritage into semiconductor metrology applications. KEYENCE Corporation represents the Japanese direct-sales model, bypassing distributor networks to capture margin pools in factory-floor relationships. Basler AG and Allied Vision Technologies GmbH illustrate the German Mittelstand precision optics tradition, with AG and GmbH structures signaling family-influenced governance and regional banking relationships.
| Leading Market Players |
|---|
| Cognex Corporation |
| KEYENCE Corporation |
| Basler AG |
| Teledyne Technologies Inc. |
| OMRON Corporation |
| Allied Vision Technologies GmbH |
| Adimec Advanced Image Systems |
| SICK AG |
| National Instruments Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act firmware traceability mandates gate qualified supply and premium-tier pricing access, forcing suppliers to absorb compliance documentation costs or forfeit certification-dependent contracts in Germany's automotive corridor. Buyers purchasing for FDA-regulated medical device workflows face elongated validation timelines that compress negotiation leverage, while smart camera adopters in logistics hubs accept hardware-plus-software bundles that obscure unit economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, separating radiation-hardened semiconductor inspection units from PC-tethered legacy architectures and bare-bones CCTV modules for process documentation. Price differentiation hinges on EU AI Act conformity grade and embedded processing capability, with certified smart cameras commanding substantial premiums over uncertified equivalents. Cost compression in standard-tier line scan cameras intensifies because foundry allocation bottlenecks for high-resolution CMOS sensors above 25 megapixels constrain supply elasticity. Electronics contract manufacturers in China's Yangtze River Delta exhibit acute price sensitivity, while German automotive OEMs prioritize guaranteed defect detection rates over per-unit procurement savings.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns for electronics manufacturing quality control equipment, pressuring multinational suppliers to establish local assembly or forfeit smartphone sector contracts. Sensor fabrication concentrates in Taiwan, South Korea, and Japan, with East Asian foundry capacity constraints stretching lead times for high-speed imagers. Raw material dependencies span silicon wafers, rare-earth optical coatings, and precision glass substrates. Single-source vulnerability in advanced CMOS sensor supply creates allocation risk during demand surges. Distribution runs through authorized system integrators and direct factory-floor relationships, with Japanese suppliers bypassing distributor networks to capture margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The machine vision camera market compounds steadily as industrial automation mandates propagate across automotive and electronics manufacturing corridors worldwide. Regulatory compliance investments create durable competitive moats for certified suppliers.
For Market Incumbents: Cement firmware traceability advantages by embedding EU AI Act risk-classification protocols directly into sensor production pipelines, absorbing compliance costs that would disqualify smaller competitors. Expand captive sensor partnerships with East Asian foundries to secure allocation priority during CMOS imager shortages, defending margin position against smart camera entrants attacking PC-tethered legacy architectures. For New Entrants and Emerging Players: The gap between premium radiation-hardened semiconductor inspection units and economy-tier CCTV modules creates white-space opportunity for mid-range 3D depth-sensing cameras with sub-millimeter accuracy. Target India's PLI-supported electronics manufacturing corridor for smartphone assembly quality control, where outcome-guaranteed performance contracts transfer operational risk and accelerate vendor stickiness post-installation. For Investors and Strategic Acquirers: Roll-up economics work for algorithm-integrated specialists with in-house ISP pipeline design because EU MDR and FDA validation documentation creates high switching costs and recurring revenue attachment. Target firms controlling embedded processing capabilities and notified body relationships for Class IIa and above medical device cameras. Watch for EU AI Act enforcement intensity as the inflection signal determining certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Traceability Investment | EU AI Act compliance documentation creates defensible margin pools in safety-critical automotive inspection. |
| Captive Sensor Partnership Expansion | East Asian foundry allocation agreements secure supply priority during high-resolution CMOS shortages. |
| Smart Camera Platform Integration | Embedded processing eliminates PC dependencies in harsh factory environments across Germany's Stuttgart-Munich corridor. |
| Medical Device Certification Pathway | FDA 21 CFR Part 820 and EU MDR validation extends sales cycles but locks in pharmaceutical packaging contracts. |
| India Manufacturing Footprint Establishment | PLI scheme incentives attract local assembly for smartphone quality control in Yangtze River Delta-competing zones. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automation engineering directors, vision system integrators, semiconductor fab equipment procurement managers, and regulatory affairs leads at notified bodies with secondary validation. Sources included SEC 10-K filings from listed automation suppliers, EU MDR technical documentation databases, FDA 510(k) clearance records, and foundry capacity utilization reports from East Asian semiconductor manufacturers. Bottom-up sensor shipment data and top-down industrial automation capex forecasts were triangulated against end-user procurement patterns.
Segment-weighting approaches modeled demand across product architecture, sensor technology, application workflow, and end-use regulatory exposure. CAGRs were derived from install-base penetration curves and replacement cycle analysis across the projection horizon. Forecast inputs incorporated EU AI Act implementation timelines, FDA validation backlog estimates, and NMPA electromagnetic compatibility harmonization progress.
Caveats apply where foundry allocation disruptions, regulatory enforcement delays, or embedded vision engineering talent scarcity could materially shift the outlook. Forecasts reflect assumptions about certification pathway efficiency and sensor supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Image Signal Processor Market
Imaging
X Ray Tubes Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Global Digital Binoculars Market
Imaging
Gige Camera Market
Imaging
North America IP Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
Webcam Market
Imaging
Industrial Camera Market
Imaging
Chemical Imaging Systems Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Global Cell Imagers Market
Imaging
X-Ray Microscopes Market
Imaging
Global Computed Radiography Market
Imaging
Photoacoustic Imaging Market