
 High-Power Microwave Source Market | 2026-2036
High-Power Microwave Source Market Size, Share, and Industry Trends Forecast 2026-2036
High-Power Microwave Source Market Insights
Software-defined waveform customization is broadening what defense and research buyers procure alongside hardware cores. CPI International leverages captive vacuum electronic manufacturing to sustain long-term service contracts with US national laboratories. L3Harris Technologies anchors its position through integrated radar system offerings that bundle traveling wave tube sources with proprietary control interfaces. Qorvo competes aggressively in gallium nitride solid-state segments where thermal management and frequency agility differentiate performance tiers.
High-power microwave sources generate electromagnetic energy at kilowatt to megawatt levels across centimeter and millimeter wavelengths, typically employing vacuum electronic devices or compound semiconductor amplifiers to drive radar transmitters, particle accelerator RF cavities, and industrial plasma heating systems. Magnetron and klystron categories retain dominant installed bases in legacy defense radar and industrial heating applications where replacement cycles extend across decades. Solid-state amplifier segments attract fastest-growing demand from satellite communication and active electronically scanned array radar programs where reliability and rapid beam steering outweigh peak power density.
US ITAR export controls, EU dual-use regulation frameworks, and Japan's METI foreign trade licensing requirements collectively shape which suppliers access defense and space-qualified procurement channels across major demand centers. FCC spectrum allocation proceedings in the United States and ETSI harmonized standards in Europe further constrain permissible operating bands for commercial and scientific microwave source deployments. Stakeholders must monitor how national security classification protocols and emerging frequency spectrum reallocation decisions reshape addressable market boundaries for both vacuum electronic and solid-state product lines.
Market Dynamics
The vacuum-to-solid-state technology transition is compressing procurement cycles and rewiring supplier relationships across defense and commercial segments. Gallium nitride amplifiers are displacing legacy traveling wave tubes in active electronically scanned array radar programs, forcing incumbent vacuum electronic manufacturers to defend installed bases through long-term service contracting.
Growth Catalysts
- Directed Energy Roadmap:The US Department of Defense's multi-phase technology maturation program is accelerating solid-state amplifier qualification for next-generation counter-UAS and shipboard defense platforms.
- EU Defense Modernization:NATO member states are consolidating procurement frameworks for radar modernization, creating pooled demand for high-reliability microwave sources across Germany, France, and Poland.
- Gallium Nitride Thermal Performance:Advances in wide-bandgap semiconductor thermal management are extending solid-state amplifier duty cycles into previously vacuum-dominated megawatt-class applications.
Market Restraints
- ITAR Export Controls:US International Traffic in Arms Regulations restrict vacuum electronic and solid-state amplifier transfers to non-allied nations, fragmenting addressable demand pools.
- Tungsten and Rare Earth Supply Concentration:Cathode manufacturing depends on Chinese-processed rare earth elements and tungsten supplies, exposing vacuum electronic producers to input volatility.
- Peak Power Density Limitations:Solid-state amplifiers face fundamental thermal dissipation constraints at frequencies above Ka-band, preserving vacuum electronic dominance in millimeter-wave radar.
Strategic Opportunities
- Japan Space Qualification:METI-funded national laboratory programs are creating domestic demand for radiation-hardened solid-state amplifiers in satellite communication payloads.
- Industrial Plasma Heating:Semiconductor fabrication equipment manufacturers are adopting high-power microwave sources for atomic layer deposition processes, opening non-defense revenue streams.
- Software-Defined Waveform Integration:Defense integrators are unbundling hardware procurement from firmware customization, creating service revenue for waveform engineering specialists.
Industry Challenges
- Vacuum Electronic Engineering Talent Pipeline:University programs have reduced microwave tube physics curricula, constraining replacement hiring for retiring specialist workforces at national laboratories.
- Dual-Use Classification Complexity:EU Regulation 2021/821 implementation varies across member state export licensing authorities, creating compliance timeline uncertainty for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Power Microwave Source Market |
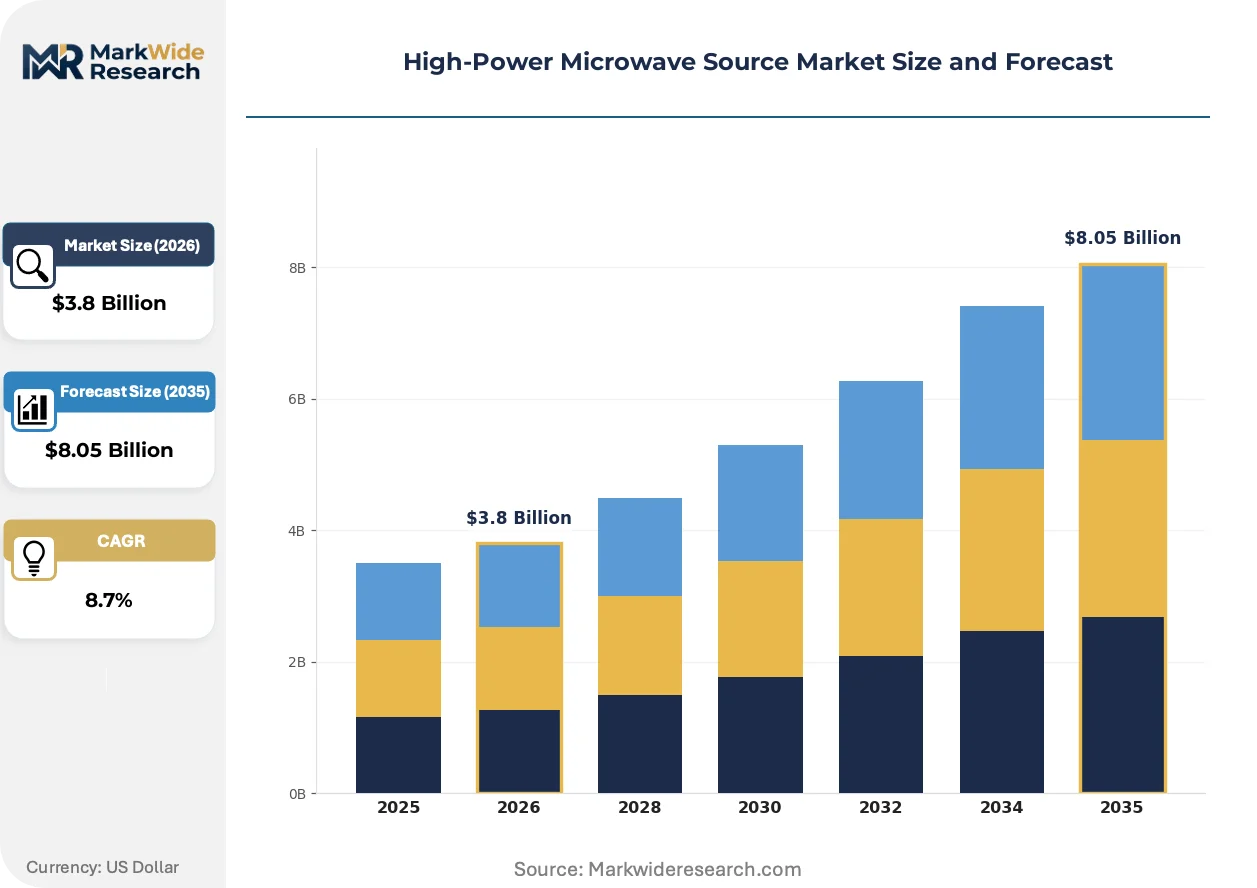
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Klystron, Magnetron, Traveling Wave Tube, Solid State Amplifier, Gyrotron Technology: Vacuum Electronic, Solid State, Vacuum Tube, Semiconductor, Traveling Wave Application: Radar Systems, Particle Accelerators, Industrial Heating, Satellite Communication, Scientific Research End User: Defense Contractors, Research Laboratories, Telecommunications Providers, Industrial Manufacturers, Space Agencies |
| Companies Covered | CPI International, Qorvo, Teledyne Technologies, L3Harris Technologies, Northrop Grumman, Thales Group, RTX Corporation, Lockheed Martin, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Power Microwave Source Market Trends and Innovations
Active electronically scanned array architectures are redistributing power generation from centralized transmitters to distributed aperture elements. This structural shift is collapsing traditional distinctions between source and antenna subsystems.
GaN-on-SiC transistor technology is decentralizing radar transmitter architectures by enabling solid-state transmit/receive modules with sufficient output power for fighter aircraft and naval surveillance applications. Prime defense contractors in the United States and Japan are qualifying these modules for full-rate production. The technology is compressing supplier tiers by allowing system integrators to source directly from compound semiconductor foundries rather than through vacuum electronic specialists.
EU F-Gas Regulation phase-down schedules are restricting sulfur hexafluoride use in high-voltage vacuum electronic power supplies, forcing manufacturers to redesign modulator topologies. Industrial heating equipment suppliers face accelerated compliance timelines compared to defense contractors with exemption pathways. German and French vacuum electronic producers are investing in solid-state modulator alternatives to maintain CE marking eligibility.
Defense procurement offices are unbundling hardware acquisition from sustainment services, creating separate contracting vehicles for source replacement and depot-level maintenance. This pattern is most visible in US Navy radar modernization programs, where traveling wave tube lifetime buy contracts now run independent of system integration awards. Service revenue is concentrating with captive maintenance facilities and original equipment manufacturer technical field teams.
High-Power Microwave Source Market Segmentation
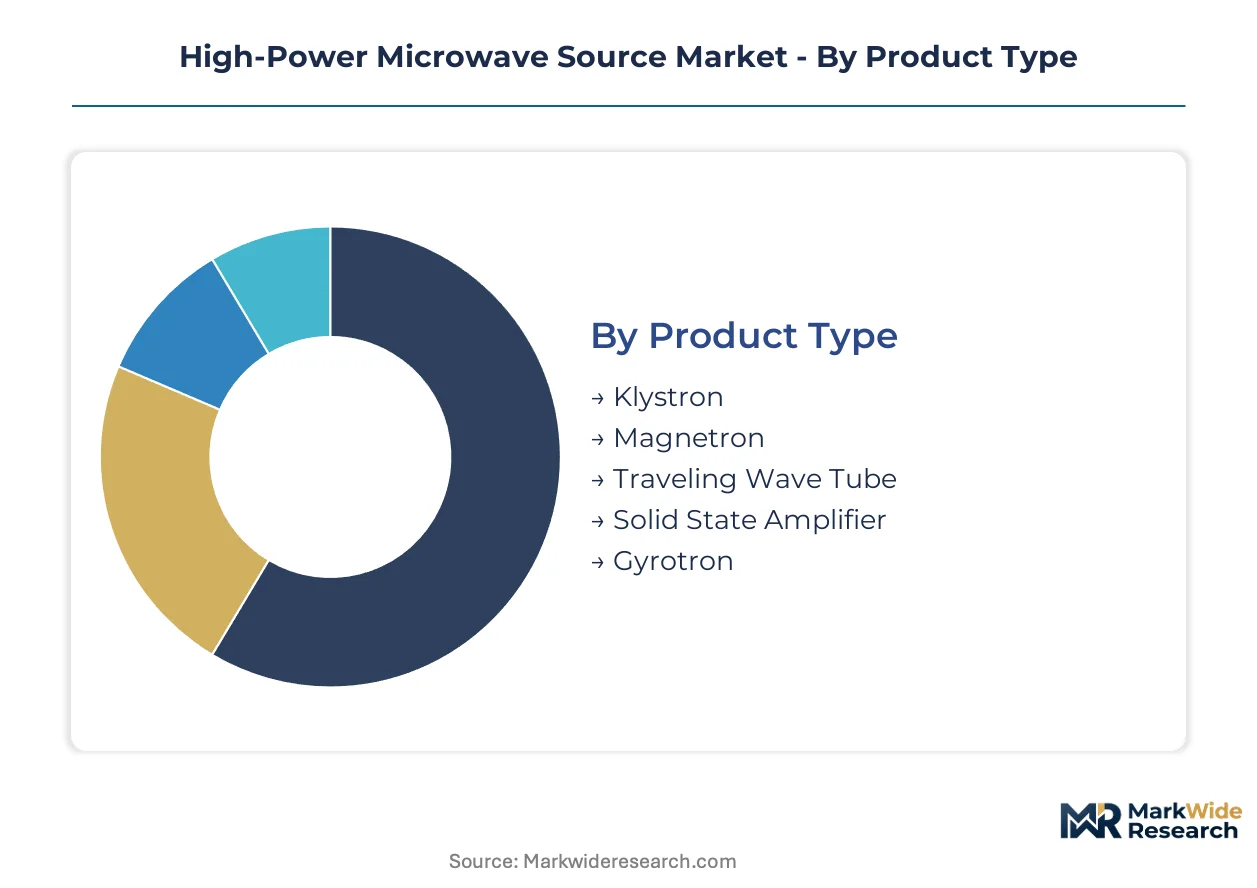
Segmentation in high-power microwave sources reveals how procurement authority, qualification pathways, and technology maturity split demand across incompatible supply chains. Defense contractors navigate ITAR-restricted vacuum electronic channels while commercial satellite operators source from open-market semiconductor foundries.
Product Type:
Klystron and magnetron segments require ITAR registration or EU dual-use export licenses for cross-border transfers, while solid-state amplifier procurement faces lighter documentation burdens under EAR99 classifications for commercial variants.
- Klystron:Velocity-modulated vacuum tubes generate coherent, high-gain output at megawatt peak power levels for particle accelerator RF cavities and long-range radar transmitters. US national laboratories at SLAC and Fermilab sustain demand through multi-decade replacement cycles for linear accelerator infrastructure.
- Solid State Amplifier:Gallium nitride transistor arrays deliver phased-array beam agility without mechanical steering, displacing legacy tubes in active electronically scanned array radar. Japanese defense integrators and US Navy surface ship programs are qualifying these modules for full-rate production, prioritizing mean-time-between-failures over peak power density.
- Magnetron:Crossed-field oscillators dominate industrial heating equipment with lower unit costs and simpler magnet power supplies.
- Traveling Wave Tube:Helix or coupled-cavity slow-wave structures amplify across octave bandwidths for electronic warfare jamming pods.
- Gyrotron:Cyclotron resonance maser action generates hundred-kilowatt continuous wave output at submillimeter wavelengths for fusion plasma heating.
Magnetron sits at the top of the volume ranking, with solid state amplifier climbing the fastest.
Technology:
Cost tiers separate vacuum electronic architectures requiring precision machining and high-voltage modulators from semiconductor-based alternatives leveraging compound semiconductor foundry economies.
- Vacuum Electronic:Thermionic emission devices demand specialized cathode manufacturing with tungsten-rhenium alloys and rare earth oxide coatings. German and French producers maintain captive cathode production lines to shield against Chinese-processed tungsten supply volatility.
- Solid State:Gallium nitride-on-silicon carbide transistors enable distributed transmitter architectures with graceful degradation and rapid beam steering. Thermal management constraints limit these devices to sub-megawatt average power, preserving vacuum electronic dominance in millimeter-wave applications.
- Vacuum Tube:Encompasses magnetron, klystron, and traveling wave tube categories with shared reliance on high-voltage power supplies and magnetic focusing.
- Semiconductor:Silicon LDMOS and gallium nitride HEMT technologies compete for S-band and L-band radar applications below 6 GHz.
- Traveling Wave:Slow-wave interaction structures enable broadband amplification across multi-octave instantaneous bandwidths.
Vacuum electronic commands the highest average selling prices, while solid state technology is expanding most quickly through defense radar modernization programs.
Application:
Customer type determines whether procurement flows through classified defense channels with multi-year qualification cycles or commercial supply chains with faster vendor switching.
- Radar Systems:Active electronically scanned array architectures redistribute power generation across thousands of transmit-receive modules, collapsing traditional distinctions between source and antenna subsystems. US Air Force and Japanese ASDF fighter programs are driving gallium nitride module qualification timelines.
- Satellite Communication:Solid-state power amplifiers in Ku-band and Ka-band support high-throughput satellite payloads with decade-long operational lifetimes. Radiation-hardened variants require METI-funded Japanese qualification protocols or NASA GSFC standards for geostationary deployments.
- Particle Accelerators:Klystron and gyrotron sources feed RF cavities for electron and proton acceleration at CERN, DESY, and US DOE facilities.
- Industrial Heating:Magnetron sources at 915 MHz and 2.45 GHz drive plasma processing and materials drying applications.
- Scientific Research:Fusion energy programs require megawatt-class gyrotrons for electron cyclotron resonance heating.
Radar systems holds the largest installed base, with satellite communication gaining share fastest through constellation deployment schedules.
End User:
Volume concentration varies sharply across end users, with defense contractors consolidating procurement through prime integrators while research laboratories fragment demand across specialized specifications.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and Raytheon bundle microwave sources into integrated radar and electronic warfare systems. These primes increasingly source solid-state transmit-receive modules directly from compound semiconductor foundries, bypassing traditional vacuum electronic specialists.
- Research Laboratories:CERN, DESY, SLAC, and Japan's QST operate custom-designed klystron and gyrotron fleets with dedicated maintenance facilities. Academic microwave tube physics programs have contracted, constraining replacement hiring for specialist technician workforces.
- Telecommunications Providers:Satellite operators procure solid-state amplifiers through commercial channels with standard reliability screening.
- Industrial Manufacturers:Semiconductor fabrication equipment makers adopt microwave plasma sources for atomic layer deposition.
- Space Agencies:NASA, ESA, and JAXA impose radiation-hardening and vibration qualification requirements distinct from commercial satellite specifications.
Defense contractors dominate procurement value, with space agencies showing the steepest expansion trajectory through lunar and deep-space communication relay programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan sustain parallel but distinct procurement ecosystems for high-power microwave sources, with German firms specializing in vacuum electronic cathode production and Japanese integrators prioritizing GaN-on-SiC qualification for defense radar programs.
United States
The US Department of Defense's directed energy roadmap channels procurement through national laboratory networks at SLAC and Fermilab. FCC spectrum allocation proceedings constrain commercial operating bands while ITAR export controls fragment addressable demand pools. Defense primes in California and Massachusetts co-locate with vacuum electronic specialists to sustain long-term service contracting.
Germany
EU F-Gas Regulation phase-down schedules force redesign of high-voltage vacuum electronic power supplies ahead of accelerated compliance timelines. DESY operates custom-designed klystron fleets with dedicated maintenance facilities in Hamburg. Bavarian and French vacuum electronic producers invest in solid-state modulator alternatives to maintain CE marking eligibility.
Japan
METI-funded national laboratory programs create domestic demand for radiation-hardened solid-state amplifiers in satellite communication payloads. Japan's foreign trade licensing requirements shape defense and space-qualified procurement channels. Kansai and Tokyo-based defense integrators qualify GaN transmit-receive modules for fighter aircraft programs.
United Kingdom
BAE Systems anchors procurement through integrated radar system offerings that bundle traveling wave tube sources with proprietary control interfaces. UK defense modernization aligns with NATO pooled demand frameworks. Southwest England clusters host electronic warfare specialists serving jamming pod applications.
South Korea
The Seoul Capital Area concentrates compound semiconductor foundry capacity feeding distributed transmitter architectures for active electronically scanned array radar. National security classification protocols restrict technology transfer pathways. Daegu-Gyeongbuk regions develop thermal management solutions for wide-bandgap semiconductor deployments.
High-Power Microwave Source Market Competitive Landscape
Top-tier vendors anchor integrated system offerings, while component specialists defend positions through captive manufacturing and long-term service contracts. The market structure splits between vacuum electronic incumbents with decades-long installed bases and compound semiconductor challengers displacing legacy tubes in phased-array applications. Three archetypes dominate: national laboratory service contractors, defense prime integrators with bundled offerings, and GaN foundry direct suppliers. Competitive moves concentrate on technology licensing for thermal management and strategic partnerships for waveform engineering capabilities.
Within the vacuum electronic tier, CPI International represents the national laboratory service contractor archetype through captive manufacturing relationships. L3Harris Technologies and Qorvo exemplify divergent positioning strategies—one anchoring integrated radar systems, the other competing in gallium nitride segments where frequency agility differentiates performance tiers. These three entities collectively illustrate how procurement unbundling is redistributing value between hardware cores and firmware customization services.
| Leading Market Players |
|---|
| CPI International |
| Qorvo |
| Teledyne Technologies |
| L3Harris Technologies |
| Northrop Grumman |
| Thales Group |
| RTX Corporation |
| Lockheed Martin |
| BAE Systems |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride-on-silicon carbide foundry expansions in South Korea and Japan are simultaneously compressing unit economics for solid-state amplifiers and redrawing supplier tier relationships. This technology migration is collapsing traditional cost premiums between vacuum electronic and semiconductor architectures while concentrating procurement leverage with compound semiconductor foundries.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for GaN transmit-receive modules as foundries achieve wafer-scale economies. Three-tier pricing structure across ITAR-restricted defense-grade, space-qualified radiation-hardened, and commercial EAR99 tiers reflects certification burden differentials. Cost compression in commercial satellite amplifier segments is intensifying because Japanese and South Korean foundries are qualifying automotive-grade GaN processes for RF applications. Defense contractors show lowest price sensitivity due to multi-year qualification lock-in, while industrial heating equipment manufacturers face acute margin pressure from magnetron commoditization.
Supply Chain Analysis
Direct-to-prime-defensive-integrator channels handle classified procurement for active electronically scanned array radar programs, while open-market distribution serves commercial satellite operators. Manufacturing concentrates in the United States for ITAR-restricted vacuum electronics, Japan for radiation-hardened solid-state amplifiers, and South Korea for commercial GaN foundry output. Tungsten-rhenium cathode alloys and Chinese-processed rare earth oxide coatings constitute critical input dependencies. Single-source vulnerability in tungsten supply exposes German and French vacuum electronic producers to price volatility. Distribution runs through captive maintenance facilities for national laboratory service contracts and compound semiconductor foundry direct relationships for defense prime integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in high-power microwave sources rests on GaN thermal management advances enabling premium-tier displacement of legacy traveling wave tubes. Solid-state amplifier qualification timelines for defense radar programs are compressing cost structures while preserving pricing power in radiation-hardened satellite segments.
For Market Incumbents: Cement captive cathode production capabilities to insulate against Chinese tungsten supply volatility. Secure long-term service contracting vehicles with US national laboratories and European accelerator facilities to defend installed base revenue against GaN displacement. Lockheed Martin and Northrop Grumman direct sourcing from compound semiconductor foundries threatens traditional vacuum electronic supplier tiers. For New Entrants and Emerging Players: Direct-to-defense-prime digital sales channels bypass established vacuum electronic distribution hierarchies for commercial GaN module procurement. Target industrial plasma heating equipment manufacturers adopting microwave sources for semiconductor fabrication atomic layer deposition processes. Qualify under EAR99 classifications to access commercial satellite constellation demand without ITAR registration burdens. For Investors and Strategic Acquirers: Roll-up economics work for waveform engineering specialists because defense procurement unbundling is separating hardware acquisition from firmware customization services. Five-to-ten-year viability hinges on compound semiconductor foundry capacity expansion sustaining cost-down trajectories. Watch GaN-on-diamond thermal interface qualification timelines as the inflection signal for megawatt-class solid-state amplifier viability.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Capacity Expansion | South Korean and Japanese foundry investments compress unit costs for defense radar transmit-receive modules. |
| Captive Cathode Manufacturing Integration | German and French vacuum electronic producers shield margin structures from Chinese tungsten supply volatility. |
| Software-Defined Waveform Service Unbundling | US Navy radar modernization programs separate source replacement contracts from system integration awards. |
| Radiation-Hardened Amplifier Qualification | METI-funded Japanese protocols create premium-tier pricing power for geostationary satellite payload suppliers. |
| EU F-Gas Regulation Compliance Redesign | Solid-state modulator investments preserve CE marking eligibility for industrial heating equipment manufacturers. |
Research Methodology
Bottom-up defense procurement modeling reconciled against top-down compound semiconductor foundry output tracking forms the analytical core. Primary interviews with radar system procurement officers at prime defense integrators, GaN foundry engineering directors, national laboratory maintenance facility managers, and satellite payload qualification specialists combined with secondary validation from FCC spectrum allocation proceedings, ETSI harmonized standards documentation, US Department of Defense budget justification materials, and METI foreign trade licensing records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of vacuum electronic replacement cycles and solid-state amplifier qualification timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, technology maturity tier, application mission profile, and end-user procurement authority cluster. CAGRs derived from fitted growth curves adjusted for regulatory approval pathway duration and defense modernization program pacing. GaN thermal performance roadmaps and EU F-Gas Regulation compliance timelines constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for vacuum electronic lifetime extension through advanced cathode coatings would alter the outlook. Forecasts reflect base-case assumptions regarding ITAR export control continuity and tungsten supply concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
China Small Signal Transistor Market
RF Components
Flat Panel Antenna Market
RF Components
Global RF Transceiver Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
LTCC Power Dividers Market
RF Components
RF Mixers Market
RF Components
Radio Frequency Front End Module Market
RF Components
US RFID Tags Market
RF Components
Analog Phase Shifter Market
RF Components
RF Spectrum Analyzer Market
RF Components
Europe Small Signal Transistor Market
RF Components
Tunable Capacitors Market
RF Components
Global RF Power Semiconductor Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Radio Frequency Duplexer Market
RF Components
RF Switches Market