
 Widefield Imaging Systems Market | 2026-2036
Widefield Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Widefield Imaging Systems Market Outlook
A shortage of trained retinal imaging specialists is reorganizing how healthcare providers deploy widefield systems across diagnostic networks. Carl Zeiss Meditec AG leverages its century-old optics heritage to dominate premium instrument segments in European university hospitals. Optos anchors the North American installed base through proprietary ultra-widefield scanning laser technology. Forus Health Pvt Ltd competes in emerging markets with portable, cost-engineered platforms designed for rural screening programs.
Widefield imaging systems capture high-resolution images across extended retinal fields, typically spanning 100 to 200 degrees in a single exposure using scanning laser ophthalmoscopy or confocal optical designs. These instruments serve primarily for peripheral retinal disease detection, diabetic retinopathy screening, and intraoperative surgical guidance where standard fundus cameras leave blind zones. Camera systems command the largest revenue share due to recurring replacement cycles and tethered software licensing models. Fluorescence imaging represents the fastest-expanding technology segment as angiographic protocols migrate from standard-field to widefield acquisition for vascular pathology assessment. Healthcare providers absorb the majority of end-user demand, though research institutions are building dedicated widefield cores for longitudinal ophthalmology studies.
FDA 510(k) pathways and the EU MDR framework impose distinct clinical validation requirements on widefield device manufacturers seeking dual-market access. ISO 13485 quality management standards and IEC 60601-1 electrical safety benchmarks further constrain design choices for fluorescence-enabled systems. Stakeholders must monitor how computational imaging algorithms shift regulatory scrutiny from hardware optics to software-as-medical-device classifications.
Market Dynamics
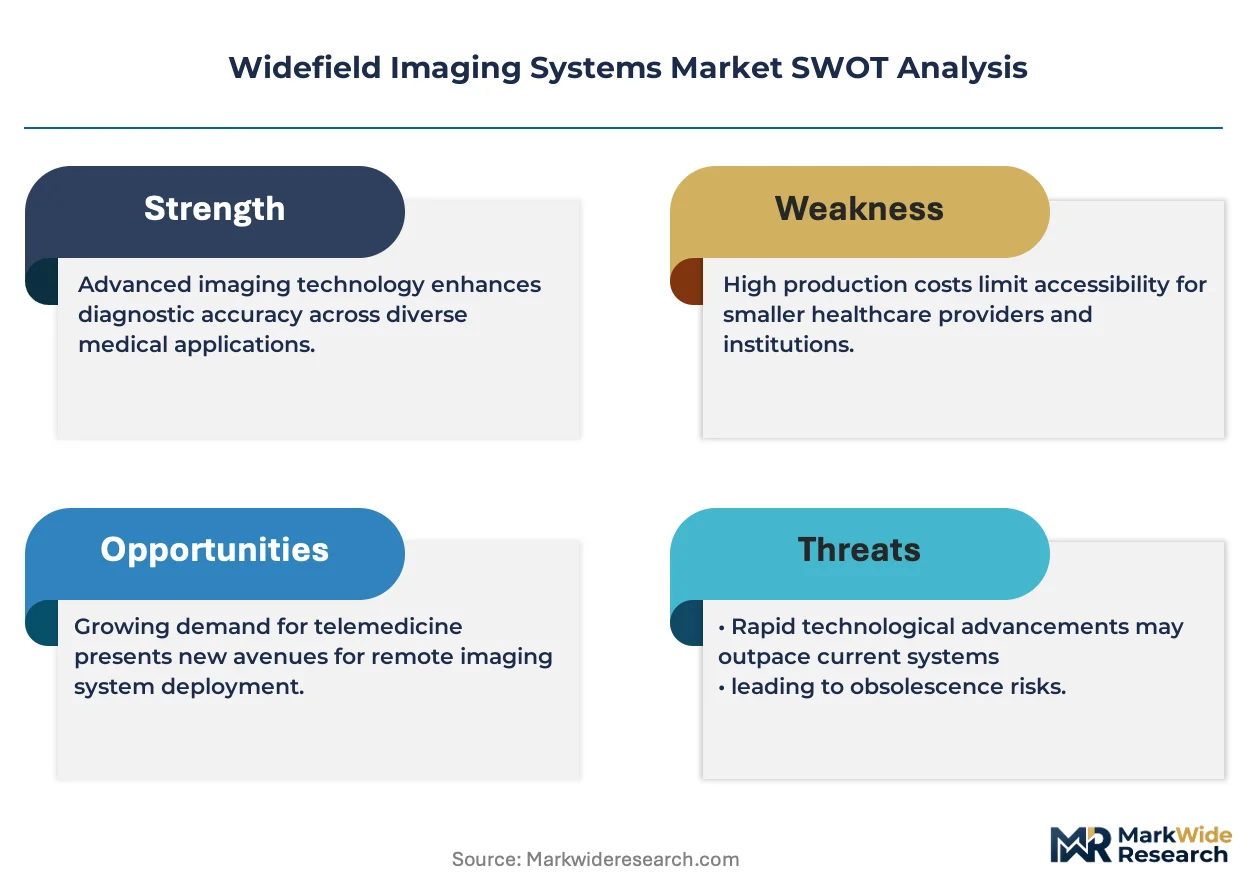
The EU Medical Device Regulation is forcing widefield imaging manufacturers to rebuild clinical validation dossiers, compressing product launch timelines while ophthalmology clinics demand faster diagnostic throughput. This regulatory pressure intersects with AI-assisted diagnostic modules that require separate software-as-medical-device clearances, creating dual-track compliance burdens for fluorescence-enabled systems.
Growth Catalysts
- Diabetic retinopathy screening mandates:National diabetes management programs in Germany and the United Kingdom are embedding widefield imaging into standard-of-care protocols, expanding installed base requirements for hospital networks.
- EU MDR framework alignment:Streamlined conformity assessment routes for Class IIa diagnostic devices are reducing registration friction for manufacturers with established ISO 13485 quality systems.
- Confocal optical design advances:Enhanced signal-to-noise ratios in scanning laser ophthalmoscopy are extending single-capture fields beyond 150 degrees, eliminating stitching artifacts in peripheral pathology detection.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component foundries control critical lens grinding capabilities, exposing manufacturers to extended lead times for aspheric objective assemblies.
- FDA 510(k) predicate device limitations:Narrow equivalence pathways for AI-augmented widefield systems are forcing novel device classifications that extend review cycles by 12-18 months.
- Fluorophore cost volatility:Indocyanine green and sodium fluorescein dye prices fluctuate with pharmaceutical raw material markets, compressing margin on angiography service lines.
Strategic Opportunities
- Rural screening program expansion:Portable widefield platforms with tablet-based image review are penetrating India's tier-2 and tier-3 cities where specialist density remains critically low.
- Intraoperative surgical guidance integration:Hybrid widefield systems combining preoperative mapping with real-time heads-up display are displacing microscope-integrated fundus viewing in vitreoretinal suites.
- CE marking mutual recognition:Switzerland and Australia's alignment with EU MDR technical documentation standards is opening parallel market access without redundant clinical trials.
Industry Challenges
- Computational imaging talent scarcity:Machine learning engineers with ophthalmic image annotation expertise command premium compensation, constraining algorithm development timelines for mid-tier manufacturers.
- Legacy PACS integration complexity:Hospital information systems built on DICOM 3.0 variants require custom middleware development for widefield image storage and retrieval workflows.
- IEC 60601-1 third edition compliance:Updated electrical safety and electromagnetic compatibility testing protocols are extending certification timelines for fluorescence excitation subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Widefield Imaging Systems Market |
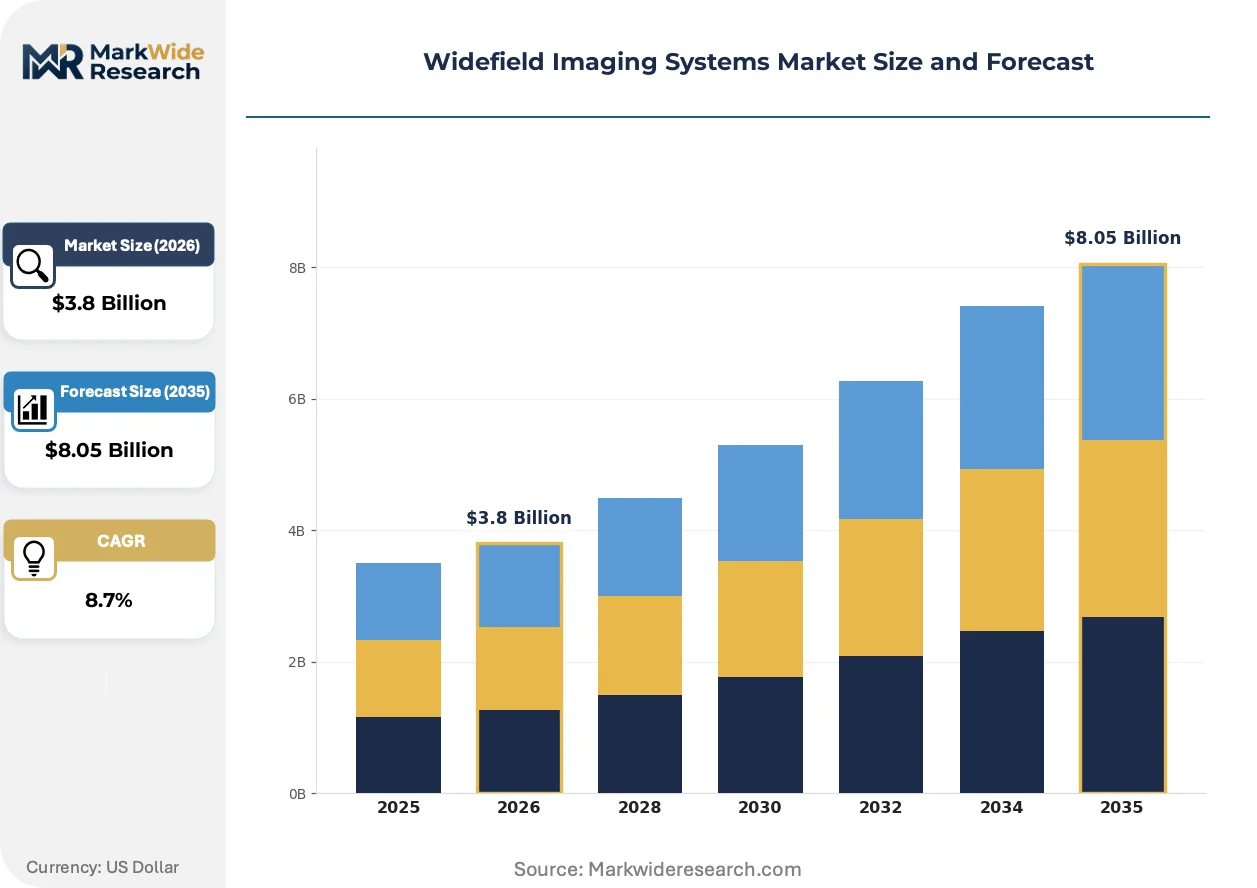
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Imaging Software, Data Acquisition Systems, Accessories Application: Research, Clinical Diagnostics, Industrial Inspection, Environmental Monitoring End User: Healthcare Providers, Research Institutions, Manufacturing Companies, Government Agencies Technology: Optical Imaging, Fluorescence Imaging, Video Imaging, Computational Imaging |
| Companies Covered | Heidelberg Engineering GmbH, Optos, Visunex Medical Systems, Clarity Medical, Carl Zeiss Meditec AG, Centervue SpA, ZEISS Group, Forus Health Pvt Ltd, epipole limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Widefield Imaging Systems Market Strategic Shifts
Computational imaging algorithms are decomposing traditional hardware-centric value chains in widefield ophthalmology, shifting competitive advantage from optical engineering to software training data quality and regulatory clearance velocity for diagnostic outputs.
Adaptive optics technology is decomposing the resolution limitations of conventional widefield systems by correcting wavefront aberrations in real-time. University hospital research cores in Germany and Japan are deploying these platforms for photoreceptor-level imaging. The structural consequence is decomposing the boundary between clinical diagnostic devices and preclinical research instruments, forcing manufacturers to maintain dual product architectures.
The EU AI Act's risk classification framework is reclassifying diagnostic algorithms that provide treatment recommendations as high-risk AI systems. Widefield imaging vendors must now implement post-market monitoring systems and algorithmic change control protocols. Fluorescence angiography modules with automated leakage quantification face the steepest compliance burden, with notified bodies in Germany and the Netherlands developing specialized audit capacities.
Hospital procurement departments are consolidating widefield imaging contracts under enterprise ophthalmology platform agreements. Standalone device vendors face displacement by integrated suite providers offering multi-modality installations with unified service contracts. This concentration is most visible in France and the United Kingdom, where hospital network mergers have reduced the number of independent purchasing committees by over one-third since 2020.
Widefield Imaging Systems Market Segmentation
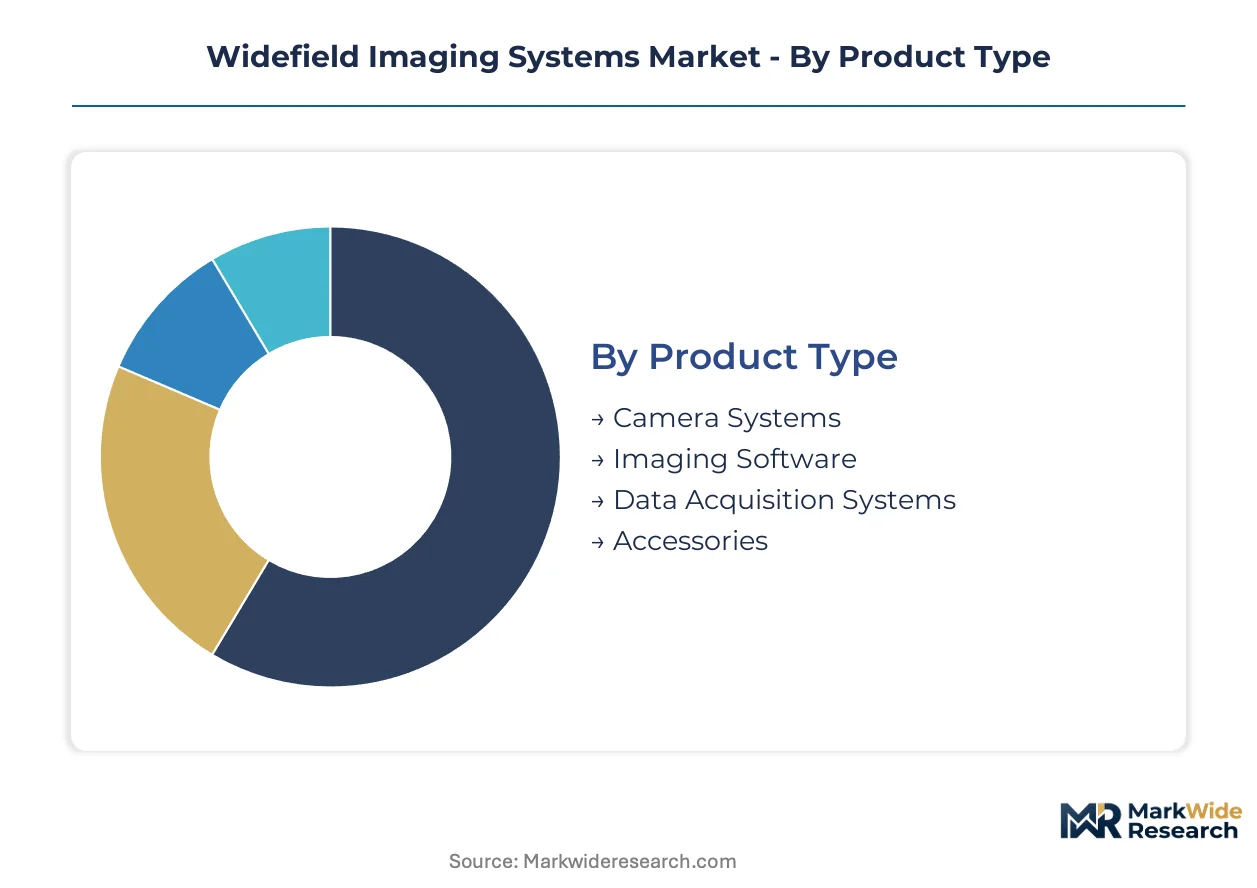
Widefield imaging systems serve divergent performance requirements across ophthalmology clinics, research cores, and industrial quality control labs. Product architecture, software capabilities, and optical specifications vary sharply by intended use case and regulatory pathway.
Product Type:
German and Japanese manufacturers dominate export markets for precision optical assemblies, while software modules increasingly originate from development centers in India and Israel.
- Camera Systems:Scanning laser ophthalmoscopy and confocal optical designs capture 100-200 degree retinal fields in single exposures. Hospital networks in Germany and the United Kingdom absorb the majority of installed base expansion as diabetic retinopathy screening mandates tighten.
- Imaging Software:AI-assisted diagnostic modules with automated pathology detection require separate software-as-medical-device clearances under FDA and EU MDR frameworks. Computational imaging algorithms are shifting competitive advantage from hardware optics to training data quality and regulatory velocity.
- Data Acquisition Systems:Real-time image stitching and wavefront correction engines for adaptive optics platforms.
- Accessories:Specialized lens assemblies, calibration phantoms, and fluorophore injection systems for angiography protocols.
Camera Systems holds the largest share; momentum sits with Imaging Software.
Application:
Cost structures stratify sharply between reimbursed clinical procedures and grant-funded research deployments.
- Clinical Diagnostics:Peripheral retinal disease detection and diabetic retinopathy screening drive recurring utilization in ophthalmology clinics. EU hospital procurement consolidation under enterprise platform agreements is displacing standalone device vendors in France and the United Kingdom.
- Research:University hospital cores in Germany and Japan deploy adaptive optics platforms for photoreceptor-level imaging studies. Funding cycles and publication priorities determine replacement timelines rather than clinical reimbursement codes.
- Industrial Inspection:Semiconductor wafer and display panel quality control applications.
- Environmental Monitoring:Remote sensing and ecological survey deployments.
Clinical Diagnostics commands the revenue base; Research shows the steepest expansion trajectory for specialized instrumentation.
End User:
Volume concentration differs between high-throughput screening networks and low-frequency specialized research installations.
- Healthcare Providers:Hospital networks and ophthalmology clinics absorb the majority of device shipments. Tier-2 and tier-3 cities in India are penetrating with portable platforms where specialist density remains critically low.
- Research Institutions:Dedicated widefield cores for longitudinal ophthalmology studies require multi-modality installations with unified service contracts.
- Manufacturing Companies:Quality control departments in precision optics and electronics fabrication.
- Government Agencies:Public health screening programs and regulatory reference laboratories.
Healthcare Providers represent the installed base anchor; Research Institutions are gaining share fastest for adaptive optics adoption.
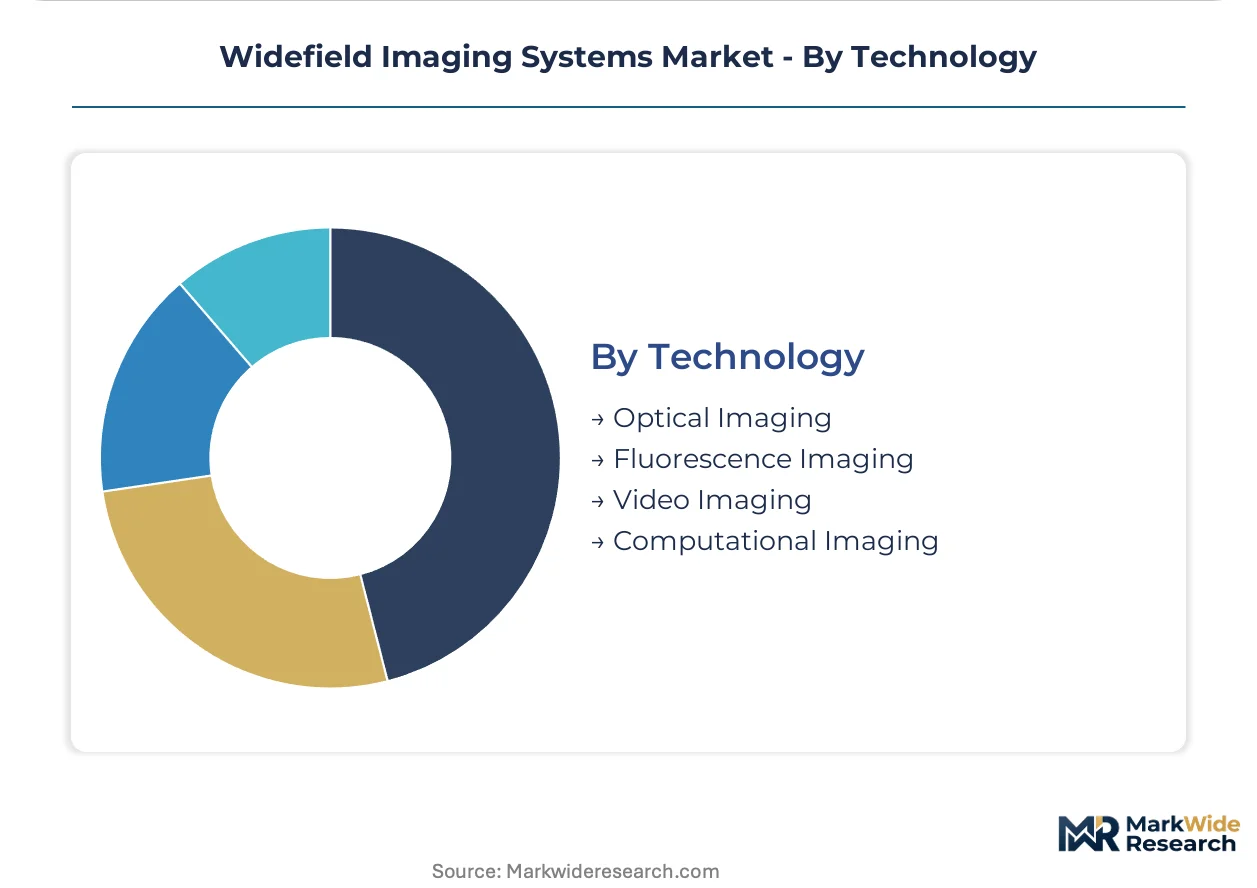
Technology:
Margin profiles separate mature optical designs from emerging computational and fluorescence modalities with complex regulatory dossiers.
- Optical Imaging:Established scanning laser and confocal architectures with proven clinical validation dossiers. German precision optics clusters anchor manufacturing for premium instrument segments.
- Fluorescence Imaging:Angiographic protocols migrating from standard-field to widefield acquisition for vascular pathology assessment. Indocyanine green and sodium fluorescein dye cost volatility compresses service line margins.
- Video Imaging:Real-time intraoperative surgical guidance with heads-up display integration.
- Computational Imaging:Machine learning engineers with ophthalmic image annotation expertise command premium compensation, constraining algorithm development timelines.
Optical Imaging retains the volume lead; Fluorescence Imaging is climbing the fastest as angiography protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography for widefield imaging system commercialization, while EU MDR technical documentation requirements reshape competitive positioning across European hospital networks.
United States
Ophthalmology clinic consolidation and diabetic retinopathy screening program expansion drive installed base growth. FDA predicate device limitations for AI-augmented systems extend review cycles by 12-18 months for novel classifications. The Boston-Cambridge corridor concentrates computational imaging algorithm development for diagnostic software modules.
Germany
Precision optics manufacturing clusters and national diabetes management protocols sustain premium instrument demand. EU MDR conformity assessment routes for Class IIa devices reduce registration friction for ISO 13485-certified manufacturers. Heidelberg and Jena anchor lens grinding capabilities for aspheric objective assemblies serving global export markets.
United Kingdom
Hospital network mergers have reduced independent purchasing committees by over one-third since 2020, consolidating procurement under enterprise platform agreements. NHS diabetic retinopathy screening mandates tighten standard-of-care protocols. London and Manchester ophthalmology centers deploy multi-modality installations with unified service contracts.
India
Tier-2 and tier-3 cities penetrate with portable widefield platforms where retinal imaging specialist density remains critically low. CDSCO medical device registration requirements govern import and local manufacturing compliance. Bangalore and Hyderabad development centers produce tablet-based image review software for rural screening programs.
Japan
University hospital research cores deploy adaptive optics platforms for photoreceptor-level imaging studies. PMDA pharmaceutical and medical device agency oversight governs software-as-medical-device classifications for AI-assisted diagnostic modules. Tokyo and Osaka precision electronics clusters supply fluorescence excitation subsystems for angiography-enabled instruments.
Widefield Imaging Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in widefield imaging systems. The upper tier combines precision optics manufacturing with captive software development capabilities, while mid-tier players concentrate on single-modality hardware or regional service networks. Three archetypes dominate: heritage optics conglomerates with century-old manufacturing legacies, laser scanning specialists with proprietary ultra-widefield intellectual property, and portable platform engineers targeting cost-sensitive emerging markets. Competitive moves concentrate on strategic partnerships for AI algorithm licensing and geographic expansion through distributor network establishment.
Among heritage German optics manufacturers, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify the integrated leader archetype through precision instrument manufacturing anchored in Baden-Württemberg and Heidelberg clusters. Optos represents the laser scanning specialist position with proprietary technology development. Forus Health Pvt Ltd occupies the portable platform engineer tier, exemplifying cost-engineered system design for emerging market penetration. These three company structures illustrate how competitive positioning stratifies across premium research instrumentation, established clinical installed bases, and rural screening accessibility vectors.
| Leading Market Players |
|---|
| Heidelberg Engineering GmbH |
| Optos |
| Visunex Medical Systems |
| Clarity Medical |
| Carl Zeiss Meditec AG |
| Centervue SpA |
| ZEISS Group |
| Forus Health Pvt Ltd |
| epipole limited |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between German precision optics foundries and widefield imaging manufacturers lock in supply access for aspheric objective assemblies while anchoring price visibility across multi-year procurement cycles. These arrangements insulate Heidelberg Engineering and Carl Zeiss Meditec from spot-market volatility in fluorophore inputs while exposing mid-tier vendors to margin compression when dye costs spike.
Pricing Analysis
Price spreads between German-manufactured premium instruments and Indian-assembled portable platforms exceed threefold across equivalent optical specifications. Camera systems deploy a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by field-of-view breadth and AI software bundling. Cost compression in the economy tier intensifies because CDSCO registration requirements force local assembly partnerships that fragment procurement leverage. Hospital networks in France and the United Kingdom demonstrate lowest price sensitivity due to enterprise platform consolidation, while rural screening programs in India absorb the highest sensitivity.
Supply Chain Analysis
Inventory buffers for indocyanine green and sodium fluorescein dyes rarely exceed sixty days given pharmaceutical raw material volatility, forcing manufacturers into quarterly procurement cycles. German and Japanese optical component foundries anchor supply for precision lens grinding, while Indian software development centers feed computational imaging modules. Single-source vulnerability concentrates in aspheric objective assemblies where Heidelberg and Jena clusters control specialized grinding equipment. Distribution runs through hospital procurement committees in consolidated networks and medical device distributors in fragmented markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The widefield imaging market is recovering from a cyclical trough driven by EU MDR compliance investment overhang, with hospital capital expenditure cycles now releasing pent-up replacement demand across European networks.
For Market Incumbents: Shield installed base revenue by embedding AI diagnostic modules into existing hardware through software-as-medical-device upgrade pathways, neutralizing portable platform threats from Indian manufacturers. Deepen backward integration into fluorescence excitation subsystem production to reduce dependency on Tokyo and Osaka electronics clusters. Prioritize ISO 13485 certification maintenance to accelerate EU MDR conformity assessment routes. For New Entrants and Emerging Players: Rural screening program infrastructure gaps in India's tier-2 and tier-3 cities offer immediate white-space penetration where specialist density constraints prevent incumbent platform deployment. Tablet-based image review software with offline diagnostic capability represents the most penetrable application layer. Pursue CDSCO registration partnerships with local assembly facilities to bypass import duty structures. For Investors and Strategic Acquirers: Computational imaging algorithm boutiques with FDA 510(k) clearance velocity and ophthalmic image annotation expertise represent the highest-conviction acquisition archetype. Long-term viability hinges on software-as-medical-device revenue streams displacing hardware replacement cycles. Monitor PMDA software classification guidance in Japan as the inflection indicator for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined routes for Class IIa devices reduce Heidelberg and Zeiss registration friction. |
| Hospital System Partnership | NHS diabetic retinopathy mandates in the United Kingdom consolidate procurement under enterprise agreements. |
| Software Companion Development | AI-assisted diagnostic modules require separate FDA clearances, extending Optos review cycles. |
| Backward Integration | In-house fluorescence excitation production reduces Tokyo electronics cluster dependency. |
| Reimbursement Strategy | German national diabetes management protocols embed widefield imaging into standard-of-care reimbursement codes. |
Study Parameters
A spread of perspectives from vitreoretinal surgeons, hospital purchasing committee chairs, biomedical engineers at university research cores, and GPO contracts managers converged on the working assumptions for installed base expansion and replacement cycle timing. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up triangulation across device shipment data and top-down reconciliation against healthcare capital expenditure surveys anchored volume estimates.
Segmentation dimensions modeled include product architecture, application setting, end-user category, and technology modality across the projection horizon. CAGRs derived from weighted regression across historical shipment trajectories and forward-looking reimbursement policy assumptions. Fluorophore cost volatility curves and precision optics lead time distributions fed scenario-based forecast intervals.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR conformity assessment; material policy shifts would require re-modeling software-as-medical-device classification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Europe CT Market
Imaging
Global Digital Photography Market
Imaging
On-Chip Color Filters Market
Imaging
Photography Equipment Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Global Mobile Image Sensor Market
Imaging
IP Camera Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Near Infra-Red Imaging Market
Imaging
Global Automotive Imaging Market
Imaging
Handheld Imaging Systems Market
Imaging
Global Ingaas Camera Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Camcorder Market
Imaging
Borescope Market