
 Camera Stabilizer Market | 2026-2036
Camera Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Stabilizer Market Intelligence
Carbon fiber is displacing aluminum alloy in premium gimbal construction and is recalibrating weight-to-stiffness ratios across mid-tier and professional product lines. SZ DJI Technology Co., Ltd. leverages its Shenzhen manufacturing base to control component costs and accelerate iteration cycles. Freefly Systems specializes in high-payload cinema stabilizers for aerial and handheld configurations. Zhiyun competes aggressively in the entry-level electronic gimbal segment through direct-to-consumer channel dominance.
A camera stabilizer is an electromechanical or passive device that maintains optical axis orientation during camera movement, typically employing brushless motors with encoder feedback loops achieving stabilization precision within 0.01 degrees, or counterweighted mechanical systems, to eliminate perceptible frame shake in recorded or transmitted video. Its primary commercial purpose is to reduce post-production correction costs and enable usable footage under dynamic filming conditions. Handheld gimbals now anchor the largest volume pool as smartphone and mirrorless camera operators prioritize portability over payload capacity. Electronic stabilization technology leads innovation investment, though hybrid mechanical-electronic systems retain margin concentration in broadcast and cinema applications where redundancy prevents shot failure.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU machinery and electromagnetic compatibility directives, and China's GB standards for electronic equipment safety collectively shape product certification timelines and market access costs for stabilizer manufacturers. RoHS substance restrictions and REACH chemical registration obligations in Europe further constrain material selection and supplier qualification processes. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to partition supply chains and delay product introductions in key territories.
Market Dynamics
Carbon fiber substitution in gimbal construction is compressing weight thresholds while China's NMPA imaging standards and EU RoHS substance mandates simultaneously reshape material qualification pathways and certification timelines across manufacturer portfolios.
Growth Catalysts
- Creator economy expansion:YouTube and TikTok content producers in Los Angeles and New York metro areas are driving volume demand for sub-2kg handheld electronic gimbals optimized for mirrorless camera payloads.
- REACH chemical registration:European downstream users now require full material disclosure for electronic imaging equipment, pushing manufacturers toward pre-qualified supplier networks that accelerate EU market entry.
- Brushless motor encoder precision:Stabilization accuracy within 0.01 degrees enables broadcast-grade footage capture without post-production correction, reducing post-house dependency for independent production units.
Market Restraints
- Rare earth magnet supply concentration:Brushless motor production depends on neodymium supply chains centered in China's Jiangxi and Inner Mongolia processing zones, creating single-source vulnerability for motor manufacturers.
- FCC electromagnetic emissions compliance:United States market access requires extensive pre-certification testing for wireless-enabled gimbals, extending product introduction timelines by 4-6 months for new entrants.
- Smartphone computational stabilization:Native optical and electronic stabilization in flagship mobile devices reduces attach rates for accessory stabilizers among casual video producers.
Strategic Opportunities
- India production incentives:PLI scheme benefits for electronic manufacturing services create cost-competitive assembly alternatives to Shenzhen-centric supply chains for mid-tier product lines.
- Hybrid mechanical-electronic systems:Broadcast and cinema applications require redundant stabilization architectures where motor failure cannot compromise shot integrity, preserving premium margin pools.
- Direct-to-consumer channel maturation:Platform-native brands are bypassing traditional camera retail distribution, capturing full margin stacks through owned e-commerce and social commerce integration.
Industry Challenges
- Embedded firmware engineering scarcity:PID control algorithm optimization for multi-axis stabilization requires specialized electromechanical software talent concentrated in Shenzhen, Tel Aviv, and Southern California.
- CE marking machinery directive alignment:EU regulatory interpretation variance between notified bodies creates inconsistent conformity assessment outcomes, forcing duplicate testing for pan-European distribution.
- Carbon fiber layup quality variance:Hand layup processes for premium gimbal arms produce stiffness inconsistencies that complicate automated assembly and require manual tuning, constraining scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Stabilizer Market |
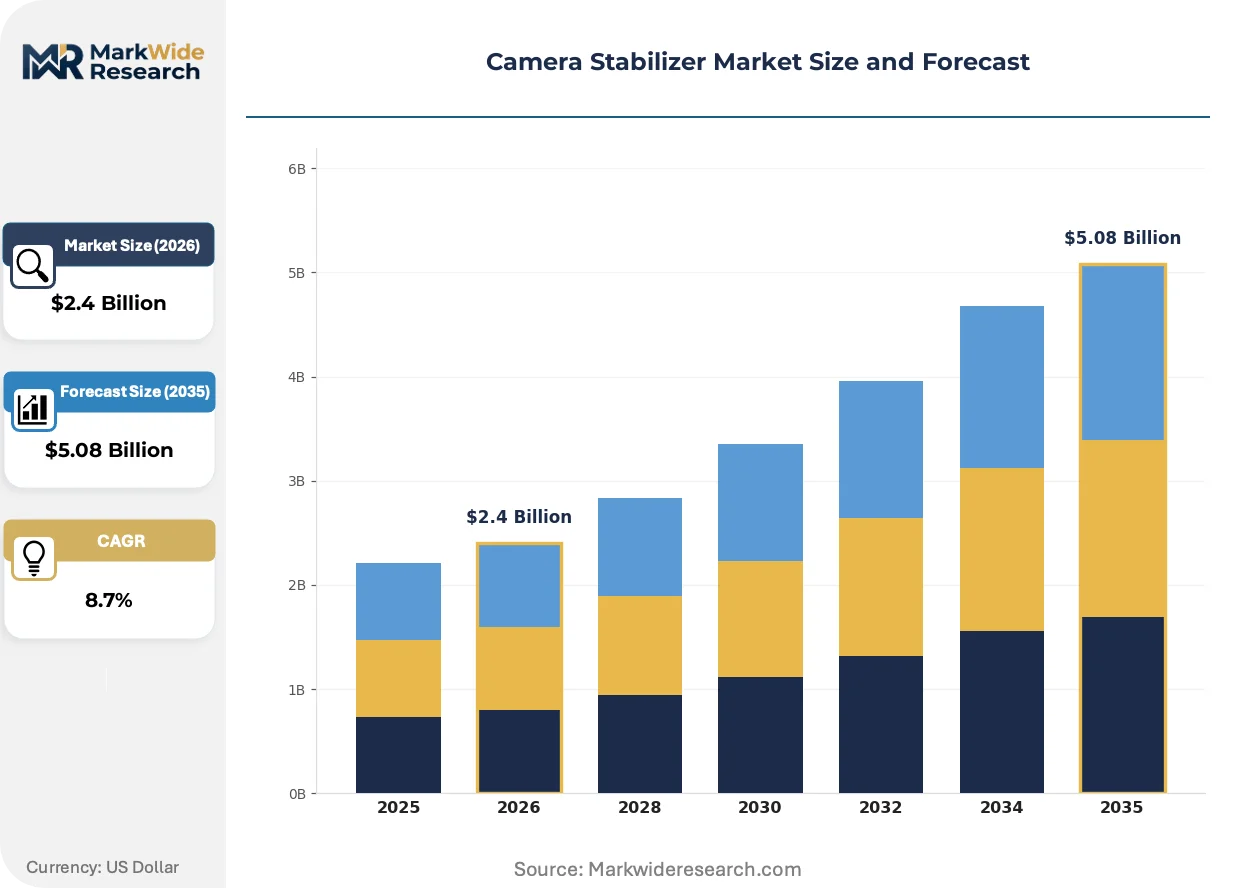
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Gimbals, Steadicams, Shoulder Mounts Technology: Mechanical, Electronic, Hybrid, Software Stabilization End User: Professional Filmmakers, Content Creators, Event Videographers, Broadcast Media Application: Film Production, Live Events, Aerial Photography, Sports Coverage |
| Companies Covered | FeiyuTech, Freefly Systems, SZ DJI Technology Co., Ltd., Tilta Inc., Ikan Corporation, Glidecam Industries, Inc., Tiffen Company, Zhiyun, Gudsen Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Stabilizer Market Strategic Shifts & Innovations
Active stabilization architectures are fragmenting into three distinct development vectors: materials science advancement, regulatory compliance automation, and distribution model disintermediation. Each vector carries distinct investment requirements and competitive implications.
Carbon fiber composite layup with variable thickness topology is consolidating structural performance in professional-grade gimbal arms. Cinema rental houses and commercial production companies in Los Angeles are specifying carbon fiber payload structures for 10kg+ camera packages. This material transition is consolidating supplier relationships around aerospace-qualified composite manufacturers with existing NADCAP certification, compressing vendor pools and extending qualification timelines for second-tier producers.
EU RoHS hazardous substance restrictions and REACH SVHC candidate list expansions are forcing material requalification across electronic imaging supply chains. Manufacturers must now track substance concentrations below 0.1% weight thresholds through three-tier supplier depth. Professional broadcast equipment vendors face the steepest compliance burden, as their product lifecycles exceed five years and require forward-looking substance restriction forecasting.
After-sales service unbundling from hardware purchase is reshaping buyer relationships in the entry-level segment. Direct-to-consumer brands now monetize firmware feature unlocks, extended warranty tiers, and cloud-based shot analytics through subscription attachments. This behavioral shift concentrates most visibly in the United States, where creator economy participants prioritize predictable operating expenditures over capital-intensive equipment ownership.
Camera Stabilizer Market Segmentation
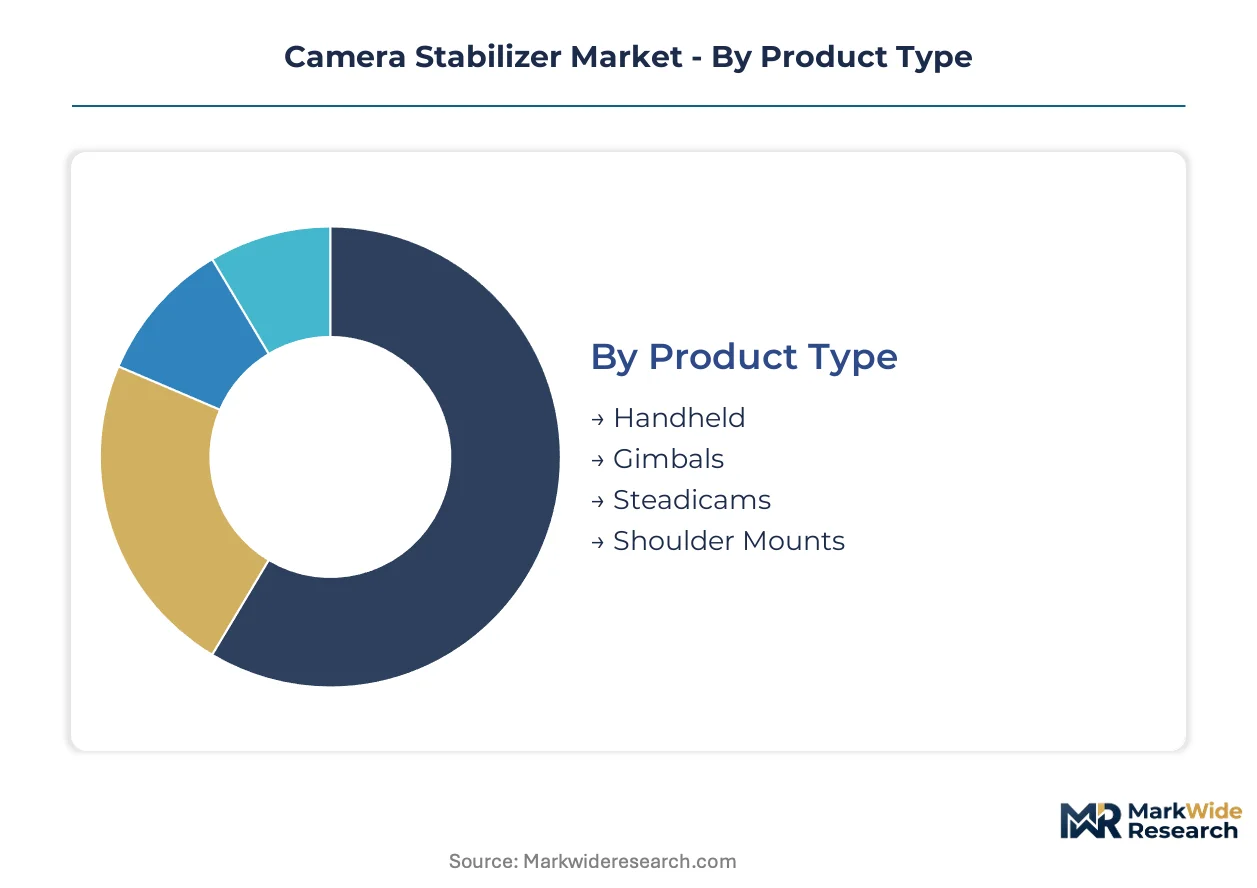
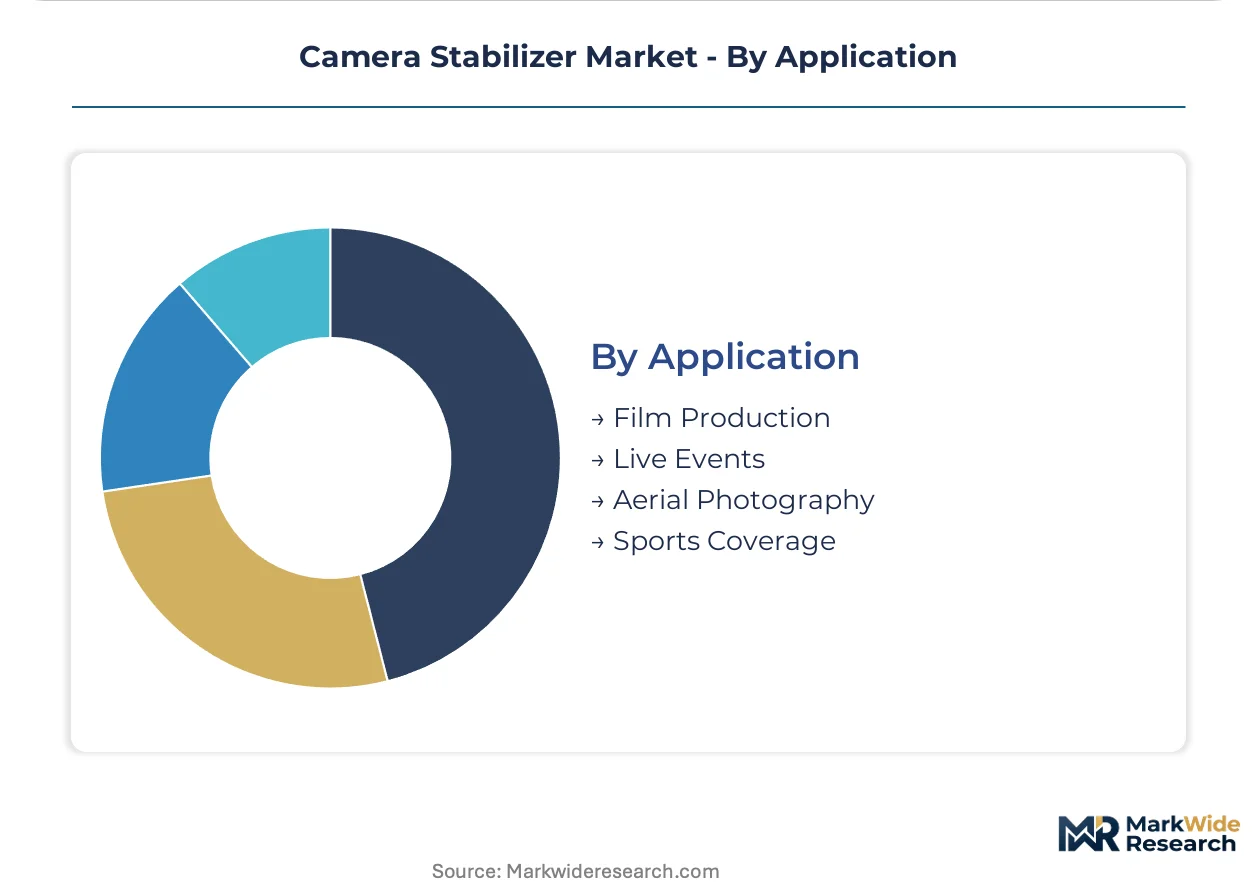
Camera stabilizer procurement patterns diverge sharply across payload requirements, operator skill levels, and production budgets. Manufacturers configure product portfolios around these axes to capture margin pools ranging from entry-level smartphone accessories to cinema-grade aerial rigs.
Product Type:
Carbon fiber construction and brushless motor density define performance tiers across physical stabilizer architectures.
- Handheld:Sub-2kg electronic gimbals dominate volume flows to mirrorless camera operators in Los Angeles and New York creator economies. YouTube and TikTok producers prioritize pocketable form factors over maximum payload capacity.
- Gimbals:Three-axis brushless systems with encoder feedback loops achieving 0.01-degree precision anchor professional workflows. SZ DJI Technology and Zhiyun compete aggressively here through Shenzhen manufacturing scale and direct-to-consumer channel dominance.
- Steadicams:Counterweighted mechanical systems retain broadcast and cinema penetration where operator skill substitutes for electronic complexity.
- Shoulder Mounts:Passive stabilization for ENG and documentary crews requiring rapid deployment without battery dependency.
Mature deployment sits with Steadicams in legacy broadcast infrastructure. Newer deployment is concentrated in Handheld electronic gimbals.
Technology:
Stabilization architectures segment by electromechanical sophistication and redundancy requirements.
- Electronic:Brushless motors with IMU-driven PID control algorithms process motion data at 1000Hz for real-time axis correction. FCC electromagnetic emissions compliance extends certification timelines for wireless-enabled variants.
- Hybrid:Mechanical-electronic redundancy prevents shot failure in cinema and broadcast applications where motor malfunction cannot compromise production. Freefly Systems specializes in high-payload configurations for aerial and handheld use.
- Mechanical:Counterweighted systems eliminate battery dependency and firmware failure modes entirely.
- Software Stabilization:Computational cropping and gyroscopic metadata processing in post-production reduces hardware attach rates among casual producers.
Electronic systems capture the steepest expansion trajectory. Hybrid architectures preserve premium margin concentration in professional tiers.
End User:
Operator sophistication and production budget determine feature prioritization and price elasticity.
- Content Creators:Solo operators in Los Angeles and New York metro areas drive sub-2kg handheld gimbal volume through platform-native monetization models.
- Professional Filmmakers:Commercial production companies and cinema rental houses specify carbon fiber payload structures for 10kg+ camera packages with NADCAP-certified composite sourcing.
- Event Videographers:Wedding and corporate operators balance portability against rapid setup requirements.
- Broadcast Media:Network news divisions mandate redundant stabilization and multi-year product lifecycles, intensifying REACH SVHC compliance burdens.
Established procurement patterns sit with Broadcast Media. Creator economy participants represent the fastest volume expansion.
Application:
Environmental constraints and shot dynamics dictate stabilizer specification requirements.
- Film Production:Narrative and commercial shoots demand hybrid redundancy and carbon fiber stiffness-to-weight ratios for complex camera movement.
- Live Events:Concert and conference operators prioritize rapid deployment and battery swap efficiency over maximum precision.
- Aerial Photography:Drone-mounted gimbals require vibration isolation and wind resistance optimization.
- Sports Coverage:Sideline and tracking applications demand weather sealing and impact tolerance for unpredictable field conditions.
Traditional volume concentration sits with Film Production. Sports Coverage is gaining share fastest through broadcast rights inflation and mobile production unit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hollywood production clusters and independent creator economies in Los Angeles and New York concentrate the heaviest demand for camera stabilizers worldwide. Regulatory divergence between jurisdictions threatens to partition supply chains and delay product introductions in key territories.
United States
FCC electromagnetic emissions standards extend certification timelines for wireless-enabled gimbals by 4-6 months for new entrants. Los Angeles commercial production companies specify carbon fiber payload structures for 10kg+ camera packages. New York metro area TikTok and YouTube creators drive volume demand for sub-2kg handheld electronic gimbals.
China
NMPA standards for electronic imaging equipment tighten material compliance requirements for manufacturers. Shenzhen manufacturing bases control component costs and accelerate iteration cycles for SZ DJI Technology and Zhiyun. Jiangxi and Inner Mongolia processing zones concentrate rare earth magnet supply chains for brushless motor production.
Germany
CE marking requirements under EU machinery and electromagnetic compatibility directives shape product certification timelines. REACH chemical registration obligations push manufacturers toward pre-qualified supplier networks. Broadcast equipment vendors in Munich and Hamburg face steep compliance burdens due to product lifecycles exceeding five years.
India
PLI scheme benefits for electronic manufacturing services create cost-competitive assembly alternatives to Shenzhen-centric supply chains. BIS standards for electronic equipment safety constrain material selection processes. Karnataka and Tamil Nadu emerging as alternative production locations for mid-tier handheld gimbal lines.
Japan
METI industrial policy supports precision electromechanical component manufacturing for professional imaging equipment. JIS standards for electronic device safety align with international certification frameworks. Tokyo and Osaka metropolitan areas sustain demand for broadcast-grade hybrid stabilization systems in commercial production.
Camera Stabilizer Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers scale Shenzhen-adjacent production to serve direct-to-consumer channels. The vendor base organizes around three strategic archetypes: Shenzhen-based scale operators controlling manufacturing economics, California-specialized cinema equipment developers, and platform-native brands bypassing traditional retail distribution. M&A activity and geographic diversification represent the two dominant competitive moves as firms seek to reduce single-source supply chain exposure.
Within the Shenzhen manufacturing tier, SZ DJI Technology Co., Ltd. and Zhiyun exemplify scale-driven competitive positioning through component cost control and iteration velocity. Freefly Systems occupies a position among California-based specialists in high-payload cinema configurations. FeiyuTech represents the direct-to-consumer channel maturation archetype through platform-native brand development.
| Leading Market Players |
|---|
| FeiyuTech |
| Freefly Systems |
| SZ DJI Technology Co., Ltd. |
| Tilta Inc. |
| Ikan Corporation |
| Glidecam Industries, Inc. |
| Tiffen Company |
| Zhiyun |
| Gudsen Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Carbon fiber certification tiers split the Camera Stabilizer Market into divergent pricing bands and sourcing configurations. NADCAP-qualified aerospace composite suppliers command 40-60% cost premiums over uncertified alternatives, compressing margins for mid-tier producers while insulating premium cinema equipment vendors from price-based competition.
Pricing Analysis
Volume concentration in sub-2kg handheld gimbals compresses per-unit margins, while 10kg+ cinema configurations preserve premium pricing through carbon fiber payload specifications and hybrid redundancy architectures. Three-tier pricing structure across premium, standard, and economy levels differentiates by encoder precision grades and REACH pre-certification status. Pricing pressure stems from smartphone native stabilization eroding attach rates among casual producers. Content creators in Los Angeles and New York exhibit highest price sensitivity, whereas commercial production companies prioritize shot reliability over unit cost.
Supply Chain Analysis
Trans-Pacific freight volatility amplifies landed cost variance for carbon fiber composite shipments from aerospace-qualified suppliers. Manufacturing concentrates in China, with Shenzhen controlling component costs and iteration velocity for SZ DJI Technology and Zhiyun, while India PLI incentives build Karnataka and Tamil Nadu as emerging assembly alternatives. Brushless motor production draws from neodymium processing in Jiangxi and Inner Mongolia, creating single-source vulnerability for electronic gimbal architectures. Distribution runs through direct-to-consumer channels bypassing traditional camera retail, capturing full margin stacks for platform-native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare earth magnet supply concentration in China's Jiangxi and Inner Mongolia processing zones constrains brushless motor capacity, propping pricing power for manufacturers with secured magnet offtake agreements.
For Market Incumbents: To counter smartphone computational stabilization erosion in the casual video segment, SZ DJI Technology and Zhiyun should deepen backward integration into brushless motor production through captive neodymium sourcing, while accelerating carbon fiber arm in-house manufacturing to compress NADCAP supplier dependency timelines. For New Entrants and Emerging Players: Firmware feature unlock monetization represents the most penetrable wedge for platform-native brands targeting United States creator economy participants, with subscription-based shot analytics offering recurring revenue attachment to hardware sales through owned e-commerce channels. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid mechanical-electronic specialists given broadcast redundancy requirements preserving premium margin pools, with FCC certification timelines serving as the inflection signal for wireless-enabled gimbal market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Certification Investment | NADCAP qualification compresses vendor pools and extends premium pricing power for cinema equipment. |
| Brushless Motor Backward Integration | Captive neodymium sourcing insulates against Jiangxi and Inner Mongolia supply concentration risks. |
| Direct-to-Consumer Channel Expansion | Platform-native brands bypass traditional retail, capturing full margin stacks through owned e-commerce. |
| Hybrid Redundancy Architecture Development | Mechanical-electronic backup systems preserve broadcast and cinema premium tier positioning. |
| India PLI Manufacturing Relocation | Karnataka and Tamil Nadu assembly alternatives reduce Shenzhen-centric single-source exposure. |
Research Approach
Document review covered FCC electromagnetic emissions filings, EU REACH SVHC candidate list updates, and China NMPA electronic imaging equipment standards, complemented by interviews with product development leads at Shenzhen-based scale manufacturers, Los Angeles commercial production company equipment buyers, and New York metro area content creator procurement decision-makers. Secondary validation drew from customs trade data, SEC equipment manufacturer disclosures, and platform-native brand e-commerce analytics. Bottom-up unit shipment estimates triangulated against top-down production capacity assessments.
Segment-level outputs across product type, stabilization technology, end-user archetype, and application environment were generated over the projection horizon. CAGRs were derived from regression analysis against historical shipment trajectories, with inputs including brushless motor encoder precision adoption curves and carbon fiber substitution rates in premium gimbal construction.
Several conditions sit outside the modeled scope, including unannounced smartphone optical stabilization technology advances and potential rare earth export restriction policy shifts. Forecasts reflect stated assumptions around regulatory timeline stability and material qualification pathway continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
CCD Image Sensors Market
Imaging
Image Intensifier Market
Imaging
Global Camera Module Market
Imaging
Hybrid Imaging Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Photoacoustic Imaging Market
Imaging
Light Field Market
Imaging
Multi Camera System Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Digital Image Processing Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Global Label-Free Array Systems Market
Imaging
Ent Cameras Market