
 Industrial Automation Sensors Market | 2026-2036
Industrial Automation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Sensors Market Intelligence
The capability gap between vertically integrated sensor manufacturers and modular component suppliers is collapsing as scale economies favor firms with captive semiconductor fabrication. Siemens leverages in-house chip production to sustain margin resilience across its photoelectric and proximity sensor portfolios. Rockwell Automation anchors its North American position through deep channel control in process control applications, while ABB competes aggressively in robotics integration with specialized force-torque sensing modules.
Industrial automation sensors are electromechanical devices that transduce physical variables—temperature, pressure, position, or optical reflectance—into standardized electrical signals, typically operating at 24V DC with IP67 ingress protection for factory floor durability. Their primary purpose is enabling closed-loop control in automated systems where human intervention is economically or physically impractical. Wired technology still dominates installed base value, though wireless segments are capturing disproportionate growth in material handling retrofits where cable routing proves cost-prohibitive. Photoelectric sensors occupy the largest share of replacement demand, while quality inspection applications concentrate margin pools due to vision-system complexity and shorter replacement cycles.
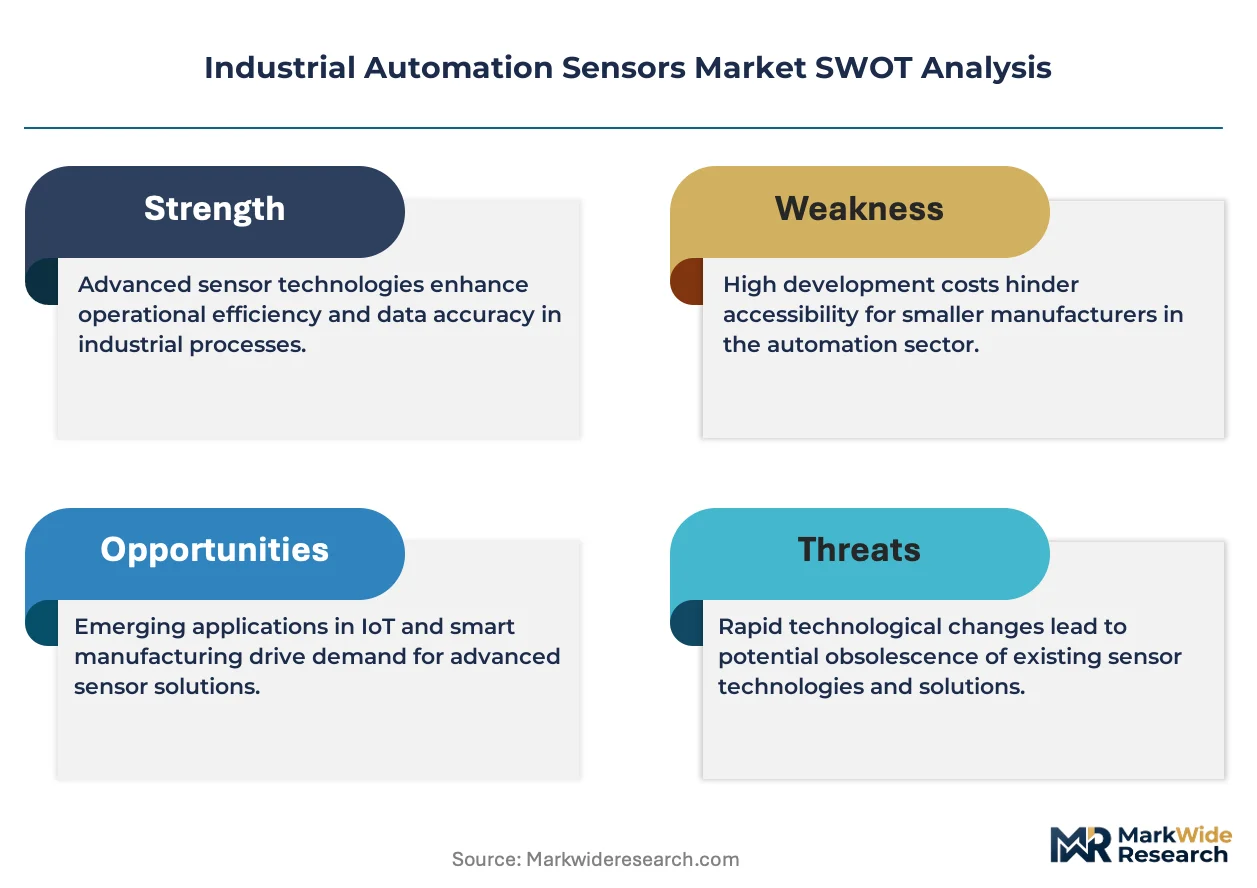
FDA scrutiny of pharmaceutical batch consistency is elevating demand for calibrated pressure and temperature sensors in aseptic processing environments. EPA emissions monitoring mandates and OSHA machine-guarding standards are jointly expanding the addressable base for proximity and laser displacement sensors in chemical plants and heavy manufacturing. Stakeholders must weigh the capital trade-off between incremental wired upgrades and full wireless architecture overhauls as cybersecurity frameworks from IEC and NIST mature.
Market Dynamics
Automotive assembly plants are accelerating sensor deployment for precision robotics, compressing replacement cycles and forcing component suppliers to synchronize R&D cadences with OEM platform launches.
Growth Catalysts
- REACH compliance:Tightening material disclosure requirements for electronic components in Europe are compelling manufacturers to redesign sensor housings and substrates, opening specification windows for compliant suppliers.
- Vision-system complexity:Quality inspection applications are concentrating margin pools due to shorter replacement cycles and embedded AI processing requirements in semiconductor fabrication.
- Germany's industrial corridor:OEMs retrofitting legacy lines with smart sensing architectures are generating concentrated demand for IO-Link compatible photoelectric and inductive proximity devices.
Market Restraints
- Silicon wafer supply concentration:Taiwan and South Korea dominate 300mm wafer production, exposing sensor manufacturers to geopolitical disruption in semiconductor feedstocks.
- IP67 ingress protection standards:The cost premium for hermetic sealing and conformal coating limits price competitiveness in cost-sensitive material handling retrofits.
- Wireless latency limitations:Time-critical motion control applications in robotics integration still mandate wired architectures, constraining addressable market expansion for battery-powered sensor nodes.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting sensor assembly investments to serve domestic automation equipment demand.
- FDA pharmaceutical mandates:Calibrated pressure and temperature sensors for aseptic processing environments represent underpenetrated demand in batch consistency monitoring.
- Time-Sensitive Networking convergence:The integration of IEEE 802.1AS time synchronization with industrial Ethernet is enabling deterministic wireless for motion control applications previously reserved for wired fieldbus.
Industry Challenges
- Cybersecurity framework maturity:IEC 62443 and NIST SP 800-82 implementation timelines are delaying wireless architecture certifications, extending sales cycles for retrofit projects.
- Legacy PLC integration:Brownfield deployments require protocol translation gateways that add cost and failure points, complicating margin structures for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Sensors Market |
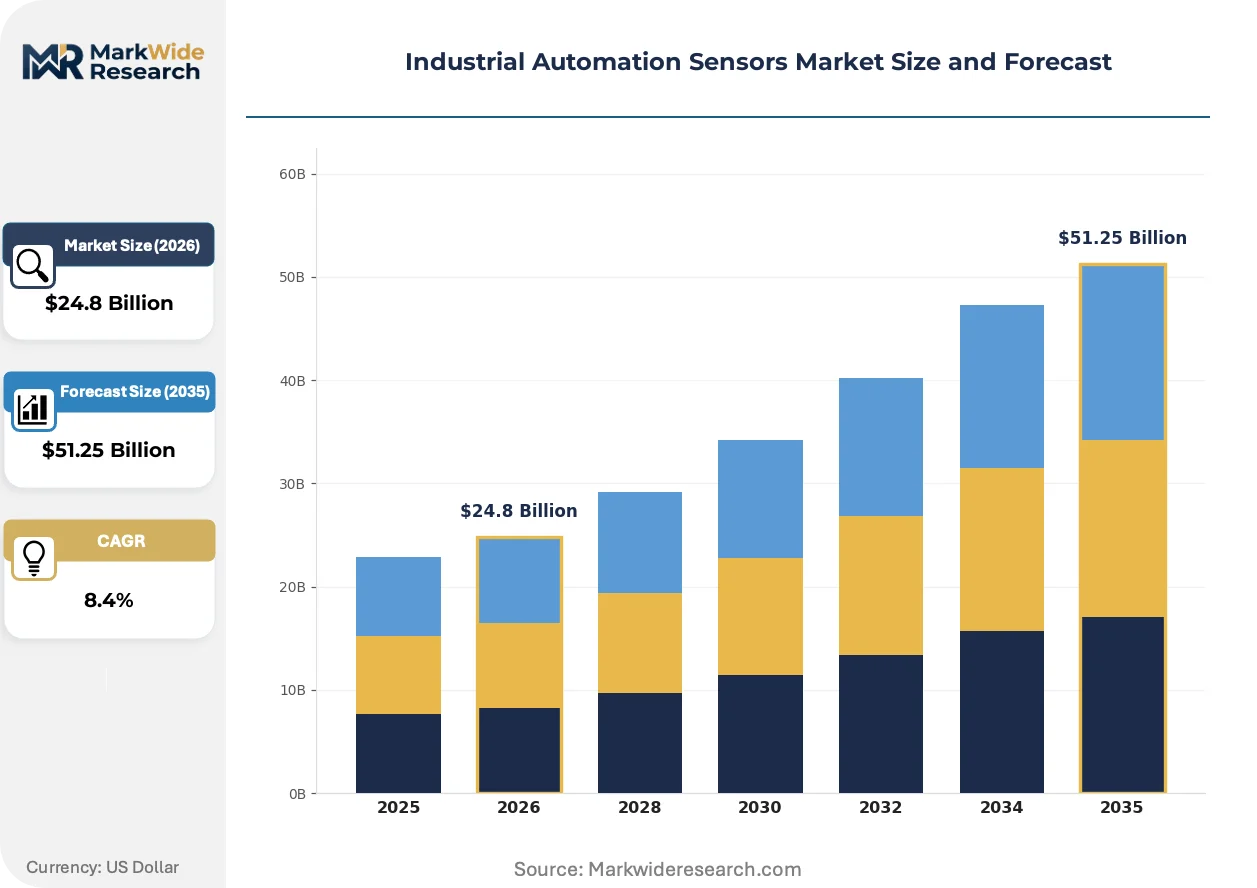
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Proximity, Photoelectric, Ultrasonic, Capacitive, Inductive, Magnetic Technology: Wired, Wireless, Fiber Optic, Infrared, Laser, Acoustic Application: Process Control, Robotics, Material Handling, Quality Inspection, Packaging, Assembly Lines End User Industry: Manufacturing Units, Oil Refineries, Food Processing Plants, Electronics Facilities, Chemical Plants, Pharmaceutical Developers |
| Companies Covered | Emerson Automation Solutions, FANUC, Rockwell Automation, Mitsubishi Electric, Cognex Corporation, Siemens, Honeywell, Schneider Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Sensors Market Strategic Shifts & Innovations
Sensor architectures are bifurcating between high-performance edge-computing nodes and stripped-down commodity transducers, with differentiation increasingly residing in firmware rather than hardware specifications.
MEMS-based pressure sensing is miniaturizing die footprints below 2mm² while maintaining 0.1% full-scale accuracy, enabling multi-point array deployments in hydraulic manifold monitoring. Tier-one automotive suppliers are qualifying these devices for transmission control modules at 18-month validation cadences. The technology is miniaturizing packaging constraints that previously limited sensor density in confined mechanical assemblies.
EPA emissions monitoring mandates are expanding the addressable base for laser displacement sensors in chemical plant leak detection and flare stack monitoring. Continuous emissions monitoring systems now require redundant sensor paths with SIL 2 certification, elevating procurement specifications above commodity alternatives. Chemical processors in Texas and Louisiana are consolidating vendor lists to suppliers with captive calibration laboratories.
Buying committees are unbundling sensor hardware from lifecycle service contracts, compressing upfront capital outlays while elongating total cost of ownership evaluation horizons. Distributors are responding with inventory consignment programs that transfer working capital risk from plant maintenance departments. This pattern is most pronounced in German automotive supply chains where OEMs mandate vendor-managed inventory for line-side sensor replenishment.
Industrial Automation Sensors Market Segmentation
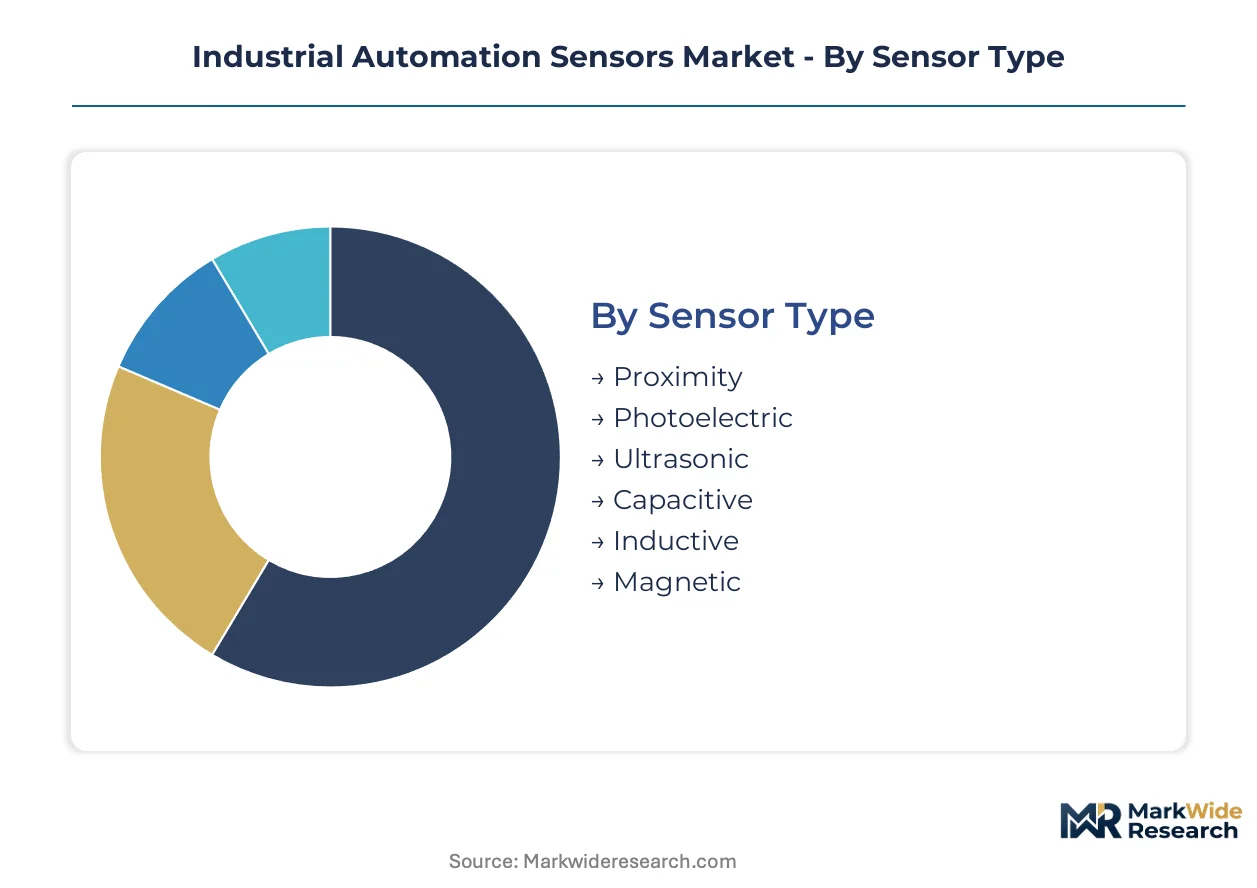
Industrial automation sensors fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct channel strategies, margin profiles, and competitive intensity patterns that shape supplier positioning.
Sensor Type:
Channel distribution varies sharply by sensing modality—photoelectric and proximity devices flow through electrical distributors with high SKU velocity, while specialized magnetic and ultrasonic variants concentrate in direct OEM specification.
- Photoelectric:These sensors detect object presence through emitted light beam interruption or reflectance, typically operating at 10-30V DC with sensing ranges spanning 0.1 to 60 meters. Demand concentrates in German automotive supply chains where OEMs mandate IO-Link compatibility for line-side replenishment systems. REACH compliance on housing materials is compressing supplier qualification timelines.
- Proximity:Inductive variants dominate metal detection in CNC machine tools and conveyor systems, with IP67-rated cylindrical housings constituting the volume standard. Retrofit demand in Texas chemical processing clusters favors 18mm barrel formats with M12 quick-disconnect cabling. OSHA machine-guarding standards are expanding specification requirements for fail-safe inductive arrays.
- Ultrasonic:Time-of-flight measurement enables liquid level and transparent object detection where optical methods fail.
- Capacitive:Dielectric sensing targets bulk solids and aqueous media in food processing environments requiring sanitary washdown ratings.
- Inductive:Eddy-current principles deliver reliable ferrous detection without physical contact in high-vibration stamping press applications.
- Magnetic:Reed and Hall-effect devices serve cylinder position feedback in pneumatic automation with minimal power draw.
Photoelectric dominates installed base. Proximity is where expansion concentrates.
Technology:
Cost tiering separates commodity wired fieldbus deployments from premium wireless architectures carrying cybersecurity certification premiums.
- Wired:4-20mA analog and digital IO-Link protocols constitute the installed base majority, with M12 connector standardization enabling rapid replacement. Brownfield manufacturing units in Louisiana petrochemical corridors favor wired reliability for SIL-rated safety loops. Legacy PLC integration requirements extend sales cycles through gateway procurement.
- Wireless:Battery-powered sensor nodes with IEEE 802.15.4 mesh networking are gaining share in material handling retrofits where cable routing costs exceed hardware premiums. German automotive plants pilot wireless torque monitoring on final assembly lines to eliminate slip-ring maintenance. IEC 62443 certification delays are constraining rollout velocity.
- Fiber Optic:Immunity to electromagnetic interference suits welding cell and induction heating applications.
- Infrared:Thermal detection arrays monitor bearing temperature and electrical hotspot conditions.
- Laser:Triangulation and time-of-flight methods deliver micrometer-precision displacement for semiconductor wafer alignment.
- Acoustic:Vibration signature analysis enables predictive maintenance on rotating machinery.
Wired technology anchors current procurement volumes. Wireless architectures are climbing the fastest as cybersecurity frameworks mature.
Application:
Volume concentration in process control and material handling contrasts with margin concentration in vision-integrated quality inspection.
- Process Control:Pressure, temperature, and flow sensors enable closed-loop regulation in continuous manufacturing with 99.99% uptime requirements. Oil refineries along the US Gulf Coast consolidate vendor lists to suppliers with captive calibration laboratories meeting EPA emissions monitoring mandates. Redundant sensor paths with SIL 2 certification elevate procurement specifications.
- Quality Inspection:Machine vision systems with embedded AI processing inspect semiconductor wafers and pharmaceutical packaging at sub-millimeter resolution. FDA scrutiny of pharmaceutical batch consistency is driving calibrated sensor demand in aseptic processing environments. Shorter replacement cycles concentrate margin pools.
- Robotics:Force-torque and proximity sensing enable collaborative robot safety and precision assembly.
- Material Handling:Photoelectric arrays and laser distance sensors coordinate automated storage and retrieval systems.
- Packaging:Registration mark detection and fill-level monitoring ensure consistent consumer goods presentation.
- Assembly Lines:Part presence verification and torque feedback synchronize multi-station automation.
Process control dominates installed base. Quality inspection is where margin expansion concentrates.
End User Industry:
Customer maturity varies—electronics facilities and pharmaceutical developers specify premium validated sensors, while manufacturing units prioritize total cost of ownership.
- Manufacturing Units:General automation across discrete industries consumes high-volume proximity and photoelectric devices through distributor inventory consignment programs. India's PLI scheme for electronics manufacturing is attracting sensor assembly investments to serve domestic automation equipment demand.
- Pharmaceutical Developers:Aseptic processing and batch consistency monitoring require calibrated pressure and temperature sensors with full documentation trails. FDA validation protocols extend procurement lead times but secure multi-year supply agreements.
- Oil Refineries:Continuous emissions monitoring and flare stack applications demand laser displacement sensors with redundant certification.
- Food Processing Plants:IP69K washdown ratings and hygienic design standards govern sensor selection for CIP/SIP compliance.
- Electronics Facilities:Cleanroom-compatible particle counters and precision positioning sensors support semiconductor fabrication.
- Chemical Plants:Corrosion-resistant housings and intrinsically safe electronics address hazardous area classifications.
Manufacturing units dominate installed base. Pharmaceutical developers are where specification premium expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where IO-Link compatibility commands specification premiums, while cost-sensitive material handling retrofits in India compress margins through distributor consignment programs. This asymmetry shapes regional deployment strategies across the forecast window.
United States
Louisiana and Texas petrochemical clusters drive demand for SIL 2-certified laser displacement sensors in continuous emissions monitoring. EPA mandates on flare stack and leak detection systems elevate procurement specifications above commodity alternatives. Houston-area refineries consolidate vendor lists to suppliers with captive calibration laboratories.
Germany
Automotive OEMs in Stuttgart and Munich mandate IO-Link compatible photoelectric devices for line-side replenishment systems. REACH compliance on housing materials compresses supplier qualification timelines for retrofitted legacy lines. Baden-Württemberg's industrial corridor generates concentrated specification demand for smart sensing architectures.
China
Semiconductor fabrication facilities in Shanghai and Beijing deploy MEMS-based pressure sensing arrays at sub-2mm² die footprints. MIIT standards on industrial Ethernet convergence accelerate Time-Sensitive Networking pilots for deterministic wireless motion control. Yangtze River Delta electronics manufacturers qualify 18-month validation cadences for transmission control modules.
India
PLI scheme incentives attract sensor assembly investments to serve domestic automation equipment demand in Maharashtra and Gujarat. Cost-sensitive material handling retrofits favor wireless architectures where cable routing proves prohibitive. Pune and Ahmedabad manufacturing corridors pilot battery-powered sensor nodes with IEEE 802.15.4 mesh networking.
Japan
Collaborative robot safety systems in Nagoya and Osaka integrate force-torque sensing modules with specialized robotics architectures. METI guidance on cybersecurity framework maturity delays wireless certifications, extending sales cycles for brownfield deployments. Chubu region automotive suppliers synchronize R&D cadences with 18-month platform validation timelines.
Industrial Automation Sensors Market Key Industry Players
Concentration sits with diversified industrial conglomerates that leverage in-house semiconductor fabrication for margin resilience across photoelectric and proximity sensor portfolios. The vendor base stratifies into three tiers: vertically integrated giants with captive chip production, modular component specialists serving distributor channels, and vision-system pure-plays capturing quality inspection premiums. Scale economies favor firms controlling upstream wafer supply, while firmware differentiation increasingly displaces hardware specifications as the primary competitive vector. Dominant competitive moves include backward integration into semiconductor feedstocks and strategic partnerships for IO-Link protocol certification.
Within the diversified industrial tier, Siemens and ABB exemplify archetypes of vertical integration strategies, with the former leveraging in-house chip production and the latter competing aggressively in robotics integration. Rockwell Automation anchors the North American position through channel control in process control applications. Among vision-system specialists, Cognex Corporation occupies a position exemplifying margin concentration in quality inspection through embedded AI processing requirements.
| Leading Market Players |
|---|
| Emerson Automation Solutions |
| FANUC |
| Rockwell Automation |
| Mitsubishi Electric |
| Cognex Corporation |
| Siemens |
| Honeywell |
| Schneider Electric |
| ABB |
| Others |
Cost & Logistics Intelligence
Eighteen-week lead times for IO-Link compatible photoelectric sensors concentrate pricing power with German distributors serving Stuttgart automotive corridors, while Texas petrochemical buyers compress margins through vendor-managed inventory consignment programs. This inventory-service trade-off separates specification-premium capture from working-capital efficiency across regional demand clusters.
Pricing Analysis
Configured-to-order pricing for IO-Link enabled proximity sensors commands 35-40 percent premiums over standard M12 barrel formats in German automotive supply chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with SIL 2 certified laser displacement sensors capturing sustained premiums in EPA-mandated emissions monitoring applications. Price erosion runs through commodity photoelectric devices in Indian material handling retrofits where PLI scheme assembly investments intensify local competition. Pharmaceutical developers exhibit lowest price sensitivity due to FDA validation protocol requirements, while general manufacturing units prioritize total cost of ownership through distributor consignment programs.
Supply Chain Analysis
Just-in-time inventory strategies dominate German automotive corridors where OEMs mandate vendor-managed line-side replenishment, while strategic stockpiling of MEMS pressure sensing die concentrates in Shanghai semiconductor fabrication facilities. Taiwan and South Korea anchor 300mm wafer supply for sensor semiconductor feedstocks, with China and Japan providing packaged MEMS substrates and magnetic sensing elements. Single-source vulnerability in Taiwan wafer production exposes sensor manufacturers to geopolitical disruption. Distribution runs through electrical distributors with high SKU velocity for photoelectric and proximity devices, while specialized force-torque modules flow direct to robotics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial automation sensors trace capital expenditure cycles in automotive and petrochemical end-markets, with German OEM platform launches and US Gulf Coast refinery upgrades signaling recovery phase entry.
For Market Incumbents: Compound margin resilience through captive semiconductor fabrication investments that offset silicon wafer supply concentration risks in Taiwan. Deepen channel control in process control applications to defend against modular component specialists encroaching on distributor relationships. Prioritize IO-Link protocol certification investments to sustain specification premiums in Baden-Württemberg automotive corridors. For New Entrants and Emerging Players: Lead with wireless sensor node architectures targeting Indian material handling retrofits where cable routing costs exceed hardware premiums and cybersecurity certification delays have constrained incumbent rollout velocity. Focus initial deployment on Pune and Ahmedabad manufacturing corridors piloting IEEE 802.15.4 mesh networking. Pursue strategic partnerships with industrial Ethernet convergence specialists to accelerate Time-Sensitive Networking integration for deterministic motion control applications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core sensing portfolios to focus on software-defined automation platforms. Five-to-ten year viability hinges on firmware differentiation displacing hardware specifications as the primary competitive vector. Monitor IEC 62443 certification velocity as the inflection signal indicating wireless architecture readiness for time-critical robotics integration previously reserved for wired fieldbus.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | In-house wafer production insulates Siemens and ABB from Taiwan supply concentration risks. |
| IO-Link Protocol Certification Investment | REACH compliant housing materials combined with digital interface compatibility capture German OEM specification windows. |
| Wireless Architecture Cybersecurity Certification | IEC 62443 compliance unlocks material handling retrofit demand where cable routing proves cost-prohibitive. |
| Strategic Partnership for Time-Sensitive Networking | IEEE 802.1AS integration enables deterministic wireless for robotics applications previously mandating wired architectures. |
| Vendor-Managed Inventory Program Expansion | Inventory consignment transfers working capital risk from plant maintenance departments to distributor balance sheets. |
Research Approach
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distributor channel partners anchors the qualitative findings against secondary validation from SEC filings, customs and trade data, IEC certification registries, and automotive production databases. Bottom-up sensor shipment estimates triangulate with top-down industrial automation equipment capex trends to constrain forecast variance.
Sensitivity analysis across sensor type, technology architecture, application vertical, and end-user industry segmentation dimensions shapes the analytical framework over the projection horizon. CAGRs derive from installed base replacement cycle analysis and greenfield deployment intensity by regional manufacturing cluster. Forecast inputs incorporate MEMS die miniaturization trajectories, IO-Link adoption curves in German automotive supply chains, and EPA emissions monitoring mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive platform investment cycles and stable semiconductor feedstock access would require recalibration. Forecasts reflect documented assumptions regarding cybersecurity framework maturity and REACH compliance implementation velocity. Revision becomes warranted when wireless latency benchmarks cross thresholds enabling time-critical motion control displacement of wired architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Handheld GPS Units Market
Sensors
Gesture Recognition in Retail Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Yield Monitoring Systems Market
Sensors
Lidar in Mapping Market
Sensors
Indoor Location Market
Sensors
Traffic Sensor Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Asia Pacific RFID Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Eye Tracking Solutions Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Robot Sensor Market
Sensors
Handheld RFID Readers Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Bluetooth Photo Capture Device Market