
 Asia Pacific RFID Market | 2026-2036
Asia Pacific RFID Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific RFID Market Analysis
Chinese semiconductor foundries is restructuring UHF chip output to serve domestic logistics platforms before export commitments. NXP Semiconductors leverages its Eindhoven-to-Shanghai design pipeline to anchor high-security tag supply for Asia Pacific banking clients. Fujitsu Limited dominates railway asset tracking across Japan's JR network, while Invengo Technology Pte Ltd specializes in library and apparel RFID systems across Singapore and Malaysia.
Radio frequency identification uses electromagnetic fields to automatically identify and track tags attached to objects, typically operating between 125 kHz and 960 MHz depending on the protocol layer. The technology enables real-time data capture without line-of-sight requirements, making it indispensable for automated inventory and access systems. Passive RFID leads unit volume across the region due to minimal per-tag cost, while UHF technology captures the fastest growth trajectory as warehouse automation intensifies. Inventory management applications command the deepest margin pools, though asset tracking in healthcare is gaining structural importance as hospital networks digitize equipment fleets.
China's MIIT governs radio spectrum licensing for UHF RFID deployments, while Japan's METI coordinates industrial standardization through JIS frameworks and India's TRAI manages frequency allocation for logistics networks. These regulators shape demand by mandating interoperability certifications and restricting non-compliant imports. Stakeholders must monitor spectrum harmonization talks between Beijing, Tokyo, and New Delhi, as divergent frequency bands threaten cross-border tag compatibility.
Market Dynamics
China's MIIT spectrum reallocation is compressing UHF RFID deployment timelines, forcing manufacturers to redesign chip architectures ahead of domestic logistics platform rollouts while export commitments face secondary prioritization.
Growth Catalysts
- India's Pharmaceutical Serialization Mandate:Item-level tracking requirements under CDSCO regulations are pulling passive UHF tags into pharmaceutical supply chains at container-to-unit granularity.
- Japan's Railway Digitization:METI-coordinated JIS standardization is embedding RFID into JR network asset tracking, creating captive demand for high-durability transponders.
- Warehouse Automation Intensification:Southeast Asian retail chains are deploying real-time inventory systems, with Singapore and Malaysia leading apparel and library system integration.
Market Restraints
- Silicon Wafer Cost Volatility:Foundry capacity constraints in East Asia are inflating UHF chip input costs, compressing tag margins for passive RFID producers.
- Cross-Border Frequency Fragmentation:Divergent UHF bands between Beijing, Tokyo, and New Delhi are creating tag incompatibility, fragmenting regional supply chains.
- Barcode Persistence in Low-Value Goods:One-dimensional optical codes continue displacing RFID in price-sensitive consumer packaging across Indonesia and Vietnam.
Strategic Opportunities
- Indonesia's Unpenetrated Apparel Sector:Garment export compliance requirements are opening doors for item-level RFID in Jakarta-Bandung manufacturing clusters.
- Healthcare Equipment Digitization:Hospital networks across Australia and South Korea are digitizing equipment fleets, pulling active RFID into asset tracking workflows.
- Sensor-RFID Convergence:Temperature-logging tags are penetrating cold-chain pharmaceuticals, with temperature-sensitive biologics driving hybrid tag adoption.
Industry Challenges
- RF Engineering Talent Scarcity:Antenna design and spectrum optimization expertise concentrates in Shanghai and Tokyo, leaving Southeast Asian deployers dependent on foreign engineering services.
- Legacy Warehouse Management Integration:ERP systems in established logistics networks require middleware development, extending deployment timelines and inflating implementation costs.
- Interoperability Certification Delays:Multi-jurisdiction testing for MIIT, METI, and TRAI compliance is stretching product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific RFID Market |
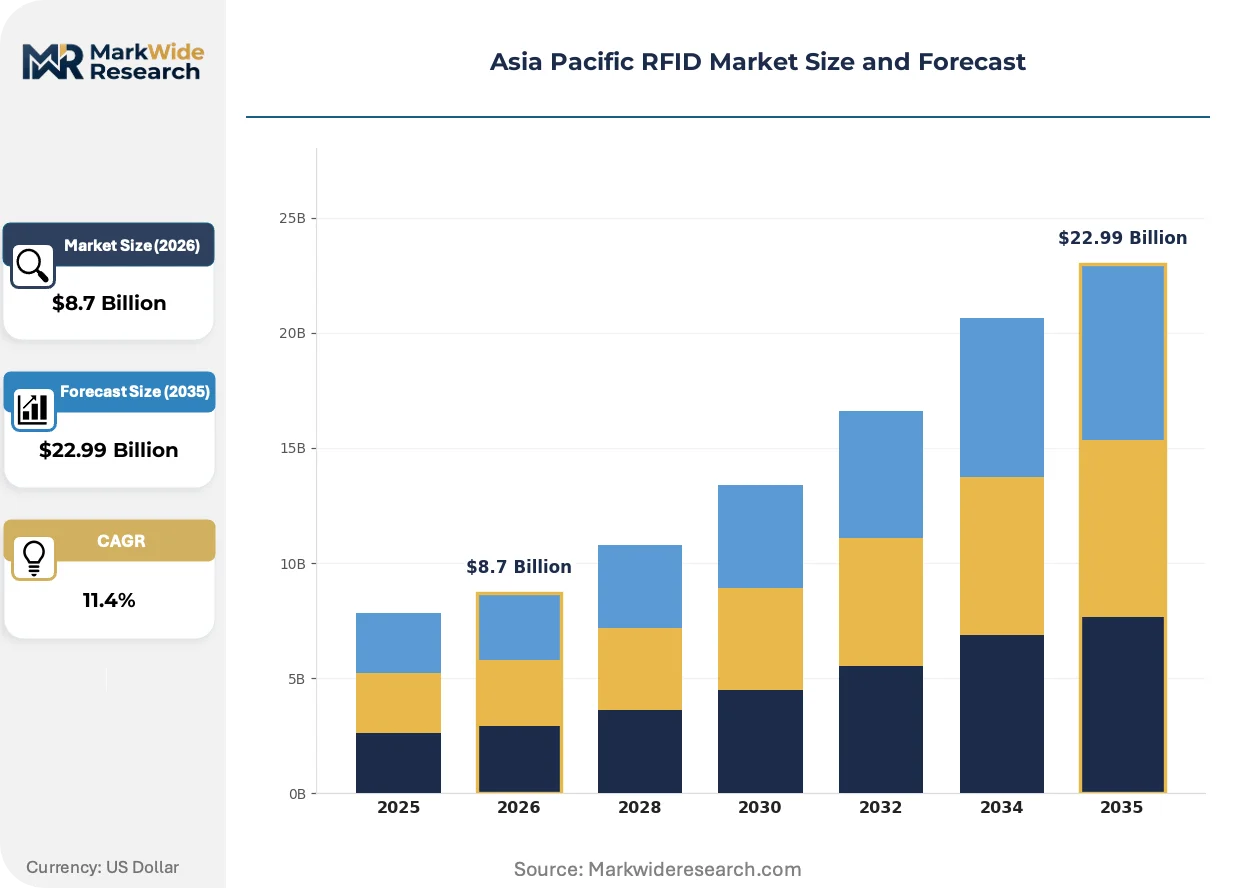
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID, Passive RFID, Semi-passive RFID, RFID Tags End User: Retail, Healthcare, Manufacturing, Transportation Technology: LF, HF, UHF, Microwave Application: Inventory Management, Access Control, Asset Tracking, Supply Chain |
| Companies Covered | NXP Semiconductors, Fujitsu Limited, Honeywell International Inc, Sato Holdings Corporation, HID Global Corporation, Impinj Inc, Avery Dennison Corporation, Invengo Technology Pte Ltd, Zebra Technologies Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific RFID Market Emerging Trajectories
UHF RFID is converging with complementary sensing and computing layers, transforming passive tags into data-collection nodes while regulatory pressure and procurement model evolution reshape deployment economics across the region.
Chipless RFID encoding is converging with printable electronics to enable sub-cent tag production for high-volume disposable applications. Indian pharmaceutical packagers are piloting these tags for serialized blister packs. The structural consequence is converging with traditional silicon-based UHF tags in cost-sensitive use cases, compressing addressable margins for conventional chip suppliers.
China's MIIT tightened radio frequency spectrum allocation rules for UHF devices in 2024, pushing manufacturers toward compliant chip designs with narrower bandwidth tolerances. Domestic logistics platforms under Alibaba and JD.com are absorbing first production runs, leaving export markets supply-constrained. Foreign deployers are responding by accelerating alternative sourcing from Taiwan and South Korean foundries.
Hospital procurement departments are unbundling RFID hardware from systems integration contracts, separating tag supply from middleware and analytics layers. Australian and South Korean health networks are driving this disintermediation, with direct tag purchasing compressing systems integrator margins. The shift is most visible in Melbourne and Seoul metropolitan hospital clusters, where procurement teams now negotiate tag volumes independently of platform vendors.
Asia Pacific RFID Market Segmentation
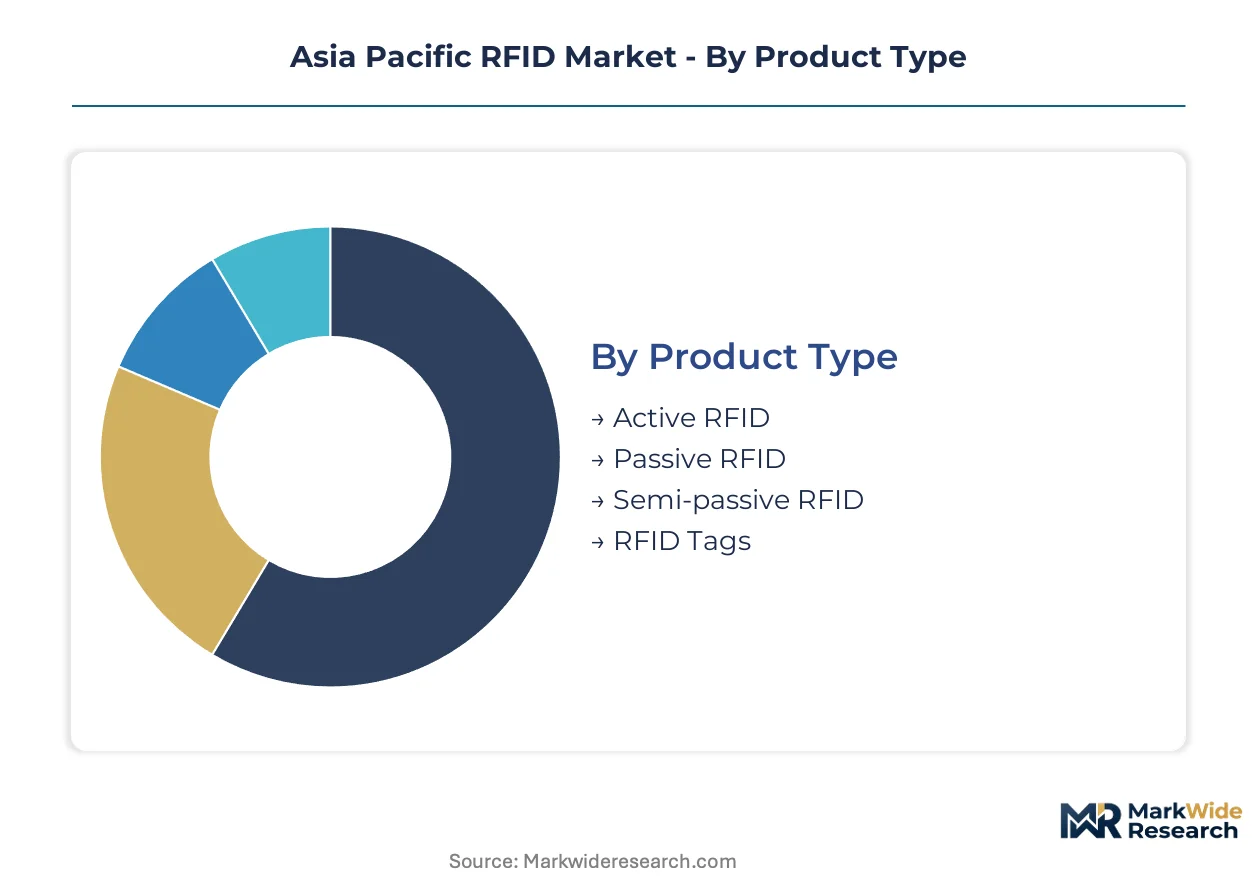
RFID deployment patterns across Asia Pacific diverge sharply by power source, frequency band, and end-use workflow. Procurement decisions hinge on read range requirements, environmental durability, and integration complexity with legacy enterprise systems.
Product Type:
Power architecture determines unit economics and deployment scale across the region's logistics networks.
- Passive RFID:Tags harvest energy from reader electromagnetic fields, eliminating onboard batteries and enabling sub-cent unit costs at million-tag volumes. India's pharmaceutical serialization mandate under CDSCO regulations is pulling passive UHF into blister-pack and vial-level tracking across Mumbai and Hyderabad manufacturing clusters.
- Active RFID:Battery-powered transponders broadcast signals autonomously, extending read ranges beyond 100 meters for real-time location systems. Australian hospital networks in Melbourne and Sydney are deploying active tags for high-value equipment fleet digitization, where battery replacement cycles align with preventive maintenance schedules.
- Semi-passive RFID:Battery-assisted backscatter combines extended range with lower power consumption than fully active designs. Cold-chain pharmaceutical distributors in South Korea are piloting these tags for temperature-sensitive biologics monitoring.
- RFID Tags:The physical transponder layer encompasses inlays, labels, and hardened encasements for industrial environments. Fujitsu's railway-focused designs for Japan's JR network exemplify high-durability specifications.
Passive RFID leads on scale; active RFID leads on momentum in healthcare digitization.
End User:
Sector-specific compliance mandates and automation intensity shape procurement volumes.
- Retail:Real-time inventory accuracy drives deployment across Southeast Asian apparel chains, with Singapore and Malaysia leading RFID integration in fitting rooms and point-of-sale systems. Warehouse automation intensification is compressing deployment timelines for regional fast-fashion distributors.
- Healthcare:Hospital equipment digitization and pharmaceutical cold-chain integrity create dual demand streams. Melbourne and Seoul metropolitan hospital clusters are unbundling tag procurement from systems integration contracts, reshaping vendor relationships.
- Manufacturing:Work-in-process tracking and finished goods serialization dominate automotive and electronics assembly lines. Indonesia's Jakarta-Bandung garment export corridors are opening to item-level RFID for compliance with destination market traceability requirements.
- Transportation:Railway asset tracking and port container management anchor demand. Japan's METI-coordinated JIS standardization embeds RFID throughout the JR network infrastructure.
Retail commands current volume concentration; healthcare is climbing fastest on regulatory tailwinds.
Technology:
Frequency band selection trades off penetration capability, data rate, and regulatory harmonization across national borders.
- UHF:Operating between 860-960 MHz, ultra-high frequency delivers longest read ranges and fastest data rates for logistics automation. China's MIIT spectrum reallocation is compressing deployment timelines and forcing chip redesigns with narrower bandwidth tolerances.
- HF:High-frequency 13.56 MHz operation enables near-field communication and payment applications. Transit card systems across Tokyo, Seoul, and Singapore transit authorities rely on HF protocols for secure proximity transactions.
- LF:Low-frequency 125-134 kHz signals penetrate metal and liquid environments where higher frequencies fail. Animal identification and industrial automation in heavy manufacturing deploy LF for harsh-environment reliability.
- Microwave:2.45 GHz and 5.8 GHz bands support high-data-rate applications including electronic toll collection. Expressway operators in Japan and South Korea utilize microwave RFID for vehicle identification at speed.
UHF dominates logistics scale; microwave is gaining fastest in intelligent transportation systems.
Application:
Workflow integration depth determines solution complexity and margin structure.
- Inventory Management:Real-time stock visibility and automated replenishment trigger deployment across retail distribution centers. Southeast Asian fast-fashion chains are eliminating cycle-count labor through shelf-level RFID infrastructure.
- Asset Tracking:Location history and utilization analytics for mobile equipment fleets. Australian and South Korean hospital networks are digitizing infusion pumps, ventilators, and imaging equipment to reduce shrinkage and optimize capital deployment.
- Supply Chain:End-to-end traceability from manufacturing through last-mile delivery. India's pharmaceutical serialization mandates under CDSCO now require container-to-unit granularity for export shipments.
- Access Control:Personnel identification and secure area entry management. Corporate campuses and data centers across Singapore and Malaysia deploy credential-based RFID for physical security layering.
Inventory management anchors current revenue concentration; asset tracking in healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT spectrum reallocation is compressing deployment timelines faster than India's pharmaceutical serialization is pulling in passive tags, creating divergent regulatory pressures across the region's two largest demand centers.
China
Domestic logistics platforms under Alibaba and JD.com are absorbing first production runs of compliant UHF chips. MIIT's tighter bandwidth tolerances are forcing chip redesigns ahead of domestic rollouts. Yangtze River Delta foundries are restructuring output to serve domestic platforms before export commitments.
India
CDSCO pharmaceutical serialization mandates require container-to-unit granularity for export shipments. TRAI frequency allocation for logistics networks is shaping deployment patterns. Mumbai and Hyderabad manufacturing clusters are pulling passive UHF into blister-pack and vial-level tracking.
Japan
METI-coordinated JIS standardization is embedding RFID throughout JR network infrastructure. Railway asset tracking creates captive demand for high-durability transponders. Kanto region rail operators are digitizing maintenance workflows through standardized tag deployment.
South Korea
Hospital networks in Seoul metropolitan clusters are unbundling tag procurement from systems integration contracts. MFDS cold-chain requirements are driving temperature-logging tag adoption. Busan-Ulsan pharmaceutical distributors are piloting battery-assisted designs for biologics monitoring.
Australia
Melbourne and Sydney hospital networks are digitizing infusion pumps, ventilators, and imaging equipment through active RFID deployment. TGA interoperability frameworks are shaping procurement specifications. Healthcare procurement teams now negotiate tag volumes independently of platform vendors.
Asia Pacific RFID Market Vendor Landscape
Chinese semiconductor foundries anchor one tier; Dutch-Japanese design-to-manufacture pipelines hold specialized positions in high-security and railway applications. The vendor base spans integrated chip designers, systems integrators, and regional deployment specialists. Three archetypes dominate: spectrum-compliant chip architects, railway-hardened transponder engineers, and hospital procurement disintermediators. Capacity expansion and strategic partnerships are the dominant competitive moves as foundries race to serve domestic logistics platforms.
Within the design-to-manufacture tier, NXP Semiconductors and Fujitsu Limited exemplify contrasting geographic anchoring strategies. NXP occupies a position linking Eindhoven design capabilities to Shanghai production access. Fujitsu represents railway-specialized durability engineering through its JR network relationships. Invengo Technology Pte Ltd sits within the Southeast Asian deployment specialist archetype, focusing on Singapore and Malaysia integration workflows.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Fujitsu Limited |
| Honeywell International Inc |
| Sato Holdings Corporation |
| HID Global Corporation |
| Impinj Inc |
| Avery Dennison Corporation |
| Invengo Technology Pte Ltd |
| Zebra Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital procurement teams unbundling tag supply from systems integration contracts are forcing chip suppliers to compete directly on unit economics while foundries restructure output priorities around domestic logistics platform demand.
Pricing Analysis
Distributor margin compression dominates channel economics as Australian and South Korean hospital networks negotiate tag volumes independently of platform vendors. Pricing stratifies across MIIT-certified premium tiers, METI-standardized railway specifications, and economy-grade passive tags for pharmaceutical serialization. Cost compression in passive UHF tags is intensifying because Yangtze River Delta foundries prioritize domestic logistics commitments. Pharmaceutical packagers in India exhibit highest price sensitivity; railway operators in Japan accept durability premiums.
Supply Chain Analysis
RF engineering talent scarcity in Shanghai and Tokyo concentrates antenna design expertise while Southeast Asian deployers import foreign engineering services. Semiconductor fabrication draws from Taiwan, South Korea, and Yangtze River Delta foundries. Silicon wafer supply rests on East Asian capacity constraints inflating input costs. Single-source vulnerability runs through compliant chip architectures for MIIT spectrum rules. Distribution runs through systems integrators unbundling hardware from analytics layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-RFID convergence for cold-chain biologics and premium-tier certification for railway-hardened transponders as input cost volatility separates efficient from legacy suppliers.
For Market Incumbents: Cement spectrum-compliant chip supply through captive foundry relationships or binding offtake agreements with Taiwan and South Korean producers. Chipless RFID encoding from printable electronics threatens conventional silicon tag margins; deepen backward integration into antenna design capabilities to defend service revenue from procurement disintermediation. For New Entrants and Emerging Players: Battery-assisted temperature-logging tag architectures offer entry into South Korean pharmaceutical cold-chain monitoring where MFDS requirements outpace incumbent capacity. Indonesia's Jakarta-Bandung garment export corridors present the most penetrable geography for item-level RFID compliance solutions. Lead with direct hospital procurement engagement bypassing systems integrator channel control. For Investors and Strategic Acquirers: Asymmetric upside sits with deployment specialists possessing RF engineering talent pipelines and multi-jurisdiction certification capabilities. Five-to-ten year viability favors vendors bridging MIIT-METI-TRAI interoperability gaps rather than single-market players. Monitor spectrum harmonization talks between Beijing, Tokyo, and New Delhi as inflection indicator for cross-border tag compatibility plays.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Compliance Certification Investment | Unlocks Alibaba and JD.com domestic logistics platform supply contracts ahead of export markets. |
| Sensor-RFID Hybrid Product Launch | Captures MFDS-driven temperature-logging demand for biologics monitoring in Busan-Ulsan corridors. |
| Antenna Design Talent Acquisition | Addresses RF engineering scarcity constraining Southeast Asian deployment timelines and service margins. |
| Hospital Procurement Direct Channel | Bypasses systems integrator disintermediation reshaping Melbourne and Seoul metropolitan vendor relationships. |
| Taiwan-South Korea Foundry Partnership | Secures alternative UHF chip sourcing as Yangtze River Delta capacity prioritizes domestic commitments. |
Methodological Framework
Bottom-up hospital and retail inventory modeling reconciled against top-down semiconductor foundry output tracking forms the analytical core of this study. Primary interviews with RFID systems integrators, hospital procurement managers, pharmaceutical supply chain directors, and railway maintenance engineers combined with secondary validation from CDSCO serialization guidelines, MIIT spectrum allocation notices, METI JIS standardization documents, and customs trade data for chip and inlay imports.
Historical trendline analysis of passive versus active tag deployment ratios informed projection frameworks across power source, frequency band, and end-use workflow dimensions. CAGRs derived from segment-level adoption curves weighted by regulatory mandate enforcement timelines. Forecast inputs incorporated foundry capacity utilization rates and multi-jurisdiction interoperability certification backlogs.
The model holds under stable spectrum allocation regimes and continued pharmaceutical serialization enforcement; deviation in cross-border frequency harmonization or foundry capacity reallocation would shift regional supply-demand balances. Material deviation in MIIT-METI-TRAI coordination or East Asian semiconductor input cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Indoor Location Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Cloud Camera Market
Sensors
Vibration Monitoring Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Connected Smart Thermostats Market
Sensors
Smart Beacon Market
Sensors
Ultrasonic Technologies Market
Sensors
Asset Tracking Market
Sensors
Conveyor Monitoring Market
Sensors
Lidar in Mapping Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Body Area Network Market
Sensors
Global Tunnel Monitoring System Market