
 Traffic Sensor Market | 2026-2036
Traffic Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Sensor Market Analysis
Aftermarket sensor calibration and firmware maintenance revenue is fragmenting across regional service networks as municipalities extend equipment lifecycles rather than replace legacy inductive loops. Kapsch TrafficCom AG leverages its Vienna headquarters to sustain dense European service coverage for radar and infrared installations. Siemens AG competes through integrated traffic management platforms that bundle sensor hardware with control software. TE Connectivity anchors North American supply chains through its automotive sensor manufacturing scale repurposed for infrastructure applications.
Traffic sensors are electromechanical or photonic detection devices that measure vehicle presence, speed, classification, or flow density through Doppler radar echoes, piezoelectric strain, thermal infrared differential, or electromagnetic field disturbance, typically operating at sampling frequencies between ten hertz and one kilohertz to enable real-time signal actuation and corridor optimization. Their primary commercial purpose is converting physical traffic phenomena into digital inputs for intelligent transportation systems and urban mobility platforms. Radar sensors now lead unit shipments among product types due to their all-weather reliability and declining semiconductor cost curves, while video analytics technology captures the fastest expansion as edge AI processing enables automated incident detection without dedicated roadside computers. Wireless technology segments command premium pricing where fiber trenching proves cost-prohibitive for retrofit corridors.
The US DOT's MUTCD compliance requirements and the EU's ITS Directive framework mandate interoperable data formats and minimum detection accuracy thresholds that shape procurement specifications for government agency end users. Germany's KBA and Austria's BMK enforce type-approval testing for radar-based speed enforcement sensors, creating certification barriers for unvalidated hardware entrants. China's MIIT issues GB standards for vehicular radar emission limits that constrain transmitter power design. Stakeholders must monitor evolving cybersecurity mandates for connected infrastructure nodes as transportation departments classify sensor networks as critical operational technology requiring encrypted backhaul protocols.
Market Dynamics
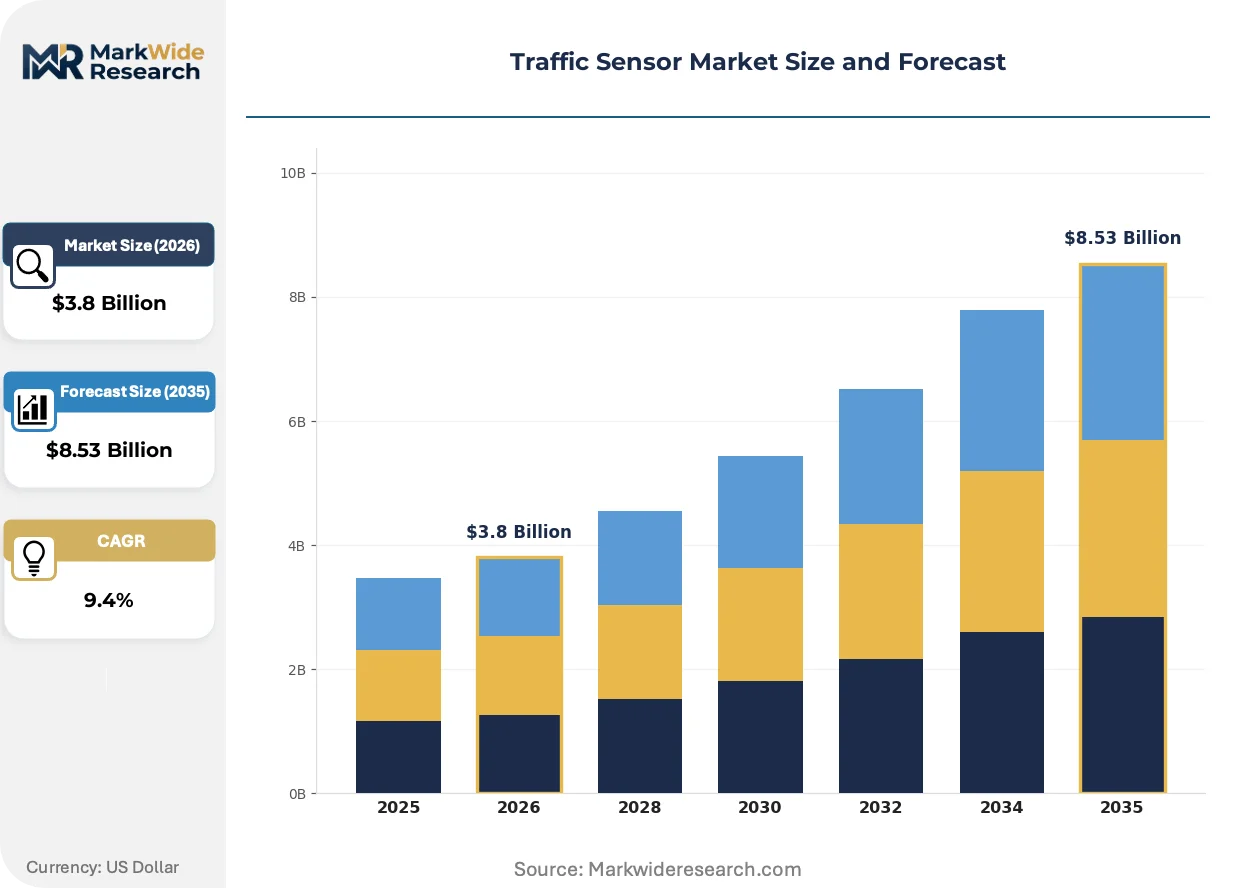
Municipal procurement departments are compressing replacement cycles for inductive loop detectors while simultaneously piloting radar-video fusion systems, creating a bifurcated equipment landscape where legacy maintenance revenue competes with next-generation deployment budgets.
Growth Catalysts
- EU Green Deal mobility targets:The framework mandates intersection efficiency improvements that require real-time vehicle detection, accelerating specifications for Doppler radar and thermal infrared sensors in German and Dutch municipal tenders.
- Edge AI processing:On-chip inference engines are enabling video analytics sensors to operate without roadside computing enclosures, reducing fiber backhaul requirements and expanding retrofit corridor viability in cost-constrained districts.
- Barcelona and Singapore smart city deployments:These flagship programs demonstrate integrated traffic management platforms that bundle detection, signal control, and corridor optimization, establishing reference architectures for mid-sized cities in Spain and Southeast Asia.
Market Restraints
- Inductive loop lifecycle extension:Saw-cutting and pavement repair costs for loop replacement average three to four times sensor hardware expense, locking municipalities into firmware updates and calibration contracts rather than technology migration.
- Semiconductor supply concentration:Radar front-end modules depend on gallium nitride foundry capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction and foundry allocation decisions.
- GB standard transmitter power limits:China's MIIT vehicular radar emission caps constrain detection range for speed enforcement applications, forcing hardware redesigns that sacrifice performance for compliance.
Strategic Opportunities
- Wireless retrofit corridors:Cellular and dedicated short-range communication backhaul commands premium pricing where fiber trenching encounters utility congestion or historic district preservation restrictions.
- US IIJA infrastructure framework:The program's intersection safety improvement carve-outs create dedicated funding streams for radar and video detection systems in states with elevated pedestrian fatality rates.
- Cybersecurity certification services:Transportation departments are classifying sensor networks as critical operational technology, generating demand for encrypted protocol implementation and penetration testing capabilities.
Industry Challenges
- KBA and BMK type-approval timelines:German and Austrian speed enforcement sensor certification requires six to eighteen months of field validation, compressing vendor margins and delaying revenue recognition.
- Radar-infrared sensor fusion integration:Municipal signal shops lack technicians trained in calibrating multi-modal detection zones, forcing manufacturers to embed self-diagnostic firmware or dispatch field engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Sensor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, Ultrasonic Sensors, Inductive Loop Sensors, Infrared Sensors Technology: Wireless, Wired, Infrared, Video Analytics Application: Traffic Management, Smart City Solutions, Vehicle Counting, Parking Assistance End User: Government Agencies, Transportation Departments, Urban Planners, Research Institutions |
| Companies Covered | Kapsch TrafficCom AG, SWARCO AG, Teledyne FLIR LLC, TE Connectivity, Siemens AG, International Road Dynamics Inc., Q-Free ASA, EFKON AG, Kistler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Sensor Market Emerging Trajectories
Detection hardware is converging with edge computing and encrypted networking, transforming standalone sensors into distributed infrastructure nodes that demand new procurement, maintenance, and cybersecurity competencies from transportation departments.
Millimeter-wave radar arrays with integrated signal processing are digitizing vehicle classification and trajectory prediction at the roadside, eliminating dependency on centralized traffic management computers. State DOTs in Texas and Florida are deploying these units at high-speed rural intersections where video analytics fail in low-visibility conditions. The technology is digitizing how agencies allocate detection budgets, compressing capital expenditure into single-unit procurements rather than multi-vendor system integration.
The EU ITS Directive framework is mandating interoperable data formats and minimum detection accuracy thresholds that reshape procurement specifications for government agency end users. Municipalities must now demonstrate cross-jurisdictional data compatibility in tender submissions, favoring vendors with established European installed bases. Radar-based speed enforcement sensors face the most stringent compliance burden, as KBA enforcement of harmonized testing protocols creates certification barriers for unvalidated hardware entrants.
Service unbundling is separating sensor hardware procurement from multi-year maintenance agreements that municipalities previously awarded as single contracts. Transportation departments in California and New York are negotiating calibration and firmware update services independently, pitting original equipment manufacturers against regional service networks. This shift is most visible in Germany, where Kapsch TrafficCom and SWARCO compete to retain legacy inductive loop accounts through aftermarket service pricing rather than replacement hardware sales.
Traffic Sensor Market Segmentation
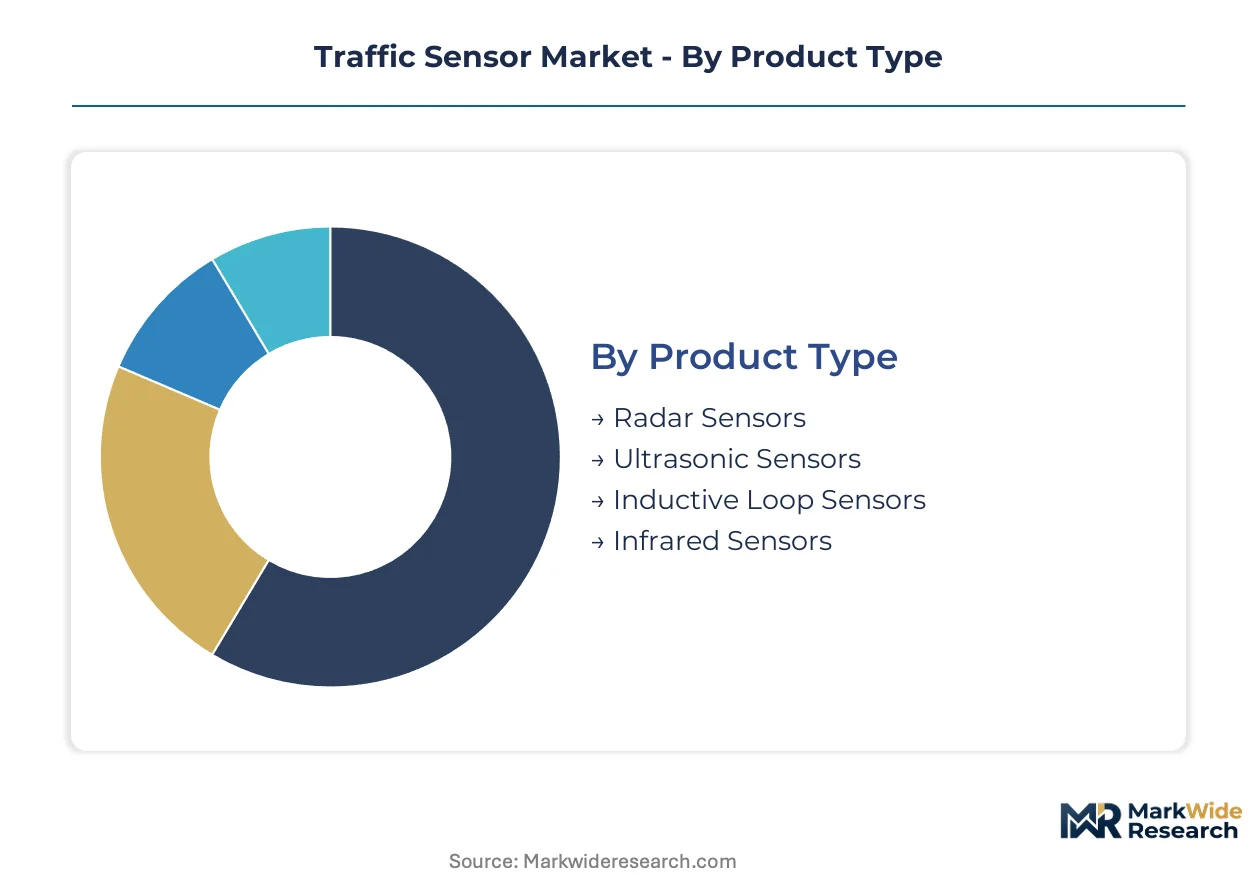
Traffic sensor procurement cycles vary dramatically across product categories, with inductive loops persisting for fifteen to twenty years while radar and video analytics platforms face three-to-five-year replacement windows driven by firmware obsolescence and AI model updates. Understanding these differential lifecycles enables vendors to calibrate service revenue models and inventory strategies against municipal capital planning horizons.
Product Type:
Replacement velocity diverges sharply across detection technologies, with legacy electromagnetic systems turning over slowly while solid-state radar arrays refresh rapidly due to semiconductor roadmap pressures.
- Radar Sensors:Millimeter-wave Doppler arrays with integrated signal processing classify vehicles through micro-Doppler signatures and trajectory prediction. Texas DOT and Florida DOT deploy these at rural high-speed intersections where thermal and optical methods fail, prioritizing all-weather reliability over upfront hardware cost.
- Infrared Sensors:Thermal differential detectors capture vehicle presence through heat signature contrast against ambient pavement temperature. Singapore's Land Transport Authority specifications favor these for tunnel and underpass deployments where radar multipath interference degrades accuracy.
- Inductive Loop Sensors:Electromagnetic field disturbance detectors embedded in saw-cut pavement channels.
- Ultrasonic Sensors:Piezoelectric transducers measuring time-of-flight echoes for short-range presence detection.
Inductive loops anchor the volume base while radar sensors gain share at the steepest rate.
Technology:
Backhaul economics separate premium wireless deployments from cost-optimized wired infrastructure, with trenching constraints and right-of-way restrictions determining viable architecture for each corridor.
- Video Analytics:Edge AI inference engines process convolutional neural networks on-chip to detect incidents, classify vehicle types, and queue lengths without roadside computing enclosures. Barcelona's smart city deployment eliminated fiber dependency through these units, enabling retrofit installation in historic districts where excavation permits face preservation restrictions.
- Wireless:Cellular and DSRC protocols transmit detection events where fiber installation encounters utility congestion or per-mile trenching costs exceed hardware budgets. German municipal tenders specify wireless backhaul for temporary construction zone monitoring and event traffic management.
- Wired:Fiber and copper backhaul for permanent installations with predictable data loads.
- Infrared:Dedicated thermal detection networks operating independently of visible-spectrum cameras.
Wired infrastructure commands the installed base while video analytics climbs the fastest among new procurement specifications.
Application:
Functional requirements range from binary presence detection to complex multimodal corridor optimization, with software integration depth determining total contract value beyond hardware margins.
- Traffic Management:Real-time signal actuation and adaptive corridor timing based on vehicle flow density, speed, and classification. The EU Green Deal's intersection efficiency mandates accelerate specifications for these systems in Dutch and German municipal tenders.
- Smart City Solutions:Integrated platforms bundling detection, control, and analytics for multimodal mobility optimization. Singapore's flagship deployment establishes reference architectures for Southeast Asian mid-sized cities replicating its sensor-to-cloud data pipeline.
- Vehicle Counting:Axle-based and volumetric tallies for planning studies and federal reporting compliance.
- Parking Assistance:Space occupancy detection for guidance systems and enforcement automation.
Traffic management absorbs the largest procurement volumes while smart city solutions attract the steepest expansion trajectory.
End User:
Buyer sophistication and procurement authority fragment across administrative levels, with federal compliance requirements filtering down through state specifications to municipal implementation.
- Government Agencies:Federal and state transportation departments specifying interoperable data formats and minimum accuracy thresholds under US DOT MUTCD and EU ITS Directive frameworks. These entities mandate encrypted backhaul protocols as sensor networks receive critical infrastructure classification.
- Transportation Departments:Municipal and county engineers operating signal systems and maintaining detection assets. California and New York departments increasingly unbundle hardware procurement from multi-year calibration and firmware maintenance contracts.
- Urban Planners:Technical staff in metropolitan planning organizations integrating sensor data into long-range mobility studies.
- Research Institutions:University and national laboratory programs validating emerging detection methodologies.
Transportation departments dominate current installed capacity while government agencies reshape specifications most aggressively through compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement environments, with German municipalities accepting hardware premiums for certified compliance while Indian state agencies prioritize lowest-bidder specifications that extend inductive loop lifecycles.
United States
The IIJA infrastructure framework directs dedicated funding streams toward intersection safety improvements in states with elevated pedestrian fatality rates. The US DOT's MUTCD compliance requirements mandate interoperable data formats and minimum detection accuracy thresholds for federal aid eligibility. Texas DOT and Florida DOT anchor demand for millimeter-wave radar arrays at rural high-speed intersections where thermal and optical methods fail.
Germany
KBA type-approval testing for radar-based speed enforcement sensors creates six-to-eighteen-month certification timelines that compress vendor margins. The EU Green Deal's mobility targets mandate intersection efficiency improvements requiring real-time vehicle detection. Kapsch TrafficCom AG and SWARCO AG anchor substantial installed bases of inductive loop and infrared sensor networks across municipal deployments.
Singapore
The Land Transport Authority's smart city specifications favor thermal infrared sensors for tunnel and underpass deployments where radar multipath interference degrades accuracy. Edge AI processing requirements in flagship programs establish reference architectures for Southeast Asian mid-sized cities. The sensor-to-cloud data pipeline demonstrated here replicates across procurement specifications in Malaysia and Indonesia.
China
MIIT's GB standards for vehicular radar emission limits constrain transmitter power design, forcing hardware redesigns that sacrifice detection range for compliance. Dual carbon goals accelerate specifications for corridor optimization systems in provincial capital cities. Yangtze River Delta municipalities pilot radar-video fusion systems under central government smart city directives.
Spain
Barcelona's integrated traffic management platform demonstrates bundled detection, signal control, and corridor optimization for mid-sized city replication. EU ITS Directive interoperability mandates reshape municipal tender submissions toward cross-jurisdictional data compatibility. Historic district preservation restrictions in Catalan cities drive premium pricing for wireless backhaul where excavation permits face regulatory barriers.
Traffic Sensor Market Vendor Landscape
Capability concentration sits with specialized traffic technology developers; scale advantage sits with diversified industrial conglomerates. The vendor base separates into certification-heavy European specialists, North American diversified electronics suppliers, and integrated platform providers. Three archetypes dominate: type-approved radar specialists, multi-modal detection integrators, and repurposed automotive sensor fabricators. Competitive moves center on aftermarket service unbundling and cybersecurity certification layering.
Among Vienna-headquartered specialists, Kapsch TrafficCom AG exemplifies the certification-intensive tier sustaining dense European service coverage. SWARCO AG occupies a comparable position anchoring legacy inductive loop accounts through aftermarket pricing rather than replacement hardware. Siemens AG represents the integrated platform archetype competing through bundled sensor hardware with control software. TE Connectivity sits within the scale-driven segment leveraging automotive sensor manufacturing capacity for infrastructure applications.
| Leading Market Players |
|---|
| Kapsch TrafficCom AG |
| SWARCO AG |
| Teledyne FLIR LLC |
| TE Connectivity |
| Siemens AG |
| International Road Dynamics Inc. |
| Q-Free ASA |
| EFKON AG |
| Kistler Group |
| Others |
Supply Flow & Price Mechanics
Gallium nitride foundry concentration in Taiwan and South Korea determines both tiered hardware margins and procurement resilience strategies for radar front-end modules. Municipal buyers face extended lead time exposure that compresses vendor pricing power while amplifying aftermarket service premiums.
Pricing Analysis
Aftermarket calibration and firmware maintenance contracts now drive lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across certified compliance, standard interoperability, and economy retrofit levels segments municipal budgets from German type-approval premiums to Indian lowest-bidder specifications. Cost compression in wireless backhaul tiers is intensifying because cellular module commoditization erodes hardware differentiation. State transportation departments exhibit highest price sensitivity where IIJA funding constraints apply, while German KBA-certified deployments accept substantial premiums for compliance assurance.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor sources dominates strategic sourcing decisions for edge AI processing chipsets. Radar sensor manufacturing draws from Taiwan, South Korea, and Germany for millimeter-wave front-end components, with gallium nitride substrates and silicon CMOS baseband processors anchoring bill-of-materials volatility. Single-source vulnerability in Taiwan foundry capacity exposes lead times to geopolitical friction and allocation priority shifts. Distribution runs through municipal procurement departments increasingly unbundling hardware from multi-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through service unbundling trends that fragment vendor lock-in and pit original equipment manufacturers against regional calibration networks.
For Market Incumbents: Insulate legacy inductive loop accounts through embedded self-diagnostic firmware that reduces field engineer dispatch frequency. Deepen European service density to defend against unbundling pressures from California and New York transportation departments. Certification investment in KBA and BMK type-approval pipelines creates switching costs that delay emerging radar-video fusion entrants. For New Entrants and Emerging Players: Mid-sized Southeast Asian cities replicating Singapore's sensor-to-cloud architecture represent the most penetrable entry point for integrated platform providers. Wireless retrofit corridors in historic European districts where excavation permits face regulatory barriers offer premium pricing escape from commoditized wired competition. Direct municipal engagement bypassing traditional systems integrators accelerates pilot-to-deployment conversion. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors aftermarket service specialists over hardware-replacement-dependent vendors. Five-to-ten-year viability hinges on cybersecurity certification capabilities as transportation departments classify sensor networks as critical operational technology. Monitor EU ITS Directive enforcement intensity as the signal for interoperability mandate acceleration that reshapes competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Program | Encrypted protocol implementation addresses US DOT critical infrastructure classification requirements for sensor networks. |
| Wireless Backhaul Partnership | Cellular and DSRC alliances unlock historic district deployments where Barcelona demonstrated retrofit viability. |
| Radar-Video Fusion Development | Multi-modal detection integration responds to EU Green Deal intersection efficiency mandates in German tenders. |
| Aftermarket Service Unbundling | Independent calibration contracts capture revenue from municipalities extending inductive loop lifecycles. |
| Edge AI Platform Integration | On-chip inference eliminates roadside computing enclosures for cost-constrained district retrofits. |
Methodological Framework
The analysis maps radar sensor, infrared detection, inductive loop, and video analytics sub-sectors, each validated through municipal signal engineers, transportation department procurement officers, smart city program directors, and aftermarket service technicians. Primary interviews with Kapsch TrafficCom, SWARCO, and Siemens field operations teams combined with secondary validation from US DOT MUTCD filings, EU ITS Directive compliance databases, KBA type-approval registries, and municipal tender archives. Bottom-up unit shipment estimates triangulate against top-down infrastructure spending allocations across the analysis window.
Assumptions held fixed include IIJA funding continuity, EU Green Deal mobility target enforcement, and gallium nitride foundry capacity allocation patterns, while semiconductor cost curves and edge AI processing efficiency were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, backhaul technology, application functional depth, and end-user procurement authority. CAGRs derive from replacement cycle differential analysis between fifteen-to-twenty-year inductive loop persistence and three-to-five-year radar refresh rates. Forecast inputs incorporate KBA certification timeline distributions and Barcelona-Singapore reference architecture replication rates.
Practitioners should monitor foundry allocation priority shifts, cybersecurity mandate acceleration, and service unbundling litigation for early signals of structural revision. Forecasts reflect documented assumptions about municipal capital planning horizons and regulatory enforcement intensity. Macroeconomic infrastructure spending contraction, geopolitical semiconductor access restriction, or edge AI processing breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
IO-Link Technology Market
Sensors
Beacon Market
Sensors
Handheld RFID Readers Market
Sensors
Global RFID Market
Sensors
Indoor Location Market
Sensors
Machine Health Monitoring Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Smart Barcode Readers Market
Sensors
India Asset Tracking Market
Sensors
Smart Beacon Market
Sensors
Surface Haptic Technology Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Fixed RFID Readers Market
Sensors
Personal Navigation Devices Market