
 Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market | 2026-2036
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market Insights
The capability gap between capital-intensive semiconductor fabricators and lightweight hardware assemblers is collapsing as node miniaturization demands in-house MEMS foundry investment. Texas Instruments leverages its captive analog fabrication network to dominate piezoelectric signal-conditioning chip supply. STMicroelectronics anchors European demand through its vertically integrated MEMS production lines in Italy and France. Honeywell competes via aerospace-certified packaging expertise that satisfies FAA airworthiness standards for bonded sensor installations.
Wireless sensor nodes for monitoring exterior panel fatigue comprise compact, energy-harvesting measurement systems that attach to structural surfaces and transmit strain-cycle data via low-power radio protocols, typically operating at sampling rates between 1 Hz and 1 kHz depending on vibration mode capture requirements. Their primary purpose is to replace scheduled manual inspection with continuous structural health monitoring, reducing unplanned downtime in transportation and energy infrastructure. Strain gauge nodes command the largest installed base due to mature calibration standards and direct correlation with crack-propagation models, while LoRaWAN communication technology represents the fastest-expanding connectivity layer for remote assets spanning wind farms and rail corridors. Optical sensor variants occupy premium price tiers where electromagnetic immunity and zero-power passive operation justify higher unit costs in defense applications.
FAA airworthiness directives and EBA rail safety frameworks mandate documented fatigue-life tracking for critical exterior panels, forcing OEMs to integrate certified wireless monitoring into design-stage specifications. CE marking under the EU Radio Equipment Directive and FCC Part 15 rules in the United States govern transmission power and spectrum allocation, creating regional product-variant requirements that complicate scale economics. Stakeholders must weigh spectrum harmonization progress against country-specific certification timelines when allocating R&D budgets across communication technology roadmaps.
Market Dynamics
MEMS foundry consolidation is compressing margins for fabless sensor designers while vertically integrated analog semiconductor houses capture value from signal-conditioning die production.
Growth Catalysts
- FAA airworthiness mandates:Fatigue-life tracking requirements for bonded exterior panels on commercial aircraft force OEMs to specify certified wireless monitoring systems during design-stage procurement.
- German rail safety frameworks:EBA and KBA oversight mandates strain-cycle documentation for critical railcar shell components, concentrating sensor demand among Deutsche Bahn suppliers and rolling-stock manufacturers.
- Energy harvesting integration:Piezoelectric and thermoelectric power scavenging from structural vibration eliminates battery replacement cycles, expanding deployable node density on offshore wind turbine blades.
Market Restraints
- Silicon wafer cost volatility:MEMS substrate pricing fluctuates with 300mm foundry utilization rates, squeezing gross margins for node assemblers lacking captive wafer supply.
- Spectrum fragmentation:FCC Part 15 rules in the United States and EU Radio Equipment Directive create incompatible transmission-power variants, forcing redundant certification spend and complicating scale economics.
- Optical fiber substitution:Distributed acoustic sensing on long-span bridge cables offers electromagnetic immunity without wireless power constraints, capturing premium infrastructure monitoring contracts.
Strategic Opportunities
- Defense electromagnetic immunity requirements:Zero-power passive optical sensor variants command premium positioning in naval vessel and armored vehicle hull monitoring where radio silence is mission-critical.
- LoRaWAN corridor deployment:Low-power wide-area networks spanning German rail corridors and Danish offshore wind farms enable subscription-based monitoring-as-a-service revenue models.
- CE marking harmonization:Pending EU spectrum allocation convergence under the Radio Equipment Directive reduces variant complexity for pan-European fleet operators standardizing on single hardware platforms.
Industry Challenges
- MEMS calibration expertise scarcity:Strain gauge node production requires specialized drift-compensation engineering that concentrates among Italian and French foundry clusters, limiting qualified supplier pools.
- FAA TSO-C151 certification timelines:Bonded sensor installations on transport-category aircraft face 18-24 month airworthiness qualification cycles, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market |
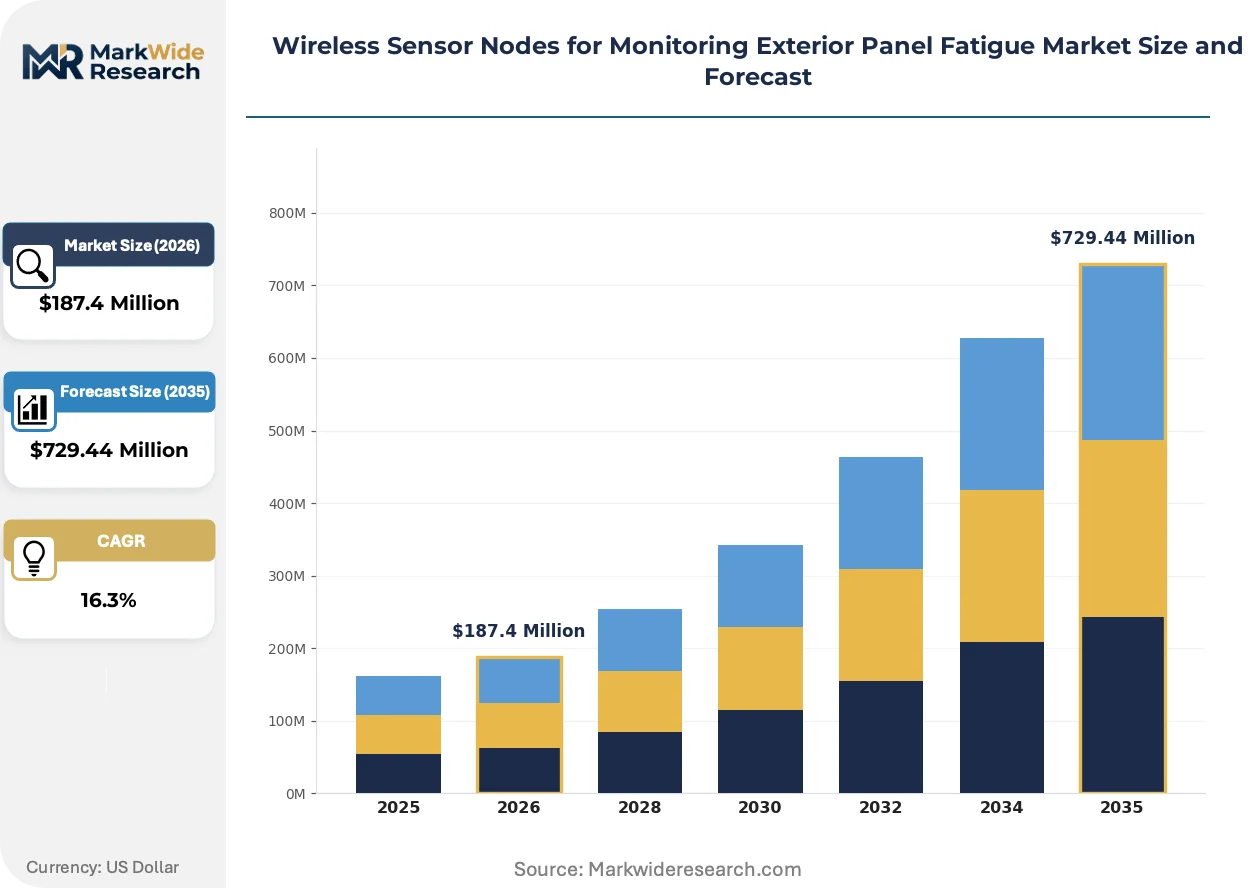
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $729.44 Million |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Accelerometer, Strain Gauge, Piezoelectric, Capacitive, Optical Communication Technology: LoRaWAN, Zigbee, Bluetooth Low Energy, NB-IoT, Sigfox Application: Aerospace OEMs, Rail Equipment Manufacturers, Marine Vessel Builders, Wind Turbine Producers End User Industry: Defense Contractors, Public Infrastructure Authorities, Commercial Fleet Operators, Energy Generation Firms |
| Companies Covered | EnOcean, ABB, Infineon Technologies, Fujitsu, Microchip Technology, Lord MicroStrain, Honeywell, Texas Instruments, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market Trends and Innovations
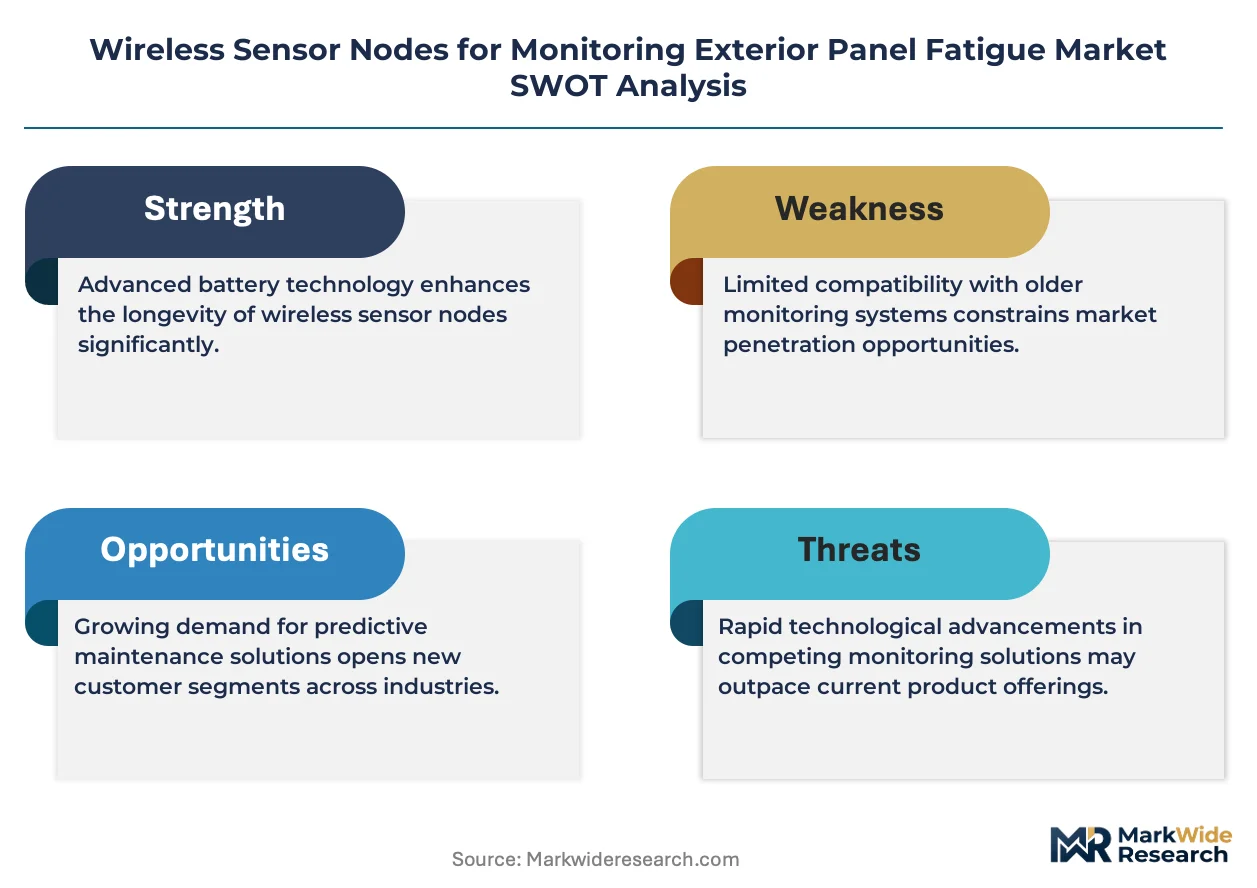
Energy-autonomous measurement architectures are displacing battery-dependent node designs across transportation and energy infrastructure, while regulatory convergence pressures reshape hardware platform strategies.
Thin-film piezoelectric energy harvesters bonded directly to vibrating aluminum aircraft skins capture sufficient mechanical strain to power sub-milliwatt radio transmission. Boeing and Airbus structural health monitoring procurement specifications now prioritize self-powered node architectures for wing and fuselage applications. This displacement of lithium primary cells eliminates scheduled maintenance intervals and enables permanent installation on sealed composite structures.
The EU Radio Equipment Directive's pending sub-GHz spectrum harmonization is forcing communication module redesigns ahead of 2027 enforcement deadlines. German rail operators and French wind farm developers are pre-qualifying dual-band LoRaWAN hardware to avoid stranded inventory. Equipment manufacturers face compressed R&D allocation timelines as national implementation schedules diverge across member states.
Commercial fleet operators now contract monitoring-as-a-service rather than purchasing sensor hardware outright. Maersk and Hapag-Lloyd container vessel managers subscribe to hull fatigue data streams from third-party analytics providers who retain node ownership. Danish and Singaporean maritime clusters exhibit the highest penetration of this model, driven by vessel classification society pressure for documented structural integrity evidence.
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market Segmentation
Wireless sensor node procurement channels diverge sharply by segment. Defense contractors route optical and piezoelectric variants through aerospace-certified distributors, while commercial fleet operators source strain gauge nodes via direct OEM contracts. Understanding these channel dynamics reveals margin concentration points and certification bottlenecks.
Sensor Type:
Distribution channels for sensor nodes map directly to calibration complexity and foundry proximity. Strain gauge and piezoelectric variants flow through specialized industrial distributors with MEMS testing capabilities, while optical sensors require defense-authorized channels with electromagnetic immunity documentation.
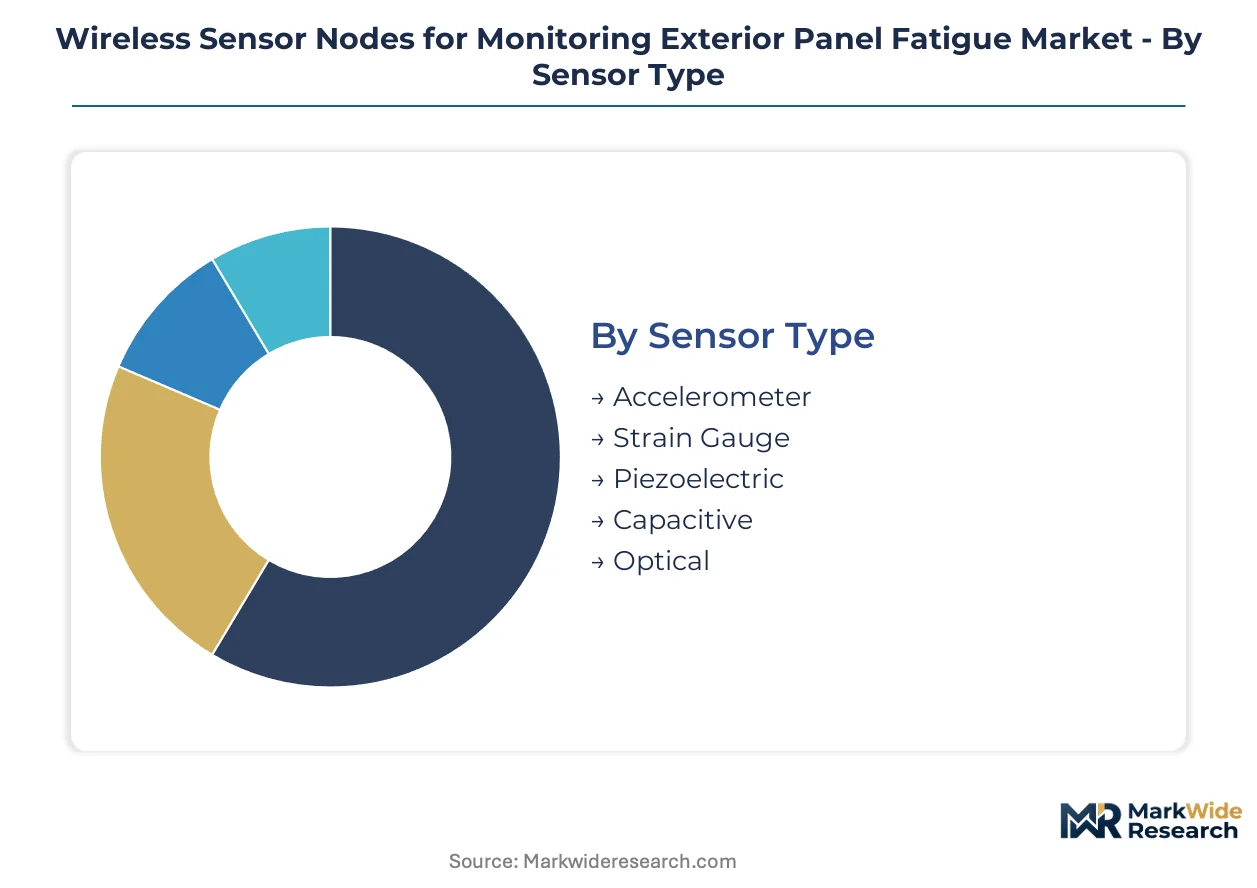
- Strain Gauge:Bonded foil or semiconductor elements measure surface deformation with microstrain resolution. Deutsche Bahn suppliers and rolling-stock manufacturers in Germany concentrate procurement here under EBA fatigue-documentation mandates. By volume, strain gauge leads. By growth pace, optical variants are climbing the fastest.
- Piezoelectric:Crystalline elements generate charge proportional to dynamic stress, enabling energy-harvesting architectures. Boeing and Airbus wing-monitoring specifications prioritize these for self-powered installations on sealed composite structures.
- Accelerometer:MEMS cantilever structures capture vibration spectra for modal analysis. Foundry supply concentrates among Italian and French clusters with drift-compensation expertise.
- Capacitive:Variable-gap electrodes suit low-frequency static strain measurement with minimal power draw. Wind turbine blade monitoring applications favor these for long-term drift stability.
- Optical:Fiber Bragg grating or interferometric designs deliver passive, zero-power operation with complete electromagnetic immunity. Naval vessel hull monitoring contracts specify these where radio silence is mission-critical.
Strain gauge dominates installed base through mature calibration standards. Optical variants gain share fastest where defense electromagnetic immunity requirements command premium positioning.
Communication Technology:
Module selection hinges on infrastructure density and spectrum allocation timelines. LoRaWAN and NB-IoT modules carry higher upfront certification costs but enable subscription revenue models, while Zigbee and Bluetooth Low Energy suit dense asset clusters with existing gateway coverage.
- LoRaWAN:Sub-GHz spread-spectrum protocol delivers kilometer-range connectivity at milliwatt power levels. German rail corridors and Danish offshore wind farms are deploying these for monitoring-as-a-service architectures.
- NB-IoT:Licensed cellular narrowband leverages existing tower infrastructure for maritime and remote infrastructure assets. Vessel classification societies in Singapore and Denmark drive adoption for hull integrity documentation.
- Zigbee:Mesh-networking protocol suits dense sensor arrays on single structures. Aerospace MRO facilities deploy these for hangar-based fleet monitoring with localized analytics.
- Bluetooth Low Energy:Short-range protocol enables smartphone-based commissioning and diagnostics. Maintenance crews favor these for rapid node deployment without specialized gateway hardware.
- Sigfox:Ultra-narrowband unlicensed service targets low-data-rate applications with minimal power budgets. Early wind farm pilots in France utilized these before LoRaWAN ecosystem maturity.
LoRaWAN module shipments exceed others in transportation and energy infrastructure. NB-IoT is expanding most quickly where cellular coverage eliminates gateway infrastructure investment.
Application:
End-use concentration determines pricing tiers and certification intensity. Aerospace and rail applications command FAA and EBA compliance premiums, while marine and wind sectors prioritize energy autonomy and corrosion resistance over formal airworthiness qualification.
- Aerospace OEMs:Wing and fuselage monitoring specifications from Boeing and Airbus mandate FAA TSO-C151 certification. Bonded sensor installations face 18-24 month airworthiness qualification cycles.
- Rail Equipment Manufacturers:Deutsche Bahn and European rolling-stock builders require EBA-documented strain-cycle tracking for critical shell components under German federal rail safety frameworks.
- Marine Vessel Builders:Maersk and Hapag-Lloyd container fleet managers subscribe to third-party hull fatigue data streams rather than owning sensor hardware outright.
- Wind Turbine Producers:Vestas and Siemens Gamesa specify blade-integrated monitoring for offshore assets where access costs dominate lifecycle economics.
Aerospace generates highest unit value per node. Marine applications are gaining share fastest through monitoring-as-a-service contract structures.
End User Industry:
Procurement authority and budget cycles vary dramatically across buyer types. Defense contractors operate classified procurement channels with electromagnetic immunity specifications, while public infrastructure authorities face transparent tender processes with multi-year appropriation timelines.
- Defense Contractors:Naval vessel and armored vehicle programs specify passive optical sensors for hull monitoring where radio emission risks mission security. Classified procurement channels limit supplier pools to cleared vendors.
- Commercial Fleet Operators:Container shipping lines and commercial aviation lessors prioritize total-cost-of-ownership metrics over upfront hardware expense. Subscription-based data access aligns with operational expenditure budgeting.
- Energy Generation Firms:Offshore wind developers and utility-scale solar operators deploy energy-harvesting nodes to eliminate battery replacement logistics at remote turbine and panel locations.
- Public Infrastructure Authorities:Bridge and highway agencies face appropriation-cycle constraints that favor proven strain gauge technologies with established calibration traceability over emerging optical alternatives.
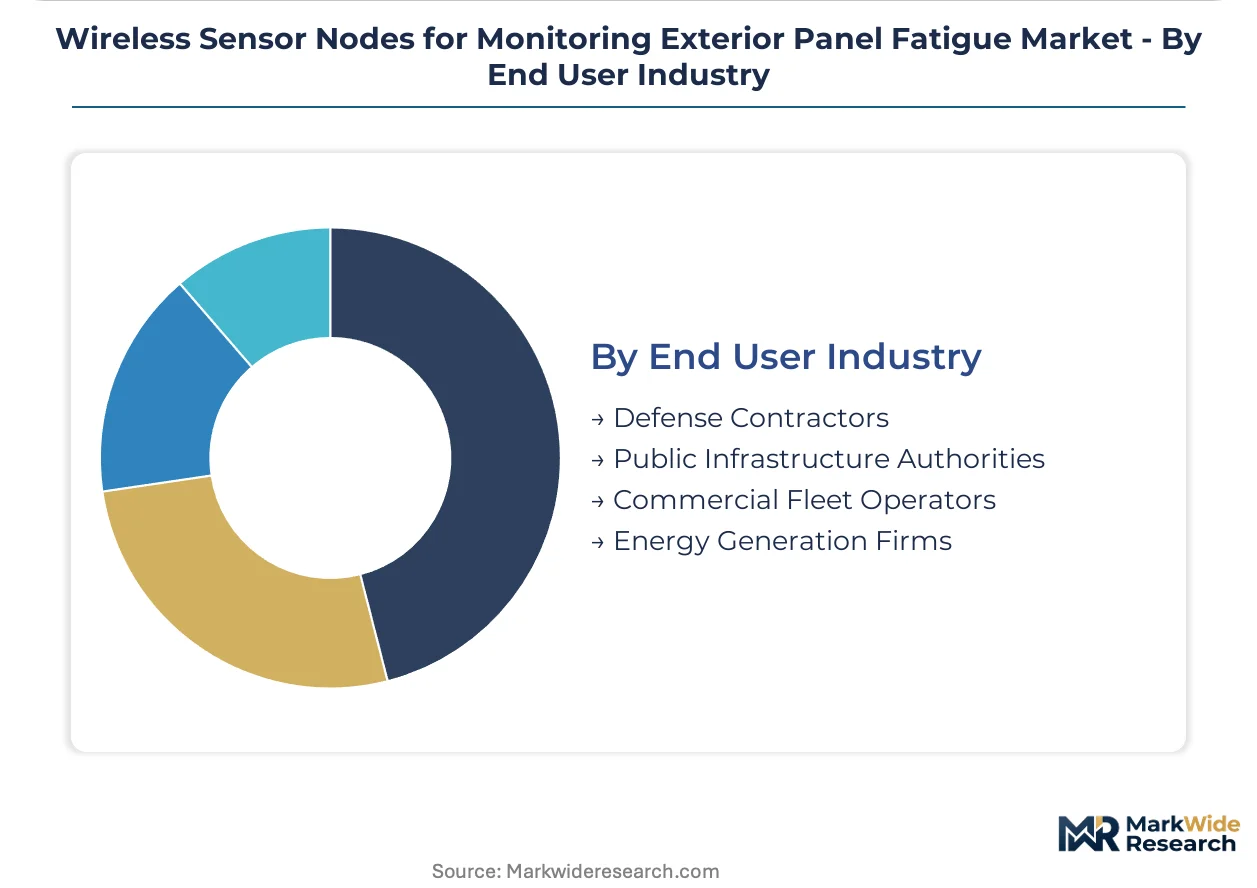
Commercial fleet operators represent largest addressable node count. Defense contractors deliver highest margin per unit through electromagnetic immunity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German rail operators absorb certification premiums under EBA mandates, while Southeast Asian wind developers prioritize lowest unit cost per node. Mature aerospace clusters in France and the United States exhibit inelastic demand for FAA-certified hardware.
United States
Boeing and Airbus North American procurement drives demand for self-powered piezoelectric nodes on transport-category aircraft. FAA TSO-C151 certification timelines stretch 18-24 months, concentrating supplier relationships among cleared vendors. Seattle and Wichita aerospace clusters anchor bonded sensor installation expertise for wing and fuselage monitoring programs.
Germany
Deutsche Bahn and rolling-stock manufacturers concentrate strain gauge procurement under EBA and KBA fatigue-documentation frameworks. Sub-GHz spectrum allocation under EU Radio Equipment Directive is forcing dual-band LoRaWAN hardware pre-qualification ahead of 2027 deadlines. Munich and Berlin rail equipment clusters host MEMS calibration facilities with drift-compensation engineering.
France
Airbus wing-monitoring specifications prioritize energy-harvesting architectures that eliminate battery replacement on sealed composite structures. CE marking harmonization pressures are compressing R&D timelines for communication module redesigns. Toulouse aerospace manufacturing and Nantes wind turbine blade production clusters drive optical sensor demand for electromagnetic-immune applications.
China
Domestic wind turbine producers specify blade-integrated monitoring for offshore assets where access costs dominate lifecycle economics. MIIT spectrum allocation rules create regional transmission-power variants that complicate scale economics. Yangtze River Delta manufacturing clusters concentrate fabless sensor designers facing MEMS foundry margin compression.
Denmark
Offshore wind farm developers deploy LoRaWAN corridor architectures enabling subscription-based monitoring-as-a-service revenue models. Vessel classification society pressure for documented hull integrity evidence drives maritime sensor adoption. Copenhagen maritime and Esbjerg offshore energy clusters exhibit highest penetration of third-party analytics provider contracts.
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. Captive MEMS foundry operators capture value from signal-conditioning die production while fabless designers face margin compression from silicon wafer cost volatility. Three archetypes dominate: vertically integrated analog semiconductor houses, aerospace-certified packaging specialists, and energy-harvesting technology developers. Competitive moves concentrate on strategic partnerships for spectrum harmonization and capacity expansion for 300mm MEMS substrate supply.
Among European integrated producers, STMicroelectronics anchors the vertically integrated tier through Italian and French MEMS production lines. Texas Instruments represents the analog fabrication specialist archetype with captive signal-conditioning chip networks. Honeywell occupies a position within aerospace-certified packaging, satisfying FAA airworthiness standards for bonded sensor installations. These three exemplify how regulatory certification requirements and foundry proximity shape competitive positioning.
| Leading Market Players |
|---|
| EnOcean |
| ABB |
| Infineon Technologies |
| Fujitsu |
| Microchip Technology |
| Lord MicroStrain |
| Honeywell |
| Texas Instruments |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
FAA TSO-C151 certification gates both supplier qualification and price stratification simultaneously, creating a dual-filter where only cleared vendors command aerospace premiums while uncertified competitors compete on unit cost in adjacent segments. This regulatory threshold bifurcates the vendor base into FAA-cleared incumbents capturing lifetime service value and commodity assemblers serving price-sensitive infrastructure buyers.
Pricing Analysis
Extended calibration service contracts and subscription-based monitoring-as-a-service revenue layers now drive lifetime value beyond hardware margins. Three-tier pricing structure across FAA-certified premium, CE-marked standard, and uncertified economy levels separates aerospace procurement from rail infrastructure and wind farm deployments. Cost compression in the economy tier intensifies because fabless designers face MEMS foundry margin squeeze without captive wafer supply. Commercial fleet operators exhibit highest price sensitivity, while defense contractors absorb electromagnetic immunity premiums without volume negotiation.
Supply Chain Analysis
300mm MEMS foundry capacity in Taiwan, South Korea, and the United States anchors sensor node substrate supply. Strain gauge foil, piezoelectric ceramic substrates, and LoRaWAN communication modules constitute critical input dependencies. Single-source vulnerability concentrates in Italian and French drift-compensation engineering clusters with scarce calibration expertise. Distribution runs through aerospace-certified channels for defense and aviation segments, while industrial distributors with MEMS testing capabilities serve rail and energy infrastructure buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monitoring-as-a-service contracts are expanding faster than hardware unit sales, reframing this market as a service-attach opportunity where recurring data revenue streams displace one-time node transactions. This shift rewards vendors who retain node ownership and bundle analytics subscriptions.
For Market Incumbents: Secure FAA TSO-C151 certification renewals ahead of airworthiness directive expansions to defend against optical fiber substitution in long-span bridge monitoring. Deepen backward integration into 300mm MEMS substrate supply through foundry partnerships or captive wafer agreements, countering silicon cost volatility that squeezes fabless competitors. Channel control over aerospace-certified distributors remains essential for defense electromagnetic immunity premiums.
For New Entrants and Emerging Players: Anchor in maritime monitoring-as-a-service contracts where vessel classification societies demand documented hull integrity evidence without mandating airworthiness certification. Danish and Singaporean maritime clusters offer lowest regulatory barriers among transportation verticals. A direct OEM partnership model with Vestas or Siemens Gamesa for offshore wind blade monitoring bypasses aerospace certification timelines entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from analog semiconductor parents with dormant MEMS fabrication lines in Italy or France, where drift-compensation engineering talent concentrates. Long-term viability hinges on spectrum harmonization execution under EU Radio Equipment Directive and FAA mandate expansion scope. The signal to watch is LoRaWAN corridor deployment velocity across German rail and Danish offshore wind as subscription revenue proof points.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Band LoRaWAN Hardware Pre-Qualification | German rail operators and French wind developers avoid stranded inventory ahead of EU spectrum harmonization deadlines. |
| Energy-Harvesting Architecture Development | Boeing and Airbus procurement specifications now prioritize self-powered nodes for sealed composite wing structures. |
| MEMS Foundry Capacity Expansion | Vertically integrated analog houses capture value from signal-conditioning die production as fabless designers face margin compression. |
| Monitoring-as-a-Service Platform Launch | Maersk and Hapag-Lloyd container fleet managers subscribe to hull fatigue data streams rather than owning sensor hardware. |
| Defense-Authorized Channel Partnership | Naval vessel programs specify passive optical sensors where radio silence requirements limit supplier pools to cleared vendors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with MEMS foundry operations directors, FAA certification engineers, rail procurement officers at Deutsche Bahn suppliers, and offshore wind project developers; and secondary validation through FCC Part 15 filings, EBA fatigue-documentation frameworks, EU Radio Equipment Directive implementation schedules, and customs data on strain gauge component trade flows. Bottom-up node shipment estimates by sensor type and communication technology triangulated against top-down infrastructure investment projections across transportation and energy verticals.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by sensor type, communication protocol, application vertical, and end-user industry procurement authority. CAGRs derived from infrastructure replacement cycles, regulatory mandate enforcement timelines, and energy-harvesting technology adoption curves. Specific inputs included FAA airworthiness directive expansion scope, EBA strain-cycle documentation mandate coverage, and LoRaWAN ecosystem maturity in European rail and offshore wind corridors.
Material uncertainties — MEMS foundry consolidation pace, national spectrum allocation divergence, and optical fiber substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline stability and energy-harvesting efficiency gains in piezoelectric architectures. Practitioners should keep alternative scenarios live as EU Radio Equipment Directive harmonization implementation and FAA mandate scope evolution reshape hardware platform strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asset Tags Market
Sensors
IO Link Market
Sensors
Europe Lidar Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Global RFID Market
Sensors
Personal Navigation Devices Market
Sensors
Beacon Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Bluetooth Beacons Market
Sensors
Real Time Location System Market
Sensors
Facial Tracking Solution Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Surface Haptic Technology Market
Sensors
Alcohol Sensor Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Transportation Sensors Market