
 Italy Fixed Wireless Access (FWA) Market | 2026-2036
Italy Fixed Wireless Access (FWA) Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Fixed Wireless Access (FWA) Market Insights
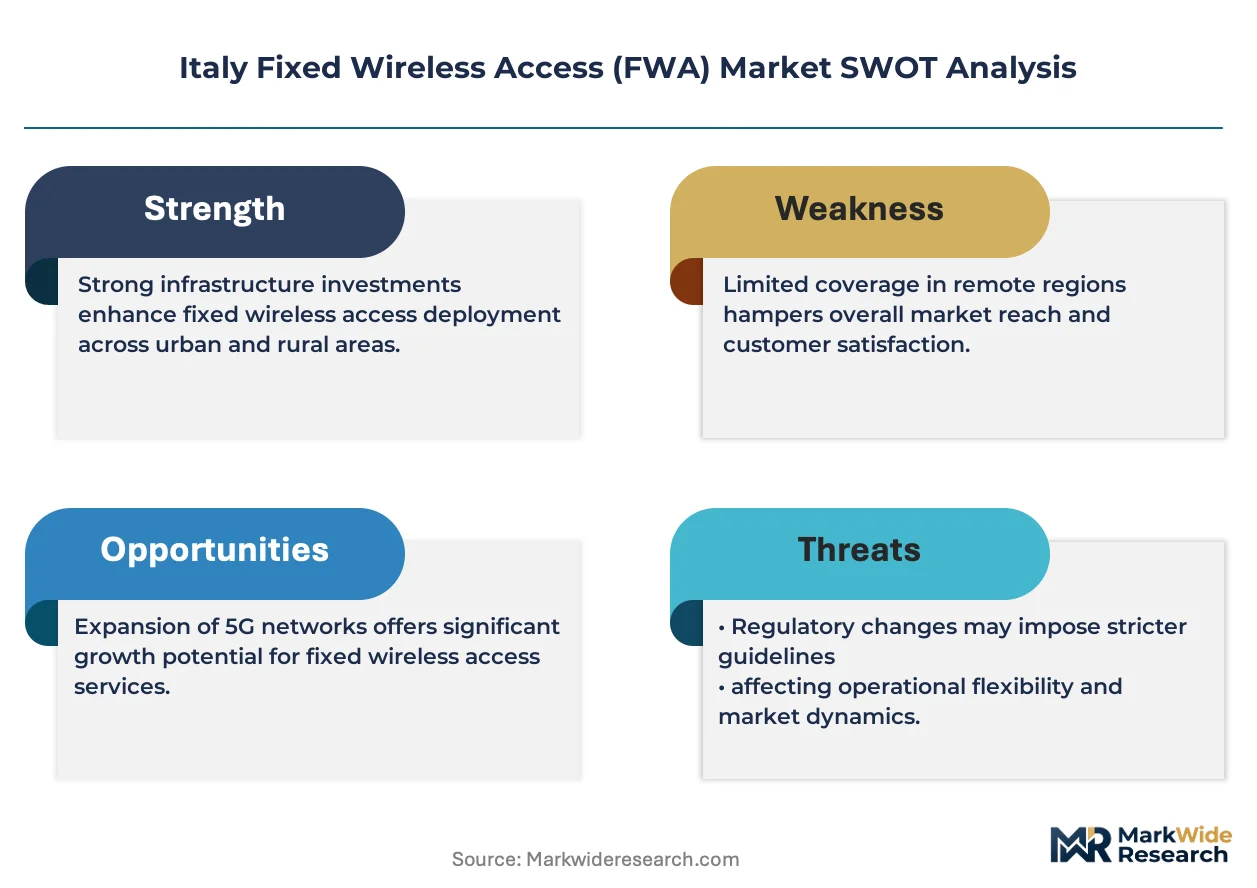
Software-defined network management is realigning what operators package as core service value rather than hardware resale. Telecom Italia S.p.A. leverages its fiber backbone to backhaul FWA traffic in dense northern corridors. EOLO S.p.A. specializes in fixed wireless for rural and semi-rural municipalities where trenching costs prohibit fiber rollout. Fastweb S.p.A. competes through aggressive spectrum positioning in the 3.5 GHz and 26 GHz bands.
Fixed Wireless Access delivers broadband connectivity via radio links between stationary base stations and customer premises equipment, typically operating in licensed spectrum below 6 GHz or in millimeter-wave bands above 24 GHz with throughput targets exceeding 100 Mbps. Its primary purpose is to extend high-speed internet to locations where fiber-to-the-home deployment proves economically unviable. The 5G technology segment carries the fastest momentum as Italian operators refarm mid-band spectrum for residential and enterprise use. Small business end users represent a deepening margin pool because these customers pay premium rates for symmetric service-level agreements that residential subscribers rarely require. Hybrid deployment models are gaining traction in Alpine and Apennine terrain where pure outdoor links face line-of-sight obstruction.
AGCOM, Italy's communications regulator, enforces wholesale access obligations and spectrum auction terms that determine which operators can serve specific territorial clusters. The European Electronic Communications Code mandates universal service benchmarks that push national funds toward FWA as a fiber-equivalent technology in white areas. Stakeholders must monitor upcoming 5G SA core rollouts and local permitting timelines for small-cell siting to anticipate where service margins will compress or expand.
Market Dynamics
The European Electronic Communications Code is forcing Italian operators to treat FWA as a fiber-equivalent universal service obligation, redirecting state broadband funds toward wireless infrastructure in white areas where trenching costs exceed deployment budgets.
Growth Catalysts
- AGCOM wholesale access mandates:The regulator's open network obligations prevent infrastructure lock-in, enabling new entrants to lease incumbent backhaul and accelerate rural coverage without duplicating fiber investment.
- Small business symmetric SLA demand:Professional service firms in Palermo and Catania pay premium rates for guaranteed upload speeds that residential tiers cannot match, deepening operator margins.
- 3.5 GHz spectrum refarming:Mid-band 5G carrier aggregation is extending coverage radius per cell site, reducing the number of rural towers needed to blanket Calabrian provinces.
Market Restraints
- Alpine terrain line-of-sight limitations:Mountainous topography in northern Lombardy and Aosta Valley blocks millimeter-wave propagation, forcing costly hybrid fiber-wireless architectures.
- Single-source CPE supply concentration:Customer premises equipment for 26 GHz bands relies on a narrow vendor base concentrated in East Asian manufacturing hubs, creating procurement bottlenecks.
- Local permitting fragmentation:Municipal siting approvals for small cells vary across Italy's 20 regions, delaying rollout timelines in areas with strict heritage or environmental review boards.
Strategic Opportunities
- Sicily agricultural IoT backhaul:Precision farming cooperatives in Ragusa and Syracuse require field-level connectivity that fiber cannot economically reach, creating dedicated enterprise FWA demand.
- EU Recovery and Resilience Facility subsidies:Italy's allocated broadband funds explicitly include wireless alternatives to fiber in marginal coverage areas, lowering operator capex burdens.
- Convergence of FWA and private 5G networks:Industrial zones in Bari and Taranto are piloting shared infrastructure models where operator spectrum serves both residential and factory automation use cases.
Industry Challenges
- RF planning talent scarcity:Specialized engineers capable of optimizing propagation models for Apennine terrain command salaries that strain regional operator payrolls.
- Legacy copper decommissioning coordination:TIM's fiber migration timelines must synchronize with FWA handoffs to prevent service gaps in Campanian provinces where copper retirement precedes wireless activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Fixed Wireless Access (FWA) Market |
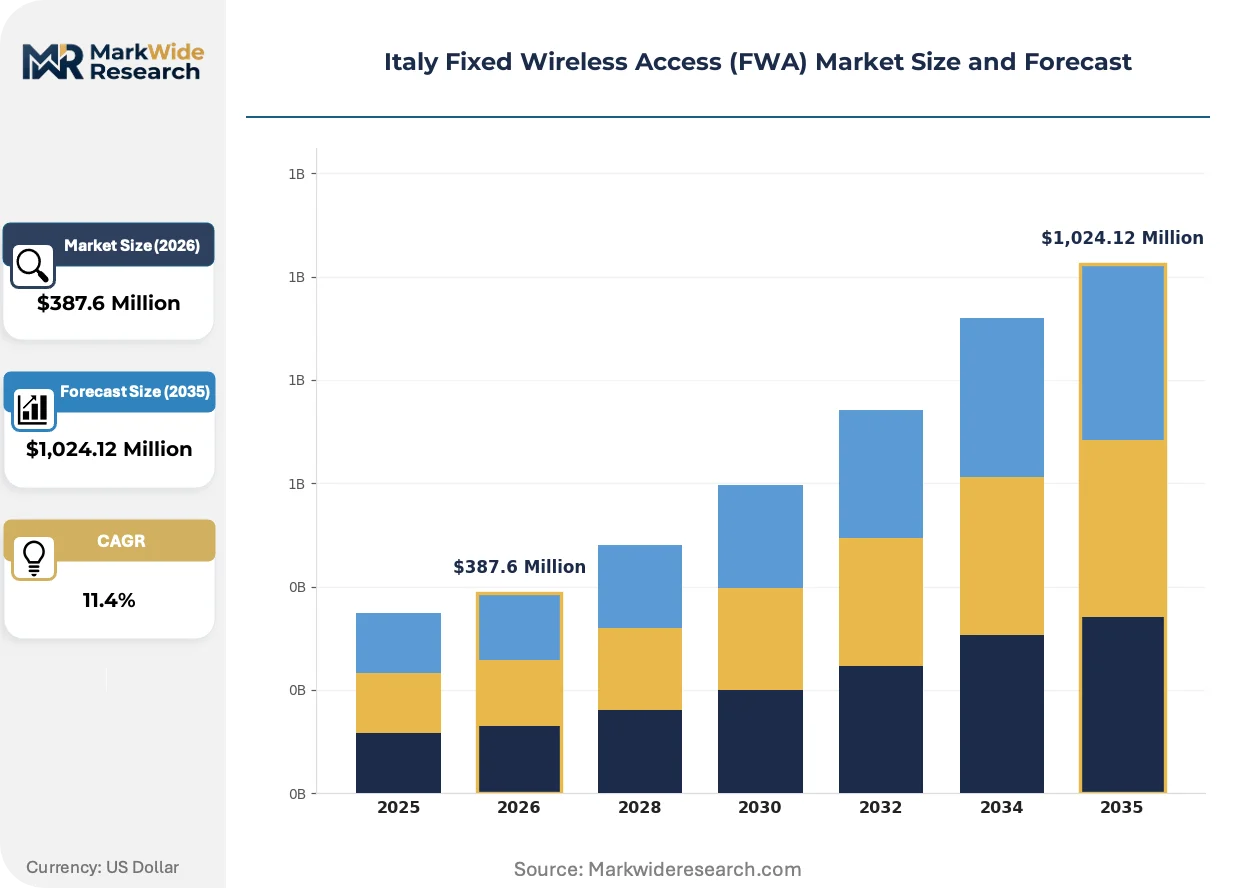
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, WiMAX, 5G, Satellite End User: Residential, Small Business, Enterprises, Government Service Type: Broadband, VoIP, IPTV, Cloud Services Deployment Model: Outdoor, Indoor, Hybrid, Small Cell |
| Companies Covered | Vodafone Italia S.p.A., Wind Tre, EOLO S.p.A., OpNet, Tiscali, Telecom Italia S.p.A., Linkem S.p.A., FiberCop, Fastweb S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Fixed Wireless Access (FWA) Market Trends and Innovations
Software-defined network management is redefining how Italian operators monetize FWA, shifting revenue models from hardware resale toward subscription-based service orchestration. This transformation is compressing capital intensity while expanding addressable use cases.
5G standalone core architecture is consolidating control plane functions previously distributed across hardware appliances, enabling dynamic network slicing for differentiated enterprise SLAs. Agricultural cooperatives in Sicily are adopting these slices for automated irrigation systems. The technology is consolidating vendor relationships as operators reduce reliance on multi-supplier integration.
Italy's national broadband plan under the European Electronic Communications Code now mandates technology-neutral funding eligibility, treating FWA as equivalent to fiber in white-area tenders. This policy revision is unlocking public financing for wireless-only deployments. Southern regions including Calabria and Basilicata are responding with accelerated procurement timelines for rural coverage contracts.
Small businesses are abandoning multi-year connectivity contracts in favor of month-to-month service tiers with embedded upgrade paths. Resellers in Milan and Rome are replacing traditional distribution with direct digital sales portals. The shift is most visible among professional services firms in northern Italy, where switching costs have fallen below contractual friction thresholds.
Italy Fixed Wireless Access (FWA) Market Segmentation
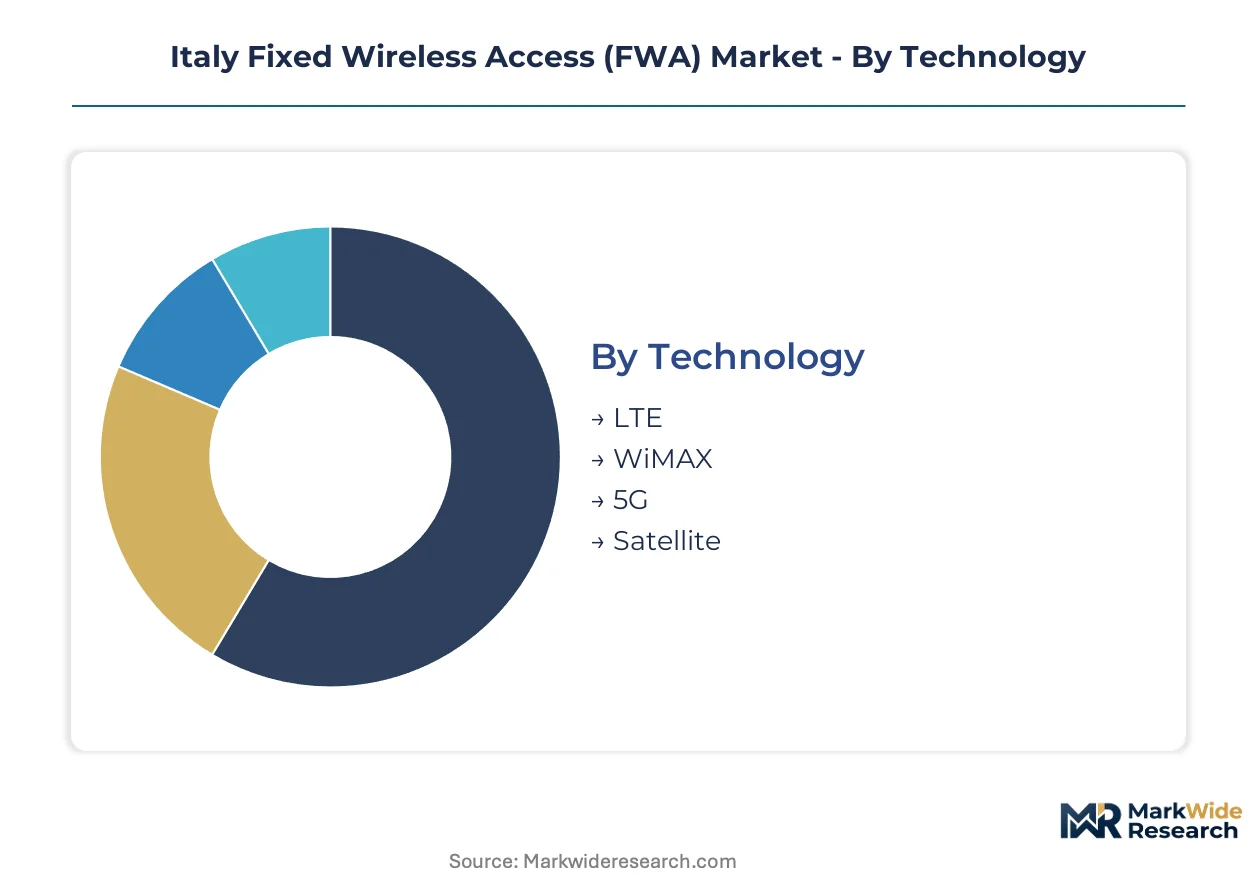
Italian operators structure FWA portfolios around distinct technology generations and customer tiers that command diverging margin profiles. Each segmentation dimension carries specific regulatory, geographic, and competitive implications for deployment economics across the peninsula.
Technology:
Buyers select radio platforms based on coverage radius requirements and spectrum availability in their target municipalities.
- 5G:Mid-band carrier aggregation in 3.5 GHz bands delivers throughput exceeding 100 Mbps with cell radii extending 5-7 kilometers. AGCOM's spectrum refarming policies favor this platform in Calabrian and Sicilian provinces where tower density must remain low. Small business demand in Palermo and Catania concentrates here for symmetric SLA guarantees.
- LTE:Mature 4G infrastructure supports sub-100 Mbps tiers at lower equipment cost, anchoring residential volumes in Campanian provinces where TIM maintains extensive legacy backhaul. Rural households in Basilicata rely on this technology where 5G small-cell timelines remain uncertain.
- WiMAX:Legacy TDD deployments persist in isolated Alpine valleys of Aosta where equipment refresh cycles lag national averages.
- Satellite:Geostationary and LEO constellations serve extreme white areas in Sardinian interior where terrestrial line-of-sight fails entirely.
Volume sits with LTE; growth tilts toward 5G.
End User:
Revenue per connection varies by customer type, with professional service firms commanding premium rates for guaranteed service levels.
- Small Business:Law firms, medical practices, and agricultural cooperatives in Sicily and Calabria purchase symmetric upload-download tiers with 99.9% uptime SLAs. These subscribers generate margins 40-60% above residential equivalents and drive 5G standalone core investments.
- Residential:Households in fiber-deprived southern provinces select asymmetric broadband tiers with embedded IPTV bundles. Campanian provinces represent the deepest addressable pool, though price sensitivity constrains ARPU expansion.
- Enterprises:Industrial zones in Bari and Taranto pilot private 5G-FWA convergence for factory automation backhaul.
- Government:Municipal administrations in rural Basilicata procure FWA for public building connectivity under EU Recovery and Resilience Facility tenders.
Residential connections dominate installed base; small business ARPU climbs the fastest.
Service Type:
Bundle composition determines customer stickiness and churn exposure across competitive provincial markets.
- Broadband:Standalone internet access constitutes the core offering, with speed tiers differentiated by 30/100/300 Mbps thresholds. Rural Campanian demand concentrates in entry tiers where fiber alternatives remain absent.
- VoIP:Voice-over-IP services replace legacy copper PSTN as TIM decommissions aging infrastructure. Small businesses in Palermo require guaranteed call quality that residential VoIP cannot match.
- IPTV:Video bundles attach primarily to residential subscribers in northern provinces where Fastweb and TIM compete for entertainment-heavy households.
- Cloud Services:Managed security and storage overlays target professional services firms in Milan and Rome with compliance requirements.
Standalone broadband captures volume; cloud service attachments expand most quickly.
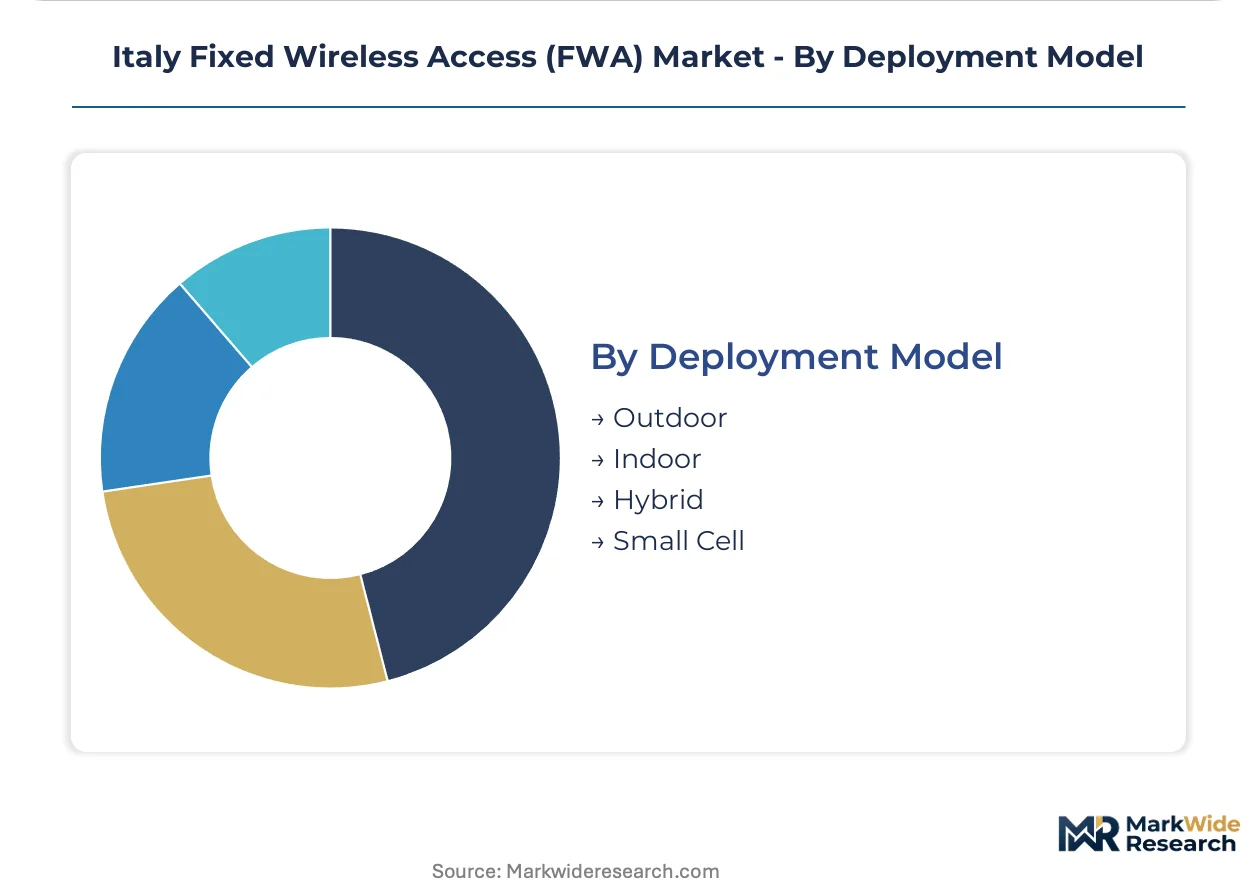
Deployment Model:
Site architecture responds to terrain constraints and regulatory siting permissions that vary across Italy's 20 regions.
- Outdoor:Directional antennas on rooftops and poles maximize line-of-sight propagation in flat Sicilian agricultural zones. EOLO specializes in this model across Ragusa and Syracuse provinces.
- Hybrid:Fiber backhaul to wireless last-mile distribution dominates Alpine and Apennine terrain where pure outdoor links face obstruction. Telecom Italia leverages this architecture in Lombard mountain valleys.
- Indoor:Self-install CPE with window-mounted receivers serves dense urban apartments in Rome and Milan where outdoor mounting faces landlord restrictions.
- Small Cell:Compact base stations supplement coverage in heritage-sensitive historic centers where macro tower placement faces municipal opposition.
Outdoor deployments hold volume; hybrid architectures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors Italy's FWA infrastructure investment as Lombardy's financial and industrial corridor drives fiber-backhaul integration for wireless distribution across the Po Valley.
Lombardy
Enterprise demand from Milan's professional services cluster and Bergamo's manufacturing belt propels hybrid FWA deployments. AGCOM's wholesale access mandates enable new entrants to lease Telecom Italia's fiber backbone. EOLO S.p.A. concentrates outdoor wireless coverage across the flat agricultural zones of Cremona and Mantua provinces.
Sicily
Agricultural cooperatives in Ragusa and Syracuse require precision farming connectivity that trenching costs prohibit. The European Electronic Communications Code redirects state broadband funds toward wireless infrastructure in these white areas. Small business symmetric SLA demand in Palermo and Catania deepens operator margins.
Calabria
Rural households and professional firms in Cosenza and Reggio Calabria purchase entry-tier broadband where fiber remains absent. Italy's national broadband plan treats FWA as fiber-equivalent for universal service obligations. 3.5 GHz spectrum refarming extends cell radii to reduce tower density requirements across mountainous terrain.
Campania
Copper decommissioning timelines in Naples and Salerno provinces force coordination between TIM's fiber migration and FWA activation. The EU Recovery and Resilience Facility subsidizes wireless alternatives in marginal coverage zones. Residential price sensitivity constrains ARPU expansion despite deep addressable pools.
Piedmont
Alpine terrain in Aosta Valley and Susa Valley blocks millimeter-wave propagation, necessitating costly hybrid architectures. Local permitting fragmentation across municipal heritage boards delays small-cell siting in Turin's historic center. Fastweb S.p.A. competes through spectrum positioning in the 3.5 GHz and 26 GHz bands.
Italy Fixed Wireless Access (FWA) Market Competitive Landscape
Capital-heavy infrastructure owners compete with asset-light service resellers for subscriber access across Italy's fragmented provincial markets. The vendor base separates into three strategic tiers: national incumbents leveraging legacy fiber assets, regional specialists exploiting rural white-space opportunities, and wholesale-dependent entrants riding open-network mandates. Consolidation pressures mount as spectrum scarcity and municipal permitting bottlenecks raise fixed costs. Dominant competitive moves include spectrum auction positioning for mid-band 5G refarming and direct digital sales portal deployment to bypass traditional distribution.
Among national incumbent operators, Telecom Italia S.p.A. and Fastweb S.p.A. anchor the infrastructure-integrated tier, while EOLO S.p.A. exemplifies the rural-specialist archetype through its concentration on wireless-only municipalities where trenching economics fail. These three entities occupy distinct competitive positions based on spectrum holdings and backhaul control rather than overlapping service territories.
| Leading Market Players |
|---|
| Vodafone Italia S.p.A. |
| Wind Tre |
| EOLO S.p.A. |
| OpNet |
| Tiscali |
| Telecom Italia S.p.A. |
| Linkem S.p.A. |
| FiberCop |
| Fastweb S.p.A. |
| Others |
Pricing and Supply Chain Analysis
A sharp divergence between premium symmetric-SLA tiers for Sicilian professional service firms and commodity residential bundles in Campanian provinces manifests in both pricing power and supply chain sourcing strategies. Italian operators source mid-band 5G radio units from Taiwan and South Korea while procuring millimeter-wave CPE from concentrated East Asian manufacturing hubs, creating tier-specific cost structures that propagate into end-user rate cards.
Pricing Analysis
Margin tightening in residential tiers traces to TIM's aggressive fiber migration timelines and wholesale access obligations under AGCOM mandates. Pricing stratifies across premium symmetric-SLA tiers for Palermo law firms, standard asymmetric bundles for Campanian households, and economy entry-level plans for Basilicata rural subscribers. Price differentiation hinges on upload speed guarantees and after-sales service bundling. Small businesses in Catania show least price sensitivity due to compliance-driven connectivity requirements.
Supply Chain Analysis
5G baseband semiconductor supply rests on Taiwanese foundry capacity and South Korean memory fabrication, with millimeter-wave RF components drawing from Japanese specialty substrate producers. Raw material dependencies span GaN-on-SiC wafers for power amplification, high-frequency laminates for antenna substrates, and precision-machined waveguide assemblies. Single-source vulnerability concentrates in 26 GHz CPE chipsets where vendor qualification timelines exceed eighteen months. Distribution runs through operator-direct procurement for macro infrastructure and authorized reseller channels for customer premises equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy FWA market functions as a vertical-integration race where spectrum control and fiber backhaul ownership determine sustainable margin capture. Players securing mid-band 5G licenses and municipal small-cell permits gain structural advantages that asset-light resellers cannot replicate.
For Market Incumbents: Anticipate margin compression in residential tiers as Linkem and OpNet exploit wholesale access mandates to undercut rate cards. Defensive moves require deepening fiber-backhaul integration in Lombardy to raise rival costs, while accelerating 5G standalone core deployment to lock in small business SLA premiums. Priority lever: spectrum auction positioning for 26 GHz millimeter-wave blocks in Piedmont heritage zones where permitting bottlenecks protect incumbent timing advantages.
For New Entrants and Emerging Players: Enter via EU Recovery and Resilience Facility tender participation in Calabrian and Basilicata white areas where public financing lowers capex barriers. Most penetrable segment: agricultural IoT backhaul cooperatives in Ragusa and Syracuse provinces where precision farming demand outstrips fiber economics. Go-to-market angle: direct digital sales portals bypassing traditional distribution to capture month-to-month service subscribers abandoning multi-year contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists controlling municipal small-cell permits and 3.5 GHz spectrum holdings given AGCOM's technology-neutral funding eligibility under the European Electronic Communications Code. Long-term viability favors operators with hybrid deployment capabilities across Alpine terrain where pure outdoor links fail. Acquisition target archetype: rural wireless specialists with concentrated Campanian or Sicilian coverage footprints. Signal to watch: local permitting timeline acceleration in heritage-sensitive historic centers as municipal review boards streamline environmental assessments.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Auction Positioning | Mid-band 5G licenses in 3.5 GHz bands determine coverage radius economics across Calabrian provinces. |
| Hybrid Deployment Architecture | Fiber-wireless integration unlocks Alpine valleys where millimeter-wave propagation faces line-of-sight obstruction. |
| Direct Digital Sales Portal | Digital channels capture month-to-month subscribers in Milan and Rome professional services clusters. |
| Small Cell Siting Acceleration | Municipal permit streamlining in Turin historic center expands coverage where macro towers face heritage opposition. |
| Symmetric SLA Product Tier | Guaranteed upload speeds command 40-60% margin premiums from Palermo and Catania professional firms. |
Research Methodology
Document review covered AGCOM spectrum auction records, European Electronic Communications Code implementation guidelines, and EU Recovery and Resilience Facility broadband tender documentation, complemented by interviews with network planning executives at Italian mobile operators, procurement leads at CPE vendors, and municipal infrastructure officers in Sicily and Calabria. Secondary validation drew from Telecom Italia regulatory filings, Fastweb spectrum holding disclosures, and customs data on 5G radio equipment imports. Bottom-up connection forecasts triangulated against top-down addressable market sizing by province.
Historical deployment trajectories cross-referenced against panel input from RF planning engineers and wholesale access negotiators shaped the analytical framework. Segmentation dimensions modeled span technology generation, end-user archetype, service bundle composition, and deployment architecture across the analysis window. CAGRs derived from province-level connection adoption curves weighted by AGCOM coverage obligation timelines. Industry-specific inputs included 3.5 GHz propagation models for Apennine terrain and municipal permitting duration distributions by regional heritage board.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated copper decommissioning schedules or delayed 5G standalone core rollouts. Forecasts reflect documented assumptions on spectrum refarming timelines, state subsidy allocation rates, and small business SLA penetration curves. Spectrum auction timing, municipal siting approval velocity, and East Asian CPE supply chain disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Public Wi-Fi Market