
 Global Remote Tank Monitoring System Market | 2026-2036
Global Remote Tank Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Tank Monitoring System Market Foresight
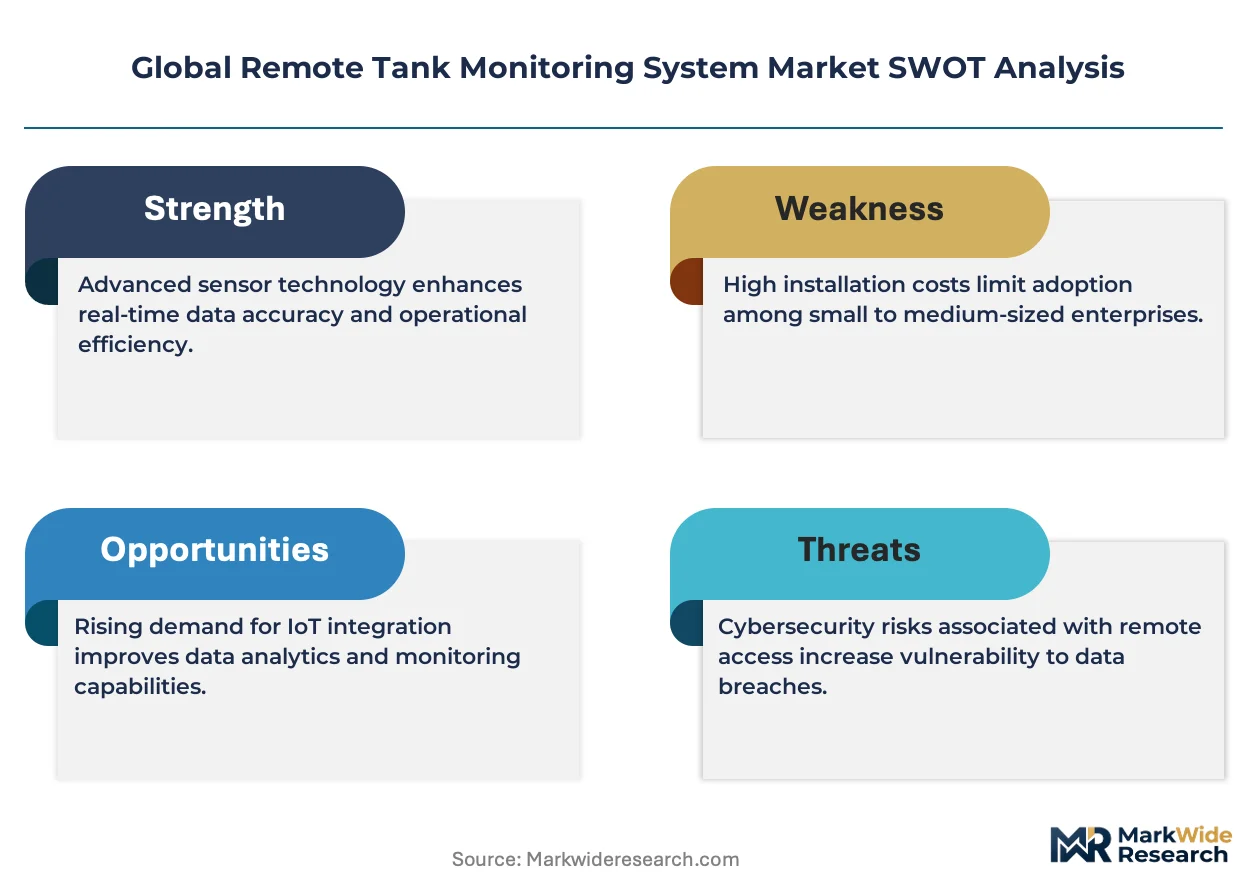
The remote tank monitoring system market is restructuring around a sharp split between premium IoT-enabled platforms with predictive analytics and commodity wireless sensors delivering basic level alerts. Emerson Electric leverages its automation heritage to anchor high-margin contracts with oil and gas operators requiring SIL-certified instrumentation. Schneider Electric competes through edge-computing architectures that process data locally before cloud transmission. Siemens dominates European municipal water authority tenders with integrated SCADA compatibility.
Remote tank monitoring systems combine level, pressure, and temperature sensors with wireless telemetry units to transmit real-time inventory data from fixed or mobile storage vessels to centralized dashboards, typically achieving accuracy within one millimeter for radar-based level measurement. These systems primarily eliminate manual dipstick readings, prevent stockouts or overflows, and enable just-in-time logistics across distributed tank networks. Ultrasonic sensors lead unit shipments in water and chemical applications where non-contact measurement resists corrosive media buildup, while radar sensors command premium pricing in petroleum terminals demanding precision through vapor layers. IoT technology sustains the fastest expansion as cellular LPWAN modules slash connectivity costs for remote sites lacking broadband infrastructure.
The EPA mandates Spill Prevention, Control, and Countermeasure plans for above-ground oil storage exceeding specific thresholds, directly driving sensor installation across US fuel distribution networks. ECHA's REACH framework in Europe restricts hazardous substance handling, compelling chemical manufacturers to deploy continuous leak detection tied to automated shutdown valves. China's MEE enforces increasingly stringent environmental monitoring for industrial storage facilities, accelerating domestic demand for cloud-connected tank monitoring. Stakeholders must weigh the trade-off between satellite monitoring's universal coverage and cellular IoT's lower operating costs when designing networks spanning multiple regulatory jurisdictions.
Market Dynamics
The remote tank monitoring system market is restructuring around a sharp split between premium IoT-enabled platforms with predictive analytics and commodity wireless sensors delivering basic level alerts. This bifurcation is compressing margins for mid-tier suppliers while rewarding vendors with certified industrial automation heritage.
Growth Catalysts
- EPA spill prevention mandates:The EPA's SPCC rules for above-ground oil storage above threshold volumes compel fuel distributors across the United States to install continuous level monitoring with automated alert systems.
- Rhine corridor industrial clustering:Chemical manufacturers along Germany's Rhine corridor prioritize real-time inventory visibility to synchronize just-in-time logistics with barge and rail schedules.
- Cellular LPWAN cost collapse:Low-power wide-area network modules have slashed connectivity costs for remote storage sites lacking fiber or broadband infrastructure, enabling sensor deployment at previously uneconomical locations.
Market Restraints
- Sensor hardware commoditization:Basic ultrasonic and pressure sensors face price erosion from Asian contract manufacturers, squeezing margin pools for established instrumentation suppliers.
- Satellite connectivity cost premium:Universal coverage via satellite telemetry carries operating expense multiples above cellular IoT, limiting adoption in multi-jurisdiction tank networks spanning remote territories.
- REACH compliance complexity:ECHA's substance restrictions create documentation burdens for chemical storage monitoring systems, extending sales cycles and inflating project engineering costs.
Strategic Opportunities
- India industrial storage expansion:Petroleum marketing companies and chemical parks under the country's PLI scheme for manufacturing are greenfielding tank farms without legacy SCADA, creating openings for cloud-native monitoring platforms.
- Predictive maintenance convergence:Integration of vibration and corrosion sensors with level telemetry enables condition-based monitoring of tank integrity, opening service revenue streams beyond hardware sales.
- Municipal water authority digitization:Aging distribution infrastructure in Italy and Spain is driving tenders for integrated pressure-level monitoring to reduce non-revenue water losses.
Industry Challenges
- SIL certification timelines:Achieving Safety Integrity Level certification for instrumentation used in hazardous petroleum storage requires 18-24 month validation cycles that delay product launches.
- Legacy SCADA integration friction:Brownfield chemical terminals operate proprietary communication protocols that demand custom gateway development to connect modern IoT sensors to existing control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Tank Monitoring System Market |
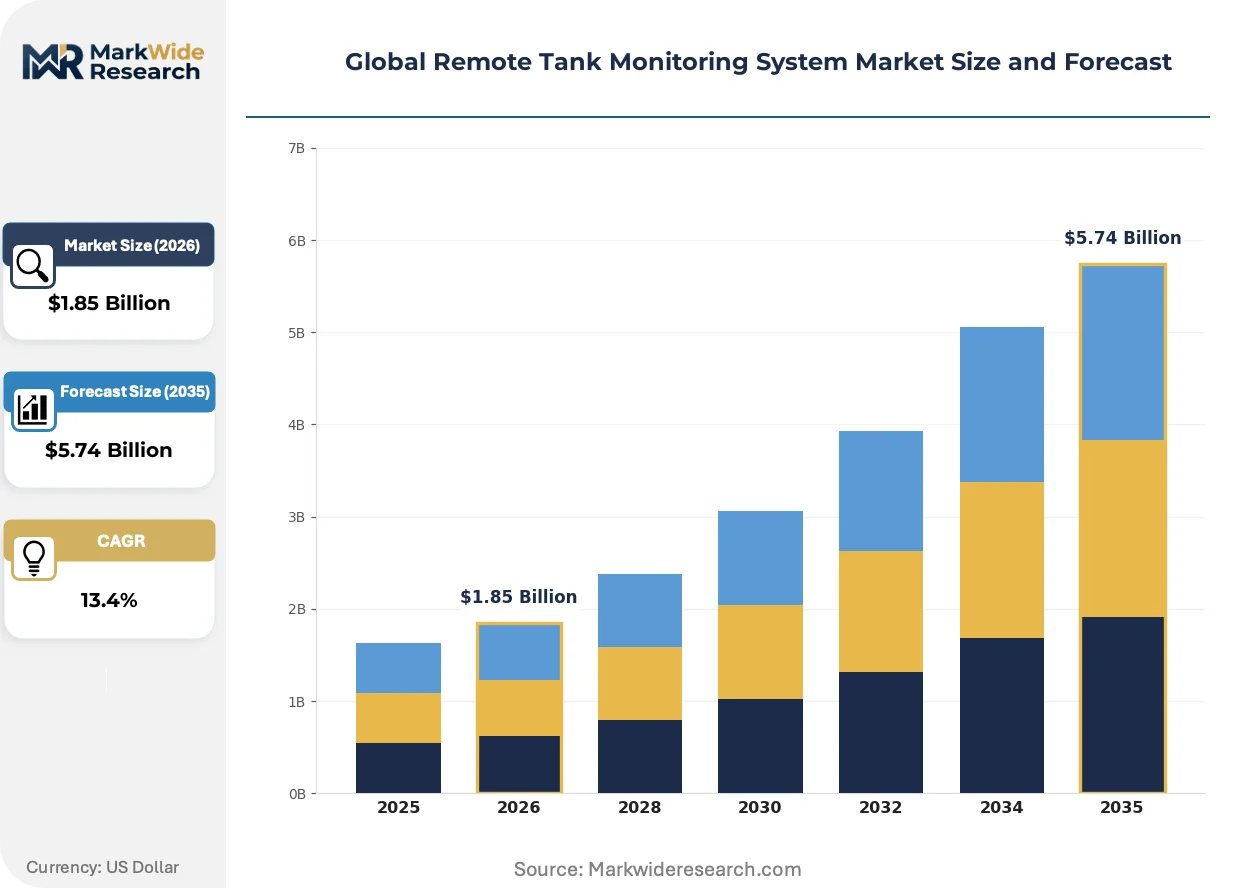
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level Sensors, Pressure Sensors, Ultrasonic Sensors, Radar Sensors, Temperature Sensors Technology: IoT, Wireless Communication, Satellite Monitoring, Cloud Computing, Data Analytics Application: Chemical Storage, Fuel Management, Water Supply, Food & Beverage, Pharmaceuticals End User: Oil & Gas Operators, Municipal Water Authorities, Food Processors, Chemical Manufacturers, Pharmaceutical Companies |
| Companies Covered | Otodata, Anova, Emerson Electric, Schneider Electric, Honeywell International, Siemens, SkyBitz, Banner Engineering, Endress+Hauser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Tank Monitoring System Market Shifts & Advancements
Radar-based level measurement is absorbing market share from ultrasonic alternatives as petroleum terminals demand precision through vapor layers and foam. Edge computing architectures are processing sensor data locally before cloud transmission, reducing latency for critical leak detection. Chemical manufacturers are unbundling hardware procurement from multi-year service contracts, compressing vendor switching costs.
Frequency-modulated continuous wave radar is absorbing the high-precision measurement segment previously dominated by guided wave radar and mechanical float systems. Petroleum terminals in the Netherlands and Belgium specify FMCW instruments for custody transfer applications where one-millimeter accuracy determines commercial settlements. The technology is absorbing premium pricing power from suppliers with patented signal processing algorithms that filter vapor interference.
China's MEE enforcement of real-time environmental monitoring for industrial storage facilities is mandating cloud-connected tank monitoring with centralized data reporting to provincial authorities. Chemical parks in Jiangsu and Shandong provinces must install continuous emission and leak detection tied to automated shutdown valves. Domestic sensor manufacturers are absorbing market share from foreign suppliers by offering MEE-compliant data interfaces as standard configurations.
Petrochemical buyers are consolidating vendor relationships from point-solution suppliers to integrated automation platforms, favoring vendors with SCADA compatibility and predictive analytics suites. Procurement teams at integrated oil companies in the United States now evaluate tank monitoring as part of enterprise-wide digital transformation programs rather than isolated capital projects. This behavioral shift is compressing contract values for standalone sensor vendors while expanding attach rates for software and services at full-platform suppliers.
Global Remote Tank Monitoring System Market Segmentation
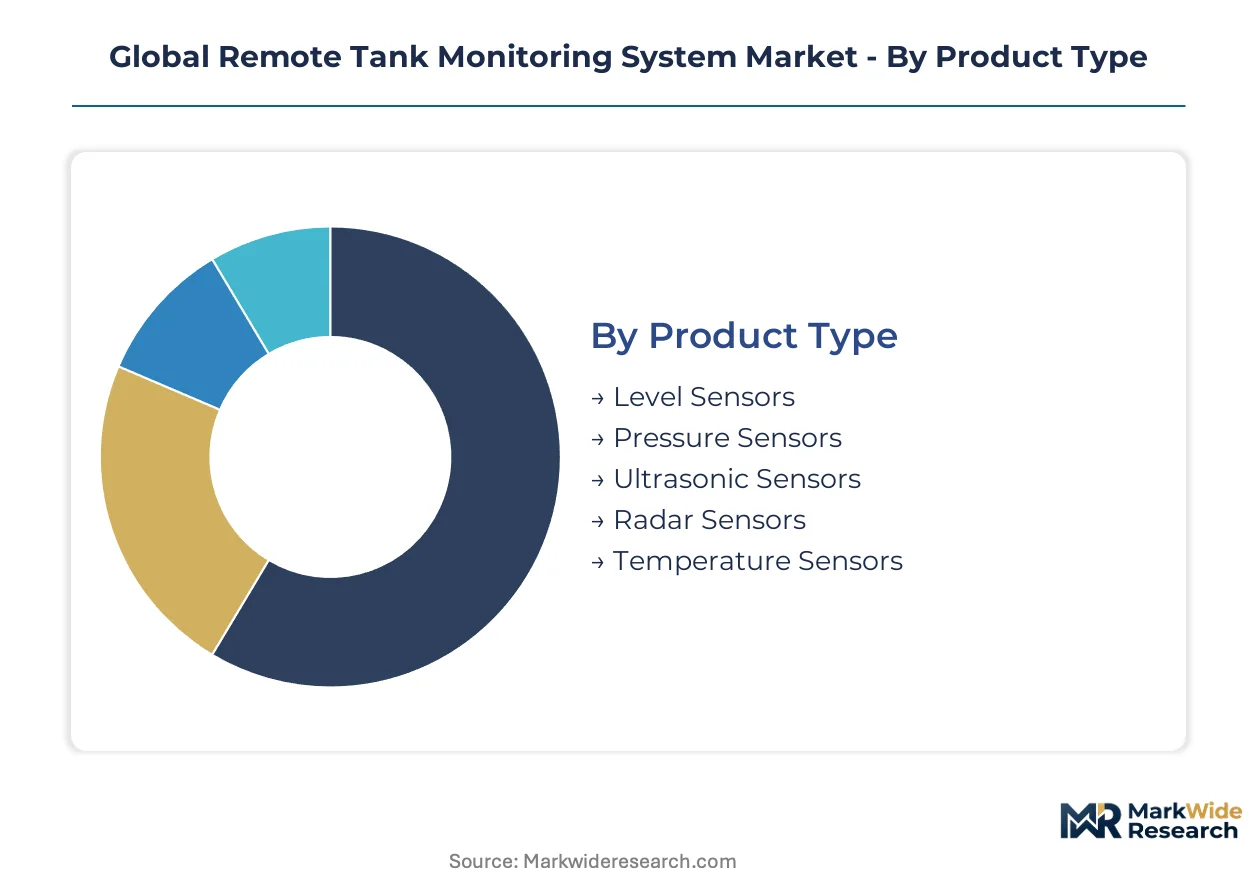
Remote tank monitoring system procurement splits sharply between commodity hardware for basic level detection and premium integrated platforms with predictive capabilities. Vendors must align product portfolios to distinct margin pools across sensor types, connectivity technologies, and end-user automation maturity.
Product Type:
Volume shipments concentrate in standard ultrasonic and pressure instruments, while radar sensors command premium positioning through precision certification.
- Level Sensors:Capacitive and hydrostatic instruments dominate water and chemical applications where continuous inventory visibility prevents overflow events. Municipal water authorities in Spain and Italy deploy these for non-revenue water reduction programs.
- Pressure Sensors:Submersible and differential pressure transmitters measure liquid head in vented and pressurized vessels. Oil and gas operators specify these for underground storage caverns where direct level access proves impractical.
- Ultrasonic Sensors:Non-contact time-of-flight measurement resists corrosive media buildup in chemical storage. German Rhine corridor manufacturers favor these for aggressive fluid compatibility.
- Radar Sensors:Frequency-modulated continuous wave technology achieves one-millimeter accuracy through vapor layers and foam. Petroleum terminals in the Netherlands and Belgium mandate FMCW instruments for custody transfer settlements.
- Temperature Sensors:RTD and thermocouple probes monitor thermal stratification and product quality in heated storage. Food processors deploy these for HACCP compliance in edible oil and dairy tanks.
Mature deployment sits with ultrasonic and pressure sensors. Newer deployment is concentrated in radar instruments with advanced signal processing.
Technology:
Connectivity architecture determines total cost of ownership across remote sites with varying infrastructure availability.
- IoT:Cellular LPWAN modules slash connectivity costs for distributed tank networks lacking broadband. China's MEE mandates cloud-connected monitoring with provincial data interfaces.
- Wireless Communication:Proprietary radio and mesh networks serve campus-style industrial facilities with established IT governance. Chemical parks in Jiangsu province deploy these for localized control before cloud uplink.
- Satellite Monitoring:Universal coverage enables Arctic fuel depots and offshore platforms beyond cellular range. Operating expense multiples above cellular IoT limit adoption in multi-jurisdiction networks.
- Cloud Computing:Centralized dashboards aggregate telemetry from thousands of distributed vessels. Indian petroleum marketing companies under PLI schemes favor cloud-native platforms without legacy SCADA investment.
- Data Analytics:Predictive algorithms forecast replenishment timing and detect anomaly patterns. Integrated oil companies in the United States evaluate these as part of enterprise digital transformation programs.
Established infrastructure relies on wireless communication and satellite. Steepest expansion trajectory belongs to IoT-enabled platforms with embedded analytics.
Application:
Regulatory stringency varies sharply across stored substances, with hazardous materials driving certified instrumentation demand.
- Chemical Storage:Continuous leak detection with automated shutdown valves satisfies ECHA REACH documentation requirements. German industrial clusters prioritize real-time inventory synchronization with barge logistics.
- Fuel Management:EPA SPCC mandates compel above-ground oil storage monitoring with automated alert thresholds. US fuel distributors face compliance deadlines for continuous level instrumentation.
- Water Supply:Pressure-level integration reduces distribution losses in aging Italian and Spanish infrastructure. Municipal authorities tender for SCADA-compatible systems.
- Food & Beverage:Hygienic design standards and CIP compatibility constrain sensor selection. Temperature monitoring dominates quality assurance protocols.
- Pharmaceuticals:Batch record integration and 21 CFR Part 11 compliance shape validation requirements. Cold chain storage demands redundant temperature telemetry.
Regulatory maturity centers on fuel management and chemical storage. Emerging deployment concentrates in pharmaceutical cold chain applications.
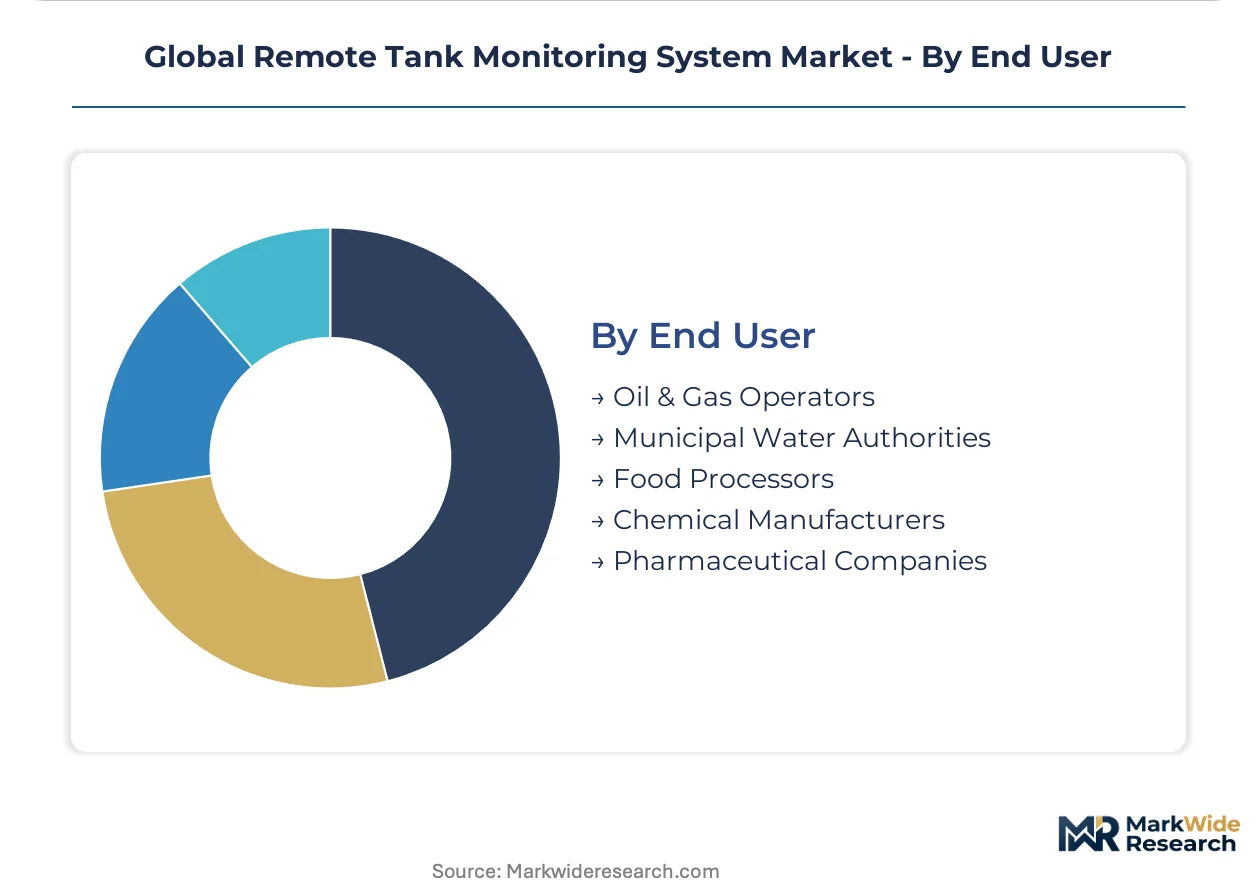
End User:
Procurement sophistication ranges from operational technology teams specifying SIL-certified instruments to facilities managers purchasing cloud subscriptions.
- Oil & Gas Operators:SIL certification requirements and hazardous area classifications filter vendor qualification. Eighteen to twenty-four month validation cycles delay product launches for this segment.
- Municipal Water Authorities:Integrated SCADA compatibility dominates European tender evaluation. Siemens anchors this vertical with legacy protocol support.
- Food Processors:Hygienic design and washdown ratings precede technical specifications. Smaller operators favor subscription-based monitoring without capital deployment.
- Chemical Manufacturers:Just-in-time logistics synchronization drives real-time inventory visibility investment. Rhine corridor producers lead sensor density per tank.
- Pharmaceutical Companies:Validation documentation and audit trails consume procurement attention. Quality assurance departments override cost optimization in vendor selection.
Established automation investment characterizes oil and gas operators and municipal authorities. Fastest-growing demand originates from pharmaceutical quality assurance expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine corridor industrial clusters in Germany anchor sensor deployment density for chemical logistics synchronization with barge and rail networks.
United States
Fuel distributors face EPA SPCC compliance deadlines for continuous level monitoring at above-ground oil storage facilities. The Houston Ship Channel petrochemical complex drives demand for SIL-certified instrumentation in hazardous area classifications. Midwest agricultural terminals deploy cellular LPWAN modules for remote grain and fertilizer storage without broadband infrastructure.
Germany
Chemical manufacturers along the Rhine corridor prioritize real-time inventory visibility to synchronize just-in-time logistics. ECHA REACH substance restrictions compel continuous leak detection with automated shutdown valves. The BASF Ludwigshafen complex exemplifies sensor density per tank for barge loading coordination.
China
MEE enforcement mandates cloud-connected tank monitoring with provincial data reporting for industrial storage facilities. Chemical parks in Jiangsu and Shandong provinces must install continuous emission and leak detection systems. Domestic sensor manufacturers capture market share by offering MEE-compliant data interfaces as standard configurations.
Netherlands
Petroleum terminals in Rotterdam and Amsterdam specify frequency-modulated continuous wave radar for custody transfer applications demanding one-millimeter accuracy. The Port of Rotterdam's storage operators require precision through vapor layers and foam for commercial settlement integrity. Dutch distribution networks favor integrated SCADA compatibility for enterprise-wide visibility.
India
Petroleum marketing companies under the PLI scheme for manufacturing greenfield tank farms without legacy SCADA infrastructure. Cloud-native monitoring platforms find openings where brownfield integration friction does not exist. Reliance Industries' Jamnagar complex represents early deployment of predictive analytics for inventory optimization.
Global Remote Tank Monitoring System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and integration depth. The market structures around three tiers: full-platform automation vendors with SCADA heritage, specialized instrumentation suppliers with sensor-only focus, and emerging IoT-native platforms without legacy protocol baggage. Strategic archetypes include SIL-certified industrial specialists, edge-computing architects, and cloud-native subscription providers. Dominant competitive moves encompass predictive analytics suite expansion and geographic footprint extension into PLI-driven Indian chemical parks.
Within the industrial automation tier, Emerson Electric Co., Schneider Electric SE, and Siemens AG exemplify divergent architectural bets. Emerson leverages its automation heritage to anchor high-margin contracts requiring hazardous area certifications. Schneider competes through edge-computing architectures that process data locally before cloud transmission. Siemens dominates European municipal water authority tenders through integrated SCADA compatibility and legacy protocol support. These three occupy positions across the premium-to-standard spectrum without overlapping core customer profiles.
| Leading Market Players |
|---|
| Otodata |
| Anova |
| Emerson Electric |
| Schneider Electric |
| Honeywell International |
| Siemens |
| SkyBitz |
| Banner Engineering |
| Endress+Hauser |
| Others |
Supply & Pricing Matrix
EPA SPCC compliance deadlines for continuous level monitoring are forcing fuel distributors to specify SIL-certified instrumentation regardless of cost premium, compelling supply chains to prioritize certified component sourcing over generic alternatives and compressing margins for uncertified suppliers.
Pricing Analysis
Value-based pricing anchored to avoided spill costs and automated replenishment savings dominates premium contracts with integrated oil companies. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified radar systems from ultrasonic alternatives and basic pressure transmitters. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from Asian contract manufacturers flooding commodity sensor segments. Municipal water authorities exhibit highest price sensitivity, while pharmaceutical quality assurance departments demonstrate lowest sensitivity due to validation requirements.
Supply Chain Analysis
Dual-sourcing requirements from oil and gas operators mandate multi-supplier qualification for critical instrumentation, fragmenting component procurement across Germany, China, and the United States for radar modules, telemetry units, and sensor housings. Supply chains draw from Taiwanese semiconductor foundries for LPWAN chipsets, German precision engineering for radar signal processors, and Chinese contract manufacturers for ultrasonic transducers. Single-source vulnerability concentrates in patented FMCW radar algorithms. Distribution runs through industrial automation distributors and direct OEM relationships with terminal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around SIL-certified radar instrumentation are propping pricing power for qualified vendors, as eighteen-to-twenty-four-month validation cycles create structural bottlenecks that outstrip near-term capacity expansion.
For Market Incumbents: Acquire predictive analytics software capabilities to defend attach rates against standalone sensor commoditization. Incumbents should anchor cloud-native platform contracts with Indian petroleum marketing companies greenfielding tank farms without legacy SCADA, while reinforcing certification investment in hazardous area instrumentation to maintain premium positioning against emerging IoT-native entrants. For New Entrants and Emerging Players: Enter via municipal water authority digitization tenders in Italy and Spain where aging infrastructure demands SCADA-compatible pressure-level monitoring without incumbent lock-in. New entrants should target pharmaceutical cold chain applications requiring redundant temperature telemetry, leveraging subscription-based pricing to bypass capital procurement cycles at smaller food processors. For Investors and Strategic Acquirers: Re-rating potential sits with edge-computing architecture specialists given Schneider Electric's demonstrated traction in latency-critical leak detection applications. Long-term viability over the next decade favors vendors with backward integration into sensor manufacturing and captive LPWAN module supply. Investors should monitor MEE enforcement intensity in Jiangsu province as inflection indicator for domestic Chinese sensor manufacturer valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of radar modules insulates Emerson and Endress+Hauser from Taiwanese chipset allocation constraints. |
| Predictive Analytics Suite Expansion | Integrated oil companies in the United States evaluate tank monitoring within enterprise digital transformation programs. |
| Geographic Expansion into Indian Chemical Parks | PLI scheme greenfield tank farms lack legacy SCADA, creating openings for cloud-native platform vendors. |
| Long-term Service Contract Unbundling | Chemical manufacturers are separating hardware procurement from multi-year monitoring subscriptions, compressing switching costs. |
| Joint Venture for MEE-Compliant Data Interfaces | Domestic Chinese manufacturers capture share by offering provincial reporting integration as standard configuration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers at chemical manufacturers, procurement leads at petroleum terminals, SCADA integration specialists, and aftermarket service heads at industrial automation distributors. EPA SPCC rulemaking documents, ECHA REACH substance restriction databases, China's MEE environmental monitoring mandates, and SEC 10-K instrumentation disclosures provided regulatory and financial validation. Bottom-up tank deployment estimates triangulated against top-down automation spending forecasts.
Granularity-level modeling disaggregated volume and value across sensor type, connectivity technology, application regulatory stringency, and end-user automation maturity throughout the projection horizon. CAGRs derived from segment-level growth rate synthesis weighted by installed base evolution and replacement cycle timing. Forecast inputs incorporated cellular LPWAN module cost trajectories, SIL certification queue lengths, and municipal water authority tender pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in EPA enforcement intensity or MEE data localization requirements. Deviation in REACH substance restriction scope would shift chemical storage monitoring demand materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Beacon Technology Market
Sensors
Connected Smart Thermostats Market
Sensors
Industrial Barcode Scanners Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Alcohol Sensor Market
Sensors
Asia Pacific RFID Market
Sensors
Gesture Recognition in Retail Market
Sensors
Cloud Camera Market
Sensors
Automated Weather Observation System Market
Sensors
Smart Beacon Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Handheld RFID Readers Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Mobile Mapping Systems Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Global Weather Monitoring Solutions and Services Market