
 Lidar in Mapping Market | 2026-2036
Lidar in Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Lidar in Mapping Market Analysis
Utility operators and environmental consultants is rotating toward mobile and terrestrial lidar platforms for corridor mapping and flood modeling. Teledyne Technologies leverages its airborne sensor portfolio to dominate government survey contracts. Hexagon AB anchors its position through integrated software-hardware workflows for geospatial data processing. RIEGL Laser Measurement Systems specializes in long-range waveform digitizing instruments for topographic applications.
Lidar in mapping denotes active remote sensing systems that emit pulsed laser light to measure distances and generate dense three-dimensional point clouds with centimeter-level accuracy. These systems capture elevation data across terrain, structures, and vegetation canopies to produce digital elevation models and classified surface products for engineering and planning decisions. Airborne lidar leads revenue contribution due to its established role in national mapping programs and large-area corridor surveys. Mobile lidar represents the fastest-expanding category as municipalities deploy vehicle-mounted systems for street-level asset inventory and urban digital twin construction. Terrestrial lidar occupies a mature niche in high-precision engineering surveys where static scanning preserves millimeter accuracy for structural monitoring.
The United States Federal Aviation Administration regulates commercial airborne lidar operations through Part 107 unmanned aircraft standards and waivers for beyond-visual-line-of-sight missions. The European Union's INSPIRE directive mandates interoperable geospatial data infrastructure, compelling member states to adopt standardized lidar-derived elevation products for environmental reporting. China's Ministry of Natural Resources enforces national basic surveying and mapping regulations that require licensed operators and calibrated instruments for cadastral updates. Stakeholders must monitor evolving unmanned aerial system rules and data sovereignty requirements as procurement shifts toward real-time, cloud-processed point cloud delivery.
Market Dynamics
Government mandates for high-resolution terrain data under the EU Green Deal and national emissions frameworks are concentrating procurement authority within federal survey agencies, compressing vendor selection cycles and elevating software-hardware integration requirements.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and companion national emissions frameworks compel member states to procure centimeter-accuracy elevation data for carbon accounting and land-use compliance verification.
- Mobile lidar platforms:Municipalities across Germany, the United States, and China are deploying vehicle-mounted systems for street-level asset inventory and urban digital twin construction at accelerating pace.
- Flood-risk infrastructure modernization:Cadastral system upgrades in flood-prone regions are driving repeat survey contracts for terrain monitoring and hydraulic modeling applications.
Market Restraints
- Sensor cost volatility:Precision laser emitter and photodetector components face supply concentration among specialized Japanese and German optics manufacturers, creating input cost instability.
- Regulatory fragmentation:Divergent unmanned aerial system certification requirements between the FAA's Part 107 framework and China's Ministry of Natural Resources licensing rules generate cross-border operational friction.
- Photogrammetry substitution:Advances in multi-view stereo reconstruction from high-resolution satellite imagery present lower-cost alternatives for coarse-resolution terrain mapping in vegetation-sparse regions.
Strategic Opportunities
- Real-time cloud processing:Edge-computing architectures and 5G backhaul are enabling streaming point cloud delivery, opening subscription-based service models for municipal planning departments.
- Carbon credit verification:Forestry carbon offset programs in Brazil and Indonesia require biomass quantification that waveform lidar uniquely provides, creating new demand geography outside traditional survey markets.
- INSPIRE directive expansion:The EU's interoperable geospatial data infrastructure mandate is extending beyond elevation products to full 3D building models, widening the addressable data product scope.
Industry Challenges
- Geospatial data scientist shortage:The specialized skillset combining point cloud classification, coordinate reference system transformation, and machine learning feature extraction faces acute labor market scarcity.
- Legacy CAD integration:Engineering firms operating established Autodesk and Bentley design workflows encounter friction importing dense lidar point clouds into parametric modeling environments without data thinning.
- Calibration protocol complexity:Maintaining traceable accuracy for long-range waveform digitizing instruments requires periodic laboratory calibration against certified reference targets, extending equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidar in Mapping Market |
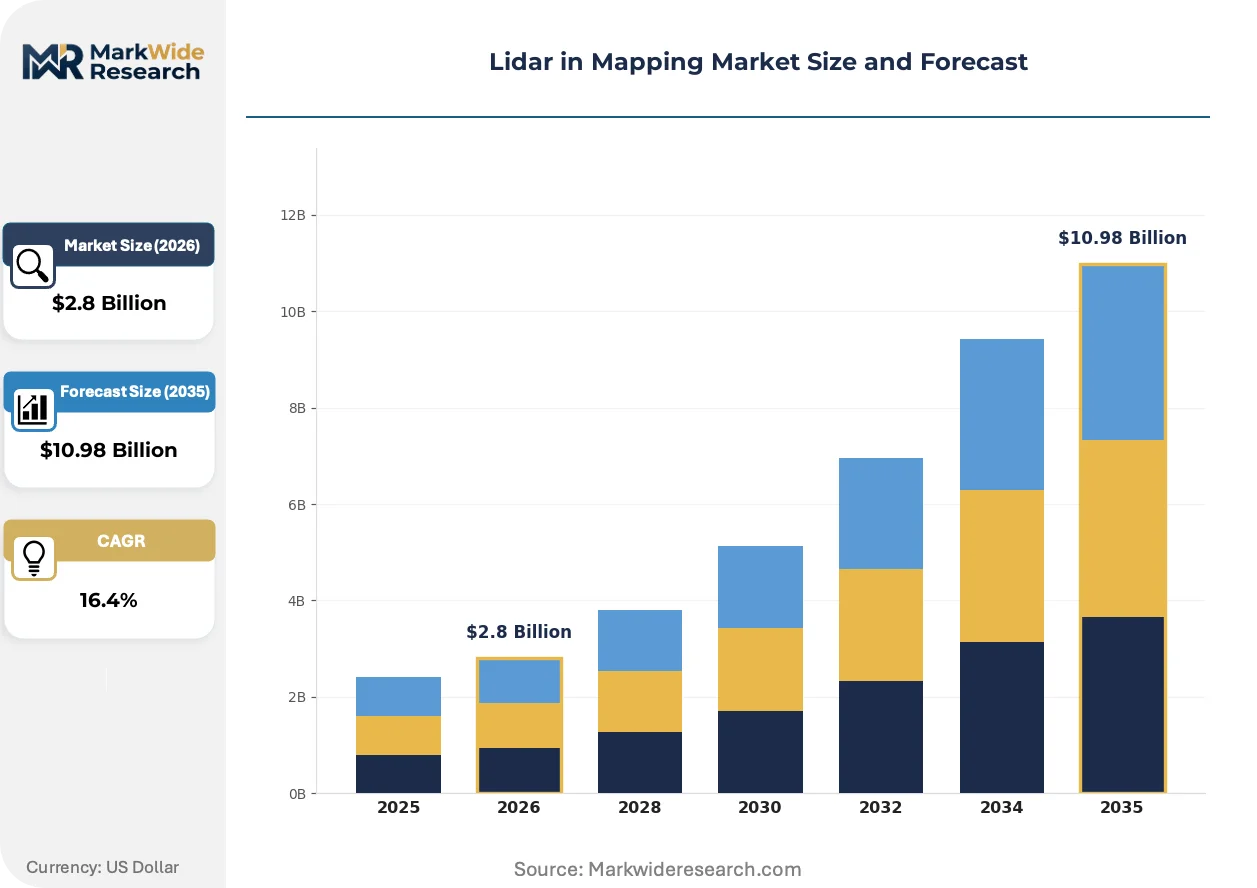
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Lidar, Terrestrial Lidar, Mobile Lidar, Satellite Lidar Technology: Time-of-Flight, Phase-Shift, Frequency Modulated Continuous Wave, Geiger-Mode Application: Topographic Mapping, Vegetation Analysis, Urban Planning, Forestry Management End User: Government Agencies, Construction Firms, Environmental Consultants, Research Institutions |
| Companies Covered | Teledyne Technologies, Hexagon AB, Trimble Inc., RIEGL Laser Measurement Systems, Leica Geosystems, Fugro, Topcon Corporation, Velodyne Lidar, FARO Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidar in Mapping Market Emerging Trajectories
Waveform digitizing technology and AI-assisted point cloud classification are compressing data processing timelines while regulatory data-sharing mandates are forcing interoperability investments across previously siloed national survey systems.
Solid-state MEMS lidar architectures are supplanting mechanical spinning assemblies in mobile mapping platforms. Municipal fleet operators in the United States and Germany are adopting these units for continuous streetscape capture at reduced maintenance burden. The shift is compressing hardware replacement cycles from seven years to three while elevating software licensing revenue share in vendor income statements.
China's Ministry of Natural Resources revised national basic surveying regulations now mandate calibrated instrument deployment and licensed operator certification for all cadastral update contracts. The rules exclude uncertified drone service providers from government procurement pools. Provincial bureaus in Guangdong and Jiangsu are responding by consolidating vendor qualification panels around established equipment manufacturers with in-country service infrastructure.
Subscription-based data-as-a-service contracts are displacing perpetual license sales for point cloud processing software. European environmental consultancies and North American utility operators now prefer annual telemetry fees bundled with cloud storage and automated feature extraction. Germany's federal mapping agency and comparable state-level authorities in California represent the most advanced adopters of this procurement model.
Lidar in Mapping Market Segmentation
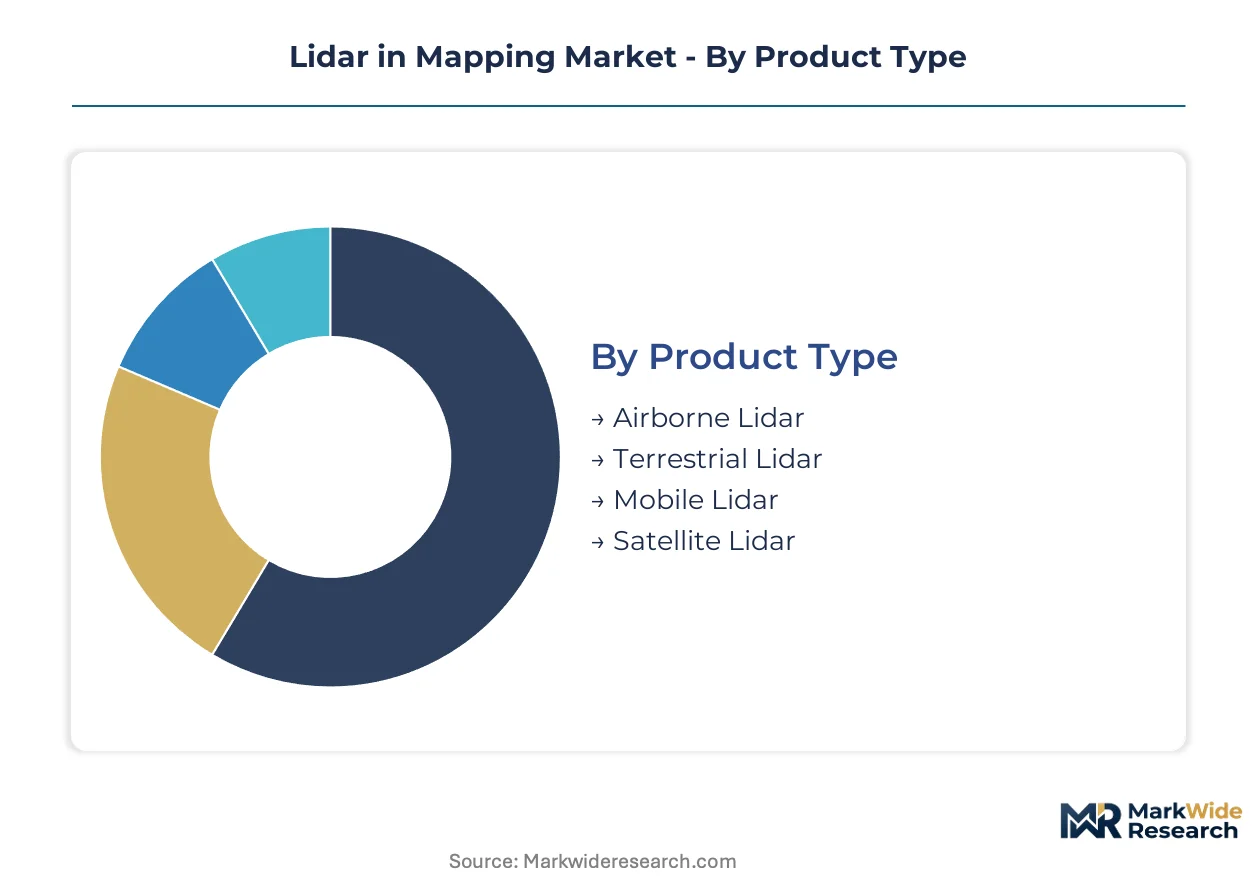
Segmentation reveals how procurement authority concentrates in government survey agencies while technology choices diverge between precision-demanding cadastral work and speed-oriented mobile applications. Understanding these splits exposes where vendor integration requirements tighten and where subscription service models gain traction.
Product Type:
Airborne systems dominate government export contracts from Germany and the United States, while mobile platforms spread through municipal domestic fleets in China and North America.
- Airborne Lidar:Pulsed laser systems mounted on crewed aircraft or large UAVs capture swath coverage across hundreds of square kilometers per flight hour. Procurement concentrates in Germany's federal mapping agency and comparable state-level authorities in California for national elevation model maintenance and flood-risk corridor surveys.
- Mobile Lidar:Vehicle-mounted solid-state MEMS architectures enable continuous streetscape capture at highway speeds. Municipal fleet operators in the United States and Germany are deploying these units for urban digital twin construction and roadside asset inventory, compressing hardware replacement cycles from seven years to three.
- Terrestrial Lidar:Static tripod-based scanners preserve millimeter accuracy for structural monitoring and high-precision engineering surveys.
- Satellite Lidar:Spaceborne altimetry missions provide coarse global coverage for ice sheet monitoring and large-scale geodynamic studies.
Airborne Lidar holds the largest share; momentum sits with Mobile Lidar.
Technology:
Cost tiers separate long-range waveform digitizing instruments for federal contracts from compact phase-shift units serving municipal budgets.
- Time-of-Flight:Direct measurement of laser pulse round-trip time dominates airborne and terrestrial platforms. German and Japanese optics manufacturers supply precision emitters and photodetectors for government survey contracts demanding centimeter-level accuracy across extended ranges.
- Geiger-Mode:Single-photon-sensitive arrays enable detection from orbital altitudes and high-altitude aircraft. NASA and European Space Agency missions drive specialized procurement for atmospheric and topographic science applications.
- Phase-Shift:Interferometric distance measurement supports short-range mobile and indoor mapping at reduced component cost.
- Frequency Modulated Continuous Wave:Coherent detection architectures promise chip-scale integration for automotive-derived mobile mapping units.
Time-of-Flight commands the dominant installed base; Geiger-Mode is climbing the fastest.
Application:
Volume concentrates in regulatory-mandated terrain data programs while customer type determines margin structure.
- Topographic Mapping:National elevation model production and cadastral boundary surveys constitute the foundational revenue pool. The EU Green Deal and companion emissions frameworks compel member states to procure high-resolution terrain data for carbon accounting compliance.
- Urban Planning:Street-level asset inventory and 3D building model construction for digital twin platforms represent the steepest expansion trajectory. Municipalities across Germany, the United States, and China are accelerating vehicle-mounted system deployment.
- Vegetation Analysis:Waveform lidar biomass quantification serves forestry carbon offset verification in Brazil and Indonesia.
- Forestry Management:Canopy structure mapping supports sustainable harvest planning and wildfire risk assessment.
Topographic Mapping holds the largest share; Urban Planning is gaining share fastest.
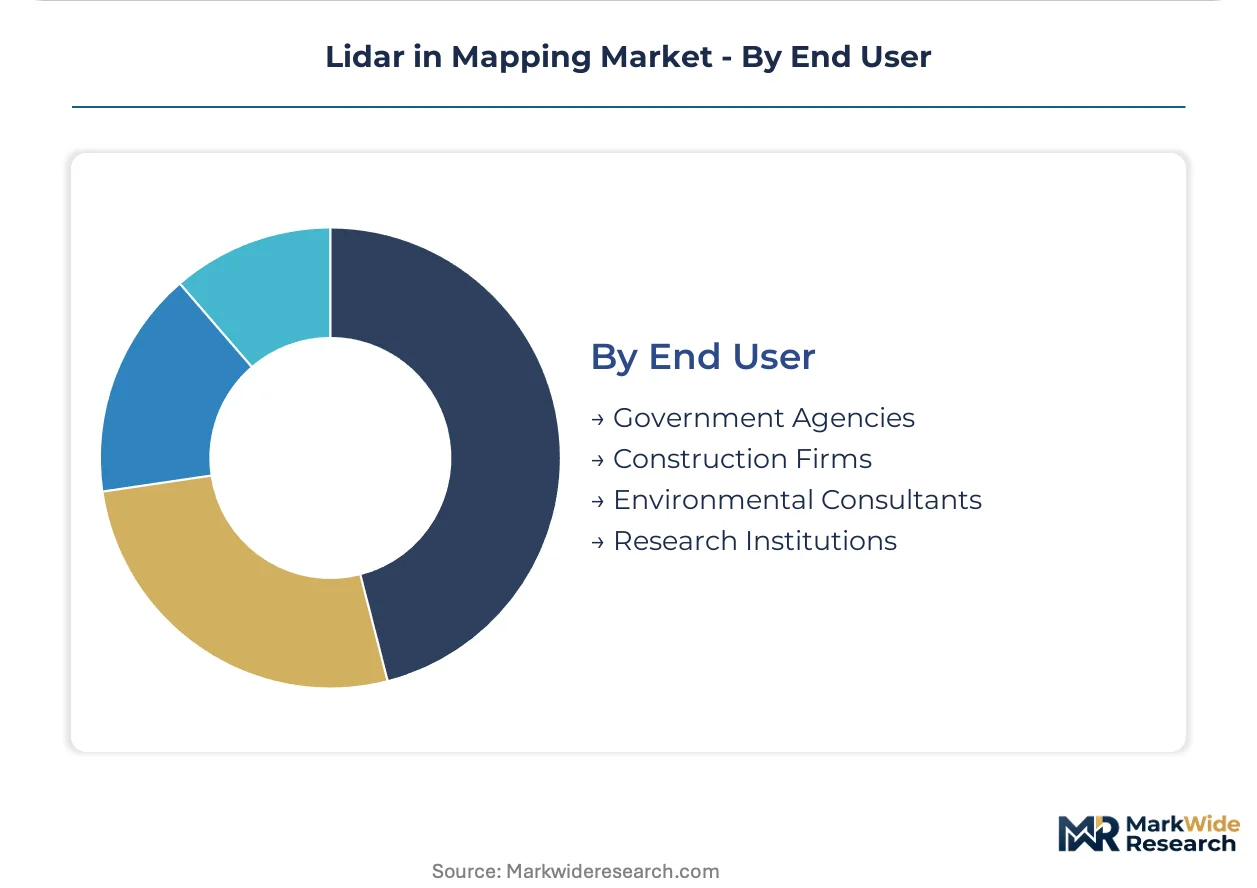
End User:
Supply concentration favors established manufacturers with in-country service infrastructure as procurement rules tighten.
- Government Agencies:Federal survey authorities in Germany, the United States, and China concentrate procurement volume for national mapping programs. China's Ministry of Natural Resources now mandates calibrated instruments and licensed operators, excluding uncertified providers from government contracts.
- Environmental Consultants:European and North American firms are shifting toward subscription-based data-as-a-service contracts for point cloud processing and automated feature extraction.
- Construction Firms:Engineering contractors import dense point clouds into Autodesk and Bentley workflows for earthwork quantification and clash detection.
- Research Institutions:Universities and national laboratories operate specialized waveform digitizing instruments for algorithm development and calibration protocol research.
Government Agencies hold the largest share; Environmental Consultants show the steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor anchors European lidar procurement for cross-border infrastructure monitoring, while the Trans-Eurasian rail belt drives Central Asian survey demand. Federal mapping agencies in Germany, the United States, and China concentrate contract volume for national elevation programs.
Germany
Federal highway digitization and flood-risk corridor surveys dominate procurement volume. The EU Green Deal mandates centimeter-accuracy terrain data for carbon accounting compliance across member states. Bavaria's federal mapping agency maintains Europe's densest national elevation model update cycle.
United States
FEMA flood map modernization and utility corridor surveys drive repeat contract structures. The FAA's Part 107 framework regulates commercial airborne lidar operations through unmanned aircraft standards and beyond-visual-line-of-sight waivers. California's state-level authorities represent the most advanced adopters of subscription-based point cloud processing models.
China
Cadastral system modernization and urban digital twin construction concentrate demand in coastal provinces. The Ministry of Natural Resources enforces licensed operator certification and calibrated instrument deployment for all government contracts. Provincial bureaus in Guangdong and Jiangsu consolidate vendor qualification panels around established equipment manufacturers with in-country service infrastructure.
Japan
Seismic risk assessment and infrastructure resilience planning sustain terrestrial lidar demand. METI standards govern precision measurement instrument calibration protocols for public works applications. Tokyo's metropolitan government deploys mobile mapping systems for underground utility inventory and flood simulation modeling.
Australia
Mining rehabilitation compliance and coastal erosion monitoring drive government survey contracts. The national geospatial data infrastructure mandates interoperable elevation products for environmental reporting across state jurisdictions. Western Australia's mining belt represents the densest concentration of long-range waveform digitizing instruments for pit slope monitoring.
Lidar in Mapping Market Vendor Landscape
Concentration sits with integrated sensor-software providers serving federal procurement channels. Three archetypes dominate: airborne system specialists with government export credentials, mobile platform vendors leveraging solid-state MEMS architectures, and terrestrial instrument manufacturers preserving millimeter accuracy for engineering applications. Competitive moves center on cloud-processing service model transitions and in-country certification infrastructure investments.
Within the integrated hardware-software tier, Teledyne Technologies, Hexagon AB, and RIEGL Laser Measurement Systems exemplify divergent positioning strategies. Teledyne leverages its airborne sensor portfolio to anchor government survey contracts. Hexagon AB occupies a position through integrated software-hardware workflows for geospatial data processing. RIEGL represents the precision-specialist archetype with long-range waveform digitizing instruments for topographic applications.
| Leading Market Players |
|---|
| Teledyne Technologies |
| Hexagon AB |
| Trimble Inc. |
| RIEGL Laser Measurement Systems |
| Leica Geosystems |
| Fugro |
| Topcon Corporation |
| Velodyne Lidar |
| FARO Technologies |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month lead times for precision laser emitters and photodetector assemblies concentrate pricing power among specialized Japanese and German optics manufacturers, compressing margins for airborne system integrators while elevating software licensing revenue share in vendor income statements.
Pricing Analysis
Volume-discount tiering structures separate federal survey agency procurement pools from municipal fleet operators and environmental consultancy subscriptions. Three-tier pricing stratifies across waveform-digitizing precision instruments, solid-state MEMS mobile units, and compact phase-shift terrestrial scanners. Cost compression in solid-state architectures stems from automotive-derived manufacturing scale. Municipal planning departments exhibit highest price sensitivity due to constrained capital budgets, while federal mapping agencies prioritize traceable accuracy and calibration certification over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and Japanese precision optics suppliers buffering against rare-earth element and specialized semiconductor feedstock volatility. Component sourcing draws from Japan, Germany, and the United States for precision emitters, photodetectors, and waveform digitizing ASICs. Single-source vulnerability concentrates in long-range laser diode fabrication. Distribution runs through authorized equipment manufacturers with in-country calibration laboratories and certified service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-processed point cloud delivery and automated feature extraction subscriptions are expanding faster than hardware unit sales, transforming procurement from capital expenditure to operational expenditure models across municipal and consultancy segments.
For Market Incumbents: Secure in-country calibration certification infrastructure to maintain government procurement eligibility under China's Ministry of Natural Resources licensing rules and comparable EU member state qualification panels. Deepen backward integration into precision photodetector supply to buffer Japanese optics manufacturer pricing power. Anchor subscription service attach rates through edge-computing architecture deployment.
For New Entrants and Emerging Players: Carbon credit verification service gaps in Brazil and Indonesia present white-space opportunities where waveform lidar biomass quantification demand outpaces established vendor presence. Target forestry carbon offset program administrators with portable terrestrial scanning units bundled with automated canopy classification software. Pursue partnership routes with environmental consultancies already holding carbon project developer credentials.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because terrain data mandates under the EU Green Deal and national emissions frameworks institutionalize repeat procurement cycles. Acquisition candidates combine hardware-software integration with existing federal survey agency contract relationships. Monitor INSPIRE directive expansion timelines as inflection indicators for 3D building model addressable market widening.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Cloud Processing Deployment | Enables subscription revenue models for municipal planning departments in Germany and California. |
| In-Country Calibration Infrastructure Investment | Satisfies China's Ministry of Natural Resources licensing requirements for government contract eligibility. |
| Carbon Credit Verification Service Launch | Captures forestry offset program demand in Brazil and Indonesia outside traditional survey markets. |
| Solid-State MEMS Architecture Adoption | Compresses hardware replacement cycles from seven years to three for municipal fleet operators. |
| INSPIRE-Compliant 3D Building Model Development | Extends addressable scope beyond elevation products to full urban digital twin construction. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across federal survey agency procurement officers, municipal fleet managers, environmental consultancy project directors, and geospatial software engineering leads. Secondary validation incorporated EU INSPIRE directive implementation reports, FAA Part 107 waiver filings, China's Ministry of Natural Resources licensing bulletins, and national mapping program budget disclosures. Bottom-up equipment shipment tracking and top-down government contract value aggregation were triangulated against vendor-reported segment revenue allocations.
Across the analysis window, projections model product type segmentation across airborne, mobile, terrestrial, and satellite platforms; technology tiers spanning time-of-flight, Geiger-mode, phase-shift, and frequency modulated continuous wave architectures; and end-user splits between government agencies, environmental consultants, construction firms, and research institutions. CAGRs derive from equipment replacement cycle compression observations and subscription service attach rate trajectories. Forecast inputs incorporate unmanned aerial system regulatory evolution pace and carbon accounting mandate implementation timelines.
Underlying assumptions cover sustained EU Green Deal enforcement continuity and China cadastral modernization funding stability, with deviation risk concentrated in unmanned aerial system certification harmonization failures between FAA and Ministry of Natural Resources frameworks. Revision becomes warranted when photodetector component supply concentration triggers sustained input cost volatility exceeding historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Conveyor Monitoring Market
Sensors
2D Barcode Reader Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Facial Tracking Solution Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Robot Sensor Market
Sensors
RFID Smart Cabinet Market
Sensors
IO-Link Technology Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Refrigeration Monitoring Market