
 North America and Europe IoT Gateway Market | 2026-2036
North America and Europe IoT Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe IoT Gateway Market Analytics
The EU Cybersecurity Act is hardening the cost-of-entry calculus for gateway vendors seeking CE marking approval across European member states. Cisco Systems Inc. leverages its established certification infrastructure to sustain market presence in regulated European verticals. Dell Technologies Inc. anchors its competitive stance through in-house server-to-edge integration capabilities. NXP Semiconductors N.V. differentiates via dedicated automotive-grade silicon portfolios purpose-built for gateway edge compute.
An IoT gateway functions as a network bridge device that aggregates sensor data from heterogeneous endpoints, typically supporting protocol translation across Wi-Fi, Zigbee, Bluetooth, and cellular interfaces while executing local preprocessing at throughput rates exceeding one gigabit per second. Its primary commercial purpose centers on enabling secure bidirectional data flow between operational technology floors and enterprise cloud architectures. Edge Gateways capture expanding margin pools as manufacturing clients demand sub-ten-millisecond latency for predictive maintenance workloads. Industrial Automation end users represent the dominant deployment category, while Smart Home applications show accelerating traction among North American utility providers rolling out managed services programs.
The U.S. Federal Communications Commission governs spectrum allocation and device authorization for cellular and Wi-Fi gateway modules, while the European Telecommunications Standards Institute coordinates cross-border interoperability mandates. Germany's Federal Office for Information Security operates country-specific certification schemes that extend product validation timelines. Stakeholders must monitor evolving NIS2 implementation timelines across EU member states and calibrate certification roadmaps accordingly.
Market Dynamics
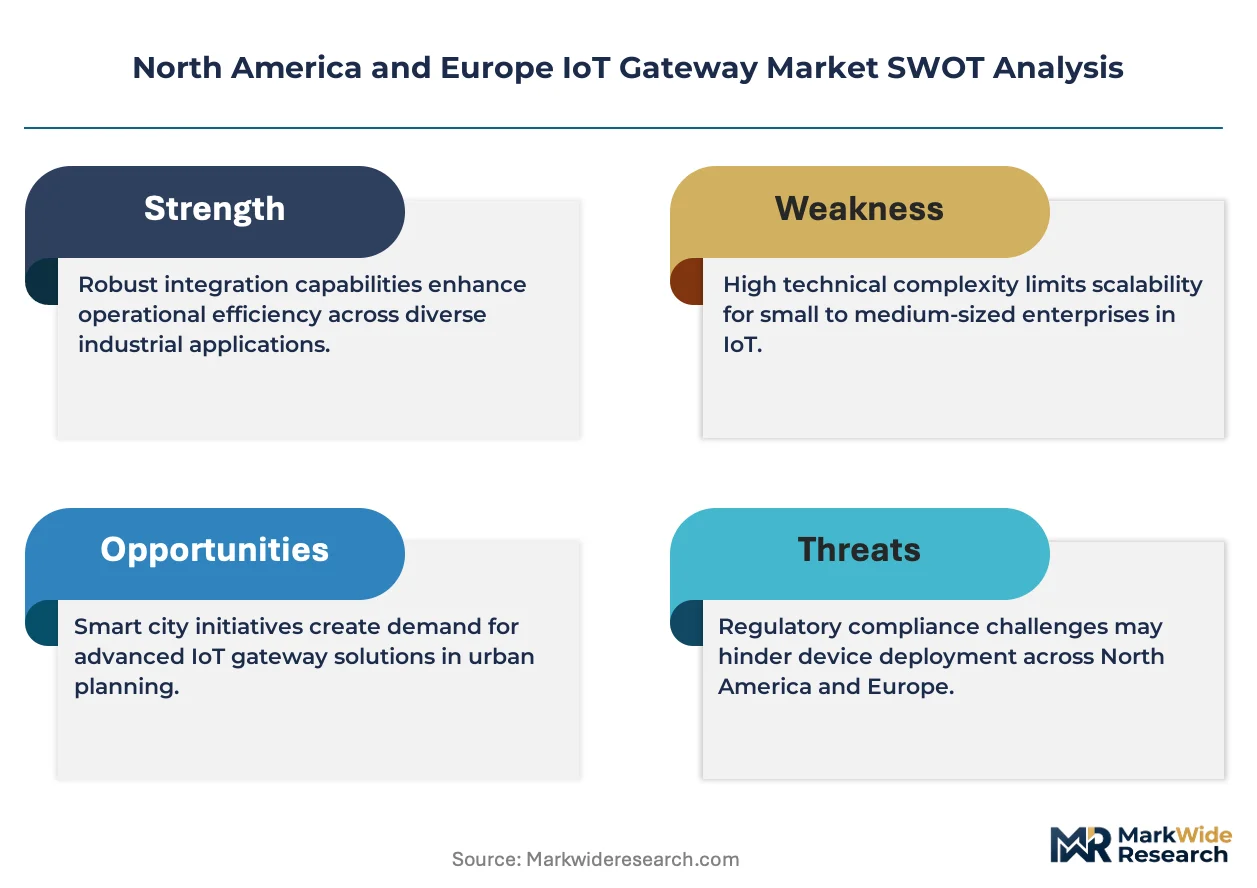
The EU Cybersecurity Act and NIS2 Directive are hardening certification requirements for IoT gateway vendors, extending validation timelines and elevating compliance costs for market entry across European member states.
Growth Catalysts
- Edge Compute Integration:Manufacturing floors in Germany's automotive corridor demand sub-ten-millisecond latency for predictive maintenance workloads, pulling high-throughput gateway deployments.
- Managed Services Programs:North American utility providers are bundling gateway hardware with subscription-based monitoring, creating recurring revenue anchors for equipment vendors.
- NIS2 Implementation:The directive's mandatory security baseline for critical infrastructure operators is forcing replacement cycles of legacy gateway installations across EU member states.
Market Restraints
- Silicon Supply Concentration:Automotive-grade SoC fabrication concentrates in East Asian foundries, exposing gateway vendors to lead-time volatility for edge-capable chipsets.
- Certification Timeline Friction:Germany's Federal Office for Information Security operates country-specific validation schemes that add quarters to product launch schedules.
- Protocol Fragmentation:Persistent incompatibility between Zigbee, Thread, and proprietary industrial fieldbus standards forces redundant hardware SKUs and inventory complexity.
Strategic Opportunities
- CE Marking Acceleration:Vendors with pre-established EU cybersecurity certification infrastructure can capture share as competitors face NIS2 compliance gaps.
- Smart Home Energy Management:Untapped deployment potential exists among European municipal utilities rolling out demand-response programs requiring residential gateway endpoints.
- Server-to-Edge Integration:Convergence of on-premise server management with distributed gateway orchestration creates margin pools for vendors with unified software stacks.
Industry Challenges
- Embedded Security Engineering Talent:Shortage of firmware developers with hardware-level cryptography expertise delays secure boot and trusted execution environment implementations.
- Legacy OT Integration:Brownfield manufacturing environments running decades-old SCADA architectures require costly protocol translation layers and field engineering customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe IoT Gateway Market |
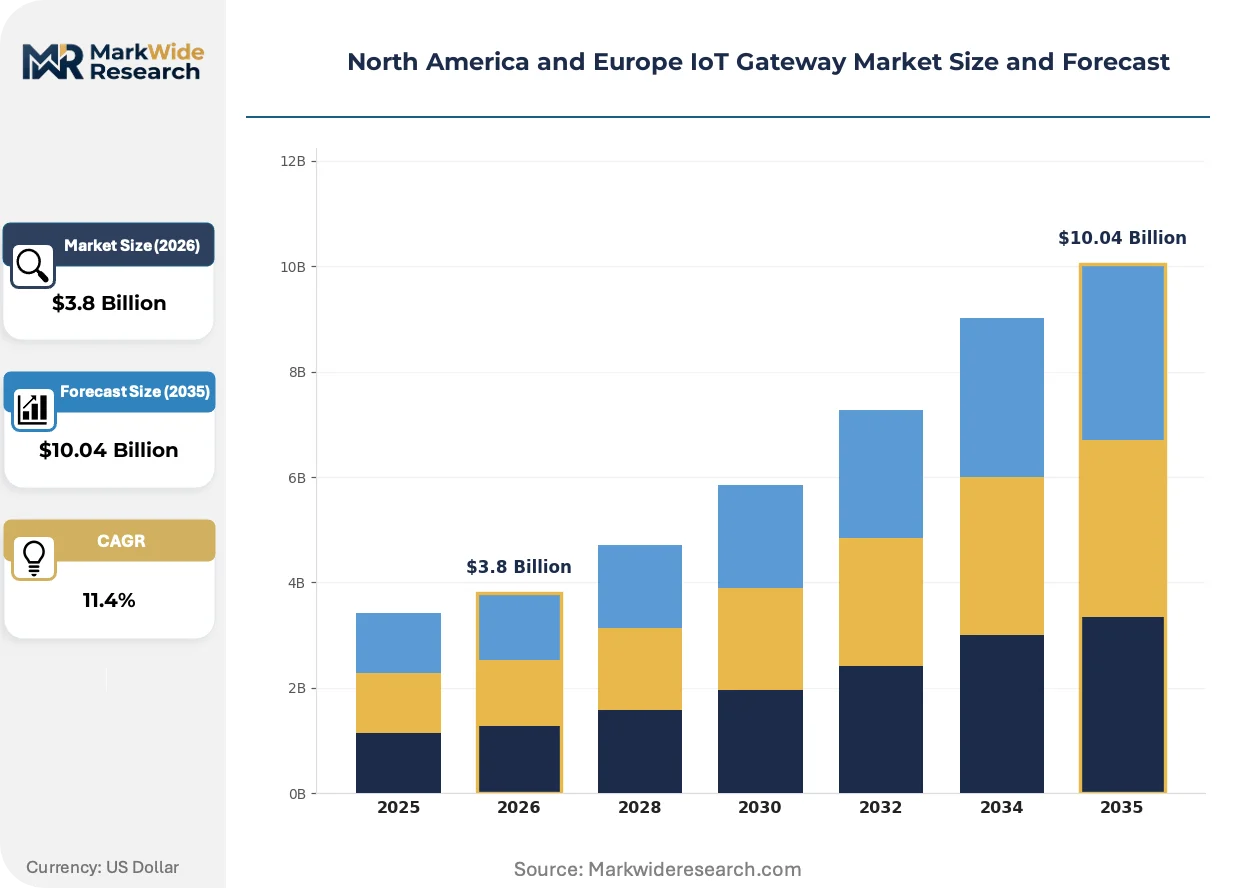
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Gateways, Gateway Hardware, Software Gateways, Edge Gateways End User: Smart Home, Industrial Automation, Healthcare, Transportation Technology: Wi-Fi, Zigbee, Bluetooth, Cellular Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems Inc., Advantech Co. Ltd, Dell Technologies Inc., Microchip Technology Inc., Intel Corporation, Huawei Technologies Co. Ltd, NXP Semiconductors N.V., Texas Instruments Incorporated, STMicroelectronics N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe IoT Gateway Market Evolving Landscape
Containerized edge runtime environments are reshaping how industrial buyers evaluate gateway procurement, shifting selection criteria from hardware specifications toward software orchestration compatibility and lifecycle management capabilities.
ARM-based system-on-chip architectures with dedicated neural processing units are overtaking x86 alternatives for vision-inference workloads at the edge. Automotive inspection lines in Stuttgart and Detroit are deploying these chipsets for real-time defect detection. The transition is compressing price-performance benchmarks for gateway hardware and favoring semiconductor vendors with integrated AI accelerators.
The EU Cybersecurity Act's Common Criteria certification framework is mandating formal security evaluation for gateway products targeting critical infrastructure sectors. Industrial automation vendors in Germany must now budget additional engineering cycles for evaluation facility engagement. This regulatory layer is advantaging incumbent suppliers with existing certification infrastructure over new market entrants.
Buyers in the U.S. Great Lakes industrial belt are consolidating vendor relationships and demanding multi-year total-cost-of-ownership contracts that bundle hardware, software licenses, and field support. Equipment distributors are responding by building in-house technical service capabilities rather than pure resale margins. This behavioral shift is visible most acutely among tier-one automotive suppliers operating just-in-time manufacturing networks.
North America and Europe IoT Gateway Market Segmentation
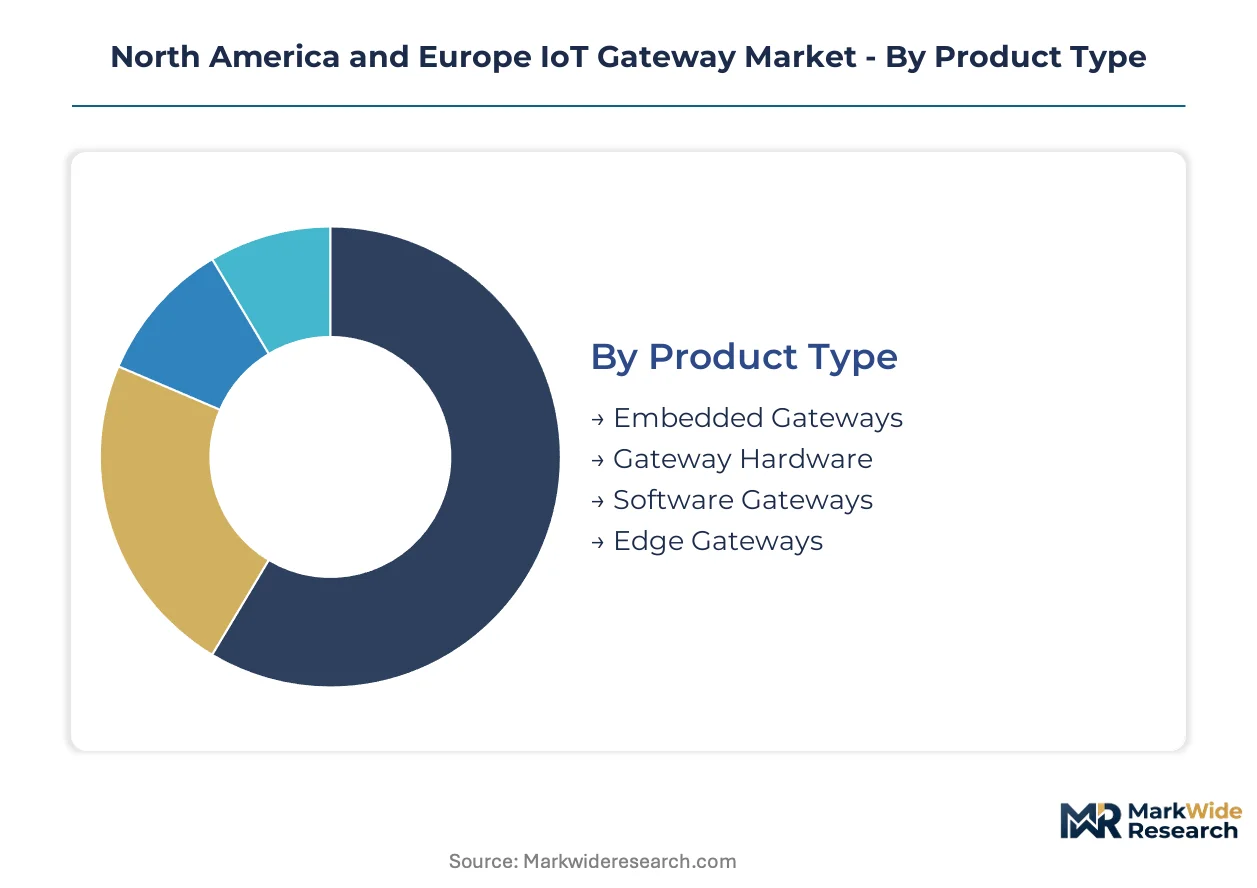
Gateway procurement patterns diverge sharply across product architectures and deployment models. Capital allocation decisions hinge on latency requirements, regulatory exposure, and integration complexity with legacy operational technology stacks.
Product Type:
Edge Gateways command the steepest upfront engineering investment due to dedicated neural processing units and automotive-grade thermal management. Embedded Gateways require substantial firmware development cycles for secure boot implementations.
- Edge Gateways:ARM-based system-on-chip architectures with integrated AI accelerators handle vision-inference workloads at sub-ten-millisecond latency. Germany's automotive manufacturing corridor in Stuttgart and Detroit's inspection lines pull these deployments for real-time defect detection, with NIS2 compliance adding validation overhead.
- Embedded Gateways:Compact form-factor devices with hardware-level cryptography and trusted execution environments serve space-constrained industrial controllers. Brownfield manufacturing environments across the U.S. Great Lakes belt demand these for protocol translation with decades-old SCADA architectures, though embedded security engineering talent scarcity extends development timelines.
- Gateway Hardware:Rack-mount and DIN-rail chassis with multi-protocol radio modules for facility-wide aggregation.
- Software Gateways:Virtualized network functions running on standard compute infrastructure with containerized edge runtime support.
Edge Gateways absorb the bulk of installed capacity in high-throughput manufacturing; Software Gateways are expanding most quickly as container orchestration matures.
End User:
Industrial Automation generates the most complex procurement specifications, with buyers demanding multi-year total-cost-of-ownership contracts bundling hardware, software, and field support. Smart Home deployments scale through utility-managed subscription programs with lower customization overhead.
- Industrial Automation:Predictive maintenance workloads in Germany's automotive corridor and the U.S. Great Lakes industrial belt require gateways with gigabit-plus throughput and deterministic latency. Tier-one automotive suppliers operating just-in-time networks consolidate vendor relationships and demand unified software stacks for server-to-edge orchestration.
- Smart Home:Residential endpoints for demand-response and energy management programs bundle gateway hardware with subscription-based monitoring. North American utility providers rolling out managed services programs create recurring revenue anchors, while European municipal utilities show accelerating traction for residential deployment.
- Healthcare:HIPAA-compliant gateways for medical device integration and remote patient monitoring with encrypted bidirectional data flows.
- Transportation:Fleet telematics and logistics optimization gateways with cellular backhaul and GPS positioning capabilities.
Industrial Automation dominates current gateway shipments; Smart Home represents the steepest expansion trajectory as utility-managed programs proliferate.
Technology:
Cellular modules carry the highest certification burden across FCC and ETSI frameworks, with spectrum allocation governed by divergent national regimes. Wi-Fi deployments face less regulatory friction but encounter interoperability challenges in dense industrial RF environments.
- Cellular:LTE-M and 5G NR modules with carrier-authorized certification for wide-area backhaul in distributed asset monitoring. The U.S. Federal Communications Commission governs device authorization timelines, while European Telecommunications Standards Institute coordinates cross-border interoperability mandates, creating fragmented validation requirements for multi-region deployments.
- Wi-Fi:Dual-band 802.11ax implementations for high-throughput local aggregation in manufacturing floors and commercial facilities. Germany's Federal Office for Information Security operates country-specific certification schemes that extend product launch schedules, compressing margin pools for unvalidated hardware.
- Zigbee:Mesh networking for low-power sensor aggregation in building automation and residential energy management.
- Bluetooth:Short-range connectivity for wearable integration and proximity-based asset tracking applications.
Cellular captures the majority of wide-area deployment value; Wi-Fi is climbing the fastest as private 5G alternatives face cost barriers.
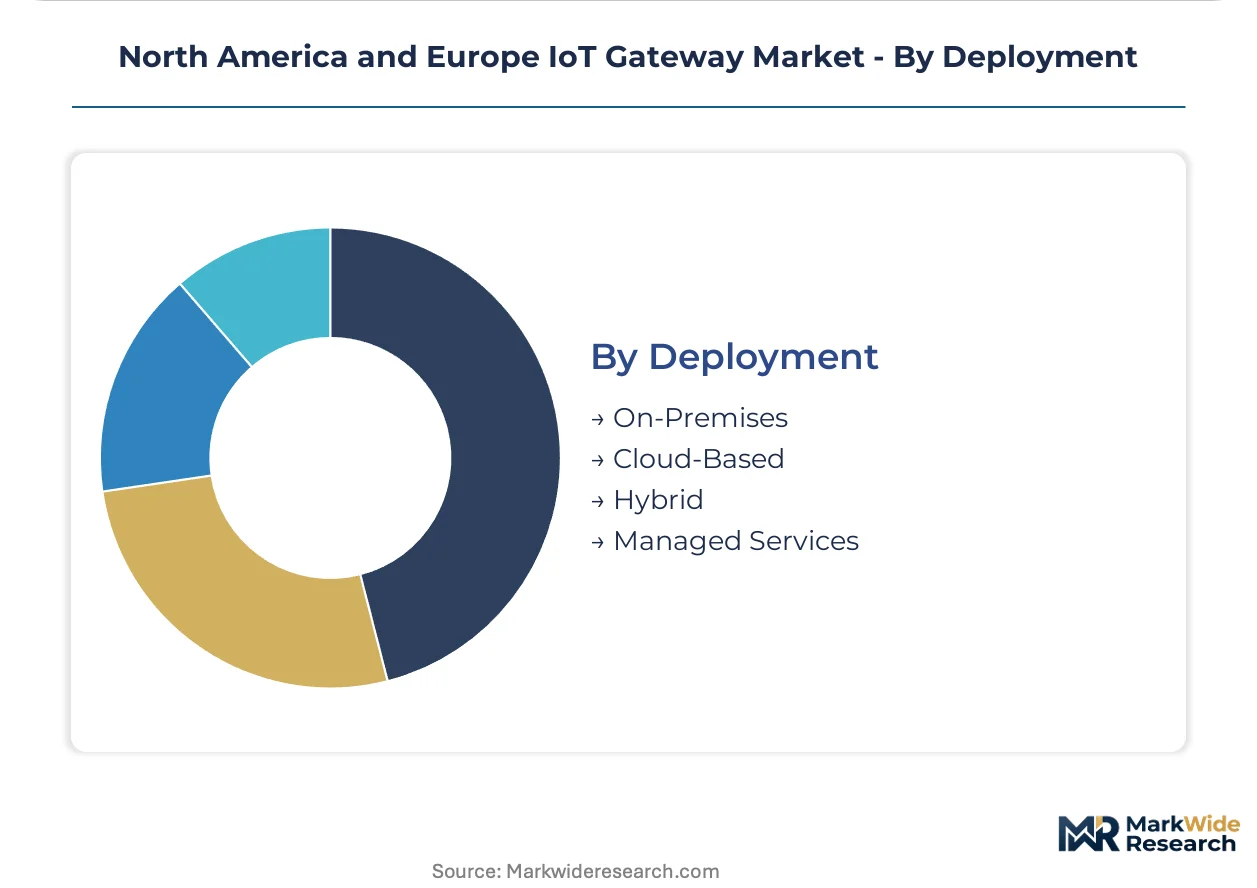
Deployment:
Managed Services programs shift capital expenditure to operational expenditure, requiring vendors to build in-house technical service capabilities rather than pure resale margins. On-Premises deployments retain the highest hardware margin capture but demand extensive field engineering.
- Managed Services:Subscription-based gateway provisioning with bundled monitoring, firmware updates, and security patch management. North American utility providers and European municipal utilities favor this model for residential Smart Home rollouts, forcing equipment distributors to develop technical service competencies.
- Hybrid:Split processing architectures with local preprocessing and cloud-based analytics for predictive maintenance workloads. Germany's automotive manufacturers deploy these configurations to satisfy EU Cybersecurity Act data residency requirements while leveraging centralized AI model training.
- On-Premises:Fully air-gapped or privately networked installations for critical infrastructure with strict operational technology isolation.
- Cloud-Based:Centralized gateway management with over-the-air configuration and telemetry aggregation.
Hybrid deployments hold the largest installed base in regulated industrial verticals; Managed Services is gaining share fastest among utility-led residential programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Opportunity Zones program and Germany's High-Tech Strategy 2025 are concentrating gateway deployment incentives in designated industrial corridors. Tax-advantaged capital flows into edge infrastructure projects accelerate procurement cycles across both jurisdictions.
United States
Utility-managed smart home programs and automotive predictive maintenance workloads drive gateway demand. The FCC governs spectrum allocation for cellular and Wi-Fi modules, extending device authorization timelines. The Great Lakes industrial belt concentrates tier-one automotive suppliers consolidating vendor relationships around multi-year service contracts.
Germany
Automotive manufacturing corridors in Stuttgart and Munich require sub-ten-millisecond latency for real-time defect detection. The Federal Office for Information Security operates country-specific certification schemes that extend product validation timelines. Baden-Württemberg's industrial automation cluster anchors edge gateway deployment for brownfield SCADA integration.
United Kingdom
Critical infrastructure operators face NIS2-mandated security baseline replacements of legacy gateway installations. The National Cyber Security Centre coordinates sector-specific guidance for operational technology security. London's financial services and Northern England's manufacturing bases pull divergent gateway specifications for compliance-heavy deployments.
France
Municipal utility demand-response programs create residential gateway deployment opportunities. ANSM and CNIL frameworks govern data residency requirements for healthcare-adjacent IoT integrations. The Île-de-France region concentrates smart building automation procurement from commercial real estate operators.
Canada
Health Canada and PMRA oversight shapes gateway certification for medical device integration use cases. Provincial utility programs in Ontario and Quebec mirror U.S. managed services bundling models. The Toronto-Waterloo corridor anchors R&D concentration for edge compute software orchestration.
North America and Europe IoT Gateway Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the gateway value chain. The vendor base organizes into three tiers: semiconductor vendors with integrated AI accelerators, systems integrators with server-to-edge orchestration capabilities, and communication equipment specialists with pre-established certification infrastructure. Consolidation pressure concentrates among mid-scale hardware fabricators lacking software stack differentiation. Dominant competitive moves include strategic partnerships for containerized edge runtime distribution and geographic expansion through local certification entity acquisition.
Among diversified technology conglomerates, Cisco Systems Inc. and Dell Technologies Inc. occupy positions anchored by enterprise infrastructure relationships and in-house integration capabilities. NXP Semiconductors N.V. exemplifies the semiconductor-specialist archetype with automotive-grade silicon portfolios. These three entities represent divergent strategic postures: unified software stack convergence, hardware-margin defense through vertical integration, and dedicated edge-AI chipset development.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Advantech Co. Ltd |
| Dell Technologies Inc. |
| Microchip Technology Inc. |
| Intel Corporation |
| Huawei Technologies Co. Ltd |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Others |
Value Network & Pricing Analysis
Tier-one automotive suppliers operating just-in-time manufacturing networks in Stuttgart and Detroit anchor procurement volume concentration, locking in multi-year total-cost-of-ownership contracts that bundle hardware, software licenses, and field support into subscription-like pricing structures.
Pricing Analysis
Lead-time-driven pricing stratification separates premium tiers for expedited delivery from discounted spot inventory for standard lead times. Three-tier pricing structure across NIS2-certified, CE-marked standard, and uncertified economy levels reflects EU Cybersecurity Act compliance investment. Cost compression in economy tiers intensifies because automotive-grade SoC fabrication concentrates in East Asian foundries, while industrial automation buyers show lowest price sensitivity due to predictive maintenance downtime costs.
Supply Chain Analysis
Certification gating through Germany's Federal Office for Information Security and the U.S. Federal Communications Commission extends validation timelines and fragments supplier qualification. Automotive-grade SoC fabrication centers on Taiwan, South Korea, and China, with gateway hardware assembly drawing from Mexico and Vietnam. Single-source vulnerability concentrates in neural processing unit foundry capacity. Distribution runs through technical service-capable distributors rather than pure resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized edge runtime environments are displacing legacy hardware-centric procurement criteria, forcing vendors to restructure around software orchestration compatibility rather than throughput specifications alone.
For Market Incumbents: Cement market position by deepening in-house server-to-edge integration capabilities and accelerating pre-established EU cybersecurity certification infrastructure against NIS2 compliance gaps. Threat from ARM-based system-on-chip specialists with integrated AI accelerators demands captive silicon supply relationships or strategic foundry partnerships. For New Entrants and Emerging Players: Smart Home energy management gateways for European municipal utility demand-response programs offer the most penetrable white-space target, with lower certification overhead than industrial automation. Container orchestration expertise provides the strongest go-to-market angle against hardware-legacy incumbents. For Investors and Strategic Acquirers: The window for entry favors semiconductor vendors with automotive-grade silicon portfolios and existing Common Criteria certification infrastructure. Long-term viability hinges on unified software stack convergence. Watch NIS2 implementation timeline acceleration across EU member states as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Pre-established EU cybersecurity certification infrastructure captures share as competitors face NIS2 compliance gaps. |
| Containerized Edge Runtime Partnership | Software orchestration compatibility shifts procurement criteria from hardware specifications toward lifecycle management capabilities. |
| Automotive-Grade Silicon Acquisition | Neural processing unit integration addresses sub-ten-millisecond latency requirements in Stuttgart and Detroit manufacturing corridors. |
| Technical Service Capability Buildout | In-house field engineering competencies respond to utility-managed subscription program demands across North American and European markets. |
| Server-to-Edge Integration Investment | Unified software stacks satisfy tier-one automotive supplier consolidation of vendor relationships around multi-year service contracts. |
Research Methodology
Document review covered regulatory filings with the FCC and Germany's Federal Office for Information Security, complemented by interviews with plant engineers at tier-one automotive suppliers, procurement leads at North American utility providers, platform engineers at container orchestration vendors, and aftermarket service heads at industrial equipment distributors. Secondary validation drew from ETSI interoperability mandates, EU Cybersecurity Act implementation guidance, SEC 10-K disclosures from diversified technology conglomerates, and customs data on automotive-grade SoC import flows. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Cross-referencing historical certification timeline data against expert panel input on NIS2 implementation pacing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include gateway product architecture, end-use vertical, connectivity technology, and deployment model, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from elasticity analysis of edge compute integration intensity and managed services program penetration, incorporating foundry capacity expansion schedules and automotive manufacturing capital expenditure cycles as industry-specific inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan Strait semiconductor fabrication, unilateral tariff imposition on East Asian chip imports, and accelerated EU AI Act overlap with gateway cybersecurity requirements. Forecasts reflect documented assumptions on certification timeline stability and foundry capacity allocation. A model refresh is warranted upon material change in NIS2 enforcement intensity or Federal Reserve interest rate posture affecting utility capital expenditure cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Global Internet of Things Technology Market