
 Robot Sensor Market | 2026-2036
Robot Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Sensor Market Analysis
Modular sensor bundling is repositioning procurement patterns across the Robot Sensor Market. FANUC Corporation leverages captive production of force-feedback arrays to lock in automotive OEM contracts. Honeywell International Inc. sustains aerospace-grade calibration protocols that differentiate its proximity sensor lines. SICK AG anchors European distribution through dedicated machine-vision integration centers.
Robot sensors convert physical stimuli—displacement, force, light, or acoustic waves—into processable electrical signals with typical response thresholds below one millisecond. These devices enable closed-loop control in autonomous systems where real-time environmental mapping determines operational safety. Vision sensors now capture the widest margin pools as semiconductor lithography improves CMOS resolution at industrial price points. Force sensors represent the fastest-expanding category as collaborative robots require torque-limiting feedback for human-robot interaction compliance. Lidar retains structural dominance in autonomous vehicle testing fleets despite cost pressures from solid-state alternatives.
FDA device regulations govern surgical robot sensor accuracy claims in the United States, while the EU Machinery Directive mandates fail-safe architectures for industrial deployments across member states. ISO 10218 and ISO/TS 15066 establish functional safety benchmarks that determine market access for collaborative robot sensor packages. Stakeholders must monitor convergence between automotive functional-safety standards and industrial robot certification regimes as platform designs merge.
Market Dynamics
Multi-modal sensor fusion architectures are compressing design cycles across the Robot Sensor Market as automotive and industrial OEMs consolidate vendor lists around integrated suite providers rather than discrete component sourcing.
Growth Catalysts
- EU AI Act conformity mandates:Machinery manufacturers across Germany, France, and Italy must retrofit existing robot fleets with certified sensor packages to maintain CE marking eligibility, forcing systematic hardware refresh cycles.
- Collaborative robot torque-limiting requirements:ISO/TS 15066 human-robot interaction standards mandate force-feedback arrays in all new cobot installations, embedding force sensors as non-discretionary safety infrastructure.
- Stuttgart-Munich automation corridor concentration:Germany's dense cluster of automotive OEMs and system integrators generates localized demand spikes that pull sensor inventory away from other European industrial centers.
Market Restraints
- Indium gallium arsenide wafer supply concentration:Near-infrared sensor substrate production concentrates among three Asian foundries, exposing vision sensor manufacturers to input cost volatility and allocation rationing.
- Solid-state lidar technical ceiling:Mechanical beam-steering alternatives retain superior range resolution for autonomous vehicle testing, delaying cost-driven substitution despite unit price compression.
- FDA 510(k) pathway friction:Surgical robot sensor accuracy claims require extensive clinical validation, extending commercialization timelines for new force-sensing catheter technologies.
Strategic Opportunities
- India PLI scheme for industrial automation:Production-linked incentives for robotics manufacturing create localized assembly demand for cost-optimized proximity and vision sensor modules.
- Edge AI processor convergence:On-chip neural inference engines are automating real-time sensor data preprocessing, reducing latency requirements and enabling simpler downstream controller architectures.
- Direct OEM sensor integration centers:Bypassing traditional distribution, sensor vendors establish captive technical support facilities inside automotive manufacturing campuses to accelerate commissioning cycles.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 and IEC 61508 certification expertise concentrates among senior practitioners in Germany and Japan, creating talent bottlenecks for new market entrants.
- Legacy fieldbus protocol fragmentation:Industrial sensor deployments must bridge incompatible communication standards across installed base equipment, multiplying integration engineering hours.
- Cross-border calibration traceability:Aerospace and medical sensor applications require NIST-traceable or DAkkS-accredited calibration chains that complicate multi-site manufacturing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Sensor Market |
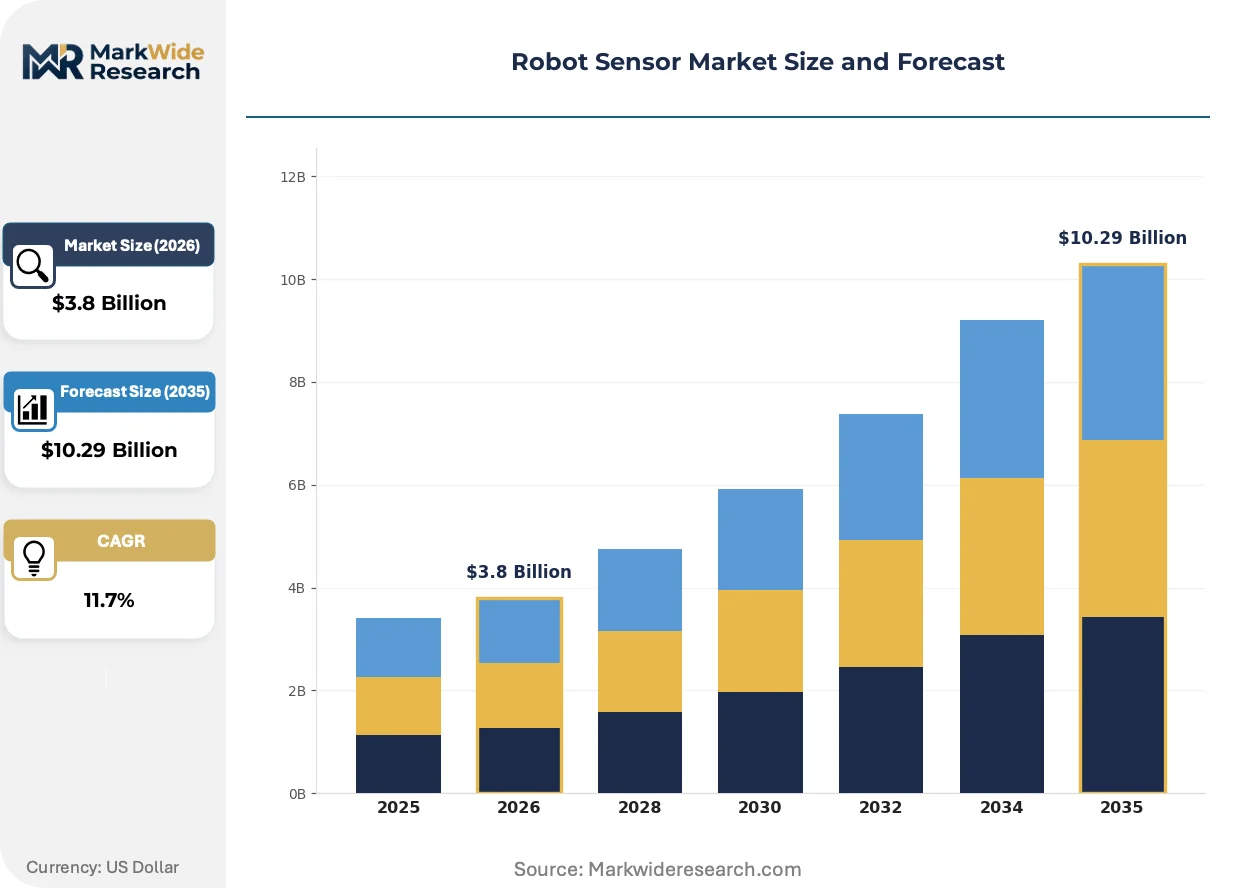
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidar, Proximity Sensors, Vision Sensors, Force Sensors End User: Manufacturing, Healthcare, Agriculture, Logistics Technology: Ultrasonic, Infrared, Camera-based, Gyroscope Application: Autonomous Vehicles, Industrial Automation, Smart Homes, Search & Rescue |
| Companies Covered | FANUC Corporation, Honeywell International Inc., TE Connectivity Ltd., Infineon Technologies AG, Omron Corporation, ATI Industrial Automation, Inc., SICK AG, Baumer Group, Cognex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Sensor Market Emerging Trajectories
Sensor fusion at the edge is compressing system architectures and redrawing competitive boundaries between component suppliers and platform integrators.
Event-based vision sensors using dynamic pixel architectures are automating motion detection with microsecond latency and orders-of-magnitude lower data bandwidth than frame-based alternatives. Automotive perception system developers in Germany and California are piloting these sensors for high-speed object tracking. The technology is automating the displacement of redundant lidar channels in certain highway-speed autonomous driving scenarios.
The EU Machinery Directive's 2023 update tightens fail-safe architecture requirements for collaborative robot sensor packages deployed across member states. Manufacturers must now demonstrate fault detection coverage through third-party notified body assessment before CE marking. Industrial sensor vendors with pre-certified safety subsystems capture disproportionate share in new cobot tenders.
Automotive OEMs are consolidating sensor procurement around multi-year platform contracts that bundle specification, validation, and after-sales calibration services. Tier-1 system integrators are absorbing these consolidated contracts, displacing direct component purchasing by individual manufacturing plants. This concentration is most visible in Germany's automotive belt and Michigan's manufacturing corridor.
Robot Sensor Market Segmentation
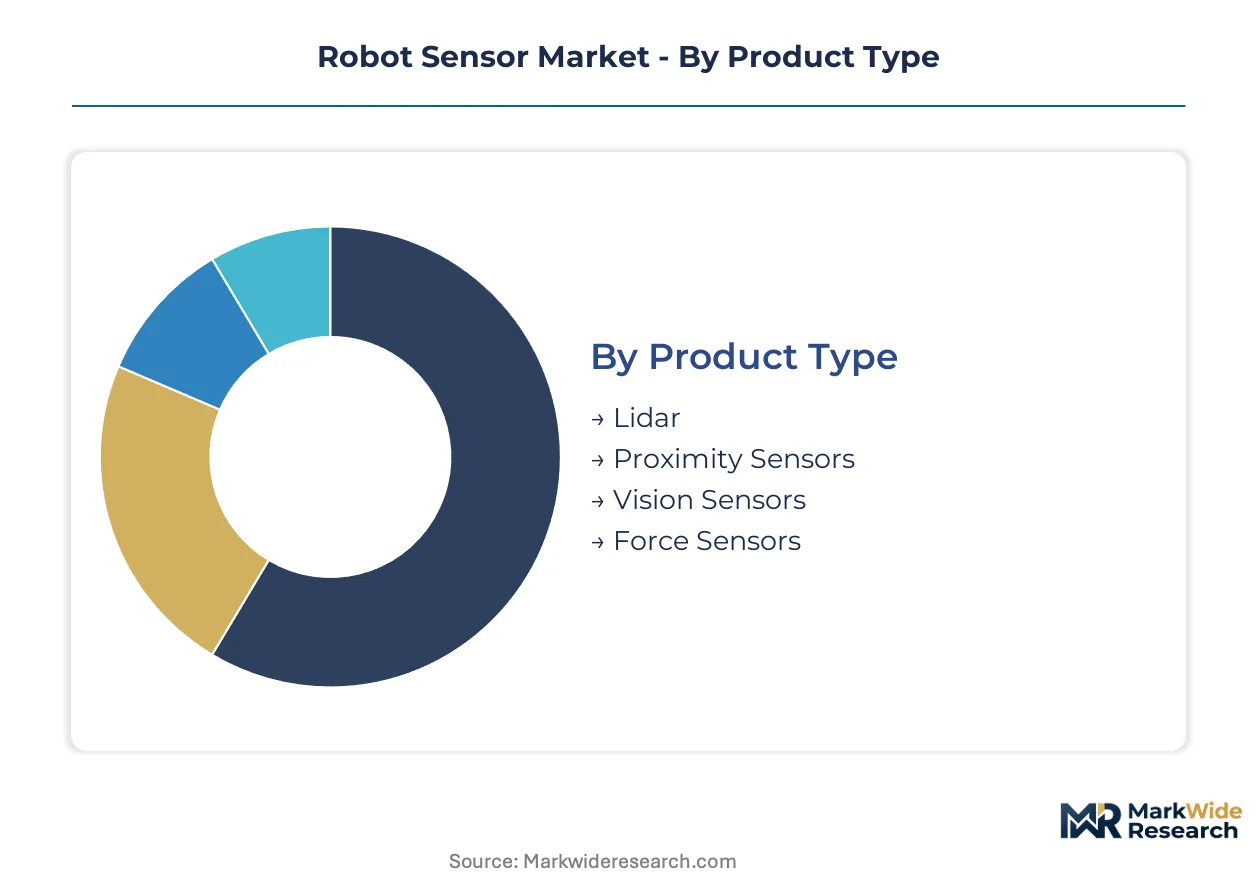
Robot sensor procurement patterns diver sharply across product architectures and deployment environments. Specification requirements from automotive functional safety standards and ISO collaborative robot mandates create tiered demand profiles that reshape vendor positioning across each segment category.
Product Type:
Technical specifications around response latency, environmental resilience, and fusion compatibility define competitive differentiation across sensor modalities.
- Vision Sensors:CMOS and CCD architectures capture optical data at industrial price points as semiconductor lithography advances. Automotive perception teams in Germany and California deploy these for lane-keeping and object classification, though indium gallium arsenide wafer supply concentration creates input cost volatility for near-infrared variants.
- Force Sensors:Torque-limiting feedback arrays enable human-robot interaction compliance under ISO/TS 15066. Collaborative robot deployments across Stuttgart and Munich drive concentrated demand as machinery manufacturers retrofit fleets for EU AI Act conformity.
- Lidar:Mechanical beam-steering systems retain range resolution superiority for autonomous vehicle testing.
- Proximity Sensors:Inductive and capacitive variants dominate collision avoidance in compact industrial workspaces.
Vision sensors lead on scale; force sensors lead on momentum.
End User:
Regulatory exposure and safety-criticality thresholds create distinct procurement behaviors across vertical deployments.
- Manufacturing:Assembly-line cobots embed multi-modal suites combining vision, force, and proximity arrays. Germany's industrial automation corridor generates localized demand spikes that pull inventory from other European centers, with EU Machinery Directive fail-safe mandates driving certified sensor package retrofits.
- Healthcare:Surgical robots require FDA-validated accuracy claims for force-sensing catheters and haptic feedback systems. Clinical validation timelines extend commercialization pathways, though reimbursement certainty supports premium pricing for NIST-traceable calibration chains.
- Logistics:Automated guided vehicles deploy lidar and camera-based navigation in warehouse environments.
- Agriculture:Precision spraying and harvesting robots utilize ultrasonic and infrared arrays for crop detection.
Manufacturing dominates volume concentration; healthcare commands specification premiums.
Technology:
Signal processing architectures and environmental robustness determine integration complexity across sensing modalities.
- Camera-based:Frame and event-based pixel architectures automate motion detection with microsecond latency. Edge AI processor convergence enables on-chip neural inference that reduces downstream controller complexity for high-speed object tracking applications.
- Infrared:Near-infrared emitters and photodetectors enable low-light operation for security and inspection tasks.
- Ultrasonic:Time-of-flight measurement supports short-range obstacle detection in cost-constrained deployments.
- Gyroscope:MEMS and fiber-optic variants provide inertial reference for mobile robot localization.
Camera-based systems anchor platform consolidation; event-based variants gain share fastest.
Application:
Operational environment constraints and safety integrity levels dictate sensor redundancy requirements and certification pathways.
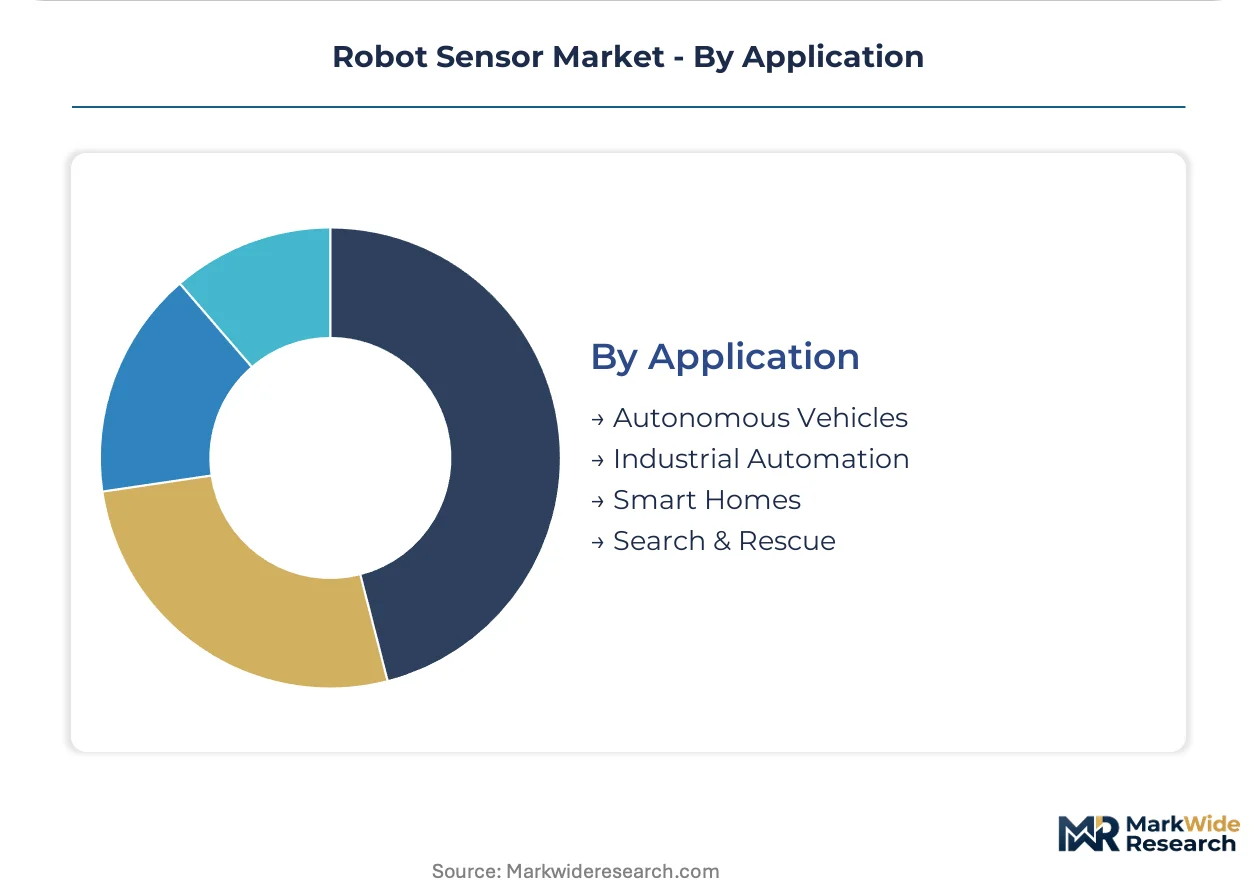
- Industrial Automation:Collaborative robot installations mandate force-feedback arrays and vision-guided positioning under ISO 10218 and ISO/TS 15066. Machinery manufacturers across France and Italy face parallel EU AI Act conformity deadlines that compress procurement timelines for certified packages.
- Autonomous Vehicles:Testing fleets retain mechanical lidar despite solid-state cost pressures, as range resolution requirements persist for highway-speed scenarios. NHTSA and KBA type-approval processes create divergent validation burdens for multi-market sensor suites.
- Smart Homes:Consumer robotics deploy simplified proximity and vision modules for navigation and interaction.
- Search & Rescue:Harsh-environment durability requirements favor ruggedized gyroscope and infrared configurations.
Industrial automation leads on deployment velocity; autonomous vehicles lead on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial robot sensor deployment through its automotive manufacturing heritage. Stuttgart and Munich now anchor Europe's densest automation corridor. Regulatory pressure from Brussels accelerates hardware refresh cycles across the continent.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria drive concentrated demand for force-feedback arrays and vision-guided systems. The EU Machinery Directive's 2023 update mandates third-party notified body assessment for CE marking eligibility. Stuttgart's machine-vision integration centers pull sensor inventory from neighboring industrial centers.
United States
Surgical robot manufacturers in Massachusetts and Minnesota require FDA-validated force-sensing accuracy claims. The FDA 510(k) pathway demands extensive clinical validation for new catheter technologies. Michigan's manufacturing corridor concentrates automotive cobot deployments with multi-modal sensor suites.
Japan
MEMS gyroscope specialists in Nagoya supply inertial reference systems for mobile robot localization. METI industrial automation incentives support domestic sensor module assembly. Kanto region system integrators consolidate procurement around platform contracts bundling validation services.
China
Automotive perception teams in Shanghai and Shenzhen pilot event-based vision sensors for highway-speed tracking. MIIT standards convergence with ISO functional safety benchmarks shapes certification requirements. Yangtze River Delta foundries face indium gallium arsenide wafer allocation pressures from vision sensor manufacturers.
India
Production-linked incentives for robotics manufacturing under the PLI scheme create localized assembly demand. BIS certification requirements for industrial safety equipment filter market access. Gujarat and Maharashtra industrial zones attract cost-optimized proximity sensor module sourcing.
Robot Sensor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across calibration traceability and functional safety certification tiers. The vendor base stratifies into three layers: diversified industrial conglomerates with captive sensor divisions, specialized machine-vision houses with integration capabilities, and component-focused suppliers serving tier-1 system integrators. Dominant competitive moves include strategic partnerships with automotive OEMs for multi-year platform contracts and backward integration into semiconductor wafer sourcing to secure near-infrared substrate supply.
Within the diversified industrial tier, FANUC Corporation and Honeywell International Inc. exemplify scale-driven positions spanning multiple sensor modalities alongside broader automation portfolios. SICK AG anchors the European specialist vector with dedicated machine-vision integration centers. These three occupy distinct competitive spaces: Japanese and American conglomerate breadth versus German precision-focused technical service depth.
| Leading Market Players |
|---|
| FANUC Corporation |
| Honeywell International Inc. |
| TE Connectivity Ltd. |
| Infineon Technologies AG |
| Omron Corporation |
| ATI Industrial Automation, Inc. |
| SICK AG |
| Baumer Group |
| Cognex Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 26262-compliant safety sensors and uncertified commodity alternatives manifests in divergent pricing power and supply chain sourcing strategies across the Robot Sensor Market. Premium-tier force-feedback arrays command sustained margins through captive calibration chains, while standard vision modules face cost compression from indium gallium arsenide wafer allocation pressures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with ISO/TS 15066 certification and NIST-traceable calibration chains as primary price differentiation drivers. Cost compression in standard vision sensors is intensifying because Yangtze River Delta foundries ration near-infrared substrate supply. Automotive OEMs exhibit lowest price sensitivity due to platform contract bundling, whereas logistics AGV operators prioritize unit economics.
Supply Chain Analysis
Functional safety engineer scarcity in Germany and Japan constrains certified sensor production capacity despite automation demand acceleration. Supply concentrates in Taiwan for CMOS fabrication, Germany for precision force-sensor assembly, and China for cost-optimized proximity module output. Raw material dependencies include indium phosphide substrates, MEMS wafer blanks, and rare-earth magnetic components. Single-source vulnerability in indium gallium arsenide wafer supply exposes manufacturers to allocation rationing. Distribution runs through tier-1 system integrators consolidating multi-year automotive platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in force-sensor categories where ISO/TS 15066 mandates embed non-discretionary demand, and in edge-AI-enabled vision modules where on-chip inference reduces downstream controller costs.
For Market Incumbents: Cement market position through backward integration into semiconductor wafer sourcing to secure near-infrared substrate supply against allocation rationing threats. Expand captive technical support facilities inside Stuttgart-Munich automotive campuses to accelerate commissioning cycles and lock out modular bundling competitors.
For New Entrants and Emerging Players: Capture white-space in India's PLI scheme robotics manufacturing zones where BIS certification requirements filter incumbent dominance. Target cost-optimized proximity sensor modules for Gujarat and Maharashtra industrial automation deployments, leveraging localized assembly partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety certification expertise concentrates among senior practitioners in Germany and Japan. Five-to-ten-year viability favors specialized machine-vision houses with pre-certified safety subsystems and established notified body relationships. Watch for EU AI Act enforcement intensity as the inflection signal determining hardware refresh cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Sourcing | Secures indium gallium arsenide supply against Yangtze River Delta allocation rationing. |
| Pre-Certified Safety Subsystem Development | Accelerates CE marking under EU Machinery Directive 2023 fail-safe architecture mandates. |
| Captive OEM Integration Center Establishment | Bypasses traditional distribution to compress commissioning cycles in Stuttgart-Munich corridor. |
| Edge AI Processor Convergence Investment | Enables on-chip neural inference that reduces downstream controller complexity for automotive perception. |
| India PLI Scheme Manufacturing Localization | Captures production-linked incentives for cost-optimized proximity and vision module assembly. |
Methodological Framework
Direct dialogue with robot sensor procurement managers, automotive OEM platform engineers, functional safety certification specialists, and tier-1 system integrator technical directors grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU Machinery Directive notified body assessments, MIIT industrial automation standards, SEC filings of diversified industrial conglomerates, and IHS Markit vehicle production databases. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across sensor modalities.
Bottom-up modeling tracked force-sensor, vision-sensor, lidar, and proximity module deployments by end-use vertical, technology architecture, and regional regulatory cluster. Top-down validation cross-checked aggregate market expansion against automotive production forecasts, cobot installation rates, and EU AI Act compliance timelines. CAGRs derived from segment-specific growth trajectories weighted by ISO certification penetration, edge-AI adoption curves, and solid-state lidar substitution elasticities across the analysis window.
Underlying measurement precision varies by segment; force-sensor and vision-sensor categories carry tighter precision than emerging event-based vision alternatives. Forecasts reflect assumptions about EU AI Act enforcement consistency, indium gallium arsenide wafer supply stability, and functional safety engineer pipeline expansion. Material deviation in notified body assessment backlogs or MIIT-ISO standards convergence timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Handheld RFID Readers Market
Sensors
Industrial Barcode Scanners Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Heat Stress Meter Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Traffic Sensor Market
Sensors
Global Position Tracking System Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
India Asset Tracking Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Europe RFID Market
Sensors
Body Area Network Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Low Power Geolocation Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market