
 Handheld RFID Readers Market | 2026-2036
Handheld RFID Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld RFID Readers Market Analytics
RF engineering talent scarcity is collapsing across industrial electronics hubs, forcing OEMs to automate test protocols and compress design cycles. Zebra Technologies Corporation leverages captive firmware development centers to sustain reader platform refresh rates. Honeywell International Inc anchors its North American position through channel control over authorized distributor networks. Impinj, Inc. specializes in RAIN RFID silicon-to-reader compatibility, differentiating its ecosystem approach against modular competitors.
Handheld RFID readers are battery-powered, portable transceiver devices operating in UHF, HF, or NFC frequency bands, designed to interrogate tags, capture identifier data, and transmit records to enterprise systems via Bluetooth, Wi-Fi, or cellular backhaul. These devices incorporate ruggedized housings, integrated antennas, and embedded operating systems to execute real-time asset tracking in warehouse, clinical, and factory floor environments. Passive technology dominates unit economics due to tag cost minimization, while active technology commands premium positioning in cold-chain and high-value logistics where extended read ranges justify battery-augmented tag expense. Handheld form factors retain the largest installed base, though wearable variants are gaining traction in pick-and-pack operations where operator dexterity constraints limit traditional pistol-grip designs.
FCC Part 15 rules in the United States constrain transmit power and spurious emissions, compelling hardware redesigns for cross-border product lines. CE marking under the EU Radio Equipment Directive plus ETSI EN 302 208 frequency allocations shapes European reader certification costs and time-to-market schedules. China's MIIT radio transmission type approval adds a third compliance layer for multinational suppliers. Stakeholders must monitor spectrum reallocation proceedings in major economies, as UHF band harmonization decisions directly impact reader interoperability investments and regional inventory strategy.
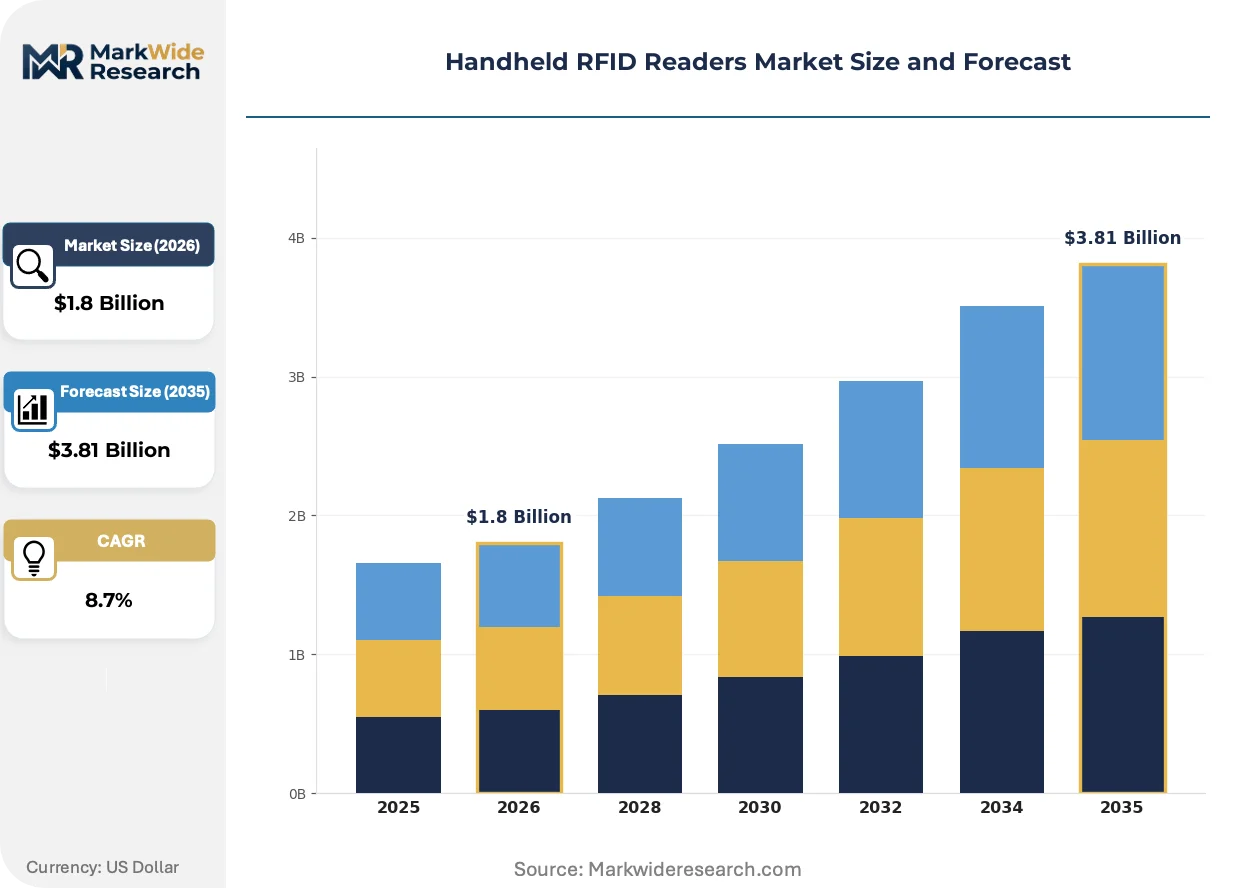
Market Dynamics
RF engineering talent scarcity is collapsing across industrial electronics hubs, forcing OEMs to automate test protocols and compress design cycles while spectrum harmonization pressures reshape regional product strategies.
Growth Catalysts
- Retail inventory automation:Omnichannel fulfillment networks in the United States and Germany are driving unit demand for real-time asset tracking in warehouse environments.
- FCC Part 15 equipment authorization:Tightening RF emission standards are compelling hardware redesigns that improve cross-border interoperability for multinational suppliers.
- Passive UHF tag economics:Tag cost minimization is expanding addressable applications beyond high-value logistics into mainstream apparel and pharmaceutical tracking.
Market Restraints
- Silicon supply concentration:RAIN RFID chip fabrication concentrates among a limited supplier base, creating vulnerability for reader OEMs dependent on compatible transceiver modules.
- Multi-jurisdiction certification costs:CE marking under EU Radio Equipment Directive plus China's MIIT type approval adds compliance layers that extend time-to-market schedules.
- Active tag battery dependency:Cold-chain applications requiring extended read ranges face ongoing battery replacement logistics that inflate total cost of ownership.
Strategic Opportunities
- Wearable form factor expansion:Pick-and-pack operations are adopting glove-mounted and wrist-worn readers where pistol-grip designs limit operator dexterity.
- Clinical asset tracking in Germany:Hospital systems are deploying handheld readers for real-time location services of mobile medical equipment.
- ETSI EN 302 208 harmonization:Frequency allocation alignment across European markets is reducing SKU complexity for regional product portfolios.
Industry Challenges
- Embedded firmware engineering scarcity:Captive development centers are competing aggressively for RF protocol stack specialists, compressing platform refresh timelines.
- Legacy WMS integration friction:Enterprise warehouse management systems require custom middleware development to ingest real-time RFID data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld RFID Readers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Mount, Handheld, Mobile, Wearable Technology: Passive, Active, Semi-Passive, NFC End User: Retail, Healthcare, Manufacturing, Logistics Sales Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc, Impinj, Inc., Alien Technology LLC, Datalogic S.p.A., CAEN RFID S.r.l., Cipherlab Co.,Ltd., GAO RFID Inc., Bluebird Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld RFID Readers Market Evolving Landscape
Handheld reader architectures are fragmenting across performance tiers while regulatory pressure and procurement model evolution reshape competitive positioning in enterprise mobility.
Reader platform architecture is bifurcating between modular Android-based devices and proprietary closed-system designs. Large retailers in the United States are adopting open-platform hardware to enable custom application development, while specialized logistics operators in Germany retain proprietary ecosystems for security-hardened deployments. This divergence is compressing margin structures for mid-tier OEMs caught between customization demands and scale economics.
CE marking obligations under the EU Radio Equipment Directive are tightening electromagnetic compatibility testing requirements. Hardware manufacturers must now demonstrate spurious emission compliance across broader frequency ranges, adding certification laboratory costs and extending European launch timelines. Medical device distributors are responding by pre-certifying reader variants against ETSI EN 302 208 before commercial rollout.
Enterprise buyers are consolidating vendor relationships through multi-year fleet management contracts. Authorized distributor networks in North America are losing ground to direct OEM engagement models that bundle hardware, software, and support services. This pattern is most visible among Fortune 500 retailers operating centralized procurement functions across United States distribution centers.
Handheld RFID Readers Market Segmentation
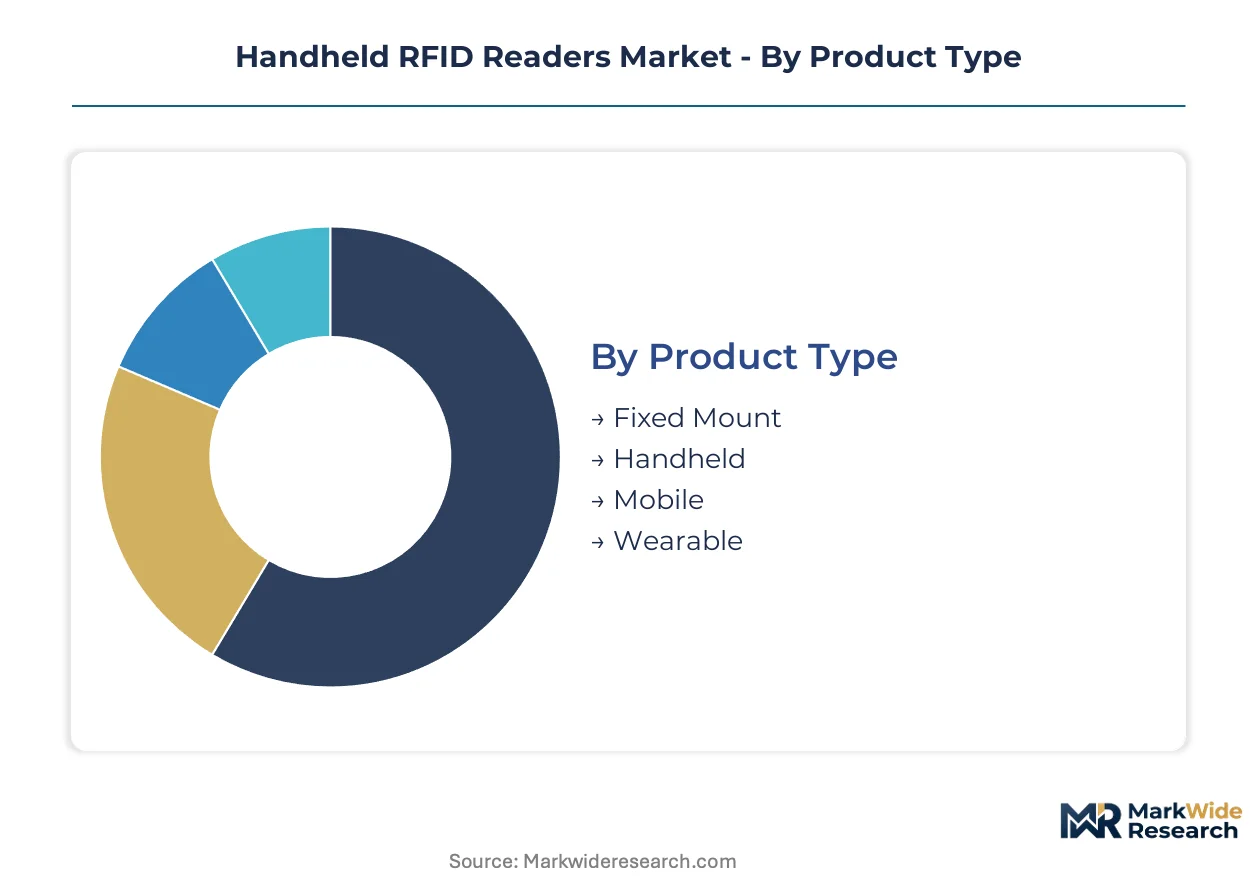
Handheld RFID reader segmentation reflects divergent compliance burdens across frequency bands and form factors, with procurement patterns increasingly shaped by enterprise fleet consolidation rather than transactional hardware sales.
Product Type:
FCC Part 15 transmit power limits and ETSI EN 302 208 spurious emission thresholds create divergent certification pathways for each form factor, directly impacting SKU proliferation strategies for cross-border suppliers.
- Handheld:Pistol-grip transceivers dominate current installed bases across United States distribution centers and German automotive plants, with integrated antennas and ruggedized IP65 housings meeting OSHA warehouse safety requirements. Demand concentrates in omnichannel retail fulfillment networks where real-time inventory visibility drives labor productivity metrics.
- Wearable:Glove-mounted and wrist-worn variants incorporate Bluetooth Low Energy backhaul and reduced antenna arrays to preserve operator dexterity in pick-and-pack operations. Germany's logistics sector leads adoption, with EDEKA and DHL Supply Chain deploying fleet pilots to reduce repetitive strain injuries.
- Fixed Mount:Portal and conveyor-integrated readers operate at higher transmit power under FCC equipment authorization for automated gate applications.
- Mobile:Vehicle-mounted forklift units combine UHF interrogation with cellular telemetry for yard management in United States intermodal facilities.
Handheld units handle the majority of throughput; wearable configurations are climbing the fastest on share as ergonomic constraints reshape operator equipment specifications.
Technology:
Cost tier differentiation separates passive tag economics from active tag total cost of ownership, with battery logistics and read range requirements driving divergent procurement approval workflows.
- Passive:UHF backscatter technology leverages reader-generated RF energy to power tag ICs, enabling sub-cent unit economics for apparel and pharmaceutical serialization at Walmart and CVS Health scale. MIIT type approval in China and CE marking under EU Radio Equipment Directive impose harmonized spurious emission testing that favors standardized reader platforms.
- Active:Battery-augmented tags transmit autonomously at 433 MHz or 2.4 GHz, commanding premium positioning in cold-chain monitoring for United States pharmaceutical distributors where FDA 21 CFR Part 11 compliance mandates continuous temperature logging.
- Semi-Passive:Battery-assisted passive tags bridge range and cost, finding niche adoption in German automotive component tracking where ETSI frequency allocations support extended read zones.
- NFC:13.56 MHz proximity interfaces serve access control and payment authentication, with EMVCo certification requirements distinct from RAIN RFID compliance pathways.
Passive technology anchors volume shipments; active systems are expanding most quickly in regulated cold-chain verticals where battery logistics justify premium positioning.
End User:
Application-specific durability and software integration requirements fragment procurement specifications, with each vertical imposing distinct middleware and security hardening demands.
- Retail:Omnichannel fulfillment networks in the United States deploy handheld readers for cycle counting and returns processing, with GS1 EPC Gen2 tag serialization mandated by Walmart and Target supplier compliance programs.
- Healthcare:German hospital systems including Charité Berlin implement real-time location services for mobile medical equipment, with CE marking under EU Medical Device Regulation adding electromagnetic compatibility validation for patient-proximity deployments.
- Manufacturing:United States automotive plants integrate fixed-mount and handheld readers for work-in-process tracking, with OSHA electrical safety standards influencing intrinsically safe variant specifications.
- Logistics:Third-party operators in China leverage MIIT-certified handheld units for cross-border e-commerce parcel sorting, with customs integration requirements driving firmware localization.
Retail absorbs the largest hardware volumes; healthcare is gaining share fastest as clinical asset tracking mandates proliferate across European hospital procurement frameworks.
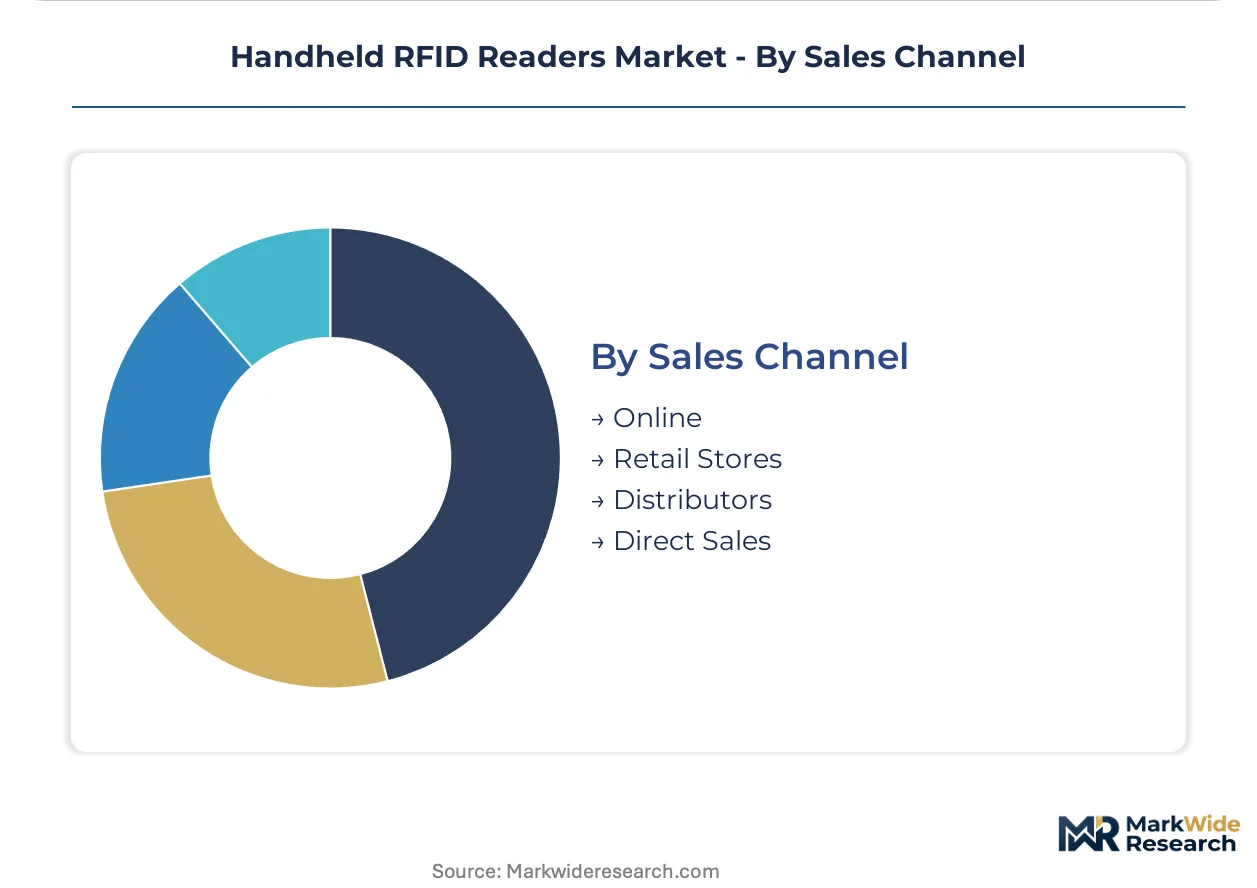
Sales Channel:
Customer type stratification between enterprise fleet buyers and mid-market transactional purchasers is restructuring channel economics, with direct engagement displacing traditional distribution in concentrated accounts.
- Direct Sales:OEM field organizations engage Fortune 500 retailers and healthcare systems through multi-year fleet management contracts bundling hardware, SaaS analytics, and break-fix services. Zebra Technologies and Honeywell International anchor North American direct sales teams in Chicago and Atlanta metro areas.
- Distributors:Authorized distributor networks including ScanSource and BlueStar serve mid-market manufacturing and logistics accounts requiring localized technical support and credit terms.
- Online:E-commerce platforms capture small business and pilot-scale deployments, with Amazon Business and Alibaba.com listing certified reader SKUs for United States and China procurement teams.
- Retail Stores:Limited consumer-facing presence through industrial electronics resellers for evaluation kit and developer board sales.
Direct sales channels manage the majority of enterprise revenue; online procurement is expanding most quickly among pilot-stage deployments and small facility rollouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States distribution centers deploy handheld readers for omnichannel fulfillment, while German automotive plants favor fixed-mount configurations for work-in-process tracking. Chinese cross-border e-commerce operators prioritize MIIT-certified units for customs integration.
United States
Walmart and Target supplier compliance programs mandate GS1 EPC Gen2 tag serialization, driving hardware refresh cycles. FCC Part 15 equipment authorization constrains transmit power and spurious emissions, compelling hardware redesigns for cross-border product lines. Chicago and Atlanta metro areas anchor Zebra Technologies and Honeywell International field organizations serving Fortune 500 retailers.
Germany
EDEK A and DHL Supply Chain pilot glove-mounted wearable readers to reduce repetitive strain injuries in pick-and-pack operations. CE marking under EU Radio Equipment Directive plus ETSI EN 302 208 frequency allocations shapes certification costs and time-to-market schedules. Charité Berlin implements real-time location services for mobile medical equipment, anchoring clinical asset tracking demand.
China
Cross-border e-commerce parcel sorting operations leverage handheld units for customs integration and firmware localization. MIIT radio transmission type approval adds compliance layers for multinational suppliers. Yangtze River Delta manufacturing clusters drive demand for automated gate applications in intermodal facilities.
Japan
Automotive component suppliers adopt semi-passive battery-assisted passive tags for extended read zones in just-in-sequence production. METI industrial standards influence intrinsically safe variant specifications for factory floor deployments. Kansai region electronics manufacturers integrate RAIN RFID silicon-to-reader compatibility testing into supplier qualification protocols.
United Kingdom
NHS hospital procurement frameworks are expanding clinical asset tracking mandates for mobile medical equipment. UKCA marking requirements post-Brexit create parallel certification pathways alongside retained CE marking obligations. London and Southeast distribution networks serve as European launch points for multi-jurisdiction product rollouts.
Handheld RFID Readers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive firmware development and channel control separating premium positioning from commodity pressure. The structure bifurcates between modular Android-based open platforms and proprietary closed-system designs. Two strategic archetypes dominate: ecosystem integrators bundling silicon-to-reader compatibility and hardware specialists anchoring authorized distributor networks. Competitive moves concentrate on direct OEM engagement displacing traditional distribution, plus multi-year fleet management contracts bundling hardware, SaaS analytics, and break-fix services.
Within the integrated leader tier, Zebra Technologies Corporation and Honeywell International Inc exemplify divergent geographic anchoring strategies, with the former leveraging captive development centers and the latter controlling authorized distributor networks. Impinj, Inc. occupies a specialist position representing the ecosystem-integrator archetype through RAIN RFID silicon-to-reader compatibility focus. These three companies collectively illustrate how vertical integration depth and channel architecture choices determine competitive positioning against modular competitors.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc |
| Impinj, Inc. |
| Alien Technology LLC |
| Datalogic S.p.A. |
| CAEN RFID S.r.l. |
| Cipherlab Co.,Ltd. |
| GAO RFID Inc. |
| Bluebird Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day component lead times for UHF transceiver modules concentrate pricing power with Taiwan and South Korea foundries, while North American OEMs absorb inventory carrying costs to buffer against RAIN RFID silicon allocation volatility. This dynamic compresses margin structures for mid-tier reader manufacturers unable to secure long-term supply agreements or captive fabrication capacity.
Pricing Analysis
Multi-year fleet management contracts dominate enterprise procurement, with SaaS-tiered pricing bundling hardware, firmware updates, and break-fix services displacing per-unit transactional sales. Price differentiation hinges on FCC Part 15 certification tier and GS1 EPC Gen2 interoperability grade, with premium positioning commanding margin buffers against commodity pressure. Cost compression in standard-tier readers intensifies as Chinese MIIT-certified imports penetrate mid-market accounts. Fortune 500 retailers exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while small-facility pilots face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of RAIN RFID integrated circuits supersedes just-in-time preferences as foundry allocation cycles lengthen, with Zebra Technologies and Honeywell International maintaining six-month safety stocks of Impinj-compatible transceivers. Component sourcing draws from Taiwan, South Korea, and China's Yangtze River Delta, with UHF antenna substrates and ruggedized housing polymers anchoring bill-of-materials exposure. Single-source vulnerability concentrates in monolithic microwave IC fabrication, where TSMC and Samsung Foundry capacity allocation dictates reader OEM production schedules. Distribution runs through authorized networks including ScanSource and BlueStar for mid-market accounts, while direct OEM engagement captures enterprise fleet consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering scarcity constrains platform refresh rates, with RF protocol stack specialists commanding premium compensation across industrial electronics hubs and compressing development timelines for reader OEMs.
For Market Incumbents: Shield installed base relationships through captive certification investment against CE marking and FCC Part 15 compliance escalation, while anchoring channel control over authorized distributor networks to resist direct OEM engagement erosion. Consolidate backward integration into UHF antenna design to reduce transceiver module dependency and defend margin position against modular competitors. For New Entrants and Emerging Players: Firmware localization services for Chinese MIIT type approval and German ETSI EN 302 208 harmonization represent the most penetrable white-space, where incumbent OEMs under-serve mid-market logistics operators lacking in-house regulatory affairs capacity. Target wearable form factor pilots at German pick-and-pack operators through ergonomic assessment partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because RAIN RFID silicon-to-reader compatibility determines ecosystem lock-in and recurring SaaS attach rates. Acquisition candidates with captive firmware development centers and pre-certified regional SKUs offer defensive positioning. The signal to watch is spectrum reallocation proceedings in major economies, where UHF band harmonization decisions trigger hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Firmware Development Center Expansion | RF protocol stack specialization accelerates platform refresh timelines against talent-scarce competitors. |
| Multi-Jurisdiction Pre-Certification Investment | Parallel FCC, CE marking, and MIIT approval reduces SKU complexity for cross-border product portfolios. |
| Wearable Form Factor R&D Partnership | Ergonomic glove-mounted designs address repetitive strain injury liability in German logistics operations. |
| Direct OEM Engagement Model Deployment | Fleet management contract bundling displaces authorized distributor networks in Fortune 500 retail accounts. |
| RAIN RFID Silicon Compatibility Deepening | Ecosystem integration with Impinj transceivers creates switching costs against modular hardware competitors. |
Research Methodology
Operator-level perspectives from warehouse operations directors, biomedical engineers at German hospital systems, and RFID integration specialists anchored the qualitative base, triangulated against FCC equipment authorization filings, ETSI EN 302 208 compliance databases, and OEM SEC 10-K disclosures. Secondary validation drew from customs trade data, GS1 EPC Gen2 implementation case studies, and MIIT radio transmission type approval registries. Bottom-up unit shipment estimates across frequency bands and form factors reconciled with top-down market value reconstruction.
Sensitivity analysis tested forecast robustness across passive versus active technology adoption scenarios, with segmentation modeling spanning handheld, wearable, fixed-mount, and mobile form factors alongside retail, healthcare, manufacturing, and logistics end-use verticals. CAGRs derived from logistic diffusion curves fitted to historical replacement cycles and regulatory-driven hardware refresh patterns. Forecast inputs incorporated spectrum harmonization timelines and enterprise fleet consolidation trajectories.
Underlying assumptions cover RFID tag cost minimization sustaining passive UHF volume expansion, with deviation risk concentrated in RAIN RFID silicon supply concentration and multi-jurisdiction certification timeline slippage. Revision becomes warranted when FCC Part 15 rulemaking or EU Radio Equipment Directive amendments cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Indoor Air Quality Monitor Market
Sensors
Eye Tracking Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Transport Monitoring System Market
Sensors
Heat Stress Meter Market
Sensors
Facial Tracking Solution Market
Sensors
Alcohol Sensor Market
Sensors
Residential Water Leak Detection System Market
Sensors
Beacon Market
Sensors
Underground Service Locator Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Refrigeration Monitoring Market
Sensors
Temperature Data Loggers Market
Sensors
Real Time Location System Market