
 Handheld GPS Units Market | 2026-2036
Handheld GPS Units Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld GPS Units Market Foresight
Specialty outdoor retailers is reshaping how handheld GPS units reach end users, with direct-to-consumer platforms and expedition outfitters capturing share from traditional electronics chains. Garmin Ltd. leverages its vertically integrated manufacturing to control chipset sourcing and firmware development. Magellan GPS competes through focused marine and off-road specialization. TomTom International BV. anchors its position in automotive-adjacent handheld crossover segments.
Handheld GPS units are portable satellite navigation receivers incorporating multi-frequency GNSS chipsets, barometric altimeters, and ruggedized enclosures rated for shock and water immersion; they serve commercial surveyors and recreational users requiring position fixes in environments beyond cellular coverage. Outdoor product types lead unit volumes due to sustained trail tourism and wilderness recreation participation. GNSS technology variants are displacing GPS-only configurations as BeiDou and GLONASS integration becomes standard even in mid-range devices. Fitness-oriented handhelds concentrate margin pools through heart rate integration and training-load analytics that command premium pricing.
FCC certification requirements govern transmitter and RF emissions for devices sold in the United States, while CE marking under EU Radio Equipment Directive mandates interoperability and safety standards for European market access. ISO 9001 quality management frameworks shape manufacturing consistency across contract assembly partners in Asia. Stakeholders must monitor spectrum allocation decisions at ITU and national regulator levels that could expand or constrain multi-constellation receiver architectures.
Market Dynamics
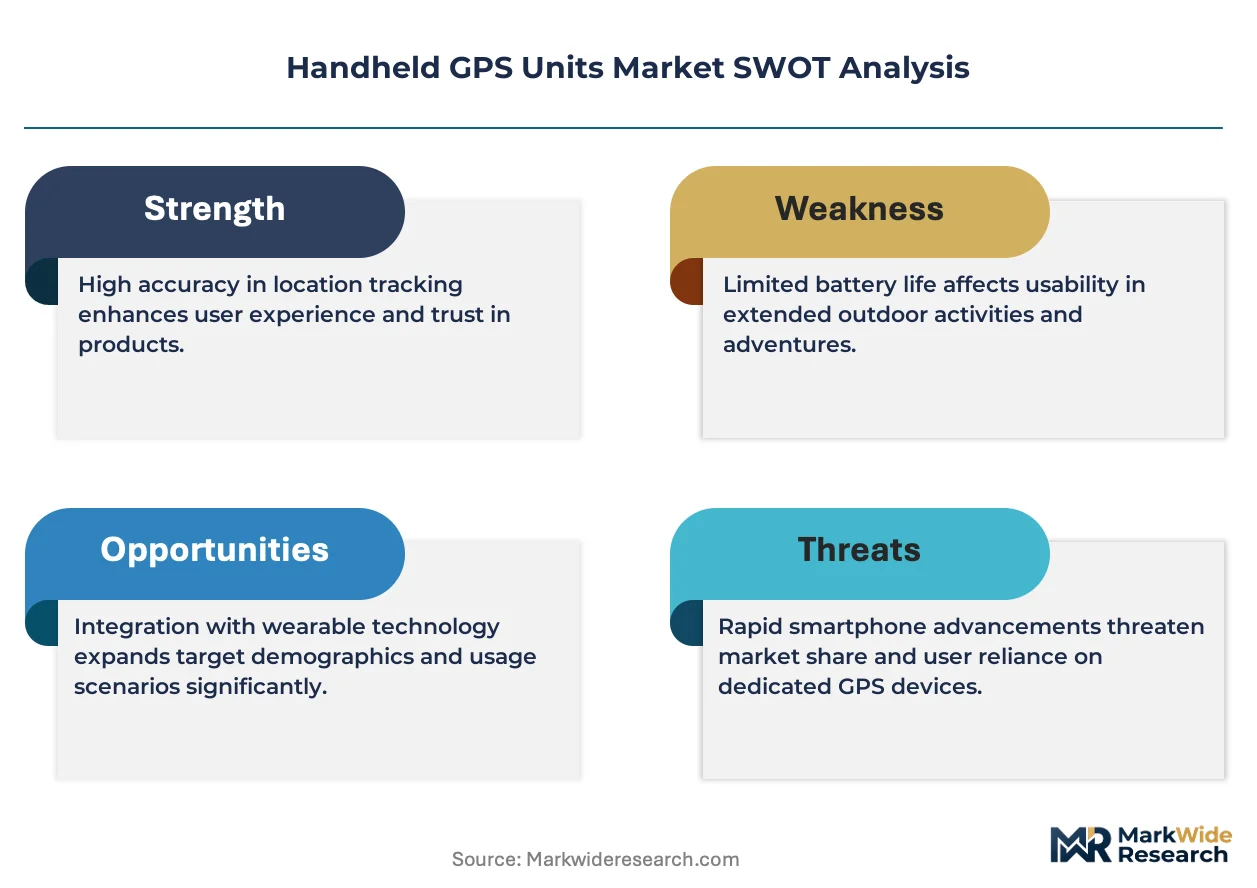
Multi-constellation GNSS chipsets are compressing the technical differentiation between premium and mid-tier handheld GPS units, forcing manufacturers to compete on firmware capabilities and sensor integration rather than raw positioning accuracy.
Growth Catalysts
- Trail tourism recovery:Wilderness recreation participation in the United States is expanding as federal land management agencies invest in backcountry infrastructure maintenance and digital mapping coordination.
- FCC certification streamlining:The Federal Communications Commission has adjusted RF equipment authorization timelines for outdoor navigation devices, reducing market entry friction for new chipset architectures.
- Barometric altimeter integration:Fitness-oriented users now expect elevation tracking and training-load analytics as standard features, pulling sensor fusion technology into mainstream price tiers.
Market Restraints
- Semiconductor supply concentration:Multi-frequency GNSS receiver fabrication depends on a narrow base of foundry capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Smartphone substitution:Consumer-grade navigation demand faces erosion from ruggedized smartphone cases and offline mapping applications that satisfy casual trail users without dedicated hardware purchase.
- CE marking complexity:The EU Radio Equipment Directive's interoperability testing requirements impose extended validation cycles for multi-constellation devices seeking European market access.
Strategic Opportunities
- Commercial surveying expansion:Precision agriculture operators in Brazil and Australia represent underpenetrated demand for centimeter-capable handheld receivers with RTK correction integration.
- Marine crossover segments:Offshore fishing enthusiasts require waterproof floating designs with tide and celestial data overlays, a specification set distinct from terrestrial hiking units.
- ISO 9001 manufacturing partnerships:Contract assemblers in Vietnam and Mexico are building quality management frameworks that qualify for federal procurement contracts without legacy facility retooling.
Industry Challenges
- Firmware talent scarcity:Embedded systems engineers with GNSS signal processing expertise command premium compensation, constraining mid-tier manufacturers' in-house development capacity.
- Multi-constellation certification backlog:Simultaneous BeiDou, GLONASS, and Galileo validation creates test matrix complexity that stretches engineering schedules and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld GPS Units Market |
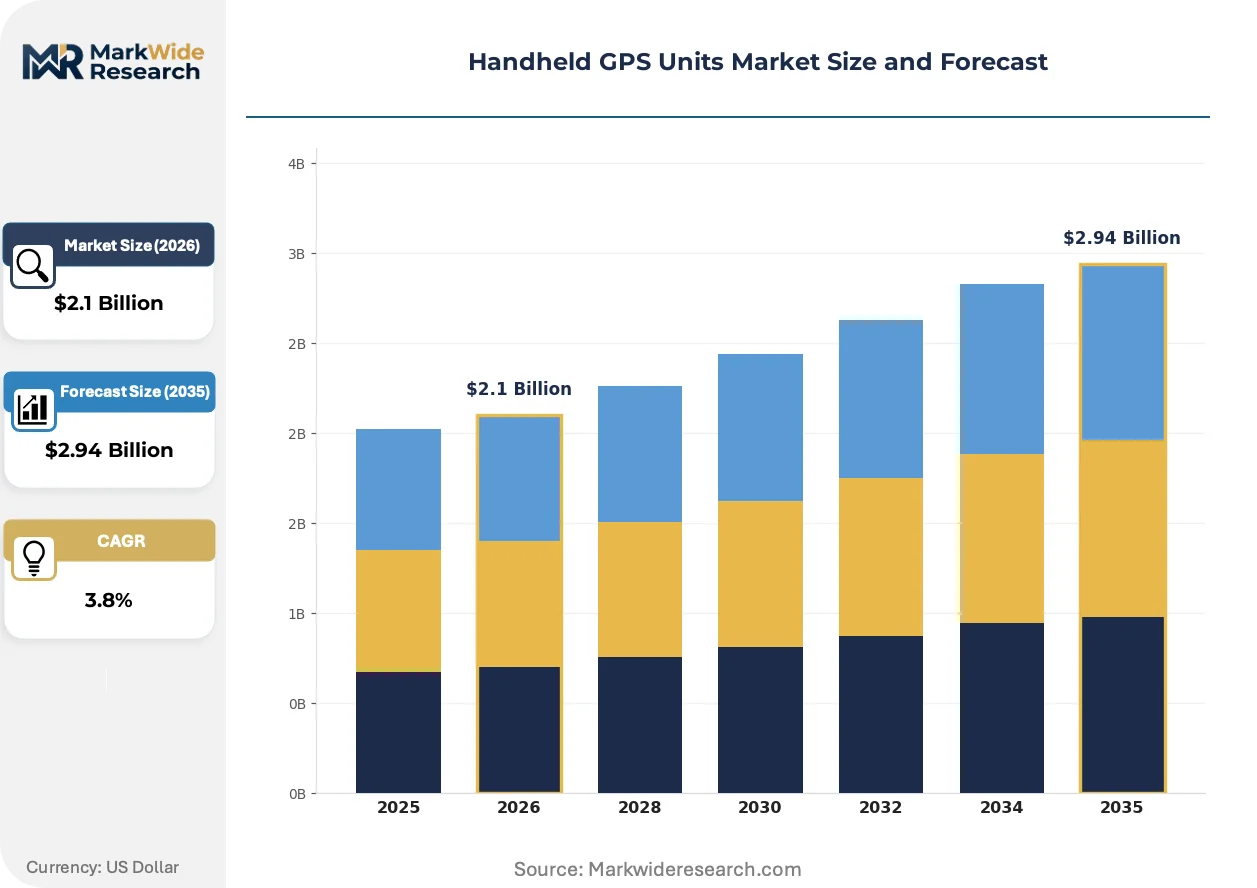
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor, Marine, Fitness, Automotive Technology: GNSS, GPS, GLONASS, BeiDou End User: Hikers, Campers, Anglers, Surveyors Feature: Waterproof, Bluetooth, Touchscreen, Voice Navigation |
| Companies Covered | Garmin Ltd., Magellan GPS, TomTom International BV., ALPS ALPINE ASIA CO. LTD, Sony Corporation, AvMap Satellite Navigation Inc., Mio Technology Corporation, Shenzhen RoadRover Technology Co Ltd, Blaupunkt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld GPS Units Market Shifts & Advancements
Sensor fusion architectures and alternative positioning methods are redefining what handheld GPS units can measure beyond latitude and longitude, creating new premium tiers around biometric and environmental data integration.
Dual-frequency L1/L5 GNSS reception is migrating from professional survey equipment into recreational handhelds. Outdoor enthusiasts operating in forest canopy or urban canyon environments demand faster signal reacquisition and multipath rejection. This migration is compressing the price-performance gap between consumer and professional-grade receivers, forcing legacy manufacturers to accelerate firmware differentiation roadmaps.
The EU Radio Equipment Directive's 2024 cybersecurity amendments now mandate vulnerability disclosure procedures for connected navigation devices. Manufacturers must maintain software update infrastructure for products sold in European markets, raising ongoing service cost structures. Marine and aviation crossover handhelds face the steepest compliance burden due to their safety-critical application profiles and extended operational lifecycles.
Expedition outfitters and direct-to-consumer platforms are capturing procurement volume from traditional electronics retail chains. Specialty outdoor retailers now curate device selection based on trip type and terrain difficulty rather than specification comparison. This behavioral shift concentrates most visibly in the United States, where REI and regional climbing cooperatives influence brand consideration through guided trip partnerships and staff technical certification programs.
Handheld GPS Units Market Segmentation
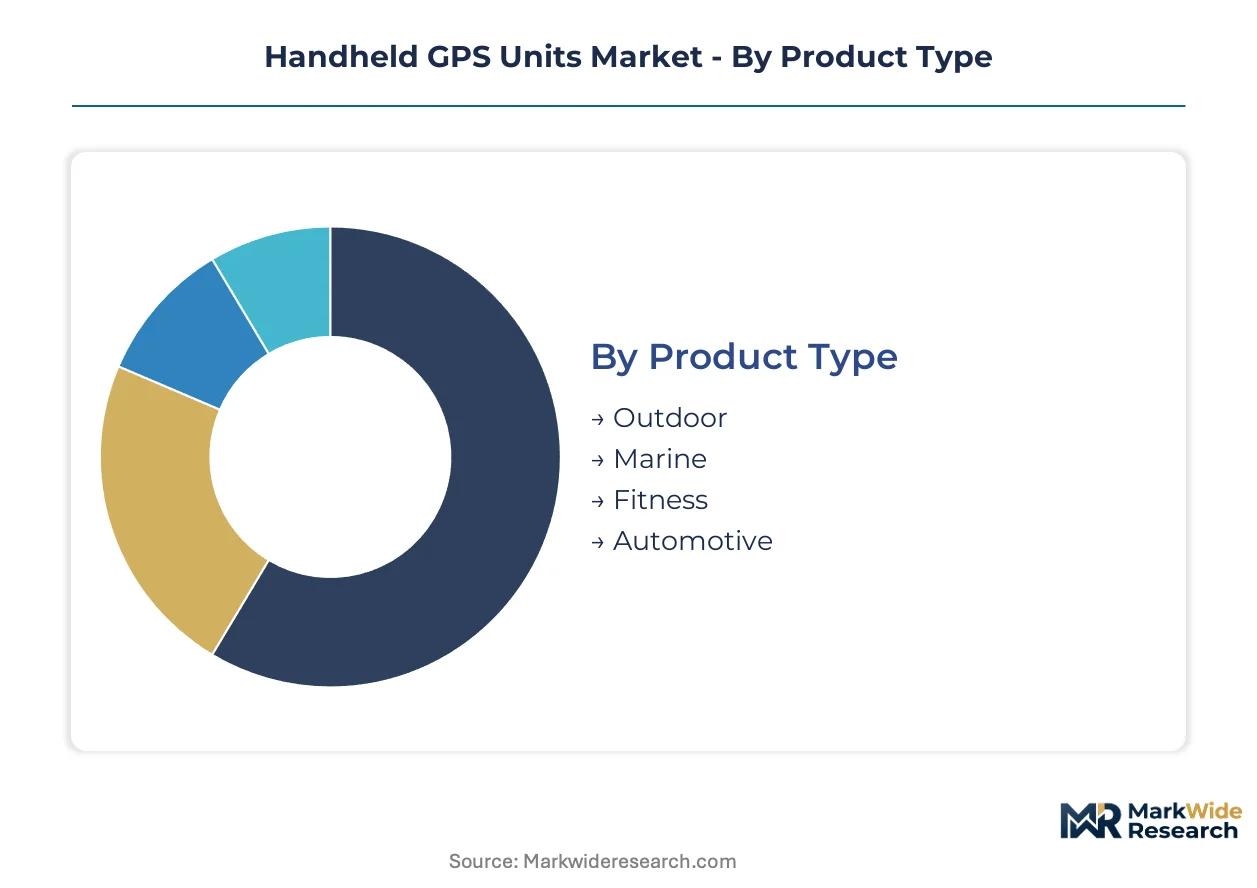
Handheld GPS unit purchasing patterns diverge sharply across use cases, with replacement cycles stretching from two years for fitness-focused consumers to seven-plus years for commercial surveyors. Understanding segment-level turnover dynamics helps manufacturers calibrate inventory planning and firmware support lifecycles.
Product Type:
Outdoor units turn over fastest at 3-4 year cycles as recreational users upgrade for improved battery life and display clarity, while marine devices persist longest due to saltwater corrosion resistance requirements that delay replacement decisions.
- Outdoor:Ruggedized enclosures rated for shock and water immersion dominate this segment, with barometric altimeters and multi-constellation chipsets now standard even at mid-tier price points. Demand concentrates among United States federal land management agency coordination with trail maintenance programs driving unit procurement for backcountry navigation reliability.
- Marine:Waterproof floating designs with tide tables and celestial data overlays serve offshore fishing enthusiasts, with IPX8 ratings and corrosion-resistant coatings extending operational lifespans in saltwater environments. Brazil and Australia represent expansion terrain for centimeter-capable receivers with RTK correction integration.
- Fitness:Heart rate integration and training-load analytics command premium positioning through sensor fusion architectures.
- Automotive:Crossover handhelds anchor TomTom International BV.'s positioning with navigation systems bridging personal and vehicle-mounted applications.
Outdoor anchors the volume base while Fitness gains share at the steepest rate.
Technology:
Cost tiers separate legacy single-constellation receivers from multi-frequency architectures, with GNSS integration now penetrating mid-range devices that previously relied on GPS-only configurations.
- GNSS:Multi-constellation chipsets incorporating BeiDou, GLONASS, and Galileo alongside GPS deliver faster signal reacquisition in forest canopy and urban canyon environments. Dual-frequency L1/L5 reception is migrating from professional survey equipment into recreational handhelds, compressing the price-performance gap between consumer and professional-grade receivers.
- GPS:Legacy single-system receivers persist in budget-tier devices serving casual trail users, though FCC certification streamlining is accelerating chipset architecture transitions.
- GLONASS:Russian constellation integration provides redundancy for northern latitude operations.
- BeiDou:Chinese system compatibility opens procurement channels for Asia-Pacific expedition outfitters and government contracts.
GNSS dominates procurement volume while BeiDou integration expands most quickly in federal procurement channels.
End User:
Application requirements dictate feature prioritization, with commercial surveyors demanding centimeter precision while recreational users prioritize battery duration and interface simplicity.
- Hikers:Wilderness recreation participants require reliable position fixes beyond cellular coverage, with trail tourism recovery in United States federal lands driving sustained demand. Barometric altimeter integration has become an expected standard for elevation tracking during multi-day treks.
- Surveyors:Precision agriculture operators in Brazil and Australia seek RTK-capable handhelds for field boundary mapping and variable-rate input application, representing underpenetrated demand for centimeter-accurate receivers.
- Campers:Overnight wilderness users prioritize extended battery life and waypoint storage capacity.
- Anglers:Offshore fishing enthusiasts require waterproof floating designs with tide overlay functionality distinct from terrestrial specifications.
Hikers sustain the largest installed base while Surveyors generate the fastest margin expansion.
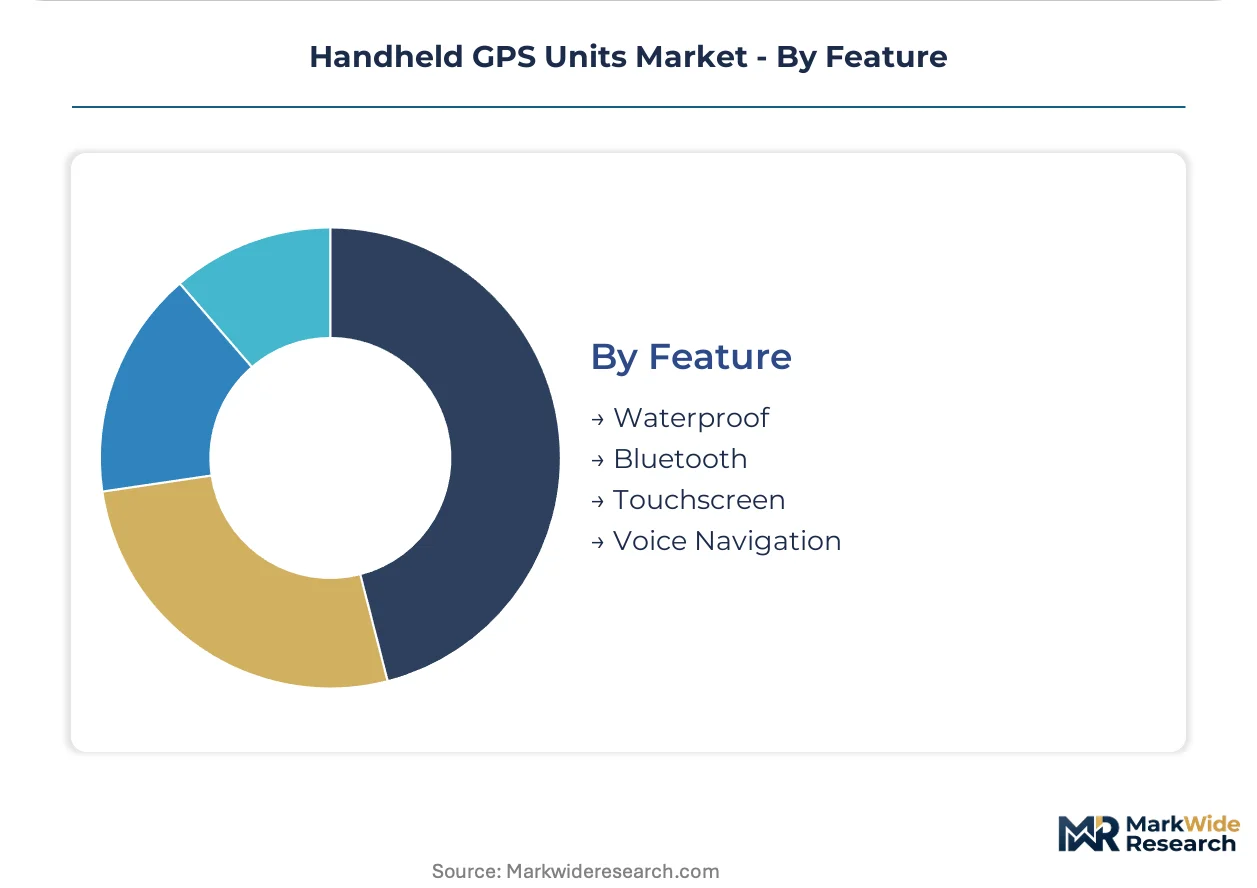
Feature:
Customer type separates premium-tier buyers seeking biometric integration from economy purchasers satisfied with core navigation functionality.
- Waterproof:IP ratings determine marine and whitewater applicability, with floating designs commanding price premiums in offshore fishing segments. ISO 9001 manufacturing partnerships in Vietnam and Mexico are building quality frameworks qualifying for federal procurement without legacy facility retooling.
- Bluetooth:Wireless sensor pairing enables heart rate monitoring and smartphone notification relay for fitness-oriented users. EU Radio Equipment Directive cybersecurity amendments now mandate vulnerability disclosure procedures for connected navigation devices, raising ongoing service cost structures.
- Touchscreen:Glove-compatible interfaces differentiate cold-weather expedition units.
- Voice Navigation:Hands-free operation serves marine and aviation crossover applications where manual interface access is impractical.
Waterproof specifications anchor commercial procurement standards while Bluetooth integration climbs fastest in fitness-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements govern transmitter and RF emissions for devices sold in the United States, while CE marking under EU Radio Equipment Directive mandates interoperability standards for European market access. National regulators across key manufacturing and consumption hubs shape procurement patterns through spectrum allocation decisions and import compliance frameworks.
United States
Federal land management agencies maintain extensive trail networks requiring reliable backcountry navigation, driving sustained procurement from the National Park Service and Forest Service. FCC streamlining of RF equipment authorization timelines reduces market entry friction for new chipset architectures. Colorado and Utah host expedition outfitter clusters that curate device selection through guided trip partnerships.
Germany
Precision agriculture operators in Bavaria and Lower Saxony seek centimeter-capable handheld receivers for field boundary mapping applications. CE marking under EU Radio Equipment Directive imposes extended validation cycles for multi-constellation devices seeking market access. Stuttgart anchors automotive-adjacent handheld crossover development with navigation systems bridging personal and vehicle-mounted applications.
China
BeiDou system compatibility opens procurement channels for Asia-Pacific expedition outfitters and government contracts. MIIT governs radio transmission equipment type approval and spectrum allocation for multi-constellation receiver architectures. Shenzhen hosts contract assembly partnerships building ISO 9001 quality management frameworks for federal procurement qualification.
Australia
Precision agriculture operators in Queensland and Western Australia represent underpenetrated demand for RTK-capable handhelds in variable-rate input application. The Therapeutic Goods Administration (TGA) does not regulate navigation devices; instead, the Australian Communications and Media Authority (ACMA) manages RF equipment compliance. Perth anchors marine crossover segments with offshore fishing enthusiasts requiring waterproof floating designs.
Brazil
Centimeter-capable receivers with RTK correction integration serve precision agriculture expansion in Mato Grosso and São Paulo soybean belts. ANVISA does not oversee navigation equipment; the National Telecommunications Agency (Anatel) certifies radio frequency devices for commercial sale. São Paulo hosts regional distribution hubs serving South American expedition outfitters.
Handheld GPS Units Market Competitive Landscape
Vertically integrated specialists and component-assembly contractors split the market between firmware-differentiated premium tiers and price-competitive mid-range volumes. Three to four manufacturers control the majority of GNSS chipset sourcing and firmware development capacity. Strategic archetypes include captive-manufacturing multinationals with in-house semiconductor production and regional assemblers dependent on contract foundry partnerships. Competitive moves center on sensor fusion technology licensing and ISO 9001 manufacturing partnerships in Vietnam and Mexico.
Within the captive-manufacturing tier, Garmin Ltd. exemplifies upstream control over chipset sourcing and firmware roadmaps. Among Netherlands-based navigation specialists, TomTom International BV. occupies a position in automotive-adjacent handheld crossover segments. Magellan GPS represents focused marine and off-road specialization, anchoring a distinct specification set from terrestrial hiking units.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Magellan GPS |
| TomTom International BV. |
| ALPS ALPINE ASIA CO. LTD |
| Sony Corporation |
| AvMap Satellite Navigation Inc. |
| Mio Technology Corporation |
| Shenzhen RoadRover Technology Co Ltd |
| Blaupunkt GmbH |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwan's semiconductor foundry base is compressing GNSS chipset pricing and forcing contract manufacturers to absorb margin erosion while maintaining ISO 9001 qualification timelines for federal procurement eligibility. This utilization dynamic rewards vertically integrated device makers with captive supply arrangements while squeezing regional assemblers dependent on spot-market component sourcing.
Pricing Analysis
United States retail pricing for mid-tier outdoor units runs 15-20 percent above equivalent European shelf prices due to FCC certification cost recovery and expedition outfitter channel markups. Three-tier pricing structure across premium, standard, and economy levels separates RTK-capable survey receivers from fitness-oriented sensor-fusion models and basic GPS-only trail units. Price differentiation rests on certification grade and firmware capability depth. Cost compression in the economy tier is intensifying because smartphone substitution erodes casual-user willingness to pay for dedicated hardware. Commercial surveyors show least price sensitivity due to centimeter-accuracy productivity gains, while recreational hikers in emerging markets resist premium positioning.
Supply Chain Analysis
Foxconn, Pegatron, and Jabil hold dominant contract-manufacturing capacity for ruggedized electronics assembly across Vietnam, Mexico, and China. Geographic supply concentrates in Taiwan for multi-frequency GNSS receiver fabrication, South Korea for memory components, and Vietnam for final device assembly and testing. Raw material dependencies include rare-earth magnetics for antenna modules, lithium-polymer cells for extended battery life, and specialized polymers for shock-rated enclosures. Single-source vulnerability in Taiwan's foundry base exposes lead times to geopolitical friction. Distribution runs through specialty outdoor retailers and direct-to-consumer platforms that have displaced traditional electronics chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Handheld GPS unit markets are shifting toward service-attach revenue models as firmware update subscriptions and RTK correction service bundles expand faster than hardware replacement cycles. This recurring-revenue layer commands superior margin profiles and extends customer lifetime value beyond initial device procurement.
For Market Incumbents: Build firmware-ecosystem moats through sensor fusion patent portfolios and exclusive RTK network partnerships that lock in commercial surveyor switching costs. Defensive moves should prioritize backward integration into GNSS chipset sourcing to escape Taiwan foundry concentration risk, while accelerating ISO 9001 certification for Mexican and Vietnamese assembly partners to qualify for federal land management agency procurement. Smartphone substitution in recreational segments and CE marking cybersecurity amendments in European markets represent dual threat vectors requiring parallel response. For New Entrants and Emerging Players: Mid-market commercial surveyors in Brazil and Australia represent the most penetrable entry point given underdeveloped RTK service infrastructure and price sensitivity among precision agriculture operators. Marine crossover segments for offshore fishing enthusiasts offer second white-space opportunity due to distinct waterproof floating specifications that incumbent terrestrial specialists underinvest. Go-to-market execution should anchor in expedition outfitter partnerships that provide technical credibility and guided-trip distribution channels without legacy retail slotting fee burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-differentiated device makers with RTK correction service subscriptions and vulnerability-patch update obligations under EU Radio Equipment Directive mandates. Long-term viability over a multi-year horizon favors acquisition targets with captive GNSS signal processing engineering talent and established federal procurement qualification rather than pure hardware assemblers. Signal to monitor: BeiDou constellation expansion timelines and corresponding Chinese government contract award patterns as inflection indicator for Asia-Pacific market access.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency GNSS Migration | L1/L5 reception in recreational tiers compresses professional-consumer price-performance gaps and forces firmware differentiation. |
| RTK Service Network Expansion | Centimeter-correction subscriptions in Brazil and Australia unlock precision agriculture margin pools beyond hardware sales. |
| ISO 9001 Manufacturing Partnership | Vietnam and Mexico qualification secures federal procurement access without legacy facility retooling investments. |
| Sensor Fusion Platform Integration | Heart rate and barometric altimeter bundling commands premium positioning in fitness-oriented handheld segments. |
| Cybersecurity Compliance Infrastructure | EU Radio Equipment Directive vulnerability disclosure mandates raise ongoing service cost structures for connected devices. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented certification timelines and spectrum allocation decisions. The research combined structured discussions with GNSS chipset procurement directors, federal land management agency equipment officers, expedition outfitter category managers, and firmware engineering leads with validation against FCC equipment authorization databases, EU Radio Equipment Directive implementation guidance, MIIT type approval records, and ISO 9001 registrar audit schedules. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Calibration against historical replacement cycle patterns and chipset architecture transition timelines shaped the projection framework. Segmentation dimensions modeled include product type, GNSS technology tier, end-user application, and feature bundle across the projection horizon. CAGRs derived from logistic diffusion curves fitted to multi-constellation receiver adoption rates and trail tourism participation indices. Forecast inputs incorporated federal land management agency budget appropriation trends and precision agriculture operator equipment survey data.
Practitioners should monitor BeiDou constellation completion milestones, Taiwan foundry utilization reports, and EU cybersecurity amendment enforcement patterns for early signals of forecast revision. Quarterly review of federal procurement contract awards, RTK service subscriber growth, and smartphone offline mapping feature releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global RFID Market
Sensors
Mobile Lidar Scanner Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
India Asset Tracking Market
Sensors
2D Barcode Reader Market
Sensors
RFID Smart Cabinet Market
Sensors
Eye Tracking Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Surface Haptic Technology Market
Sensors
Safety Motion Control System Market
Sensors
Industrial Barcode Scanners Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Wireless RFID Readers Market
Sensors
Barcode Scanner Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Robot Sensor Market