
 GNSS-Enabled Consumer Device Market | 2026-2036
GNSS-Enabled Consumer Device Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS-Enabled Consumer Device Market Foresight
RF engineering talent scarcity across semiconductor design hubs is unwinding OEM roadmaps for dual-frequency GNSS integration. Apple leverages captive silicon development to sustain positioning accuracy leadership in premium smartphones. Garmin anchors its competitive moat through specialized firmware for backcountry navigation. Xiaomi competes aggressively on cost-optimized BeiDou-GPS fusion chipsets for emerging-market handsets.
GNSS-enabled consumer devices integrate satellite navigation receivers with application processors to deliver geospatial positioning, velocity, and timing data to end users. These systems typically incorporate multi-constellation support across L1 and L5 frequency bands, with integrated inertial measurement units providing dead-reckoning continuity in signal-degraded environments. Smartphones occupy the largest volume tier though margin pools concentrate in wearable devices where health-monitoring fusion drives premium pricing. Automotive navigation systems face structural pressure from smartphone mirroring technologies, while drones represent the fastest-expanding application segment as regulatory frameworks mature for beyond-visual-line-of-sight operations.
Europe's ETSI mandates Galileo compatibility in automotive emergency-call systems, while the FCC in the United States enforces E911 location-accuracy requirements that shape handset GNSS performance thresholds. China's MIIT administers BeiDou terminal certification, creating market-access conditions distinct from Western multi-constellation regimes. Stakeholders must monitor spectrum reallocation proceedings and emerging regional certification reciprocity agreements that could fragment or unify hardware platform strategies across major consumer markets.
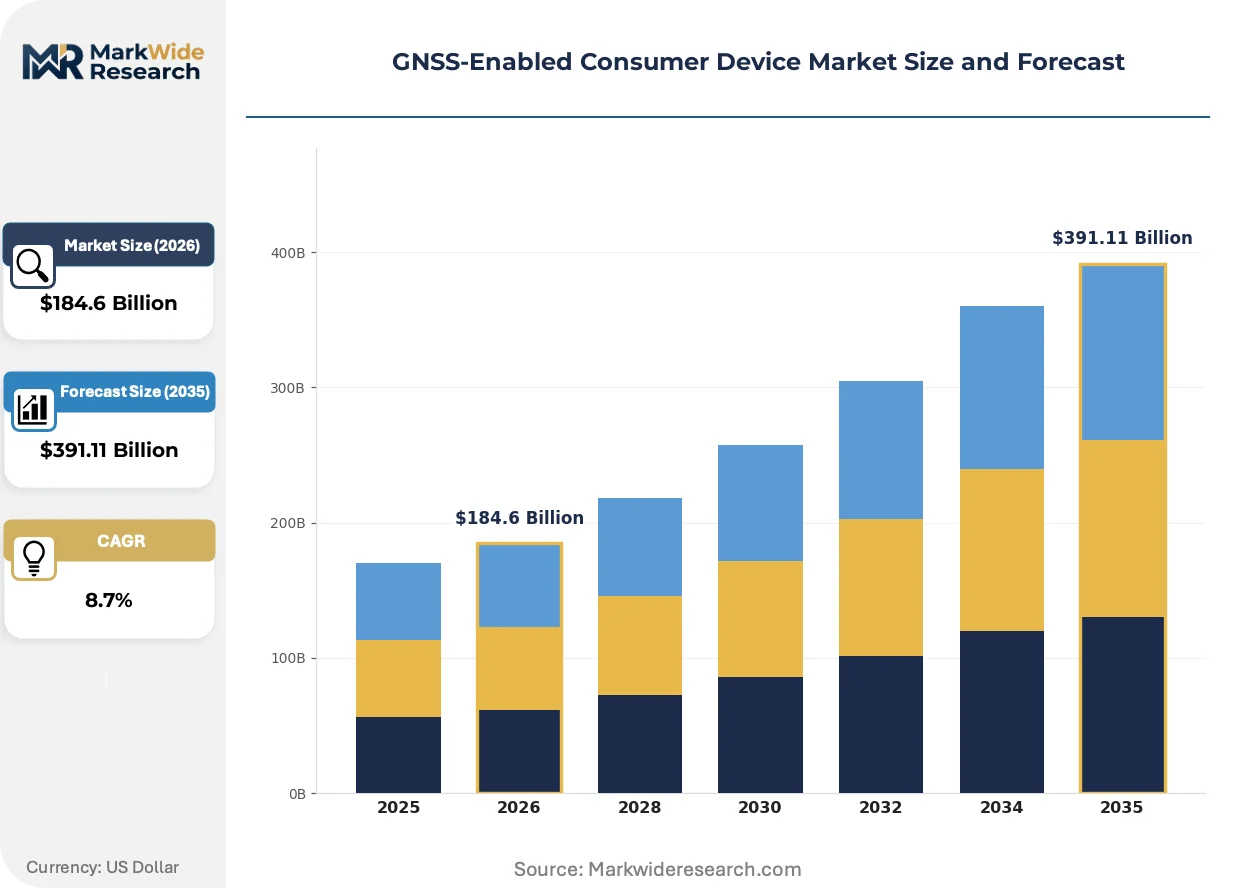
Market Dynamics
Multi-constellation GNSS integration is compressing hardware differentiation across smartphone and wearable tiers, forcing OEMs to compete on sensor fusion software and power efficiency rather than raw satellite receiver performance.
Growth Catalysts
- ETSI Galileo Mandates:Europe's emergency-call system compatibility requirements are compelling automotive Tier-1 suppliers to redesign telematics control units, expanding addressable hardware volumes for dual-frequency chipsets.
- Fitness Wearable Penetration:Outdoor recreation enthusiasts are upgrading from basic pedometers to multi-band GNSS watches for trail mapping and elevation tracking, pulling through precision positioning demand in mid-tier price bands.
- Drone Regulatory Maturation:Beyond-visual-line-of-sight frameworks in civil aviation jurisdictions are mandating redundant positioning systems for commercial UAV certification, creating dedicated receiver demand absent from consumer handhelds.
Market Restraints
- RF Engineering Scarcity:Specialized talent for L5 band filter design concentrates in semiconductor hubs around San Diego and Hsinchu, creating recruitment bottlenecks that delay product tape-outs by 6-12 months.
- Substrate Cost Volatility:Low-temperature co-fired ceramic substrates for compact antenna-in-package modules face pricing pressure from 5G infrastructure buildouts competing for identical material grades.
- Smartphone Mirroring Displacement:Android Auto and Apple CarPlay are collapsing standalone automotive navigation system volumes, compressing OEM willingness to fund next-generation GNSS receiver development.
Strategic Opportunities
- India BIS Certification Pathway:The Bureau of Indian Standards is finalizing BeiDou-GPS interoperability specifications for emergency response devices, opening procurement channels for multi-constellation hardware previously excluded from government tenders.
- Health-Monitoring Fusion:Wearable OEMs are integrating SpO2 and ECG sensors with GNSS track logs to correlate physiological stress with geographic exertion profiles, commanding premium pricing in endurance sports segments.
- Augmented Reality Wayfinding:Urban navigation apps are fusing camera-based visual positioning with satellite corrections, creating demand for sub-meter accuracy chipsets in mid-range handsets previously served by meter-class receivers.
Industry Challenges
- MIIT Certification Timelines:China's BeiDou terminal approval process requires in-country testing facilities that lack capacity for foreign OEM submission volumes, extending time-to-market by 8-14 weeks.
- Inertial Sensor Integration Complexity:Dead-reckoning algorithms demand tight calibration between MEMS gyroscopes and GNSS receivers, requiring firmware competencies that span distinct semiconductor supplier ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS-Enabled Consumer Device Market |
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $391.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Wearable Devices, Automotive Navigation, Drones Technology: GPS, GLONASS, Galileo, BeiDou End User: Individual Consumers, Outdoor Enthusiasts, Fleet Operators, Retailers Application: Tracking, Navigation, Mapping, Location-Based Services |
| Companies Covered | Samsung Electronics, Xiaomi, Apple, Fossil Group, Huami Corporation, Garmin, Huawei Technologies, TomTom, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS-Enabled Consumer Device Market Shifts & Advancements
Positioning accuracy is becoming a software-defined attribute as cloud-based correction services and AI-driven multipath mitigation reduce dependence on premium hardware architectures.
Dual-frequency L1/L5 reception is decomposing the traditional premium-mid-economy handset segmentation. Flagship smartphones from Samsung and Google now integrate triple-constellation support as standard, forcing chipset vendors to push multi-band capability into sub-$200 devices through die-shrunk RF front-ends. This compression is collapsing margin pools in the standalone receiver module business while expanding total addressable volume.
Europe's F-Gas Regulation and associated fluorinated greenhouse gas phase-down are reshaping thermal management strategies for high-precision GNSS reference stations. Network operators are retrofitting cooling systems with CO2-based alternatives, increasing capex intensity for ground infrastructure that supports consumer device augmentation services. Germany's KBA is enforcing these timelines most aggressively, affecting automotive calibration facility investments.
Subscription-based correction services are displacing hardware-centric accuracy differentiation. Trimble and u-blox now monetize centimeter-level positioning through annual software licenses rather than premium receiver SKUs, altering procurement patterns for precision agriculture and surveying adjacent to consumer markets. This shift is most visible in Australia, where TGA-aligned medical device regulations are simultaneously driving demand for location-audited cold chain logistics.
GNSS-Enabled Consumer Device Market Segmentation
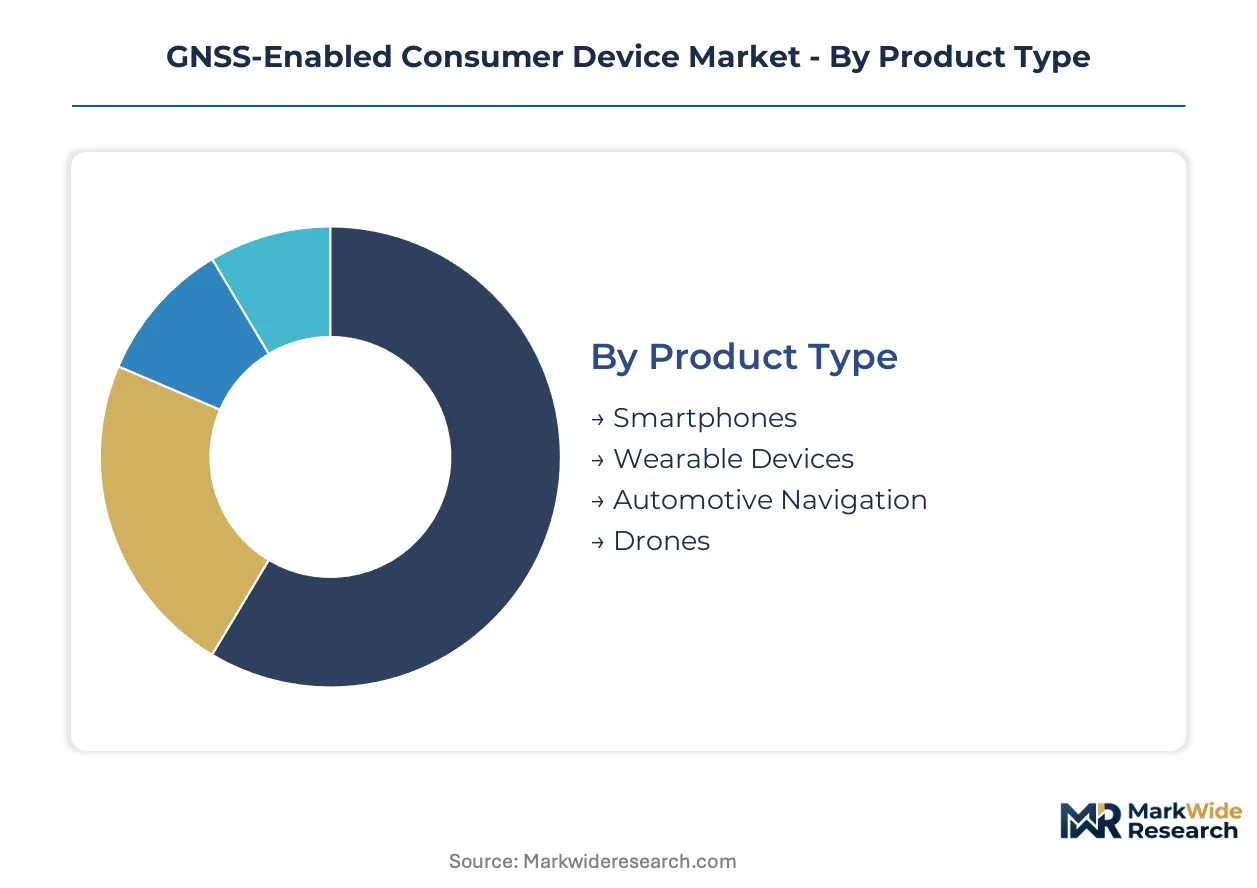
Segmentation in the GNSS-enabled consumer device market reveals divergent hardware requirements across precision tiers and use-case intensity. Product architecture, constellation support, and end-user technical sophistication create distinct procurement patterns that reshape supplier priorities.
Product Type:
Domestic demand in China and India concentrates in mass-market handsets, while export-led manufacturing in Vietnam and Mexico supplies North American and European automotive and wearable tiers.
- Smartphones:Multi-constellation L1/L5 receivers now ship standard in flagship designs from Samsung and Google, with die-shrunk RF front-ends pushing dual-frequency capability into sub-$200 handsets. Volume concentrates in Shenzhen and Dongguan manufacturing clusters serving domestic Chinese consumption and Southeast Asian export markets; FCC E911 mandates in the United States enforce minimum accuracy thresholds that elevate baseline receiver specifications.
- Wearable Devices:Specialized firmware for backcountry navigation and health-monitoring sensor fusion command premium pricing in endurance sports segments. Garmin anchors demand in North American and European outdoor recreation markets; Xiaomi competes aggressively on BeiDou-GPS fusion chipsets for emerging-market fitness bands where basic elevation tracking suffices.
- Automotive Navigation:ETSI Galileo mandates for emergency-call systems compel Tier-1 supplier redesigns of telematics control units. Android Auto and Apple CarPlay displacement pressures standalone system volumes in Germany, Japan, and South Korea.
- Drones:Beyond-visual-line-of-sight regulatory frameworks in Australia, Canada, and the United States mandate redundant positioning systems for commercial UAV certification. This application climbs the fastest as civil aviation jurisdictions mature operational rules.
Smartphones hold the largest share; momentum sits with drones.
Technology:
Cost tier stratification separates premium multi-constellation fusion from single-system economy implementations, with mid-tier devices adopting dual-constellation as standard.
- GPS:Legacy L1 C/A code reception remains ubiquitous in economy handsets and basic automotive trackers. United States market access depends on FCC certification for E911 compliance; this technology retains dominant installed base though lacks premium positioning accuracy.
- GLONASS:Russian constellation support provides high-latitude coverage advantages for Nordic and Baltic market devices. Integration complexity with GPS has standardized; GLONASS+L1 fusion now ships in mid-tier chipsets from MediaTek and Qualcomm.
- Galileo:Dual-frequency E1/E5a reception enables sub-meter accuracy for automotive emergency-call mandates. European ETSI regulations and KBA enforcement timelines in Germany accelerate adoption in telematics hardware.
- BeiDou:Chinese constellation dominance in Asia-Pacific markets requires MIIT terminal certification that extends foreign OEM time-to-market. BIS interoperability specifications in India now open government procurement channels previously restricted to GPS-only devices.
GPS retains dominant installed base; Galileo gains share fastest in regulated automotive applications.
End User:
Volume distribution skews toward individual consumers, while margin concentration favors technically demanding segments with specialized accuracy requirements.
- Individual Consumers:Mass-market smartphone and basic wearable demand concentrates in urban navigation and casual fitness tracking. Procurement runs through carrier-subsidized handset channels in the United States and direct-to-consumer e-commerce in India.
- Outdoor Enthusiasts:Multi-band GNSS watches with barometric altimeters and preloaded topographic maps command 3-4x pricing over basic fitness bands. Demand clusters in Colorado, the Alps, and Japan's mountain prefectures where backcountry navigation safety drives replacement cycles.
- Fleet Operators:Commercial vehicle telematics requires meter-class accuracy for route optimization and regulatory compliance. ELD mandates in the United States and tachograph rules in Europe sustain dedicated hardware demand resistant to smartphone displacement.
- Retailers:Location-based inventory management and indoor-outdoor positioning fusion for last-mile logistics. Amazon and Walmart deployment of warehouse robotics with GNSS-IMU integration drives enterprise receiver procurement.
Individual consumers hold the largest share; outdoor enthusiasts concentrate margin pools.
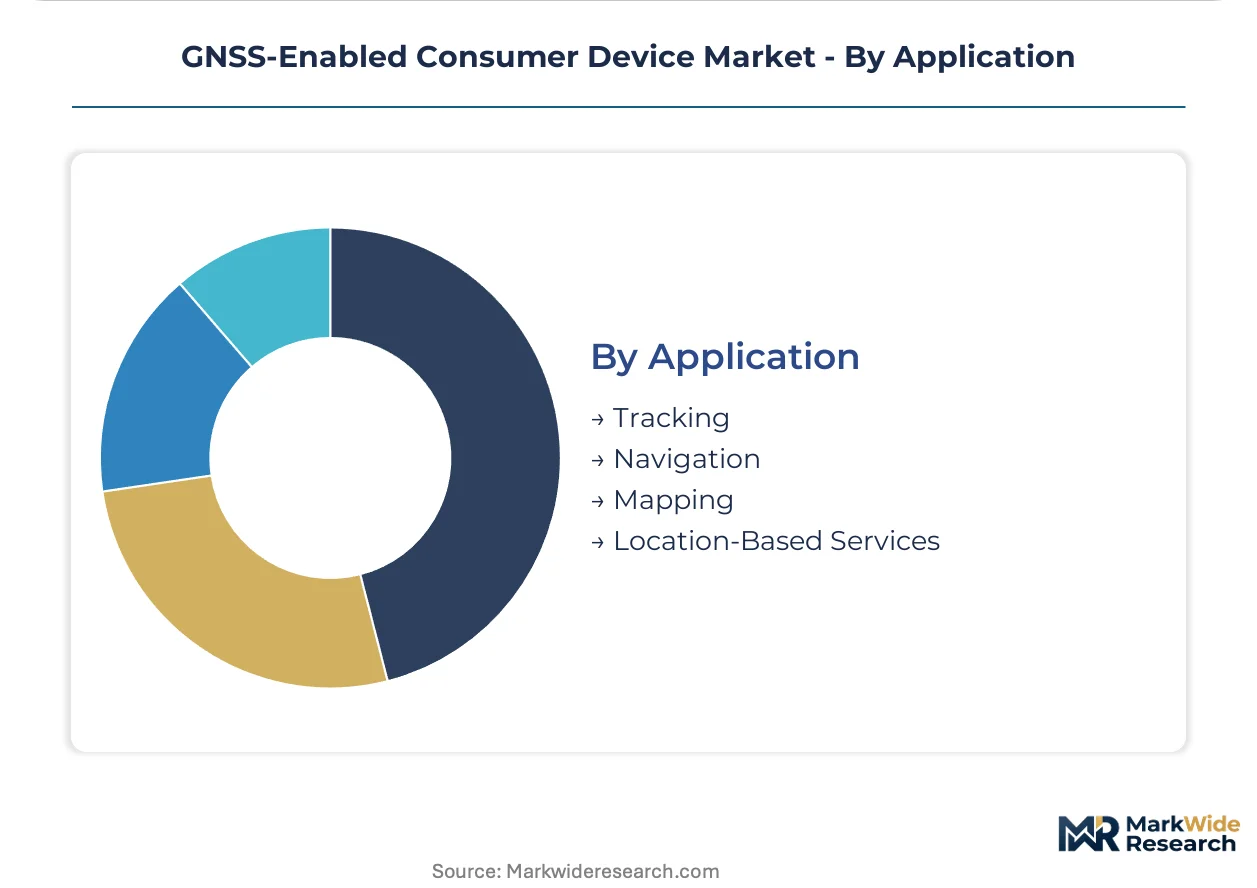
Application:
Maturity differentiation separates established navigation utilities from emerging augmented reality and precision agriculture adjacencies.
- Tracking:Asset monitoring and personal safety applications leverage low-power GNSS-Cellular fusion for extended battery operation. Pet trackers and elderly fall-detection devices drive volume in Japan and Western Europe where aging demographics elevate safety concerns.
- Navigation:Turn-by-turn routing remains the dominant consumer-facing application, though differentiation shifts from hardware receiver performance to cloud-based traffic integration and AI-powered predictive routing.
- Mapping:Professional surveying and recreational trail logging demand sub-meter to centimeter accuracy. Subscription correction services from Trimble and u-blox displace premium receiver hardware in Australian agricultural and construction adjacent markets.
- Location-Based Services:Urban wayfinding apps fuse camera-based visual positioning with satellite corrections. AR navigation in Seoul, Tokyo, and San Francisco creates demand for sub-meter chipsets in mid-range handsets previously served by meter-class receivers.
Navigation holds the largest share; location-based services expand most quickly as AR integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German automotive certification corridors while Shenzhen manufacturing clusters compress hardware margins through scale economics. This geographic asymmetry shapes divergent investment returns across the value chain.
United States
FCC E911 mandates enforce minimum accuracy thresholds for handset GNSS performance, sustaining baseline receiver specifications across carrier-subsidized channels. FAA beyond-visual-line-of-sight frameworks for commercial drones mandate redundant positioning systems, accelerating dedicated receiver procurement. San Diego semiconductor design hubs face acute RF engineering scarcity that delays dual-frequency product tape-outs.
Germany
KBA enforcement of ETSI Galileo mandates for automotive emergency-call systems compels Tier-1 supplier redesigns of telematics control units. F-Gas Regulation phase-downs reshape thermal management strategies for high-precision reference stations supporting consumer augmentation services. Stuttgart and Munich automotive calibration facilities anchor European certification gravity for dual-frequency chipset validation.
China
MIIT administers BeiDou terminal certification through in-country testing facilities that extend foreign OEM time-to-market. Shenzhen and Dongguan manufacturing clusters concentrate mass-market handset production serving domestic consumption and Southeast Asian export markets. Dual carbon goals accelerate CO2-based cooling retrofits for ground infrastructure supporting augmentation services.
India
Bureau of Indian Standards finalizes BeiDou-GPS interoperability specifications for emergency response devices, opening government procurement channels previously restricted to GPS-only hardware. Direct-to-consumer e-commerce channels concentrate mass-market smartphone and basic wearable demand in urban navigation segments. Delhi-NCR and Karnataka industrial corridors attract component assembly investments from export-oriented contract manufacturers.
Japan
METI standards shape precision requirements for location-audited cold chain logistics in pharmaceutical distribution adjacent to consumer markets. Aging demographics elevate demand for personal safety applications including pet trackers and elderly fall-detection devices with extended battery operation. Tokyo and Osaka metropolitan areas drive urban wayfinding app development fusing camera-based visual positioning with satellite corrections.
GNSS-Enabled Consumer Device Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with captive silicon developers sustaining positioning accuracy advantages while contract manufacturers compress hardware economics. Market structure fragments across smartphone OEMs, specialized wearable vendors, and automotive Tier-1 suppliers with divergent certification requirements. Three archetypes dominate: integrated platform owners with captive chip design, specialized firmware developers for vertical applications, and scale-driven component aggregators for emerging-market price bands. Competitive moves concentrate on sensor fusion software differentiation and die-shrunk RF front-end integration.
Within the integrated platform tier, Apple and Samsung Electronics exemplify technology leadership through captive silicon roadmaps that sustain accuracy advantages in premium handsets. Xiaomi occupies a position on the cost-optimized vector, representing scale-driven BeiDou-GPS fusion strategies for emerging-market penetration. Garmin anchors the specialized firmware archetype, sitting within the outdoor recreation segment where backcountry navigation safety commands premium pricing durability.
| Leading Market Players |
|---|
| Samsung Electronics |
| Xiaomi |
| Apple |
| Fossil Group |
| Huami Corporation |
| Garmin |
| Huawei Technologies |
| TomTom |
| Fitbit |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with RF foundries lock in wafer access for dual-frequency GNSS chipset vendors while capping price escalation exposure against 5G infrastructure competition for low-temperature co-fired ceramic substrates. Semiconductor OEMs in Hsinchu and San Diego anchor these arrangements, binding automotive Tier-1 suppliers to fixed pricing corridors for telematics control unit redesigns compelled by ETSI Galileo mandates.
Pricing Analysis
The customization-premium spread separates configured-to-order dual-frequency receivers from standard single-band modules, with automotive emergency-call certification commanding substantial uplifts over consumer handset baselines. Three-tier pricing structure across premium, standard, and economy levels stratifies by constellation support and MIIT certification status, while cost compression in mid-tier wearables intensifies because MediaTek and Qualcomm push multi-band capability into sub-dollar chipsets. Fleet operators exhibit lowest price sensitivity due to ELD compliance mandates; emerging-market individual consumers drive hardest bargain pressure.
Supply Chain Analysis
Strategic stockpile preferences dominate RF front-end procurement as OEMs buffer against ceramic substrate allocation competition from 5G base station buildouts. Manufacturing concentrates in Taiwan, South Korea, and China, with die-shrunk processes drawing from silicon wafer and LTCC substrate inputs. Single-source vulnerability concentrates in Hsinchu packaging facilities for compact antenna-in-package modules. Distribution runs through Shenzhen electronics markets for domestic Chinese consumption and direct-to-consumer e-commerce channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized firmware competencies for sensor fusion and dead-reckoning calibration represent the critical capability gap constraining new product introduction timelines, with RF engineering scarcity extending tape-out delays across semiconductor design hubs.
For Market Incumbents: Fortify captive silicon roadmaps through backward integration into MEMS gyroscope calibration facilities, insulating positioning accuracy leadership from recruitment bottlenecks in San Diego and Hsinchu. Deepen channel control over automotive Tier-1 supplier relationships before Android Auto displacement collapses standalone navigation system volumes entirely. For New Entrants and Emerging Players: Differentiate on health-monitoring fusion architectures for endurance sports wearables, where SpO2-GNSS correlation commands premium pricing durability unavailable in commoditized handset receivers. Target India's BIS-certified emergency response device procurement, leveraging newly opened BeiDou-GPS interoperability specifications to bypass GPS-only incumbent lock-in. For Investors and Strategic Acquirers: Specialized firmware developers with vertical expertise in backcountry navigation and aviation-grade redundant positioning systems present the most defensible acquisition profile against hardware commoditization. Monitor MIIT certification timeline compression as the inflection signal; foreign OEM time-to-market reduction would validate premium multiples for China-accessible target assets.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency Chipset Die Shrink | MediaTek's sub-dollar multi-band pushes capability into mass-market handsets previously served by premium tiers. |
| Sensor Fusion Firmware Acquisition | Garmin's specialized dead-reckoning algorithms create defensible moats against hardware commoditization pressure. |
| MIIT Certification Facility Investment | In-country testing capacity expansion reduces foreign OEM time-to-market penalties by 8-14 weeks. |
| Automotive Telematics Redesign | ETSI Galileo mandates compel Tier-1 supplier hardware refreshes for emergency-call system compliance. |
| Subscription Correction Service Launch | Trimble's annual license model displaces premium receiver SKUs in Australian agricultural adjacent markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RF engineering directors, automotive Tier-1 procurement leads, wearable OEM product managers, and MIIT certification specialists; and secondary validation against SEC semiconductor filings, FCC equipment authorization databases, ETSI mandate documentation, and customs records for GNSS receiver module trade flows. Bottom-up bill-of-materials costing for dual-frequency chipsets triangulated against top-down manufacturer revenue segmentation.
Across the analysis window, the forecast framework modeled volume and value outputs through disaggregation by product type, constellation support tier, end-user technical sophistication, and regional certification regime. CAGRs derived from curve-fitting historical penetration rates against regulatory mandate enforcement timelines and fitness wearable replacement cycle data. Industry-specific inputs included drone BVLOS regulatory maturation pace and F-Gas Regulation thermal management capex intensity for reference station operators.
Decision-makers should treat outputs as directional under assumptions of sustained RF engineering scarcity and stable ceramic substrate allocation; material deviation would warrant model refresh. Revision becomes warranted when MIIT certification capacity expansion or ETSI mandate delay crosses thresholds altering hardware refresh timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Personal Navigation Devices Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Refrigeration Monitoring Market
Sensors
Automated Weather Observation System Market
Sensors
Remote Sensing Technology Market
Sensors
Digital Direction Finder Market
Sensors
Beacon Market
Sensors
Mobile Lidar Scanner Market
Sensors
Wireless RFID Readers Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Ultrasonic Technologies Market
Sensors
Conveyor Monitoring Market
Sensors
Weigh-In-Motion System Market
Sensors
Indoor Positioning and Navigation Market
Sensors
Mobile Mapping Systems Market
Sensors
Fixed RFID Readers Market